
 Pea Processed Ingredients Market | 2026-2036
Pea Processed Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Processed Ingredients Market Outlook
Canadian prairie pea fractionation capacity is realigning global supply flows as processors expand wet-milling infrastructure. Roquette Frères leverages its decades of extrusion expertise to dominate high-viscosity pea starch applications. Ingredion Incorporated anchors North American supply through its network of pulse processing partnerships with regional growers. Puris Foods differentiates through closed-loop organic pea protein production spanning seed genetics to finished isolate.
Pea processed ingredients comprise fractionated outputs from yellow and green field peas, including protein isolates with 80-90% protein content, native and modified starches, and dietary fiber concentrates, all produced through dry milling, air classification, or alkaline wet extraction followed isoelectric precipitation. These ingredients function as emulsifiers, gelling agents, and nutritional fortifiers across formulated foods, feed rations, and cosmetic matrices. Pea protein commands the deepest margin pools as beverage and meat-alternative brands reformulate away from soy, while pea starch is accelerating fastest in gluten-free bakery and biodegradable film applications. Powdered forms retain volume leadership, though liquid concentrates are gaining traction in ready-to-drink nutritionals where dispersion speed matters.
The FDA's GRAS notification pathway governs novel pea protein concentrates entering US food channels, while the EU's REACH framework and F-Gas Regulation shape solvent recovery standards for European fractionation plants. EFSA novel food assessments create a 12-18 month lag for new pea-derived ingredients seeking EU market entry, advantaging established suppliers with existing approvals. Stakeholders must monitor how the EU Green Deal's protein autonomy targets will reshape import tariffs versus domestic processing incentives.
Market Dynamics
Pea fractionation economics are tightening as Rotterdam's port infrastructure consolidates import flows while EU Green Deal protein autonomy targets redirect agricultural subsidies toward domestic pulse cultivation, compressing margins for non-European suppliers.
Growth Catalysts
- EU Green Deal protein strategy:The framework redirects Common Agricultural Policy subsidies toward pulse cultivation, expanding domestic raw material supply for fractionation plants in the Netherlands and France.
- Clean-label meat alternatives:Food manufacturers are reformulating away from soy isolates toward pea protein to avoid allergen labeling requirements and GMO disclosure thresholds.
- Wet-milling infrastructure expansion:Canadian prairie processors are installing alkaline extraction lines that improve protein yield rates and reduce hexane dependency.
Market Restraints
- Yellow pea price volatility:Weather-driven yield fluctuations in the Canadian prairies and Black Sea region create input cost instability that fractionators cannot fully pass through.
- EFSA novel food timelines:The 12-18 month assessment lag for new pea-derived ingredients blocks market entry for innovative concentrates and hydrolysates.
- Soy protein substitution economics:Established soy isolate supply chains in Argentina and Brazil maintain cost advantages at equivalent protein concentrations.
Strategic Opportunities
- Biodegradable film applications:Pea starch is penetrating packaging markets as REACH-compliant alternatives to petroleum-derived films gain brand procurement mandates.
- Ready-to-drink nutritionals:Liquid pea protein concentrates are displacing powdered isolates in beverage manufacturing where rapid cold-water dispersion reduces production cycle times.
- Organic closed-loop production:Seed-to-isolate traceability systems command premium positioning in European retail channels with mandatory origin disclosure requirements.
Industry Challenges
- Fractionation engineering talent scarcity:Wet-milling process optimization requires specialized expertise in isoelectric precipitation that outpaces agricultural engineering program output.
- GRAS notification complexity:The FDA's self-affirmation pathway demands extensive toxicology dossiers that delay US market entry for novel protein hydrolysates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Processed Ingredients Market |
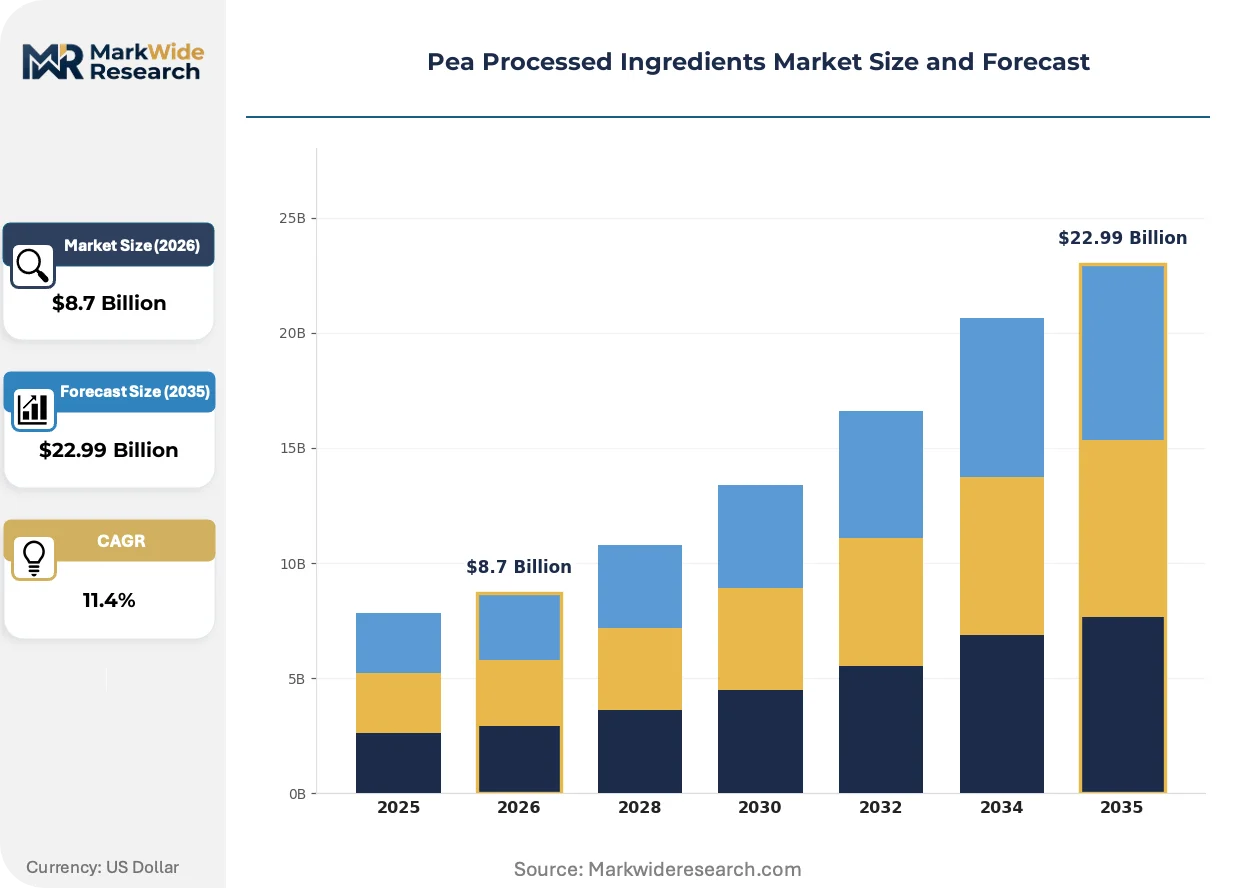
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pea Protein, Pea Flour, Pea Starch, Pea Fiber Application: Food & Beverages, Animal Feed, Nutraceuticals, Personal Care End User: Food Manufacturers, Dietary Supplement Producers, Animal Feed Companies, Cosmetic Brands Form: Powder, Liquid, Granule, Concentrate |
| Companies Covered | Roquette Frères, Ingredion Incorporated, Emsland Group, Kerry Group, DuPont, Puris Foods, AGT Food and Ingredients, COSUCRA Groupe Warcoing, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Processed Ingredients Market Strategic Shifts
Pea ingredient technology is bifurcating between commodity fractionation for bulk protein supply and precision-engineered functional ingredients that command formulation premiums in specialized nutrition and biodegradable materials.
Membrane filtration technology is rewriting protein recovery economics by enabling continuous processing that reduces water consumption and eliminates batch precipitation steps. Beverage manufacturers are adopting these native protein concentrates for neutral flavor profiles that require less masking. The shift is compressing demand for traditional alkaline-extracted isolates in liquid applications.
REACH solvent recovery mandates are forcing European fractionation plants to retrofit closed-loop hexane systems or transition to aqueous extraction methods. The regulation's F-Gas compliance requirements add capital intensity to plant upgrades. German and Dutch processors are consolidating wet-milling capacity to amortize environmental control investments across larger throughput volumes.
Direct contracting between pea protein isolators and plant-based meat brands is displacing traditional ingredient distributor networks. Large-format buyers are negotiating multi-year offtake agreements that guarantee volume allocation and price bands. This concentration is most visible in the Netherlands, where Rotterdam's import infrastructure supports just-in-time delivery to European manufacturing clusters.
Pea Processed Ingredients Market Segmentation
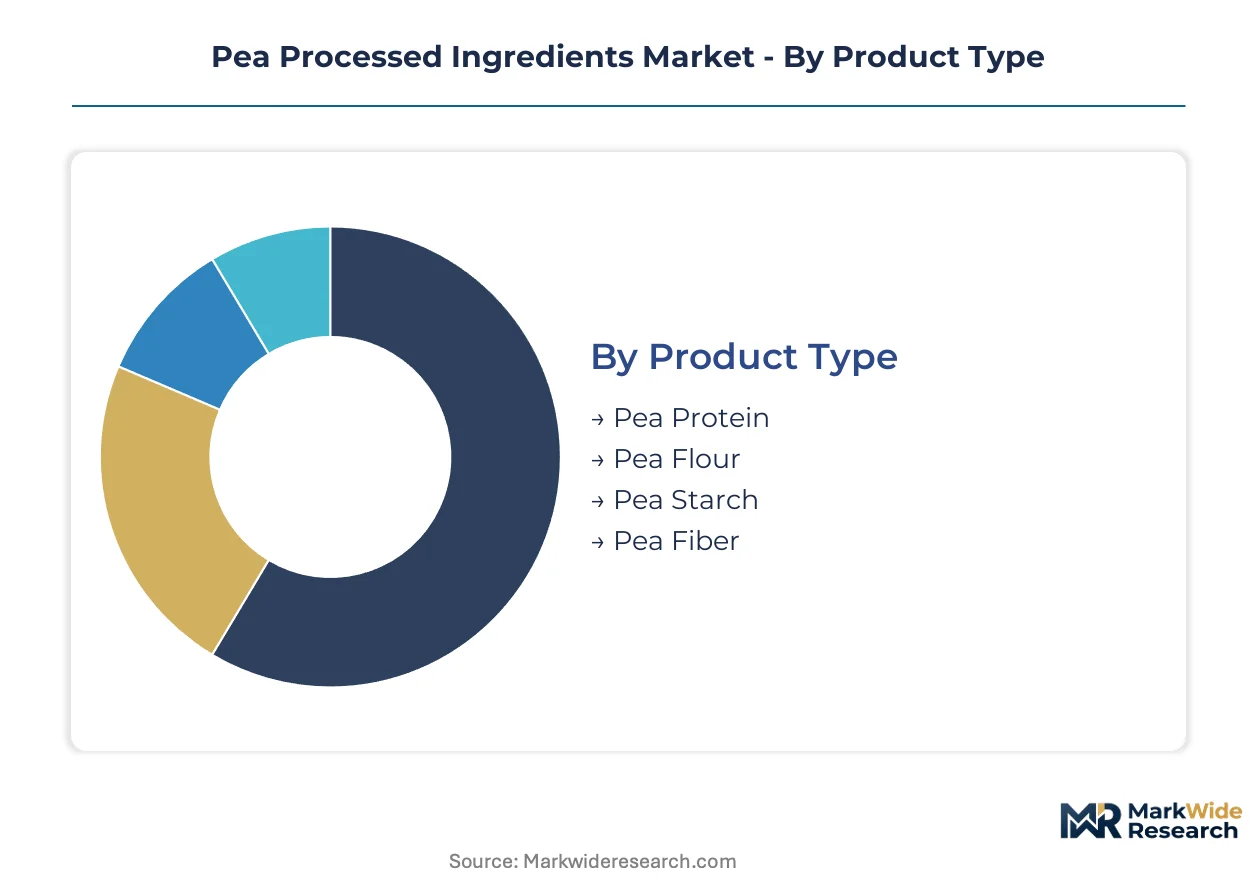
Pea processed ingredients fragment across four distinct axes that reshape procurement patterns and margin structures. Product specifications determine extraction complexity and protein yield rates. Application requirements drive formulation investments in dispersion technology and flavor masking systems.
Product Type:
Protein concentration levels and starch modification degrees define the technical hierarchy of fractionated outputs.
- Pea Protein:Isolates containing 80-90% protein content command premium positioning in beverage and meat-alternative formulations. Demand concentrates among plant-based meat manufacturers in the Netherlands and Germany seeking clean-label alternatives to soy isolates under EFSA allergen disclosure rules.
- Pea Starch:Native and modified starches with high viscosity profiles penetrate gluten-free bakery and biodegradable film applications. Rotterdam's port infrastructure supports large-scale imports for European packaging converters adapting to REACH-compliant solvent recovery mandates.
- Pea Flour:Whole-milled flour with intermediate protein content serves cost-sensitive bakery and pasta applications where complete isolation is uneconomical.
- Pea Fiber:Insoluble and soluble fiber concentrates fortify digestive health products and pet food matrices with label-friendly fiber claims.
Pea protein leads on scale; pea starch leads on momentum.
Application:
End-use specifications create divergent requirements for dispersibility, flavor neutrality, and regulatory clearance pathways.
- Food & Beverages:Ready-to-drink nutritionals and dairy alternatives require rapid cold-water dispersion that favors liquid concentrate formats. Canadian prairie processors are expanding wet-milling infrastructure to supply North American beverage manufacturers.
- Nutraceuticals:Protein hydrolysates with enhanced bioavailability face extended FDA GRAS notification timelines that delay US market entry for novel concentrates.
- Animal Feed:Pea protein concentrate rations replace fishmeal in aquaculture feeds, with procurement shifting toward Black Sea origin pulses for cost efficiency.
- Personal Care:Pea starch films and protein-derived emulsifiers penetrate cosmetic formulations seeking biodegradable alternatives to petroleum-derived ingredients.
Food and beverages dominates volume; nutraceuticals claims the steepest expansion trajectory.
End User:
Customer scale and technical capability determine contract structures and service level requirements.
- Food Manufacturers:Large-format plant-based meat brands negotiate multi-year offtake agreements with Rotterdam-based fractionators for just-in-time delivery to European manufacturing clusters.
- Dietary Supplement Producers:Powdered isolate demand from sports nutrition brands is displacing traditional distributor networks as direct contracting concentrates procurement leverage.
- Animal Feed Companies:Regional compounders source pea protein concentrates through agricultural cooperatives with integrated storage and logistics.
- Cosmetic Brands:Premium skincare formulators specify organic-certified pea derivatives with seed-to-finished-ingredient traceability systems.
Food manufacturers anchor procurement scale; cosmetic brands extract the highest margin premiums.
Form:
Physical state determines handling economics, shelf stability, and reconstitution performance in downstream processing.
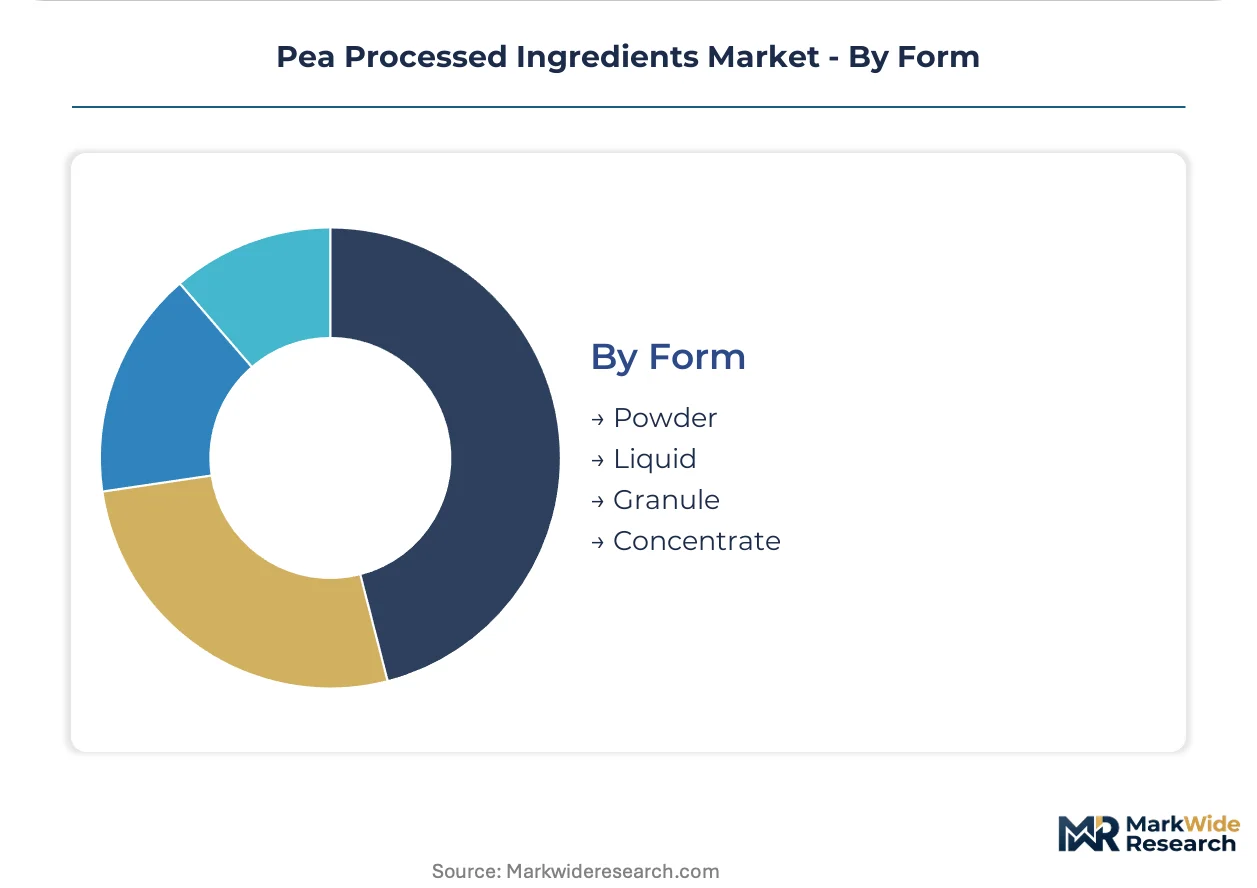
- Powder:Spray-dried isolates retain volume leadership across bakery, meat extension, and dry blend applications where extended shelf life reduces working capital requirements.
- Liquid:Ready-to-drink beverage manufacturers adopt liquid concentrates to eliminate hydration steps and reduce production cycle times in high-throughput filling lines.
- Granule:Agglomerated formats improve flowability in pneumatic conveying systems for industrial-scale food manufacturing operations.
- Concentrate:Reduced-moisture pastes balance storage efficiency against reconstitution speed in intermediate moisture food systems.
Powder retains installed base dominance; liquid concentrates are gaining share fastest in beverage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's prairie fractionation infrastructure outpaces United States wet-milling capacity, while the Netherlands leverages Rotterdam's port to dominate European import flows.
Canada
AGT Food and Ingredients and Puris Foods anchor prairie wet-milling expansion. Health Canada novel food assessments govern protein concentrate approvals. Saskatchewan's Yellowhead Highway corridor concentrates new alkaline extraction facilities serving North American beverage manufacturers.
United States
FDA GRAS notifications delay novel hydrolysate market entry for 18-24 months. Plant-based meat brands in California negotiate direct offtake agreements bypassing traditional distributors. Midwestern processors in Minnesota and North Dakota retrofit facilities for organic closed-loop production.
Netherlands
EU Green Deal protein autonomy targets redirect Common Agricultural Policy subsidies toward domestic pulse cultivation. EFSA allergen disclosure rules favor pea over soy isolates in clean-label formulations. Rotterdam's port infrastructure supports just-in-time delivery to Eindhoven-region manufacturing clusters.
France
Roquette Frères dominates high-viscosity pea starch applications through decades of extrusion expertise. REACH solvent recovery mandates force retrofits of closed-loop hexane systems. Northern France's Hauts-de-France region consolidates wet-milling capacity to amortize environmental control investments.
Germany
Emsland Group leverages modified starch expertise for biodegradable film applications. F-Gas Regulation compliance adds capital intensity to fractionation plant upgrades. Bavarian processors specialize in organic-certified derivatives with seed-to-finished-ingredient traceability for cosmetic formulators.
Pea Processed Ingredients Market Competitive Environment
European producers anchor the premium functional ingredients tier; North American specialists hold volume-driven commodity supply. The vendor base stratifies across three tiers: multinational ingredient conglomerates with integrated fractionation networks, regional wet-milling operators with crop origination advantages, and organic-certified closed-loop specialists commanding traceability premiums. Strategic moves concentrate on direct contracting with plant-based meat brands and membrane filtration technology licensing.
Within the multinational conglomerate tier, Roquette Frères and Ingredion Incorporated exemplify divergent geographic anchoring strategies. Roquette Frères represents European extrusion expertise dominance in high-viscosity applications. Ingredion Incorporated occupies a position anchoring North American supply through pulse processing partnerships. Puris Foods sits within the organic closed-loop specialist archetype, spanning seed genetics to finished isolate production. These three entities collectively illustrate how competitive positioning fragments across functional specialization, geographic origination, and certification tier.
| Leading Market Players |
|---|
| Roquette Frères |
| Ingredion Incorporated |
| Emsland Group |
| Kerry Group |
| DuPont |
| Puris Foods |
| AGT Food and Ingredients |
| COSUCRA Groupe Warcoing |
| Cargill |
| Others |
Value Chain & Pricing Dynamics
Yellow pea futures on the Winnipeg Commodity Exchange cascade through fractionation economics, compressing margins for non-integrated processors while concentrating pricing power among Rotterdam-based importers with just-in-time delivery contracts to Eindhoven manufacturing clusters.
Pricing Analysis
Distributor margin compression is reshaping channel economics as plant-based meat brands negotiate direct offtake agreements that bypass traditional ingredient networks. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified isolates with seed-to-finished traceability from commodity-grade protein concentrates and unmodified pea flour. Pricing pressure stems from Argentine soy isolate substitution economics that cap pea protein premiums at equivalent protein concentrations. Animal feed compounders exhibit highest price sensitivity due to thin ration margins, while cosmetic formulators absorb premiums for REACH-compliant biodegradable film derivatives.
Supply Chain Analysis
Single-source vulnerability sits with Canadian prairie wet-milling capacity that feeds North American beverage manufacturers through Saskatchewan's Yellowhead Highway corridor. Raw material flows draw from Saskatchewan and Manitoba yellow pea cultivation, Black Sea origin pulses for European cost-efficient feed rations, and Dutch domestic pulse cultivation expanding under EU Green Deal subsidy redirection. Supply chain risk centers on weather-driven yield fluctuations that fractionators cannot fully pass through to downstream buyers. Distribution runs through Rotterdam's port infrastructure for European re-export, direct rail corridors to Midwestern US processors, and agricultural cooperative networks serving regional compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as EU Green Deal protein autonomy targets institutionalize pulse cultivation subsidies that expand domestic raw material supply for fractionation plants.
For Market Incumbents: Deploy membrane filtration technology licensing to capture formulation premiums in ready-to-drink nutritionals where rapid cold-water dispersion commands price premiums. Expand wet-milling capacity in the Netherlands to amortize REACH solvent recovery mandates across larger throughput volumes. Consolidate procurement leverage through multi-year offtake agreements that guarantee volume allocation against emerging Canadian prairie competitors. For New Entrants and Emerging Players: Enter via organic closed-loop production systems that span seed genetics to finished isolate, capturing premium positioning in European retail channels with mandatory origin disclosure requirements. Target Bavarian cosmetic formulators seeking biodegradable pea starch films as petroleum-derived alternatives face REACH compliance deadlines. Pursue direct contracting with mid-size plant-based meat brands bypassing established distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with wet-milling specialists possessing isoelectric precipitation expertise that outpaces agricultural engineering program output. Five-to-ten year viability hinges on regulatory tailwinds from EU protein autonomy targets and FDA GRAS pathway maturation for novel hydrolysates. Monitor EFSA novel food assessment timelines as inflection indicator for innovative concentrate market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Genetics | Puris Foods controls organic cultivar development that underpins traceability premiums in European retail. |
| Membrane Filtration Technology Licensing | Continuous processing reduces water consumption and eliminates batch precipitation steps for beverage manufacturers. |
| REACH-Compliant Solvent Recovery Retrofit | German and Dutch processors consolidate capacity to amortize F-Gas Regulation compliance investments. |
| Direct-to-OEM Offtake Agreements | Rotterdam-based fractionators bypass distributor networks for just-in-time delivery to plant-based meat clusters. |
| Organic Certification Program Expansion | Seed-to-isolate traceability systems command premium positioning under EU mandatory origin disclosure rules. |
Study Parameters
Coverage spans Canada, the United States, the Netherlands, France, and Germany, with primary inputs from each jurisdiction combined with secondary validation. Interviews with fractionation plant managers, procurement leads at plant-based meat brands, agricultural cooperative directors, and cosmetic formulator R&D heads were triangulated against customs and trade data, EFSA novel food assessment records, EU Common Agricultural Policy subsidy disclosures, and SEC filings from publicly traded ingredient conglomerates. Bottom-up volume modeling and top-down value reconciliation anchored the analytical framework.
Granularity-level modeling disaggregated volume and value across product type, application, end user, and form dimensions throughout the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by base-year contribution. Forecast inputs incorporated EU Green Deal protein autonomy target implementation schedules, FDA GRAS notification pathway velocity, and wet-milling capacity expansion announcements across the prairie provinces.
Inputs from regulatory filing databases and primary stakeholder interviews were available through the study window; gaps in proprietary fractionation yield data and unannounced capacity expansion timelines introduce uncertainty bands around protein isolate supply projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Processed Meat Market
Processed Foods
Low-Calorie Margarine Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Low Fat Pasta Market
Processed Foods
North America Soup Market
Processed Foods
Ready to Cook Market
Processed Foods
Industrial Margarine Market
Processed Foods
United States Egg Powder Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
Ice Cream Parlor Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Processed Potatoes Market
Processed Foods
Egg White Cubes Market
Processed Foods
Fat Free Food Market
Processed Foods
US Tomato Paste Market