
 Noodles Market | 2026-2036
Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Noodles Market Insights
Subscription-based replenishment services for instant noodle assortments is realigning how manufacturers engage repeat buyers. Nissin Foods Holdings leverages its direct-to-consumer platforms to sustain brand loyalty across Asian urban markets. Nestlé SA anchors its portfolio through specialized nutrition lines that compete on protein fortification and reduced-sodium formulations. Indofood Sukses Makmur dominates Indonesian mass-market channels with manufacturing scale that extends into rural distribution networks.
Noodles are wheat-based or alternative-grain dough strands extruded, sheeted, or hand-pulled, then dried, steamed, or fried to achieve moisture levels between 8% and 12% for shelf stability; their primary commercial purpose is delivering low-cost, rapid-preparation carbohydrate bases for household and foodservice consumption. Instant noodles occupy the largest margin pool due to flavor sachet bundling and brand premiums, while gluten-free noodles represent the fastest-growing ingredient segment as buckwheat and tapioca formulations gain traction among dietary-restricted consumers. Cup packaging commands higher unit economics than bag formats in convenience-store channels across East Asian markets.
SAMR in China enforces GB standards for additive limits and labeling transparency that shape export compliance costs for regional suppliers. FDA oversight in the United States governs sodium disclosure and allergen labeling that influences reformulation priorities for brands entering North American retail. EFSA and REACH in Europe regulate packaging material migration and wheat treatment residues, creating tiered market access requirements. Stakeholders must monitor how diverging sodium-reduction mandates across these jurisdictions reshape product development budgets and regional portfolio prioritization.
Market Dynamics
China's SAMR enforcement of GB standards for additive limits and labeling transparency is compressing formulation flexibility and forcing cross-border suppliers to rebuild compliance infrastructure around ingredient traceability systems.
Growth Catalysts
- Quick-service restaurant penetration:Foodservice chains in Vietnam and Indonesia are standardizing instant noodle SKUs as low-prep carbohydrate bases for value-menu engineering.
- REACH packaging compliance:European migration limits for styrene and bisphenol in cup containers are accelerating migration to fiber-based alternatives that command shelf-space premiums.
- Buckwheat extrusion advances:Modified starch binding technologies are eliminating texture gaps in gluten-free noodles, opening institutional foodservice contracts in Japan and South Korea.
Market Restraints
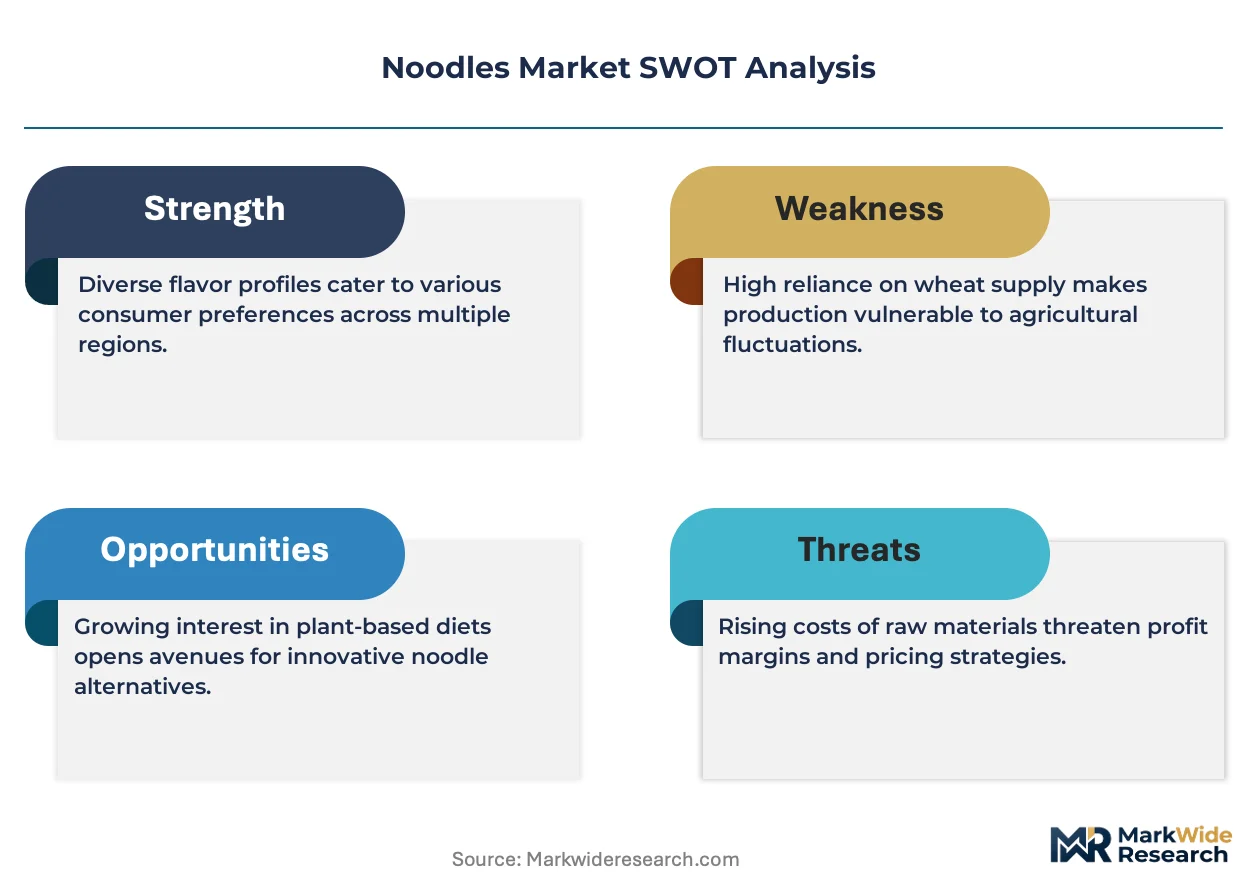
- Wheat price volatility:Black Sea supply disruptions and drought cycles in Australia are compressing margin pools for wheat-based noodle manufacturers without forward-contract coverage.
- Palm oil concentration:Malaysian and Indonesian oleochemical suppliers control 85% of frying oil inputs for instant noodle production, creating single-source vulnerability for regional processors.
- Sodium reduction technical ceilings:Potassium chloride aftertaste and texture degradation limit reformulation below 1500mg per serving without flavor sachet restructuring.
Strategic Opportunities
- Rural Indonesian distribution:Cold-chain-free last-mile networks in Sulawesi and Papua remain undersupplied by premium instant noodle assortments.
- Protein fortification mandates:India's FSSAI school feeding program specifications are creating procurement windows for fortified noodle tenders in 28 states.
- Subscription replenishment platforms:Direct-to-consumer auto-replenish models for multi-flavor assortments are capturing household pantry share in Tokyo and Seoul metropolitan areas.
Industry Challenges
- GB standard certification timelines:SAMR laboratory testing queues for novel additive approvals now extend 14-18 months, freezing product pipeline velocity for export-oriented suppliers.
- Legacy extruder retrofitting:Transitioning from fried to air-dried production lines requires $2-4 million per facility for humidity-controlled drying tunnel installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Noodles Market |
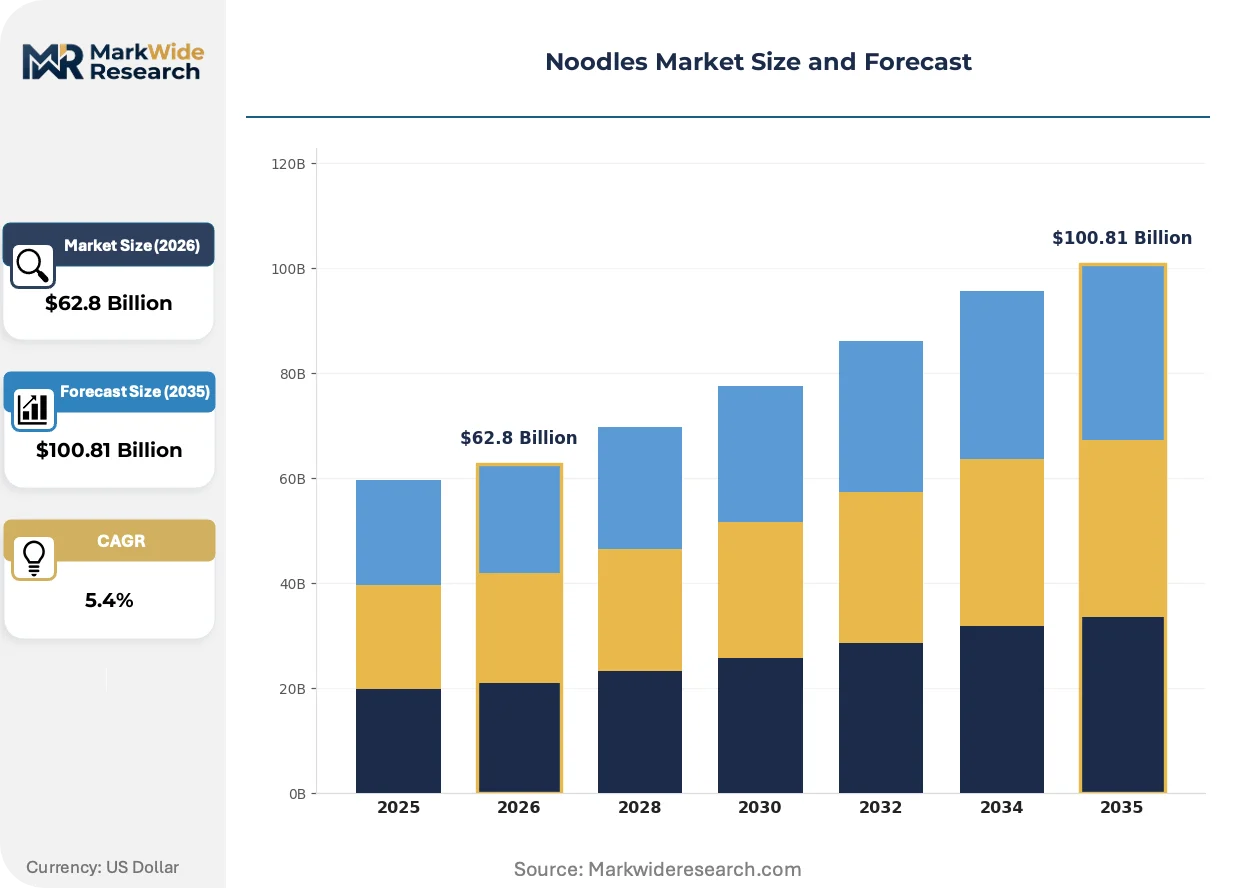
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $100.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Noodles, Dry Noodles, Fresh Noodles, Gluten-Free Noodles End User: Households, Restaurants, Food Service Chains, Institutions Ingredient: Wheat, Rice, Buckwheat, Tapioca Packaging Type: Bags, Cups, Boxes, Sachets |
| Companies Covered | Nissin Foods Holdings Co Ltd, Nestlé SA, Indofood Sukses Makmur Tbk PT, Ajinomoto Co Inc, Acecook Vietnam Joint Stock Company, Ting Hsin International Group, Uni-President Enterprises Corp, Master Kong Chongqing Convenience Food Co Ltd, ITC Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Noodles Market Trends and Innovations
Extrusion and drying technologies are converging with regulatory chemistry to compress sodium content while preserving shelf stability, reshaping how manufacturers balance formulation cost against compliance positioning.
Air-dried non-fried noodle production is rewriting the cost structure of premium instant segments. Japanese and South Korean manufacturers are retrofitting facilities at pace to serve health-positioned urban demographics. This process compression is enabling sodium reduction without the oil-based flavor carriers that dominate mass-market formulations.
China's SAMR is tightening GB 2760 enforcement for preservative limits and origin labeling. Export-oriented suppliers in Thailand and Vietnam are rebuilding supply chain documentation systems to maintain cross-border market access. Noodle categories with complex multi-origin ingredient decks face the steepest compliance cost escalation.
Household pantry replenishment is fragmenting across convenience-store immediacy and e-commerce subscription bundling. Younger consumers in Jakarta and Manila are abandoning single-flavor bulk purchases for curated variety packs delivered on 30-day cycles. This channel rotation is compressing traditional wholesale distributor margins while elevating direct manufacturer relationships.
Noodles Market Segmentation
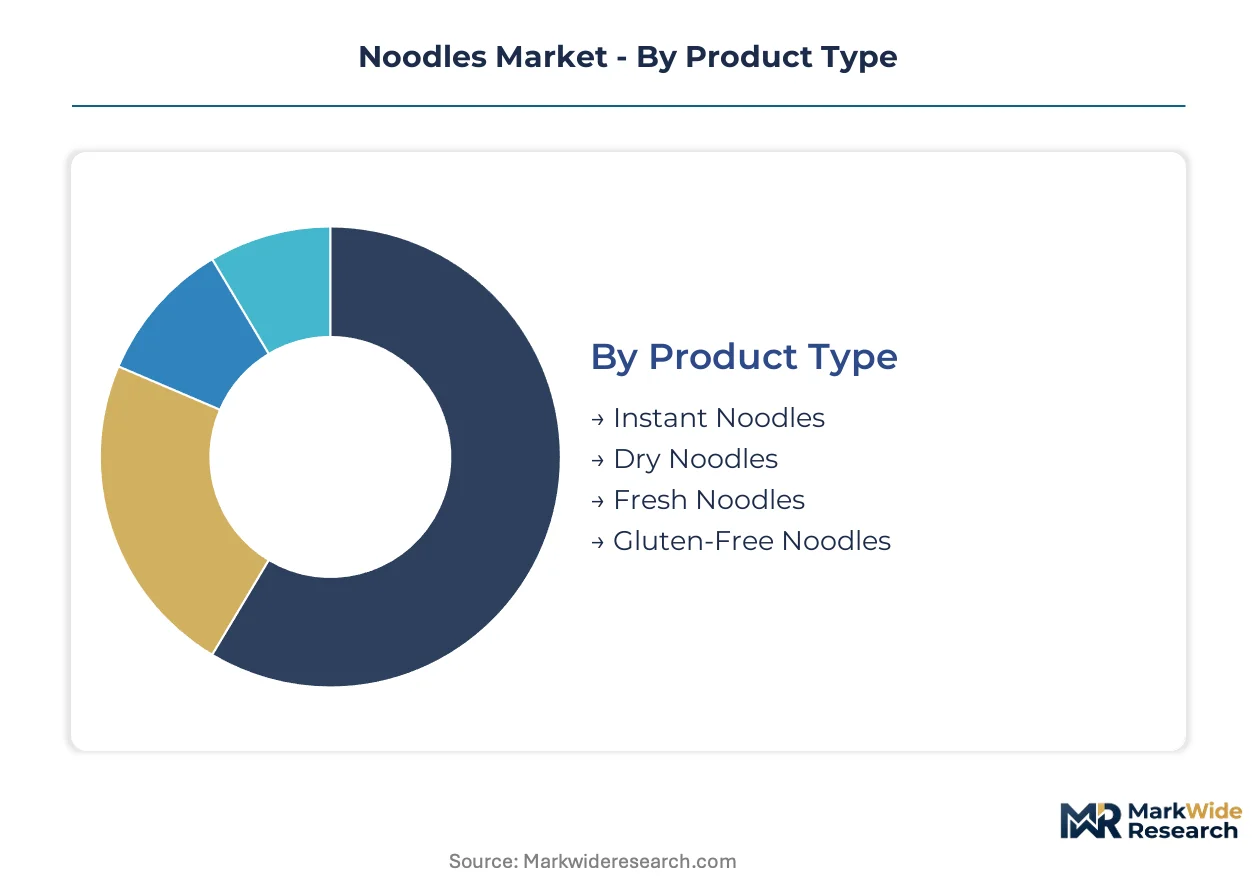
Noodle manufacturers configure production lines around distinct consumption occasions and preparation requirements. Segment boundaries determine margin pools, shelf-life engineering, and distribution channel priorities across retail and foodservice.
Product Type:
Integration depth varies sharply: instant formats embed complete flavor systems for standalone consumption, while fresh and dry noodles demand external ingredient pairing and kitchen infrastructure.
- Instant Noodles:Pre-cooked, fried or air-dried strands bundled with dehydrated seasoning sachets and oil packets for single-vessel preparation. Demand concentrates in Southeast Asian convenience-store channels and Indonesian rural distribution networks where boiling water access outpaces full kitchen facilities.
- Dry Noodles:Uncooked, dehydrated strands requiring boiling and saucing during preparation, common in East Asian household pantry stocking and restaurant back-of-house operations. Japanese and South Korean manufacturers prioritize air-dried variants to meet sodium-reduction positioning in premium urban demographics.
- Fresh Noodles:Refrigerated or frozen dough strands with moisture content above 30%, distributed through cold-chain-dependent retail and foodservice channels.
- Gluten-Free Noodles:Buckwheat and tapioca formulations processed on segregated extrusion lines to prevent cross-contamination.
Instant noodles lead volumes today; gluten-free noodles are gaining share fastest.
End User:
Cost tier stratification separates commodity procurement from premium positioning, with institutional buyers optimizing per-serving nutrition metrics and households prioritizing convenience and variety.
- Households:Individual and family-unit purchasers selecting across flavor variety, pack sizes, and preparation time for at-home consumption. Subscription replenishment platforms in Tokyo and Seoul metropolitan areas are capturing pantry share through curated 30-day flavor cycles.
- Restaurants:Independent foodservice operators sourcing bulk dry and fresh noodles for menu integration with proprietary broth and topping systems. Vietnamese pho and ramen shops in Ho Chi Minh City drive specialized fresh noodle procurement with custom thickness specifications.
- Food Service Chains:Quick-service and fast-casual networks standardizing instant noodle SKUs as low-prep carbohydrate bases for value-menu engineering across Indonesia and Vietnam.
- Institutions:Schools, hospitals, and military feeding programs procuring fortified formats under nutrition-mandated tenders.
Households lead volumes today; food service chains are expanding most quickly.
Ingredient:
Supply concentration around wheat creates cost volatility exposure, while alternative grains command sourcing premiums and segregated processing infrastructure.
- Wheat:Hard and soft wheat varieties milled to specific ash and protein content for texture control in extruded and sheeted noodles. Black Sea supply disruptions and Australian drought cycles are compressing margin pools for manufacturers without forward-contract coverage.
- Rice:Rice flour-based strands common in Southeast Asian cuisines and gluten-avoidance positioning, processed through distinct extrusion parameters than wheat.
- Buckwheat:Sobagara flour formulations requiring modified starch binding technologies to eliminate texture gaps in gluten-free applications.
- Tapioca:Cassava-derived starch providing elasticity in rice noodle alternatives and Southeast Asian vermicelli production.
Wheat leads volumes today; buckwheat shows the steepest expansion trajectory.
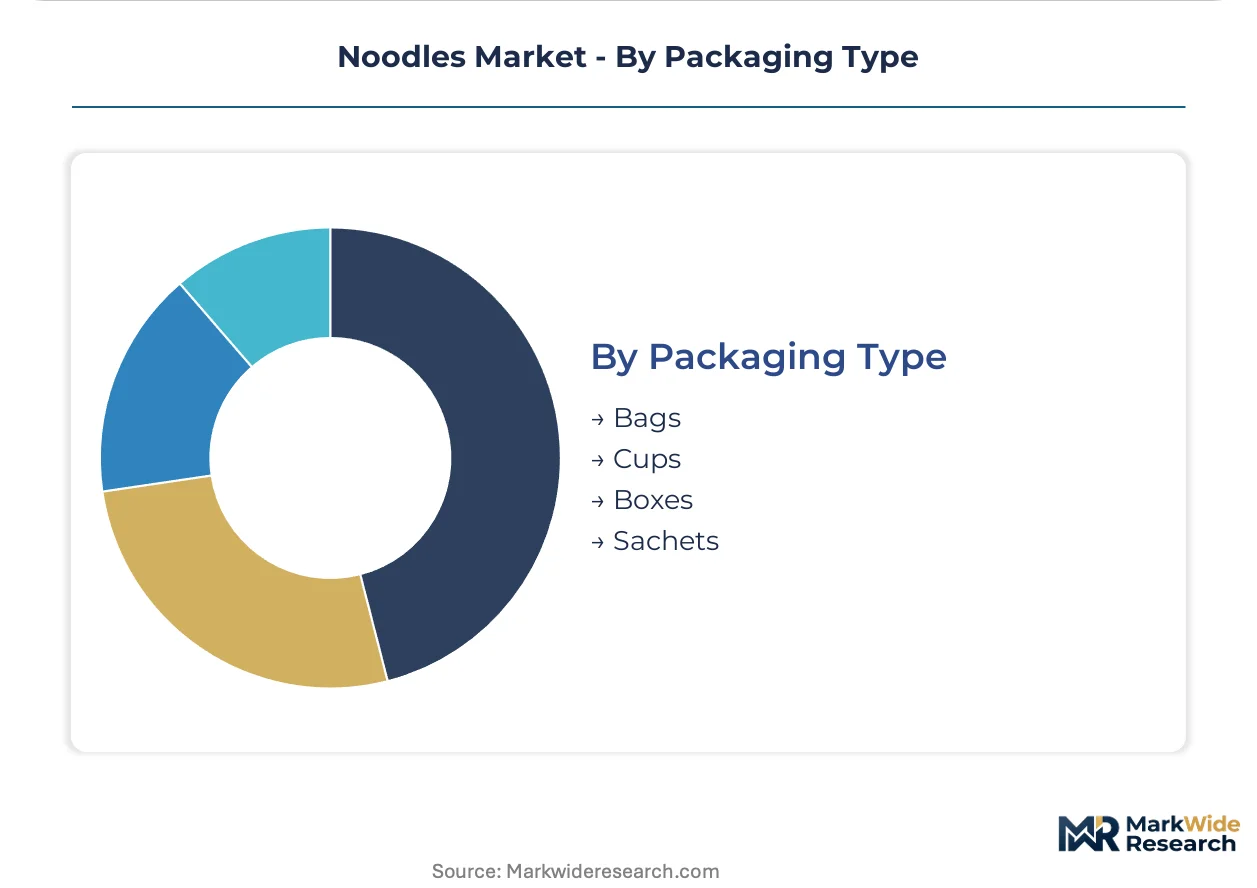
Packaging Type:
Channel placement and consumption occasion dictate format selection, with cup packaging commanding shelf-space premiums in convenience retail and bag formats dominating household pantry stocking.
- Bags:Flexible film or paper-wrapped bundles of dry or instant noodles, optimized for retail shelf density and household bulk purchasing. Traditional wholesale distributors in Jakarta and Manila face margin compression as younger consumers abandon single-flavor bulk purchases.
- Cups:Rigid containers with integrated lids designed for single-vessel preparation using boiling water, prevalent in convenience-store channels across East Asian markets. European REACH migration limits for styrene and bisphenol are accelerating fiber-based alternative adoption.
- Boxes:Cardboard cartons containing multiple serving units or premium positioning with external sauce packaging.
- Sachets:Small-format seasoning, oil, and dehydrated vegetable packets bundled with primary noodle units or sold as standalone flavoring systems.
Bags lead volumes today; cups are climbing the fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia consumes more instant noodles per capita than any other nation, while Vietnam's foodservice chains are embedding noodle SKUs into value-menu engineering at comparable velocity. Demand concentration across these two markets is reshaping where manufacturers allocate extrusion capacity and flavor R&D resources.
China
Urban households in Shanghai and Guangzhou are pivoting toward air-dried premium formats as health positioning displaces fried-mass-market legacy SKUs. SAMR's GB 2760 enforcement on additive limits and origin labeling is forcing export-oriented Thai and Vietnamese suppliers to rebuild traceability infrastructure. Manufacturing clusters in Henan province around Zhengzhou remain the dominant extrusion hub for domestic mass-market distribution.
Indonesia
Rural penetration in Sulawesi and Papua is driving volume expansion where cold-chain-free last-mile networks enable shelf-stable instant noodle distribution. The national government's BUMN procurement specifications for school feeding programs are creating institutional tender windows for fortified formats. Indofood Sukses Makmur's manufacturing scale extends into these underserved eastern provinces through captive distribution networks.
Vietnam
Quick-service restaurant chains in Ho Chi Minh City are standardizing instant noodle bases for pho and hu tieu value-menu engineering. The Ministry of Health's draft sodium reduction guidelines are pressuring reformulation toward potassium chloride blends without texture degradation. Fresh noodle fabrication clusters in the Mekong Delta supply specialized thickness specifications for independent restaurant operators.
Japan
Subscription replenishment platforms in Tokyo and Osaka metropolitan areas are capturing household pantry share through curated 30-day flavor cycles. METI's guidance on food tech innovation is accelerating modified starch binding research for buckwheat extrusion without gluten. Manufacturing facilities in Gunma and Saitama prefectures are retrofitting from fried to air-dried production lines.
South Korea
Institutional foodservice contracts for buckwheat soba and tapioca-based alternatives are expanding through modified starch advances that eliminate texture gaps. The MFDS sodium disclosure requirements for restaurant chains are pushing manufacturers toward flavor sachet restructuring below 1500mg thresholds. Production concentration in Gyeonggi-do province supplies both domestic convenience-store channels and export markets.
Noodles Market Competitive Landscape
Top-tier vendors anchor mass-market instant noodle production, while mid-scale specialists occupy premium air-dried and gluten-free segments. The competitive structure stratifies around manufacturing scale, with integrated flour milling and flavor sachet bundling determining margin capture. Three archetypes dominate: diversified food conglomerates with multi-category portfolios, national champions with captive distribution networks, and health-positioned specialists in alternative-grain formulations. Capacity expansion and direct-to-consumer platform development represent the dominant competitive vectors reshaping channel relationships.
Within the diversified conglomerate tier, Nestlé SA and Ajinomoto Co Inc occupy positions that span nutrition science and flavor system integration. Nissin Foods Holdings exemplifies the national champion archetype through direct-to-consumer platform deployment across Asian urban markets. Indofood Sukses Makmur represents manufacturing scale concentration with rural distribution network control. These three entities collectively illustrate how competitive positioning depends on backward integration into ingredient sourcing and forward control over last-mile channel access.
| Leading Market Players |
|---|
| Nissin Foods Holdings Co Ltd |
| Nestlé SA |
| Indofood Sukses Makmur Tbk PT |
| Ajinomoto Co Inc |
| Acecook Vietnam Joint Stock Company |
| Ting Hsin International Group |
| Uni-President Enterprises Corp |
| Master Kong Chongqing Convenience Food Co Ltd |
| ITC Limited |
| Others |
Pricing and Supply Chain Analysis
India's FSSAI school feeding program procurement specifications are forcing manufacturers to restructure cost models around protein fortification and micronutrient compliance, compelling supply chain investments in certified ingredient sourcing that compress margin pools at the economy tier while creating premium capture opportunities for compliant suppliers.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for mass-market instant noodle SKUs. Three-tier pricing structure across premium air-dried, standard fried, and economy bag formats stratifies around sodium content and packaging material. Cost compression in the economy tier is intensifying because of palm oil price volatility and wheat forward-contract premiums. Foodservice chains exhibit the highest price sensitivity due to value-menu engineering constraints, while subscription-based household purchasers in Tokyo and Seoul show lower elasticity for curated flavor assortments.
Supply Chain Analysis
GB standard certification from China's SAMR and REACH compliance for European migration limits are gating market access for regional suppliers. Wheat sourcing draws from Australia, Canada, and Black Sea origins, while palm oil concentration rests on Malaysian and Indonesian oleochemical suppliers. Single-source vulnerability in frying oil inputs creates structural risk for processors without alternative lipid formulations. Distribution runs through cold-chain-free last-mile networks in rural Indonesia and convenience-store channels across East Asian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The noodles market functions as a stable compounder anchored by recurring household pantry replenishment and institutional procurement mandates that generate predictable offtake regardless of cyclical pressure.
For Market Incumbents: Anchor manufacturing scale through backward integration into captive flour milling and flavor sachet production to defend against emerging air-dried specialists. Prioritize certification investment for SAMR GB 2760 compliance and REACH packaging migration standards to maintain cross-border market access. Channel control through direct-to-consumer platform deployment in Jakarta and Manila metropolitan areas offsets wholesale distributor margin compression. For New Entrants and Emerging Players: Direct-to-consumer subscription bundling offers the most penetrable route for curated gluten-free and buckwheat assortments targeting dietary-restricted urban demographics in Japan and South Korea. Rural Indonesian distribution in Sulawesi and Papua remains undersupplied by premium instant noodle variants. A go-to-market angle anchored on protein fortification tenders for India's FSSAI school feeding program specifications unlocks institutional procurement windows across 28 states. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale air-dried specialists possessing segregated buckwheat extrusion lines and modified starch binding capabilities. Long-term viability over a 5-10 year window favors manufacturers with dual certification for Chinese GB standards and European REACH compliance. The signal to watch is sodium reduction technical breakthroughs below 1500mg thresholds without potassium chloride aftertaste degradation.| Strategic Initiative | Industry Significance |
|---|---|
| Air-Dried Production Retrofit | Japanese and South Korean manufacturers retrofit facilities to serve health-positioned urban demographics with reduced-sodium positioning. |
| Direct-to-Consumer Platform Launch | Nissin Foods Holdings leverages subscription replenishment to sustain brand loyalty across Asian metropolitan markets. |
| Protein Fortification Certification | India's FSSAI school feeding program specifications create procurement windows for fortified noodle tenders in 28 states. |
| Fiber-Based Packaging Migration | European REACH migration limits for styrene and bisphenol accelerate adoption of fiber-based cup alternatives. |
| Rural Distribution Network Expansion | Indofood Sukses Makmur extends manufacturing scale into underserved eastern Indonesian provinces through captive logistics. |
Research Methodology
Coverage spans East Asia, Southeast Asia, and South Asia, with primary inputs from each region combining structured interviews with extrusion plant managers, flavor R&D directors, retail category buyers, and foodservice procurement leads at quick-service chains. Secondary validation draws from customs trade records, SAMR GB standard filings, FSSAI tender documentation, and Nielsen retail audit data. Bottom-up facility capacity modeling and top-down consumption surveys were triangulated to reconcile production estimates with household pantry penetration metrics.
Granularity-level modeling disaggregated volume and value outputs across product type, end user, ingredient base, and packaging format dimensions, with additional segmentation by regional regulatory cluster. CAGRs were derived from trend extrapolation of per-capita consumption intensities and foodservice penetration rates. Forecast inputs incorporated wheat futures pricing volatility, palm oil supply concentration metrics, and sodium reduction technical ceiling assumptions.
Regulatory enforcement shifts in China, commodity price spikes in wheat and palm oil, and breakthrough sodium reduction technologies are the dominant revision risks that could materially alter trajectory assumptions. A model refresh is warranted upon material change in SAMR certification timelines or FSSAI fortification mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Processed Meat Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Low Fat Pasta Market
Processed Foods
Fermented Foods Market
Processed Foods
Pates Market
Processed Foods
Low-Calorie Margarine Market
Processed Foods
Apple Butter Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Processed Mango Products Market
Processed Foods
United States Egg Powder Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
US Tomato Paste Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Shelf-Stable Soup Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
Soup & Broth Market