
 North America Soup Market | 2026-2036
North America Soup Market Size, Share, and Industry Trends Forecast 2026-2036
North America Soup Market Analytics
Foodservice procurement is consolidating around prepared soup programs that reduce kitchen labor and standardize flavor profiles across multi-unit restaurant chains. The Campbell's Company leverages its institutional distribution network to sustain volume leadership in contract foodservice. Conagra Brands anchors its competitive stance through private-label manufacturing scale and frozen soup innovation. General Mills competes via Progresso brand strength in the retail premium segment, while Kettle & Fire specializes in grass-fed bone broth positioning within the organic ingredient tier.
North America soup comprises liquid or semi-liquid food preparations, typically containing water, stock, or milk combined with vegetables, proteins, and seasonings, then thermally processed to achieve commercial sterility or refrigerated shelf stability. Canned soup retains dominant shelf-stable volume but faces margin compression from aluminum input costs and extended cook-cycle energy demands. Ready-to-eat formats in flexible pouch packaging represent the fastest-expanding structural segment, capturing refrigerated perimeter placement and microwave convenience demand. Organic ingredient classification commands price premiums exceeding conventional formulations, though gluten-free positioning has normalized toward baseline expectation across mass retail channels.
FDA nutrition labeling requirements and USDA organic certification standards shape reformulation investment and market access thresholds for national distribution. Health Canada and PMRA jointly regulate cross-border broth and prepared soup imports through residue limits and bilingual labeling mandates that filter smaller suppliers from Ontario and Quebec retail entry. Stakeholders must monitor evolving sodium reduction targets and recycled-content packaging mandates that will determine which manufacturing configurations retain channel access without capital-intensive retooling.
Market Dynamics
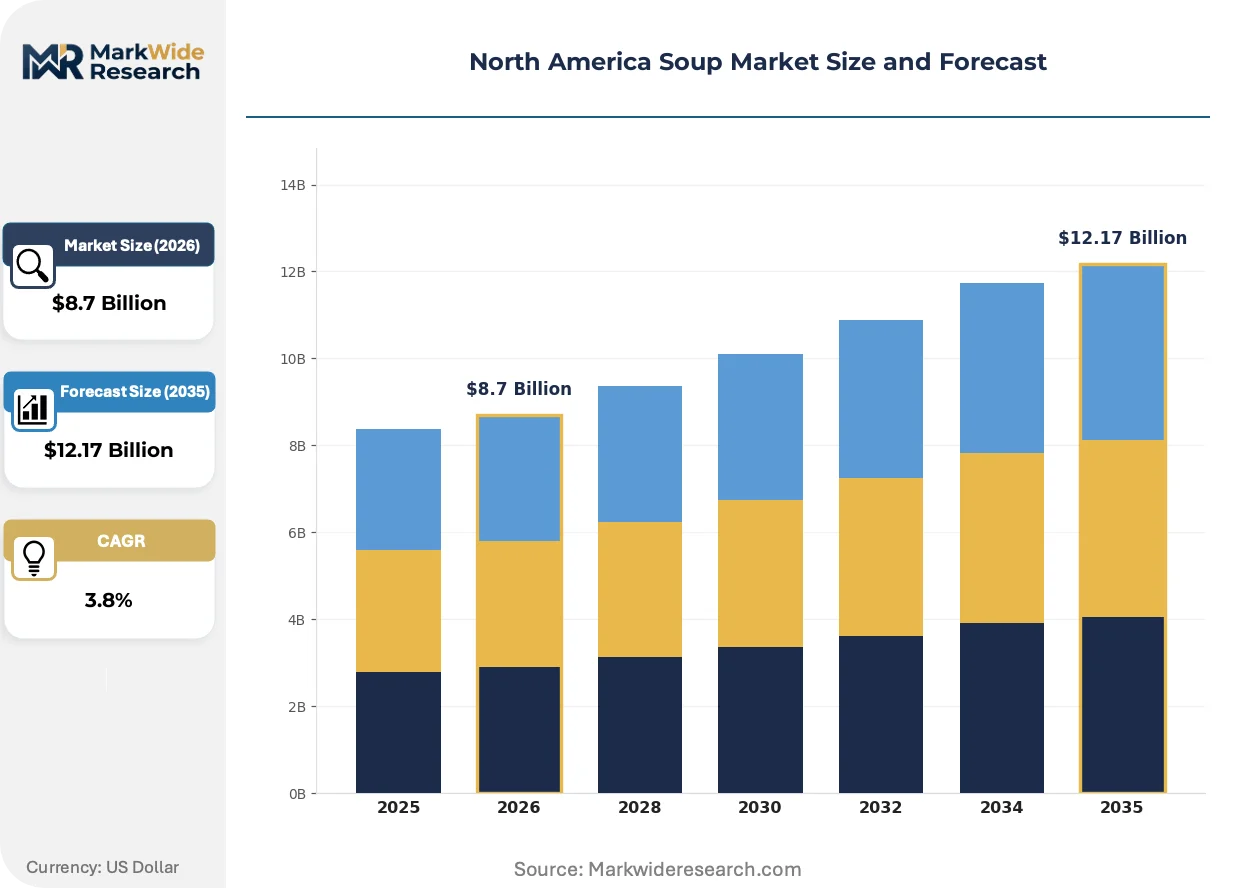
Foodservice procurement consolidation and FDA-mandated nutrition label reformulation are compressing legacy manufacturing configurations while opening shelf-stable alternatives to new entrants.
Growth Catalysts
- USDA Organic Certification:Premium positioning through certified organic ingredient sourcing unlocks price premiums exceeding conventional formulations across mass retail channels.
- Foodservice Labor Reduction:Prepared soup programs reduce kitchen staffing requirements and standardize flavor profiles across multi-unit restaurant chains.
- Flexible Pouch Technology:Refrigerated perimeter placement and microwave convenience demand accelerate ready-to-eat format adoption.
Market Restraints
- Aluminum Input Cost Volatility:Canned soup faces margin compression from volatile aluminum pricing and extended cook-cycle energy demands.
- Cross-Border Regulatory Friction:Health Canada and PMRA residue limits plus bilingual labeling mandates filter smaller suppliers from Ontario and Quebec retail entry.
- Extended Shelf-Life Substitutes:Frozen soup and meal-kit alternatives capture convenience-oriented consumers seeking longer storage flexibility.
Strategic Opportunities
- Functional Broth Expansion:Grass-fed bone broth and collagen-fortified formulations address wellness-oriented consumers in premium organic tiers.
- Recycled-Content Packaging Mandates:Early compliance with emerging state-level post-consumer recycled content requirements secures channel access before capital-intensive retooling becomes mandatory.
- Gluten-Free Normalization:Positioning gluten-free formulations as baseline expectation rather than premium differentiator captures mass-market volume.
Industry Challenges
- Sodium Reduction Technical Gap:Reformulating for FDA sodium targets without flavor degradation requires R&D investment and extended testing cycles.
- Cold Chain Integration Complexity:Refrigerated soup formats demand temperature-controlled distribution infrastructure that legacy shelf-stable networks cannot accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Soup Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Soup, Ready-to-Eat, Frozen Soup, Instant Soup Ingredient Type: Vegetarian, Meat-based, Gluten-free, Organic Packaging Type: Flexible Pouch, Tetra Pack, Glass Jar, Can Distribution Channel: Supermarkets, Online, Convenience Stores, Wholesale |
| Companies Covered | General Mills Inc., Conagra Brands Inc., The Campbell's Company, Kettle & Fire Inc., Nissin Foods, Nestlé SA, Unilever PLC, Blount Fine Foods, Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Soup Market Evolving Landscape
Processing technology and packaging material science are compressing traditional thermal sterilization cycles while regulatory pressure on sodium content forces simultaneous flavor architecture rebuilds.
Retort pouch technology is rewriting the shelf-stable soup segment by enabling shorter cook times and lighter packaging weights than metal cans. Foodservice distributors and convenience retailers are adopting these formats for reduced freight costs and faster inventory turns. The structural consequence is displacement of aluminum-dependent manufacturing lines and opening of co-packing partnerships with flexible packaging specialists.
FDA nutrition labeling requirements are mandating added sugar disclosure and serving-size recalibration that forces reformulation of legacy broth bases. Manufacturers must rebuild flavor profiles using vegetable concentrates and yeast extracts rather than maltodextrin carriers. The premium organic segment faces the steepest compliance costs due to smaller batch sizes and limited reformulation flexibility.
Direct-to-foodservice procurement contracts are consolidating buyer power among multi-unit restaurant chains and institutional operators. These contracts specify prepared soup bases that reduce on-site labor and ingredient inventory. The shift is most visible in the United States, where contract foodservice operators now specify flavor profiles and packaging formats rather than accepting standardized retail SKUs.
North America Soup Market Segmentation
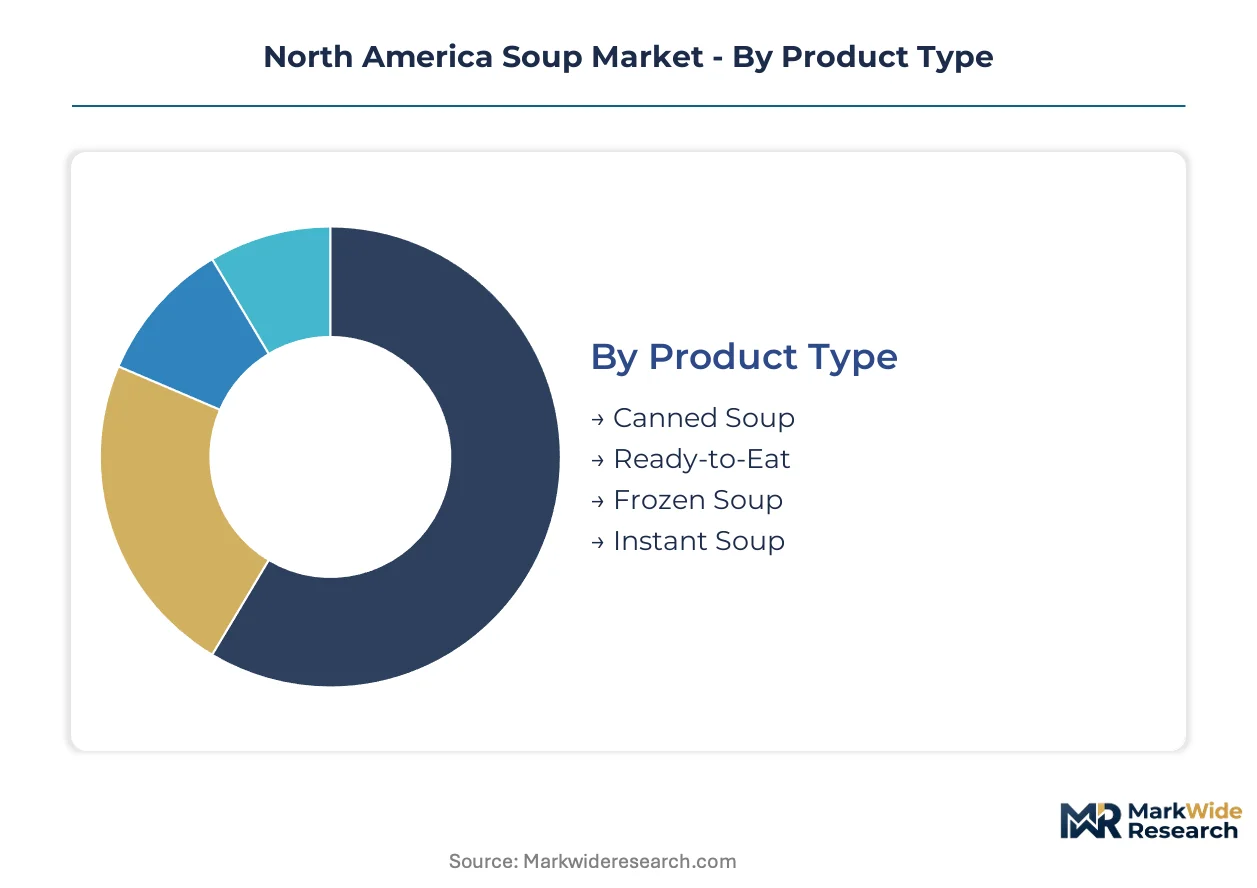
Soup manufacturers configure production assets around format-specific thermal processing requirements and channel-determined packaging specifications. Segment boundaries increasingly blur as retort pouch technology enables canned-equivalent shelf stability with refrigerated-format convenience.
Product Type:
Supply concentration clusters around formats with established co-packing infrastructure and proven cold-chain economics.
- Canned Soup:Metal-container thermal sterilization delivers commercial sterility without refrigeration. Aluminum input cost volatility and extended cook-cycle energy demands compress margins for legacy canning lines across Midwest production facilities.
- Ready-to-Eat:Refrigerated soups in flexible packaging capture perimeter placement and microwave convenience demand. United States retail chains expand refrigerated soup sets fastest in coastal urban markets where cold-chain density supports daily replenishment.
- Frozen Soup:Blast-frozen formulations extend storage flexibility for foodservice operators managing irregular demand patterns. Conagra Brands anchors volume through private-label frozen programs.
- Instant Soup:Dehydrated and concentrated bases require minimal packaging weight and ambient distribution. Powdered formats concentrate in wholesale club and emergency preparedness channels.
Today's leader: Canned Soup. Tomorrow's challenger: Ready-to-Eat.
Ingredient Type:
Cost tier stratification separates commodity formulations from certified organic price premiums exceeding conventional benchmarks.
- Vegetarian:Plant-protein broth bases and vegetable-forward formulations address flexitarian demand without meat-input cost exposure. Campbell's Company extends Progresso vegetable soup lines through reformulated low-sodium variants.
- Meat-based:Chicken, beef, and bone broth formulations retain dominant volume in foodservice prepared soup programs. Kettle & Fire specializes in grass-fed bone broth positioning within premium organic tiers.
- Gluten-free:Celiac-safe certification has normalized toward baseline expectation across mass retail channels rather than commanding price premiums.
- Organic:USDA-certified ingredient sourcing unlocks shelf placement in natural retail and premium conventional sets. Smaller batch sizes and limited reformulation flexibility impose steepest compliance costs for FDA nutrition labeling mandates.
Organic commands the steepest price premiums. Gluten-free has become table stakes.
Packaging Type:
Volume concentration shifts from metal-dependent formats toward flexible materials with lower freight cost per unit.
- Flexible Pouch:Retort and refrigerated pouch formats reduce packaging weight and enable shorter cook cycles than metal cans. Foodservice distributors adopt these formats for faster inventory turns.
- Tetra Pack:Aseptic carton technology suits broth and stock applications with extended ambient shelf life. Tetra Pak equipment requires capital investment that filters smaller regional entrants.
- Glass Jar:Premium positioning and consumer perception of purity support refrigerated organic soup price points. Weight and breakage constraints limit foodservice adoption.
- Can:Aluminum and steel containers retain dominant shelf-stable volume but face margin compression from input cost volatility and emerging state-level recycled-content mandates.
Flexible Pouch is climbing the fastest. Can retains volume leadership.
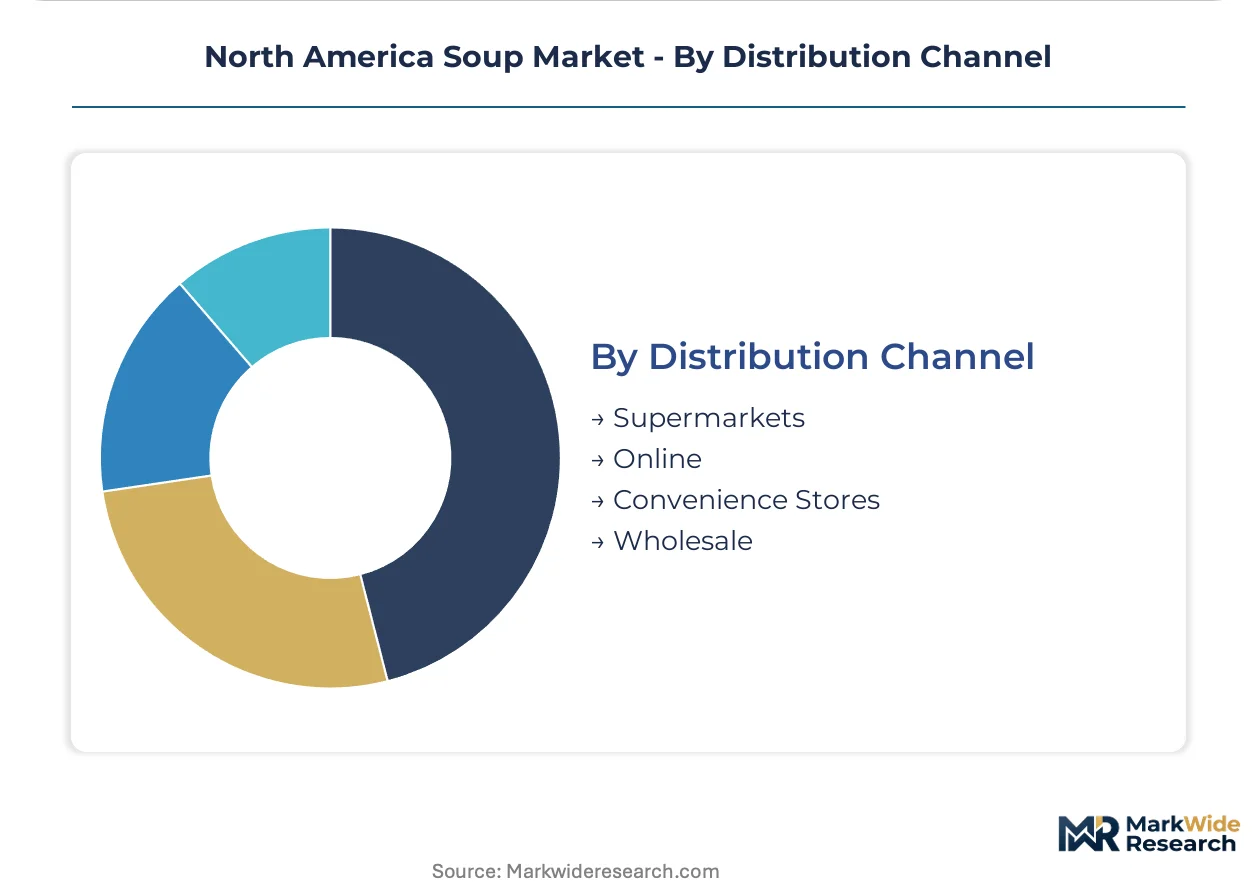
Distribution Channel:
Customer type determines packaging format specifications and replenishment frequency requirements.
- Supermarkets:Center-store shelf-stable and refrigerated perimeter placement drive volume for national brand portfolios. Retailers specify private-label programs that mirror branded ingredient positioning.
- Online:Direct-to-consumer subscription models concentrate in premium organic and functional broth categories. Shipping economics favor shelf-stable formats over refrigerated alternatives.
- Convenience Stores:Single-serve microwaveable cups and retort pouches address immediate consumption demand. Limited cold-chain capacity restricts refrigerated format penetration.
- Wholesale:Foodservice and institutional procurement contracts specify prepared soup bases in bulk formats. Multi-unit restaurant chains consolidate buyer power through direct supplier negotiations.
Supermarkets anchor current volume. Online represents the fastest-expanding trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Midwest manufacturing corridor anchors North American soup production, with Chicago and Cincinnati serving as primary co-packing and distribution nodes for shelf-stable formats.
United States
Premium organic broth demand concentrates in coastal urban markets, particularly New York City and Los Angeles, where refrigerated perimeter placement expands fastest. FDA nutrition labeling mandates and sodium reduction targets force reformulation investment across national brand portfolios. Campbell's Company leverages its institutional distribution network from Camden, New Jersey to sustain contract foodservice volume leadership.
Canada
Bilingual labeling requirements and Health Canada residue limits filter smaller US suppliers from Ontario and Quebec retail entry. Toronto and Montreal anchor the country's prepared soup procurement for multi-unit restaurant chains. Cross-border regulatory friction with PMRA standards complicates bone broth importation from US grass-fed suppliers.
Mexico
Instant soup and dehydrated bases dominate mass-market consumption through wholesale club channels in Mexico City and Guadalajara. Domestic manufacturers face limited pressure from US organic certification standards, though NOM labeling requirements shape export-oriented production. Guanajuato's food processing corridor hosts regional co-packers serving Central American markets.
North America Soup Market Competitive Landscape
Foodservice procurement consolidation dominates the current landscape, compressing margins for legacy retail-centric manufacturers while opening contract pathways for prepared soup specialists. The market structure reflects a tiered configuration: multinational conglomerates with diversified pantry portfolios, mid-cap organic specialists with premium positioning, and private-label manufacturers serving retailer-specific programs. Two strategic archetypes define competitive positioning: scale-driven shelf-stable producers optimizing aluminum-dependent supply chains, and agile refrigerated format innovators capturing perimeter placement growth. Dominant competitive moves include backward integration into ingredient sourcing and co-packing partnership expansion for flexible pouch capacity.
Among US-based diversified food manufacturers, General Mills Inc., Conagra Brands Inc., and The Campbell's Company exemplify distinct competitive archetypes. General Mills Inc. occupies a position within the premium retail segment through brand equity in ready-to-serve formats. Conagra Brands Inc. anchors private-label manufacturing scale and frozen soup innovation capacity. The Campbell's Company represents the institutional distribution model, leveraging long-standing foodservice relationships to defend volume positions against refrigerated format challengers.
| Leading Market Players |
|---|
| General Mills Inc. |
| Conagra Brands Inc. |
| The Campbell's Company |
| Kettle & Fire Inc. |
| Nissin Foods |
| Nestlé SA |
| Unilever PLC |
| Blount Fine Foods |
| Kraft Heinz Company |
| Others |
Value Network & Pricing Analysis
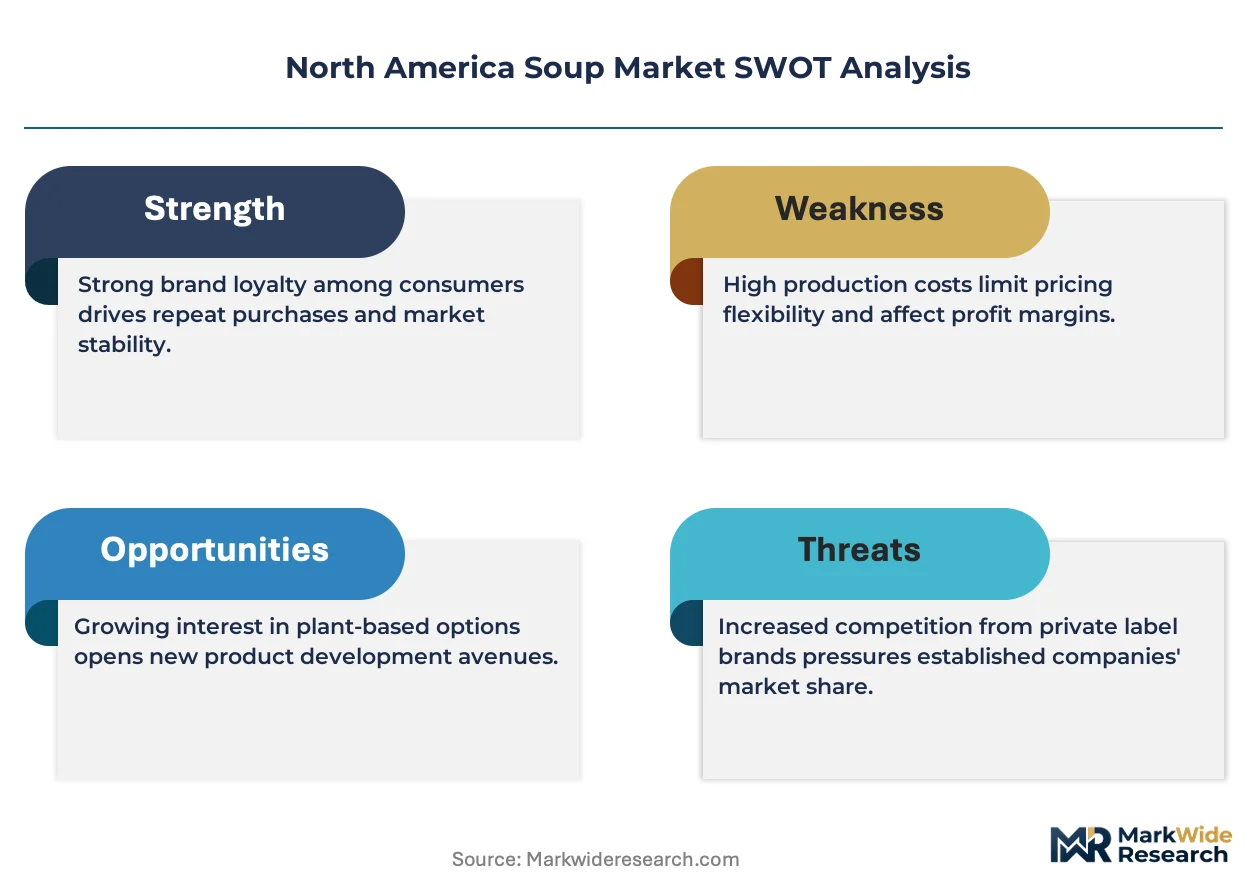
State-level post-consumer recycled content mandates in California and New York gate qualified supply access and premium-tier pricing power, as early compliance secures channel placement before capital-intensive retooling becomes mandatory for aluminum-dependent canning lines.
Pricing Analysis
Retailer markup layers in supermarket channels compress manufacturer margins while foodservice direct contracts bypass distributor tiers entirely. Three-tier pricing structure across premium organic, conventional branded, and private-label economy levels separates USDA-certified formulations from standard shelf-stable and entry-level instant formats. Pricing pressure stems from volatile aluminum input costs squeezing legacy canning operations. Mass-market private-label buyers exhibit highest price sensitivity, while premium organic consumers absorb double-digit premiums for grass-fed bone broth positioning.
Supply Chain Analysis
Freight cost differentials between aluminum cans and flexible pouches reshape procurement economics across Midwest distribution nodes. Manufacturing concentrates in the United States, Canada, and Mexico, with Chicago and Cincinnati anchoring co-packing infrastructure for shelf-stable formats. Raw material dependencies span aluminum sheet, grass-fed livestock inputs, and organic vegetable concentrates. Single-source vulnerability in aluminum smelting capacity exposes margin compression risk. Distribution runs through foodservice institutional networks and retail supermarket chains with diverging format specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA nutrition labeling mandates compound demand for reformulation investment, creating structural advantages for manufacturers with R&D scale and certified organic supply chains.
For Market Incumbents: Anticipate sodium reduction technical gaps by rebuilding flavor architectures through vegetable concentrates and yeast extracts before mandatory compliance deadlines. Secure backward integration into grass-fed livestock sourcing to defend premium organic positioning against emerging bone broth specialists. Channel control through institutional foodservice contracts remains the critical lever against refrigerated format displacement. For New Entrants and Emerging Players: Health Canada bilingual labeling requirements in Ontario and Quebec open a window for domestic co-packing partnerships that filter smaller US suppliers from cross-border retail entry. Target instant soup and dehydrated bases in Mexico's wholesale club channels where NOM standards create localization barriers. Lead with direct-to-consumer subscription models for functional broth categories to bypass supermarket slotting fee structures. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap organic specialists with certified supply chains because USDA compliance costs and FDA reformulation mandates consolidate smaller batch producers into acquirable platforms. Acquisition target archetypes include refrigerated pouch co-packers with proven cold-chain economics and grass-fed bone broth brands with premium pricing power. Watch for inflection when state recycled-content packaging mandates trigger mandatory capital retooling across legacy canning assets.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Format Expansion | Captures perimeter placement growth in coastal urban markets with cold-chain density. |
| Grass-Fed Sourcing Integration | Secures premium organic tier positioning against commodity broth competitors. |
| Retort Pouch Capacity Addition | Reduces aluminum dependency while enabling foodservice distributor adoption. |
| Direct-to-Foodservice Contracting | Bypasses retail margin layers through multi-unit restaurant chain procurement. |
| Sodium Reduction R&D Investment | Addresses FDA compliance mandates without flavor degradation in reformulated lines. |
Research Methodology
Direct dialogue with foodservice procurement directors, retail category buyers, organic certification specialists, and flexible packaging co-packers grounds qualitative findings in operational reality. Secondary validation draws from FDA labeling guidance documents, USDA organic certification databases, Nielsen retail audit data, and customs import records for bone broth formulations. Bottom-up volume modeling triangulates against top-down market sizing across the analysis window.
Bottom-up segmentation modeling tracks product type, ingredient certification, packaging format, and distribution channel dimensions throughout the forecast period. CAGRs derive from historical volume trajectories adjusted for regulatory milestone impacts and channel shift elasticity. Industry-specific forecast inputs include aluminum price volatility indices and refrigerated shelf-space expansion rates in US supermarket chains.
Revisions become necessary when FDA sodium reduction targets accelerate, state recycled-content mandates expand beyond California and New York, or foodservice procurement consolidation shifts contract specifications toward prepared soup bases. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Egg Powder Market
Processed Foods
Processed Potatoes Market
Processed Foods
Fat Free Food Market
Processed Foods
Global Potato Flake Market
Processed Foods
South America Processed Meat Market
Processed Foods
Low Fat Puddings Market
Processed Foods
Egg White Cubes Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
Processed Vegetable Market
Processed Foods
Coffee Creamer Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Europe Soup Market
Processed Foods
Accompanying Marinated Product Market