
 Spray Cheese Market | 2026-2036
Spray Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Cheese Market Analysis
Plant-based fat and protein isolates is hardening as a cost-competitive alternative to conventional dairy solids in spray cheese formulations. The Kraft Heinz Company leverages its refrigerated logistics network to sustain retail shelf presence across North American supermarkets. Conagra Brands anchors its position through private-label manufacturing scale and food-service channel control. Savencia differentiates via European cheese heritage adapted for industrial aerosol processing.
Spray cheese is an emulsified, processed cheese product dispensed through pressurized aerosol systems or squeeze containers, typically containing cheese solids, emulsifying salts, stabilizers, and propellants to achieve a smooth, extrudable texture suitable for crackers, vegetables, and prepared foods. The aerosol can format dominates household impulse purchases due to extended shelf stability and portion control, while the food service end user segment leads absolute volume through back-of-house dispensing efficiency in quick-service kitchens. Cheddar product type occupies the largest share of current manufacturing throughput, though mozzarella variants are gaining traction in pizza-focused food service applications.
The FDA governs pasteurized processed cheese product standards of identity, while the USDA oversees dairy grading and plant inspection protocols that constrain formulation flexibility and label claims. State-level dairy compacts in Wisconsin and California impose additional fluid milk pricing regulations that ripple into spray cheese input costs. Stakeholders must monitor how clean-label ingredient scrutiny and propellant-phase environmental regulations reshape acceptable formulation boundaries and packaging technology investments.
Market Dynamics
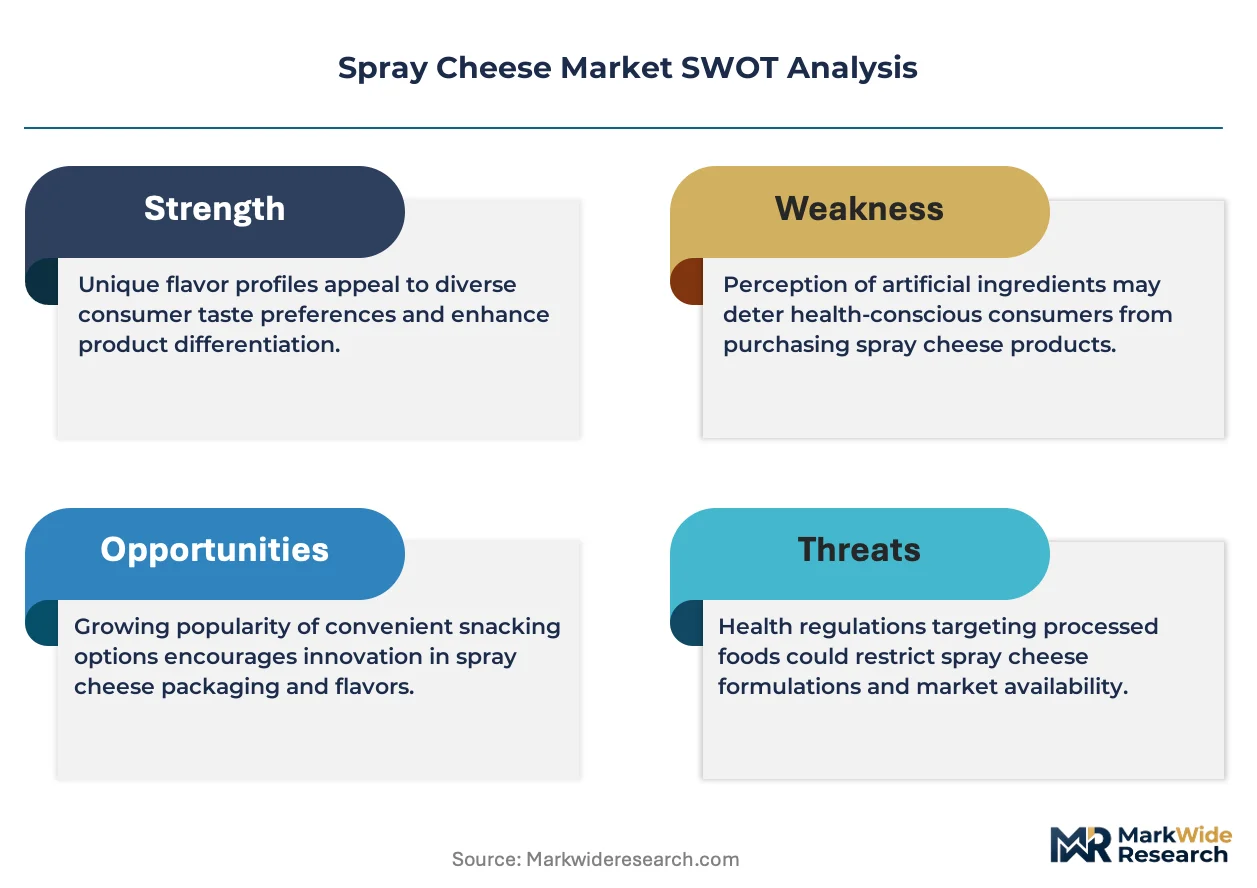
Reformulation pressure from clean-label ingredient scrutiny is compressing traditional emulsifier reliance while aerosol propellant phase-outs force packaging technology reinvestment across manufacturing footprints.
Growth Catalysts
- Urban household snacking intensity:Convenience-driven consumption patterns in metropolitan clusters sustain aerosol can format penetration through impulse retail channels and pantry-stocking velocity.
- FDA processed cheese identity standards:Evolving label requirements for pasteurized processed cheese products create compliance-driven product line refresh cycles that stimulate manufacturing equipment upgrades.
- Quick-service restaurant back-of-house efficiency:Food service procurement consolidation favors portion-controlled dispensing formats that reduce labor time and waste in high-volume kitchen environments.
Market Restraints
- Dairy input cost volatility:Wisconsin and California state dairy compact pricing mechanisms transmit fluid milk cost fluctuations directly into spray cheese manufacturing margins.
- Propellant environmental regulations:EPA phase-out schedules for hydrofluorocarbon aerosol propellants constrain formulation flexibility and require capital-intensive alternative propellant qualification.
- Plant-based cheese substitution:Fat and protein isolate alternatives from oat, cashew, and coconut sources capture label-conscious consumers in premium retail segments.
Strategic Opportunities
- Mozzarella variant expansion:Pizza-focused food service applications represent underdeveloped throughput potential beyond dominant cheddar manufacturing lines.
- Private-label manufacturing scale:Supermarket chain captive brand programs offer volume commitments that amortize dedicated production line investments.
- Squeeze container format development:Non-aerosol dispensing systems bypass propellant regulatory constraints while targeting sustainability-positioned retail channels.
Industry Challenges
- Emulsifier chemist talent scarcity:Specialized formulation expertise for stable aerosol cheese texture under variable temperature conditions commands premium compensation in competitive labor markets.
- Clean-label certification timelines:Third-party verification programs for "natural" and "organic" claims extend product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Cheese Market |
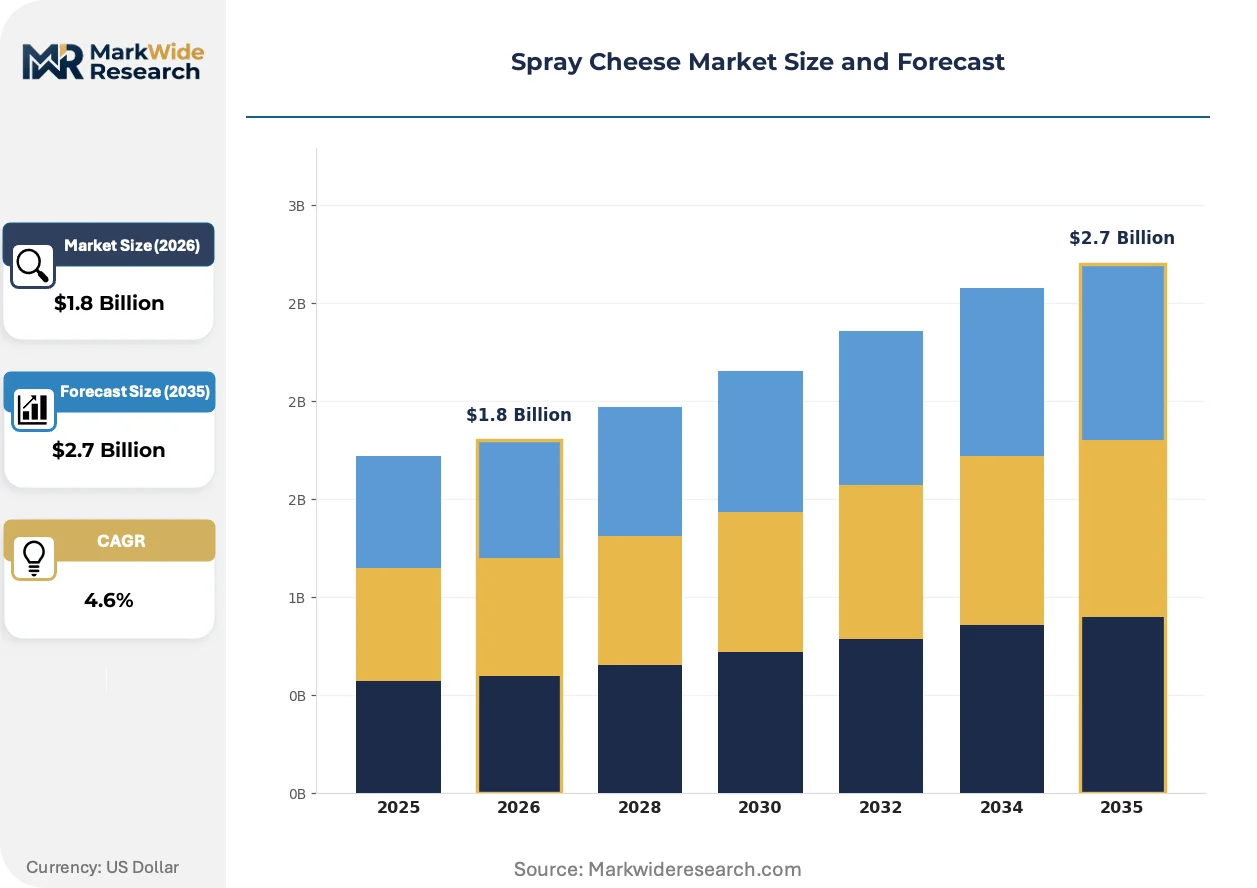
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Swiss, American End User: Household, Food Service, Retailers, Industrial Packaging Type: Aerosol Cans, Pouches, Jars, Tubs Distribution Channel: Supermarkets, Online, Convenience Stores, Wholesale |
| Companies Covered | The Kraft Heinz Company, Conagra Brands, Savencia, Lactalis Group, Bel Group, Hormel Foods Corporation, Land O'Lakes, Sargento Foods, Ricos Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Cheese Market Emerging Trajectories
Active reformulation of stabilizer systems and propellant chemistries dominates current manufacturing priorities, with sustainability credentials and processing efficiency operating as dual selection filters for technology adoption.
Plant-based fat and protein isolates is overtaking conventional dairy solids in pilot production lines. Food service procurement teams at national restaurant chains are requesting sample volumes at accelerating frequency. This ingredient transition is compressing traditional dairy supplier contract tenures and forcing reformulation partnerships with alternative protein ingredient houses.
EPA hydrofluorocarbon propellant phase-down mandates under the AIM Act impose 85% reduction targets by 2036. Aerosol cheese manufacturers must qualify hydrofluoroolefin or compressed gas alternatives without compromising extrusion consistency. The food service dispensing segment faces the steepest compliance timeline given back-of-house temperature variability requirements.
Direct-to-operator procurement platforms are fragmenting traditional food service distributor relationships. Regional quick-service restaurant groups now source spray cheese through consolidated online portals that bypass broadline distribution markups. This channel disintermediation concentrates most visibly in the southeastern United States where independent pizza chain density supports platform viability.
Spray Cheese Market Segmentation
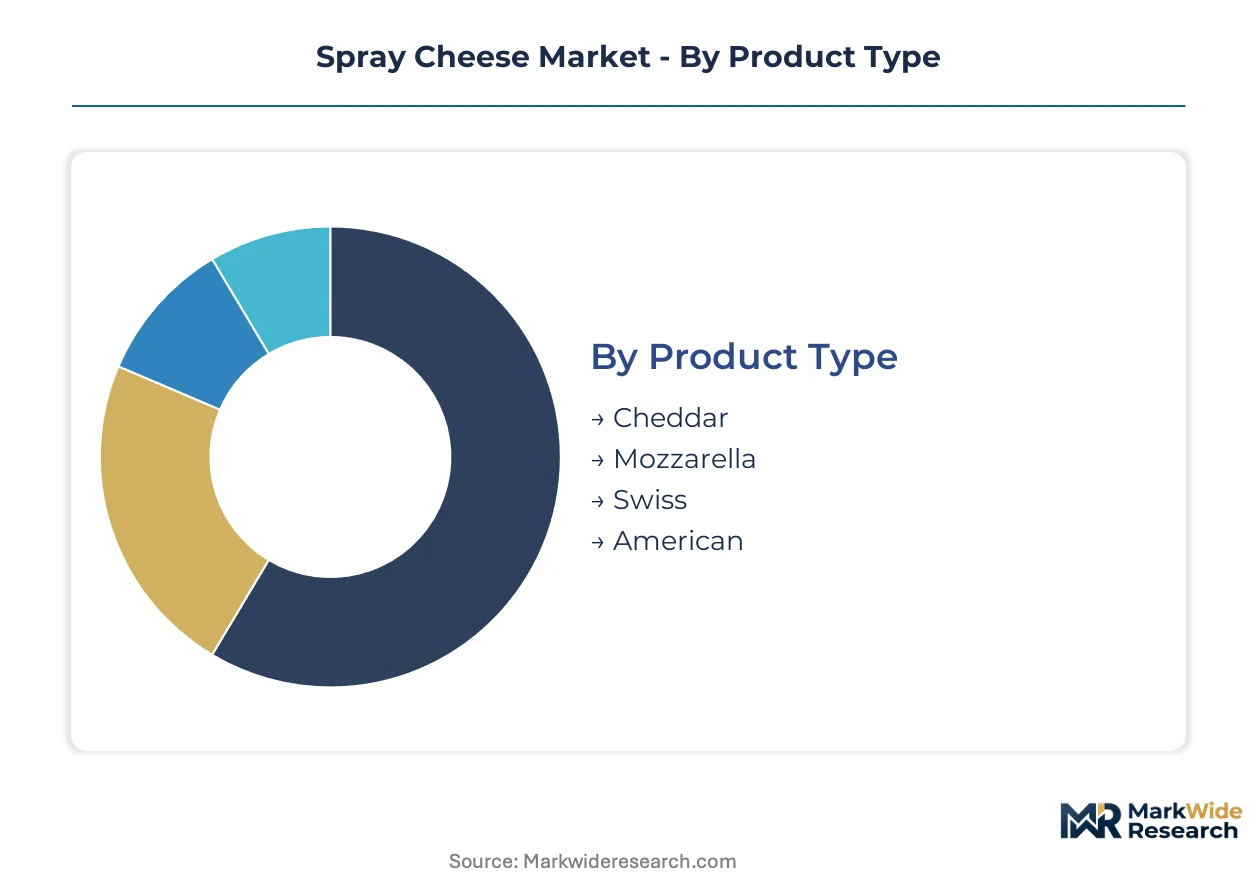
Spray cheese segmentation reveals how formulation chemistry, dispensing technology, and procurement channel economics partition demand across distinct customer workflows. Category boundaries align with temperature stability requirements, portion control needs, and regulatory exposure profiles that shape manufacturing investment priorities.
Product Type:
Integration depth varies sharply: cheddar and mozzarella anchor standalone retail and food service applications, while Swiss and American variants embed primarily in prepared food manufacturing systems.
- Cheddar:Sharp-flavored processed cheese solids with annatto coloring dominate aerosol throughput due to familiar taste profiles and stable emulsion behavior across temperature ranges. Demand concentrates in United States pantry-stocking households and quick-service restaurant back-of-house operations where portion consistency drives procurement specifications.
- Mozzarella:Mild, stretch-optimized formulations with lower moisture content target pizza-focused food service applications requiring melt performance under variable oven conditions. United States independent pizza chains and regional quick-service groups in the Southeast source mozzarella spray formats through direct-to-operator procurement platforms that bypass traditional broadline distributors.
- Swiss:Nutty-flavored variants with characteristic eye formation simulate traditional Swiss cheese profiles in industrial prepared food applications.
- American:Mild, highly processed formulations with superior meltability integrate into frozen prepared meal manufacturing lines and institutional feeding programs.
Volume placements concentrate in Cheddar; the faster expansion belongs to Mozzarella.
End User:
Cost tier stratification separates impulse-driven household purchases from efficiency-optimized institutional procurement, with margin structure diverging sharply across the four user categories.
- Household:Impulse-oriented consumers purchasing single-unit aerosol cans through supermarket and convenience store channels prioritize shelf stability and portion control over unit economics. United States metropolitan households drive the highest pantry-stocking velocity, particularly in urban clusters where snacking frequency correlates with smaller refrigerator footprints.
- Food Service:National quick-service restaurant chains and regional pizza groups procure bulk formats through consolidated online portals, demanding dispensing efficiency and waste reduction in high-volume kitchen environments. Back-of-house temperature variability requirements impose the steepest compliance timelines for EPA hydrofluorocarbon propellant phase-down mandates.
- Retailers:Supermarket chains and mass merchandisers source private-label spray cheese through captive brand programs that amortize dedicated production line investments.
- Industrial:Frozen prepared meal manufacturers and institutional feeding contractors integrate spray cheese as an ingredient input rather than finished product, purchasing in bulk tote or drum formats.
Food Service commands absolute volume throughput; Household delivers the steepest expansion trajectory as urban snacking intensity climbs.
Packaging Type:
Application context determines format selection: pressurized systems serve high-frequency dispensing environments while non-pressurized alternatives target sustainability-positioned retail channels.
- Aerosol Cans:Pressurized aluminum containers with hydrocarbon or hydrofluoroolefin propellants deliver extended shelf stability and precise portion control. United States supermarkets and convenience stores stock aerosol formats as the dominant household impulse purchase vehicle, though EPA AIM Act compliance deadlines force qualification of alternative propellant chemistries.
- Pouches:Flexible film packaging with squeeze-dispense functionality targets sustainability-conscious retail channels seeking to bypass aerosol regulatory constraints entirely.
- Jars:Wide-mouth glass or plastic containers with screw-cap closures serve bulk food service and industrial procurement requiring spoonable texture access.
- Tubs:Multi-serve plastic containers with peel-back lids accommodate high-volume institutional feeding programs and prepared food manufacturing lines.
Volume placements concentrate in Aerosol Cans; Pouches are gaining share fastest as clean-label and sustainability credentials reshape retail channel requirements.
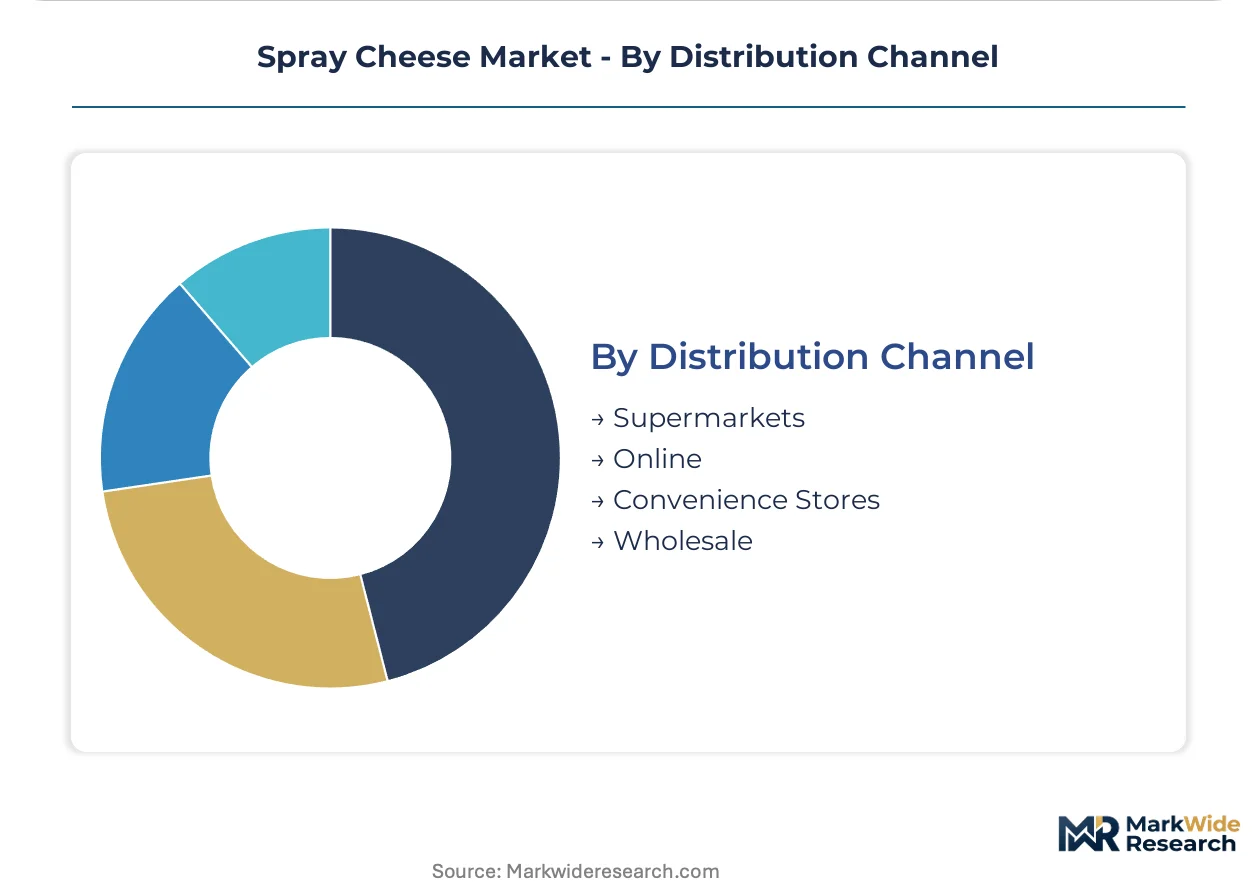
Distribution Channel:
Customer type and purchase scale fragment procurement pathways, with channel disintermediation concentrating most visibly in regional quick-service restaurant sourcing patterns.
- Supermarkets:National and regional grocery chains maintain refrigerated logistics networks that sustain spray cheese shelf presence through controlled cold-chain distribution. The Kraft Heinz Company leverages these established relationships to defend retail market position across North American supermarket footprints.
- Online:Direct-to-operator procurement platforms and e-commerce marketplaces fragment traditional food service distributor relationships, particularly in the southeastern United States where independent pizza chain density supports platform viability.
- Convenience Stores:Small-format retail locations with limited refrigerated space prioritize extended-shelf-life aerosol formats for grab-and-go snacking occasions.
- Wholesale:Broadline food service distributors and cash-and-carry warehouse clubs serve institutional and industrial volume procurement with pallet-scale fulfillment and negotiated contract pricing.
Supermarkets anchor current volume; Online channels are expanding most quickly as procurement digitization accelerates across food service operator segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households drive the highest pantry-stocking velocity for aerosol cheese formats, with urban clusters sustaining impulse retail channel penetration through convenience-oriented snacking patterns.
United States
Metropolitan households in Chicago, New York, and Los Angeles sustain the steepest aerosol can purchase frequency through supermarket and convenience store channels. FDA pasteurized processed cheese product standards of identity govern label requirements and formulation flexibility. Wisconsin dairy compact pricing mechanisms transmit fluid milk cost fluctuations directly into manufacturing margins for Midwest production facilities.
Canada
Health Canada dairy product regulations constrain aerosol cheese import volumes while sustaining domestic processor market share in Ontario and Quebec retail channels. CFIA inspection protocols for dairy processing plants impose compliance timelines that extend product registration cycles. Toronto and Vancouver metropolitan areas concentrate food service procurement through broadline distributor networks serving quick-service restaurant chains.
Germany
EFSA processed cheese additive approvals shape reformulation priorities for aerosol formats targeting Central European retail shelves. REACH chemical registration requirements constrain propellant chemistry selection for pressurized dispensing systems. Bavaria and North Rhine-Westphalia industrial dairy clusters host contract manufacturing facilities serving private-label supermarket programs across the European Union.
United Kingdom
Post-Brexit UKCA marking requirements for food contact materials extend packaging qualification timelines for aerosol can imports from continental suppliers. FSA clean-label guidance documents pressure emulsifier system reformulation away from traditional phosphate salts. London and Southeast England convenience retail chains prioritize extended-shelf-life formats for grab-and-go snacking occasions in high-density urban zones.
Australia
FSANZ processed food standards code provisions govern cheese product identity claims and additive permissions for aerosol formats. ACCC consumer protection enforcement targets misleading "natural" and "premium" label claims in supermarket channels. New South Wales and Victoria metropolitan markets concentrate food service demand through independent pizza chain procurement that bypasses traditional distributor markups via direct-to-operator platforms.
Spray Cheese Market Vendor Landscape
Portfolio diversification dominates the current landscape as established dairy processors extend into aerosol formats while specialty players defend niche positioning through formulation expertise. The vendor base concentrates around three strategic archetypes: diversified packaged food conglomerates with refrigerated logistics scale, European heritage dairy specialists with industrial processing capabilities, and regional private-label manufacturers serving captive supermarket programs. M&A activity and capacity expansion represent the two dominant competitive moves, with asset-light brands seeking contract manufacturing partnerships to bypass capital-intensive propellant qualification requirements.
Among diversified packaged food conglomerates, The Kraft Heinz Company and Conagra Brands occupy positions that exemplify scale-driven refrigerated distribution advantages across North American retail footprints. Savencia represents the European heritage specialist archetype, anchoring industrial aerosol processing capabilities derived from traditional cheese-making expertise. These three entities collectively illustrate how regulatory compliance burden and clean-label reformulation pressure favor organizations with established formulation chemist teams and capital reserves for propellant technology transitions.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Conagra Brands |
| Savencia |
| Lactalis Group |
| Bel Group |
| Hormel Foods Corporation |
| Land O'Lakes |
| Sargento Foods |
| Ricos Products |
| Others |
Supply Flow & Price Mechanics
Alternative propellant qualification under EPA AIM Act mandates simultaneously escalates capital equipment costs and consolidates manufacturing capacity toward players with balance sheet depth. Wisconsin and California dairy compact pricing mechanisms transmit fluid milk volatility directly into spray cheese input costs, compressing margin buffers for regional processors lacking backward integration into dairy solids sourcing.
Pricing Analysis
Volume throughput concentrates in food service contract tiers while margin capture clusters in premium retail formats. Three-tier pricing structure across premium clean-label, standard processed, and economy private-label levels stratifies buyer segments. Price differentiation hinges on emulsifier system complexity and organic certification status. Food service procurement teams exhibit lowest price sensitivity due to dispensing efficiency requirements, while independent retailers face acute cost compression from distributor markup fragmentation.
Supply Chain Analysis
Regional distribution centers in Chicago, Los Angeles, and Toronto anchor hub-and-spoke refrigerated logistics patterns for aerosol can fulfillment. Manufacturing draws from fluid milk suppliers in Wisconsin and California, emulsifier chemical producers in Germany, and aluminum can fabricators in the United States. Single-source vulnerability concentrates in hydrofluoroolefin propellant suppliers qualified under EPA mandates. Distribution runs through broadline food service distributors, supermarket chain direct delivery, and emerging direct-to-operator platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray cheese manufacturing is consolidating toward diversified packaged food conglomerates as propellant transition costs and clean-label reformulation timelines force sub-scale processors toward contract manufacturing or exit.
For Market Incumbents: Hedge against dairy input volatility through captive supply arrangements with Wisconsin fluid milk cooperatives. Accelerate hydrofluoroolefin propellant qualification to secure food service dispensing contracts before EPA compliance deadlines. Defend retail shelf position via refrigerated logistics scale that regional private-label manufacturers cannot replicate. For New Entrants and Emerging Players: Capture white-space opportunity in mozzarella spray formats for pizza-focused independent chains in the southeastern United States. Target sustainability-positioned retail channels with squeeze-pouch formats that bypass aerosol regulatory constraints entirely. Lead with direct-to-operator platform relationships that bypass established broadline distributor markups. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified packaged food conglomerates seeking refrigerated distribution scale. Long-term viability favors processors with in-house emulsifier formulation chemists and propellant qualification capabilities. Watch for inflection when EPA propellant phase-down enforcement accelerates contract manufacturing demand from asset-light brands.| Strategic Initiative | Industry Significance |
|---|---|
| Propellant Technology Transition | EPA AIM Act compliance forces capital-intensive hydrofluoroolefin qualification ahead of 2036 reduction targets. |
| Backward Integration into Dairy Solids | Captive fluid milk supply from Wisconsin cooperatives insulates margins from state compact pricing volatility. |
| Direct-to-Operator Platform Launch | Online procurement portals bypass broadline distributor markups for independent pizza chains in the Southeast. |
| Clean-Label Certification Investment | Third-party organic verification extends product development cycles but unlocks premium retail shelf positioning. |
| Private-Label Manufacturing Scale-Up | Dedicated production lines for supermarket captive brands amortize equipment costs across volume commitments. |
Methodological Framework
Independent corroboration across formulation chemists at aerosol cheese manufacturers, procurement directors at national quick-service restaurant chains, and category buyers at North American supermarket chains underwrites the qualitative findings. Secondary validation drew from FDA processed cheese product standards filings, EPA AIM Act regulatory dockets, Wisconsin and California dairy compact pricing records, and USDA dairy plant inspection reports. Bottom-up demand modeling triangulated against top-down manufacturing capacity assessments.
Comparable-period anchoring to historical aerosol cheese shipment data established baseline volume trajectories across the projection horizon. Segmentation dimensions modeled include product type chemistry, packaging format technology, end-user procurement scale, and distribution channel structure. CAGRs were derived from trend extrapolation adjusted for regulatory compliance timelines and ingredient substitution elasticities. Forecast inputs incorporated fluid milk price index movements and propellant technology adoption curves.
The model holds under stable dairy compact pricing and EPA enforcement schedules; deviation in propellant qualification delays or clean-label certification bottlenecks would shift throughput assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Mashed Potatoes Market
Processed Foods
Chocolate Filling Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Instant Curry Market
Processed Foods
Sugar-Free Ice Cream Market
Processed Foods
Fermented Foods Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Low Calorie Rice Pudding Market
Processed Foods
Margarine Market
Processed Foods
High Pressure Processing (HPP) for Rice and Grain Market
Processed Foods
Block Margarine Market
Processed Foods
Processed Egg Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Global Take Out Fried Chicken Market