
 Yogurt Dip Market | 2026-2036
Yogurt Dip Market Size, Share, and Industry Trends Forecast 2026-2036
Yogurt Dip Market Insights
Australia is rewriting capacity dynamics in the yogurt dip sector through expanded cultured dairy processing infrastructure aimed at export-grade output. Chobani Global Holdings leverages its integrated milk supply and fermentation expertise to sustain cost advantages across North American retail channels. Fage anchors its position through thick-strained Greek yogurt formulations that dominate Mediterranean-style dip positioning. General Mills competes via broad distribution reach and multi-brand portfolio depth in conventional grocery.
Yogurt dip denotes a cultured dairy preparation, typically containing live bacterial cultures, milk solids, and stabilizers, produced through controlled fermentation at specific temperature ranges before flavor incorporation and cold-chain distribution. The product serves as a refrigerated condiment, snack accompaniment, and recipe ingredient across retail and foodservice channels. Herb-infused variants occupy the strongest margin pools due to premium positioning and ingredient complexity, while single-serve packaging formats are capturing the fastest growth as convenience-oriented consumption expands. Bulk container sales to restaurants and catering services remain structurally mature with stable volume but compressed per-unit returns.
The FDA governs yogurt identity standards and labeling requirements in the United States, while the USDA oversees Grade A dairy plant inspections that affect production access. EFSA and national regulators across the European Union enforce strict pathogen limits and additive authorizations that shape export compliance burdens. Stakeholders must monitor evolving clean-label certification thresholds and regional dairy quota negotiations that will determine competitive manufacturing footprints.
Market Dynamics
Clean-label reformulation pressures and stricter allergen disclosure mandates are compressing formulation timelines while fragmenting supplier bases across refrigerated dairy supply chains. Manufacturers now face simultaneous demands for shorter ingredient decks, live culture preservation, and extended shelf stability.
Growth Catalysts
- Quick-service menu expansion:Foodservice operators in the United States are embedding yogurt dips into limited-time offers and permanent side-dish rotations, creating pull-through for bulk and portion-pack formats.
- EU allergen disclosure rules:Stricter labeling mandates under EFSA guidance are accelerating clean-label R&D investments, rewarding early movers with retail shelf-space premiums.
- Cultured dairy processing infrastructure:Australia's expanded fermentation capacity is lowering export-grade unit costs and reshaping competitive sourcing options for Asia-Pacific buyers.
Market Restraints
- Fresh milk input volatility:Dairy commodity price swings directly compress margin pools for manufacturers lacking backward integration into milk supply.
- Cold-chain concentration risk:Refrigerated logistics capacity bottlenecks in the United States limit distribution reach for regional brands seeking national retail placement.
- Plant-based substitution:Cashew and oat-based dip alternatives are capturing shelf space in conventional grocery, particularly among flexitarian households.
Strategic Opportunities
- Single-serve packaging innovation:Convenience-oriented consumption in the United States is driving demand for portion-controlled formats in workplace and on-the-go channels.
- Herb-infused premium positioning:Complex flavor profiles command pricing power in specialty retail, with Mediterranean and Middle Eastern variants showing particular traction.
- Foodservice contract manufacturing:Co-packing arrangements for quick-service chains offer volume stability and reduced retail slotting fee exposure.
Industry Challenges
- Fermentation science talent scarcity:Live culture management and phage control expertise is concentrating among a limited pool of dairy technologists.
- Clean-label certification timelines:Third-party non-GMO and organic validations are extending product launch cycles by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yogurt Dip Market |
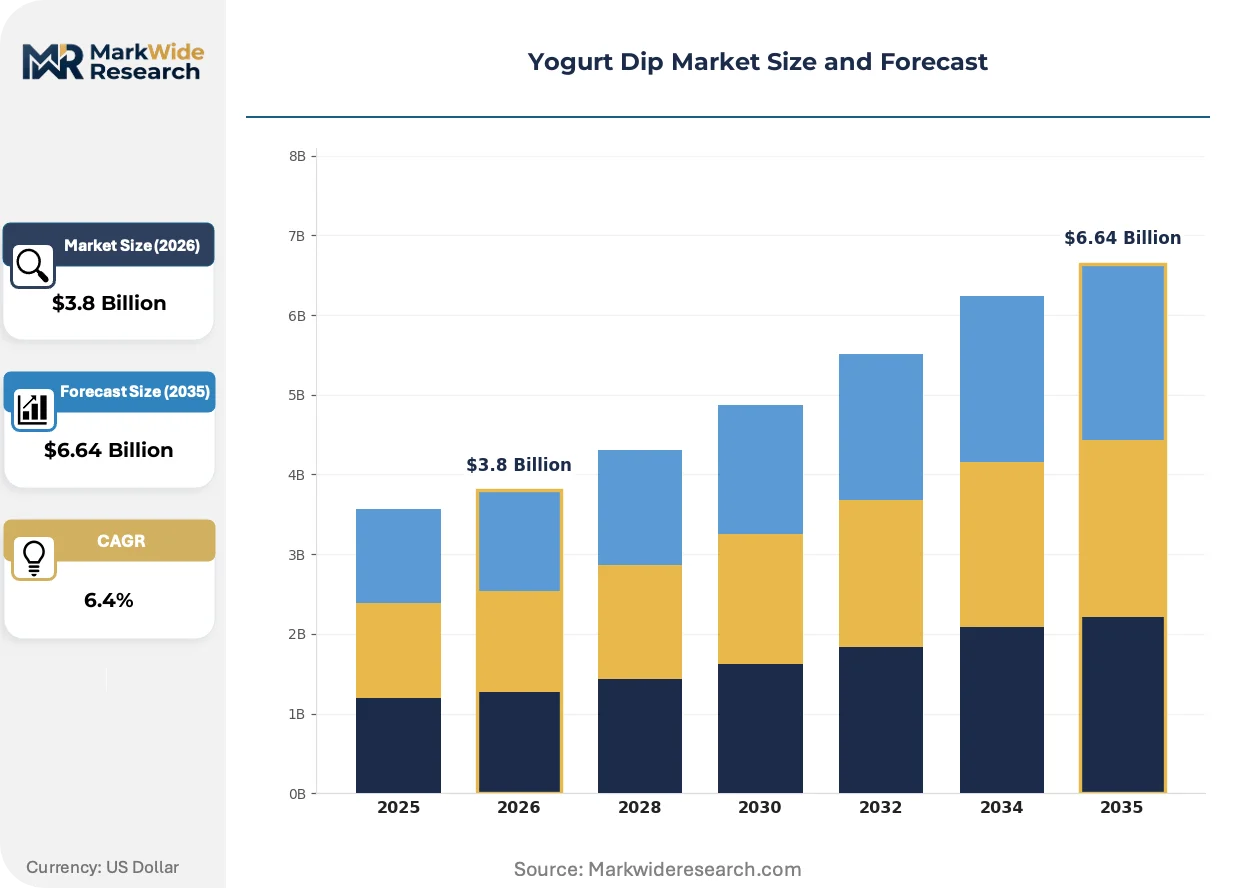
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Herb-infused, Spicy, Sweetened Packaging Type: Single Serve, Family Pack, Bulk Container, Tube End User: Households, Restaurants, Catering Services, Food Trucks Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Shops |
| Companies Covered | Chobani Global Holdings, Dannon, Fage, General Mills, Agri-Mark, Wallaby, BSA SA, Brown Cow Yogurt, YoCrunch Natural, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yogurt Dip Market Trends and Innovations
Formulation science and packaging engineering are converging to extend shelf life without synthetic preservatives, while regulatory scrutiny of live culture claims intensifies across major markets. These forces are compressing traditional competitive advantages rooted in scale alone.
High-pressure processing technology is migrating from juice applications into cultured dairy, enabling manufacturers to achieve extended refrigerated shelf life while maintaining live and active culture counts. Mid-size regional brands in the United States are piloting HPP lines at contract facilities to bypass capital-intensive in-house installation. This technology is compressing the shelf-life gap between national brands with superior distribution and smaller players seeking retail expansion.
EFSA's evolving stance on probiotic health claims is forcing reformulation documentation and substantiation investments that favor larger R&D budgets. The industrial consequence is a bifurcation between products carrying qualified health claims and those repositioning as simple cultured condiments. Mediterranean-style Greek yogurt dips face the heaviest compliance burden given their historical reliance on live culture marketing.
Buyers in the United States are consolidating procurement around suppliers offering dual retail and foodservice certifications, reducing vendor counts by thirty to fifty percent in conventional grocery. Distributor private-label programs are displacing fragmented regional brands in the refrigerated case. This concentration is most visible in the Northeast and Mid-Atlantic metropolitan corridors where retail consolidation has advanced furthest.
Yogurt Dip Market Segmentation
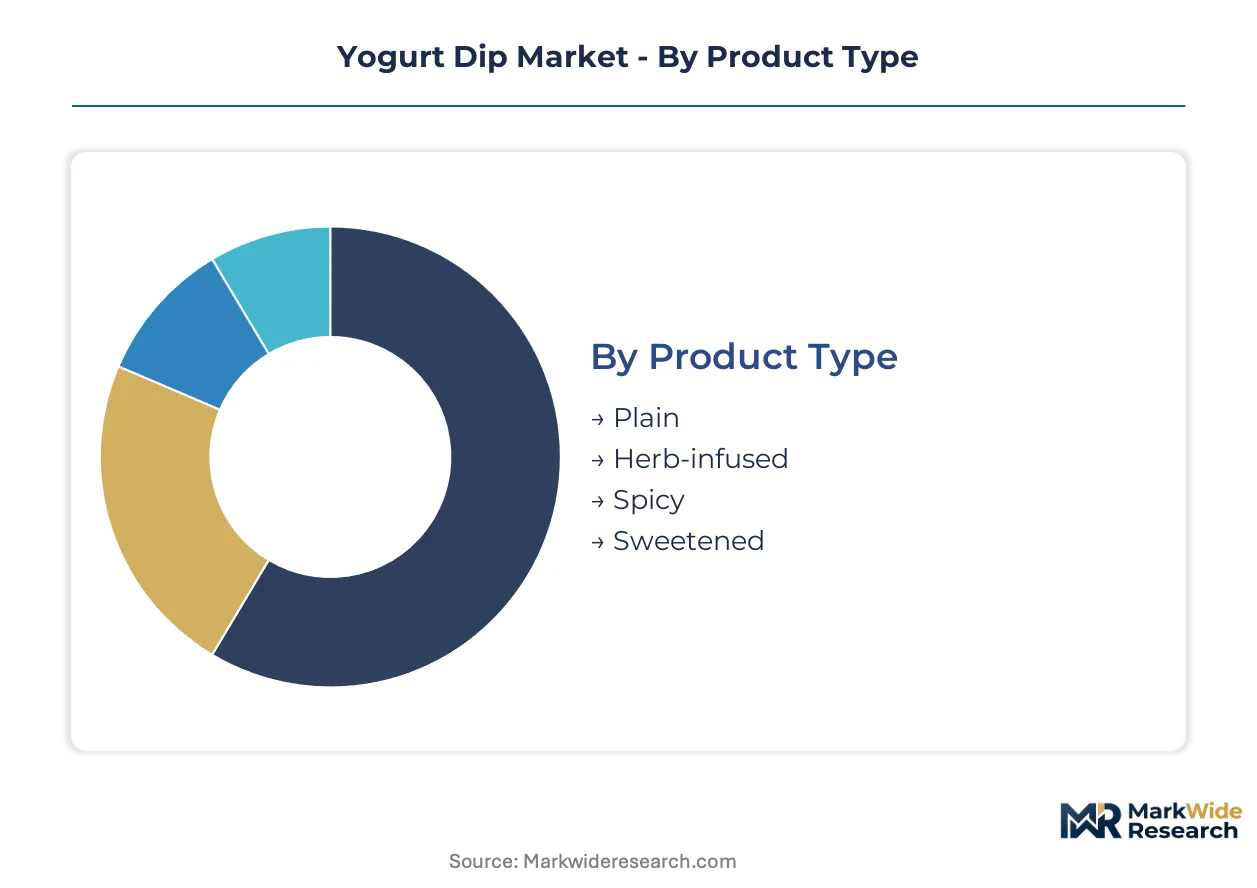
Yogurt dip segmentation reflects divergent margin structures across flavor complexity and packaging formats. Manufacturers prioritize segments offering shelf-space premiums or foodservice volume stability.
Product Type:
Mature plain formulations coexist with emerging premium flavor architectures across retail and foodservice channels.
- Plain:Unflavored cultured dairy base with live bacterial cultures serves as recipe ingredient and neutral dipping option. Demand concentrates in United States foodservice bulk procurement, constrained by commodity milk cost pass-through limitations.
- Herb-infused:Mediterranean herb blends including dill, mint, and za'atar create premium positioning through ingredient complexity. United States specialty retail channels reward these formulations with refrigerated case positioning and price premiums.
- Spicy:Chili and pepper-based heat profiles target younger demographic cohorts in convenience retail.
- Sweetened:Honey and fruit-infused variants compete with dessert spreads in conventional grocery breakfast aisles.
Plain retains volume leadership; herb-infused holds the steepest expansion curve.
Packaging Type:
Cost tier differentiation separates convenience premiums from foodservice economy formats.
- Single Serve:Portion-controlled cups and tubs target workplace snacking and on-the-go consumption. United States metropolitan corridors drive demand through convenience store and grab-and-go retail placement.
- Family Pack:Multi-serving containers balance per-ounce value with refrigerated shelf-life constraints. United States suburban household procurement favors this format for weekly grocery cycles.
- Bulk Container:Foodservice pails and tubs supply restaurants and catering operations with compressed per-unit margins.
- Tube:Squeeze formats enable controlled dispensing for food trucks and mobile foodservice applications.
Family Pack retains volume leadership; Single Serve is expanding most quickly.
End User:
Application-based segmentation reveals divergent stability profiles between recurring household purchase and event-driven foodservice demand.
- Households:Repeat retail purchase patterns generate predictable offtake through conventional grocery and online channels. United States dual-income households drive premium positioning acceptance.
- Restaurants:Quick-service and fast-casual operators embed yogurt dips in permanent and limited-time menu rotations. United States chain procurement consolidates around suppliers with dual retail-foodservice certifications.
- Catering Services:Event-volume spikes create demand for bulk formats with extended refrigerated holding requirements.
- Food Trucks:Mobile operators prioritize shelf-stable tube formats and portion-controlled packaging for operational efficiency.
Households retain volume leadership; Restaurants hold the steepest expansion curve.
Distribution Channel:
Geography of purchase separates consolidated retail from fragmented specialty access patterns.
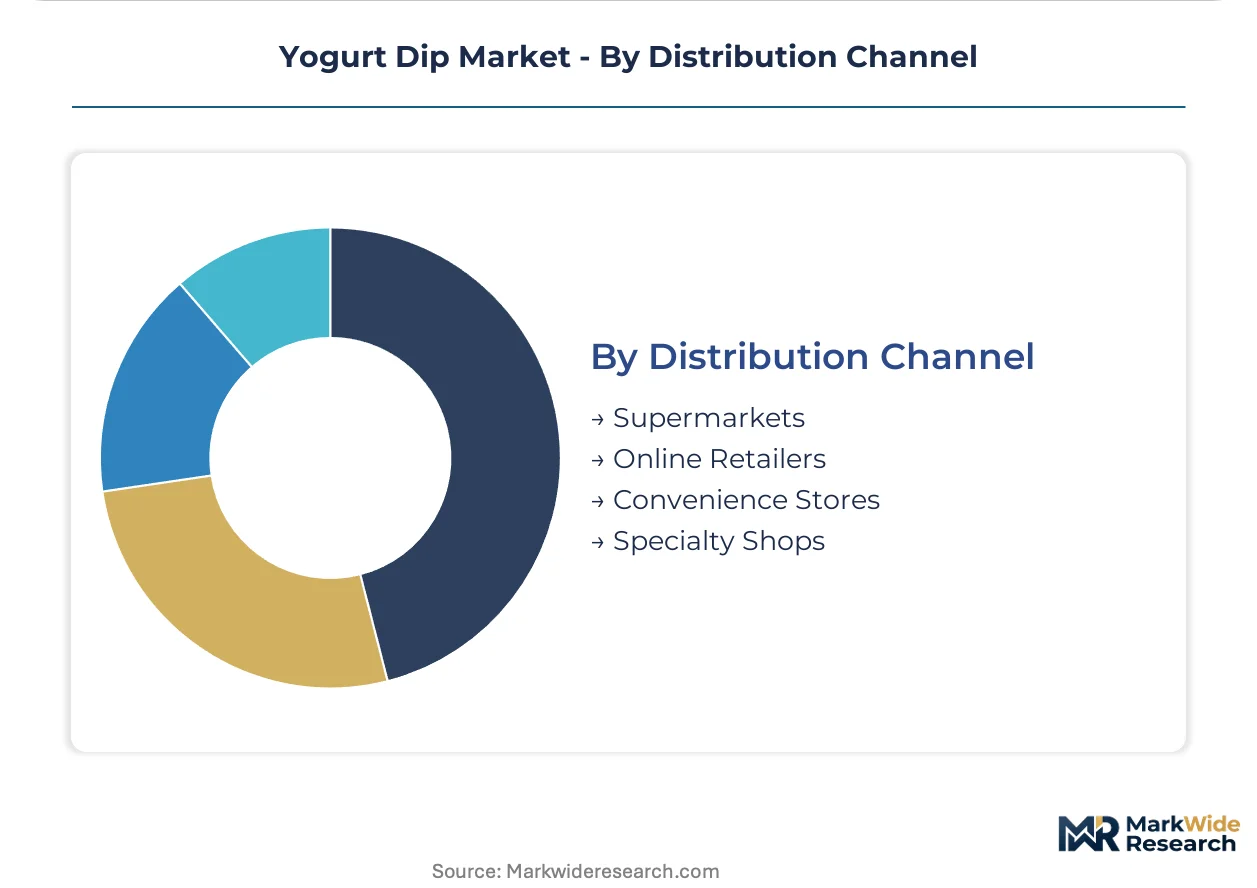
- Supermarkets:Conventional grocery refrigerated cases command slotting fee investments and category management compliance. United States Northeast and Mid-Atlantic metropolitan corridors exhibit highest retail consolidation.
- Online Retailers:Direct-to-consumer and third-party platform sales enable subscription models and flavor variety packs. Cold-chain shipping requirements limit regional expansion for smaller brands.
- Convenience Stores:Grab-and-go placement prioritizes single-serve formats with extended shelf-life engineering.
- Specialty Shops:Mediterranean and Middle Eastern grocers anchor ethnic flavor variant distribution with authentic positioning.
Supermarkets retain volume leadership; Online Retailers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA identity standards and USDA Grade A plant inspections anchor the United States as the dominant geography, while EFSA allergen mandates and Australia's export-grade fermentation infrastructure reshape competitive access patterns across major demand centers.
United States
Quick-service menu expansion and premium refrigerated shelf-space allocation drive demand concentration. FDA yogurt identity standards and USDA dairy plant inspections govern production compliance. Northeast and Mid-Atlantic metropolitan corridors exhibit the highest retail consolidation, with distributor private-label programs displacing fragmented regional brands.
Germany
Clean-label reformulation investments and Mediterranean-style flavor imports sustain procurement growth. EFSA pathogen limits and additive authorizations shape export compliance burdens for incoming suppliers. Bavaria and Baden-Württemberg host the densest refrigerated dairy processing clusters, where mid-size brands pilot high-pressure processing lines.
Australia
Export-grade cultured dairy output and Asia-Pacific sourcing relationships are expanding fermentation capacity. The country's national dairy regulator enforces strict quality assurance protocols for international shipment eligibility. Victoria and New South Wales processing corridors are lowering unit costs for regional buyers seeking alternative supply origins.
United Kingdom
Ethnic grocery channel expansion and flexitarian household penetration support specialty variant demand. EFSA-aligned national regulations enforce allergen disclosure thresholds that accelerate label simplification. London and Southeast England concentrate retail buying power, with metropolitan procurement consolidating around dual-certified suppliers.
Canada
Cross-border retail integration and foodservice chain standardization create pull-through for US-compatible formulations. Health Canada and the Canadian Food Inspection Agency govern dairy processing standards and interprovincial trade compliance. Ontario and Quebec host the primary cultured dairy manufacturing footprint, with Quebec's fermentation expertise supporting premium positioning.
Yogurt Dip Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where fermentation science expertise and cold-chain distribution depth rarely overlap. National dairy conglomerates with backward-integrated milk supply compete against specialty brands anchored in authentic regional formulations. Two strategic archetypes dominate: integrated milk-to-retail operators leveraging captive raw material access, and heritage-focused specialists commanding price premiums through provenance positioning. Competitive moves concentrate on co-packing contract acquisitions for foodservice volume stability and clean-label certification investments for retail shelf-space premiums.
Within the integrated tier, Chobani Global Holdings and General Mills exemplify scale-driven positioning through broad distribution reach and multi-brand portfolio depth. Fage occupies a heritage-specialist position, with thick-strained Greek yogurt formulations anchoring Mediterranean-style dip positioning in premium channels. These three named entities represent the dominant competitive archetypes without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Chobani Global Holdings |
| Dannon |
| Fage |
| General Mills |
| Agri-Mark |
| Wallaby |
| BSA SA |
| Brown Cow Yogurt |
| YoCrunch Natural |
| Others |
Pricing and Supply Chain Analysis
Interstate refrigerated freight corridors connecting California's Central Valley to Northeast metropolitan distribution hubs transmit cost volatility that both concentrates supply among backward-integrated operators and fragments price tiers across retail channels. Cold-chain logistics expenses cascade through bulk milk procurement, fermentation processing, and final-mile delivery to create three distinct pricing strata that separate national brands from regional competitors and private-label alternatives.
Pricing Analysis
Price spreads between United States coastal metropolitan markets and interior regions reach double-digit percentage gaps driven by cold-chain delivery differentials and slotting fee structures. Three-tier pricing structure across premium, standard, and economy levels separates herb-infused Mediterranean formulations with live culture certifications from conventional plain bases and distributor private-label alternatives. Pricing pressure stems from dairy commodity input swings that compress margins for non-integrated manufacturers lacking captive milk supply. Foodservice buyers exhibit highest price sensitivity due to volume procurement and menu cost constraints, while specialty retail channels absorb premium positioning with lower elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with dairy co-packers in Wisconsin, New York, and California that hold USDA Grade A certifications and multi-brand fermentation capacity. Fresh milk supply draws from Great Lakes and Northeast dairy cooperative networks, while herb and spice inputs source from Mediterranean and Middle Eastern trade corridors. Single-source vulnerability concentrates in live bacterial culture supply dominated by two domestic fermentation technology providers. Distribution runs through refrigerated third-party logistics networks anchored in Chicago, Dallas, and Atlanta hub facilities that limit national reach for unintegrated regional brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive access as foodservice procurement portals and retail category management systems consolidate vendor selection around dual-certified suppliers with integrated data interchange capabilities.
For Market Incumbents: Build switching-cost moats through embedded foodservice menu integration and proprietary live culture strain libraries that lock in quick-service chain relationships. Plant-based substitution from cashew and oat alternatives threatens volume retention in flexitarian households. Capacity addition in Australia's export-grade fermentation corridors offers geographic diversification against domestic milk cost volatility. For New Entrants and Emerging Players: Build out white-space positioning in single-serve convenience formats for workplace and mobile consumption channels that national brands underserve with legacy family-pack architectures. Online retailer subscription models present the most penetrable go-to-market angle, bypassing slotting fee barriers through direct-to-consumer cold-chain fulfillment partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from dairy conglomerate non-core dip divisions lacking fermentation science depth or clean-label certification infrastructure. Long-term viability hinges on live culture management expertise and phage control capabilities that concentrate among limited technical talent pools. Watch for consolidation signals when mid-size regional brands pilot high-pressure processing lines at contract facilities to bypass capital-intensive in-house installation.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | EFSA-aligned allergen disclosure compliance unlocks retail shelf-space premiums in European Union markets. |
| Foodservice Co-Packing Expansion | USDA Grade A contract manufacturing agreements with quick-service chains reduce slotting fee exposure and stabilize volume. |
| Single-Serve Packaging Innovation | Portion-controlled formats capture workplace snacking demand in United States metropolitan convenience channels. |
| High-Pressure Processing Adoption | HPP technology migration from juice applications extends refrigerated shelf life without synthetic preservatives. |
| Mediterranean Flavor Portfolio Extension | Herb-infused za'atar and dill variants command pricing power in specialty retail with authentic positioning. |
Research Methodology
A spread of perspectives from dairy processing plant managers, quick-service chain procurement directors, refrigerated logistics operators, and retail category buyers converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with fermentation technologists and cold-chain distribution specialists against secondary validation from USDA dairy plant inspection records, FDA yogurt identity standard filings, Nielsen retail audit data, and customs trade documentation. Bottom-up volume builds across packaging formats and flavor tiers triangulated with top-down market sizing from dairy industry cooperative reports.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions spanning product type, packaging format, end-user application, and distribution channel. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated live culture preservation technology diffusion rates, clean-label certification timeline compression, and foodservice menu embedding velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plant-based alternative manufacturers or rapid high-pressure processing capital deployment by mid-size regional brands would shift outcomes from baseline trajectories. Quarterly review of dairy commodity price indices, refrigerated logistics capacity utilization, and EFSA probiotic claim enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Fermented Foods Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
Tomato Puree Market
Processed Foods
Low Moisture Food Market
Processed Foods
Margarine Market
Processed Foods
Spray Cheese Market
Processed Foods
Europe Processed Egg Market
Processed Foods
United States Ice Cream Market
Processed Foods
Europe Egg Powder Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
North America Soup Market
Processed Foods
Processed Superfruits Market
Processed Foods
Porridge Market
Processed Foods
Processed Eucheuma Seaweed Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Mashed Potatoes Market