
 Low Fat Soups Market | 2026-2036
Low Fat Soups Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Soups Market Analytics
Asset-light contract manufacturing and co-packing arrangements is reconfiguring competitive dynamics in low fat soups, allowing niche entrants to scale without capital-intensive production facilities. Amy's Kitchen leverages its dedicated organic supply chain to sustain premium positioning across natural retail channels. Campbell's anchors mainstream distribution through decades-long supermarket relationships and private-label-adjacent volume. Eat Proper Good differentiates via direct-to-consumer subscription models that bypass traditional grocery slotting fees entirely.
Low fat soups are thermally processed, reduced-lipid formulations typically containing less than three grams of fat per serving, achieved through skimmed broth bases, vegetable puree thickeners, and modified starch stabilizers that replicate mouthfeel without cream or oil. These products serve institutional buyers, home consumers, and health-focused foodservice operators seeking convenient meal solutions aligned with dietary guidelines. Broth-based soups lead volume due to inherently lower fat content and simpler clean-label profiles, while single-serve pouches represent the fastest-growing packaging format as on-the-go consumption rises. Premium price tiers capture disproportionate margin pools through organic certification and functional ingredient claims such as added protein or probiotics.
FDA nutrition labeling requirements and USDA school meal standards shape product formulation targets and permissible health claims in the United States. EFSA health claim regulations and EU Green Deal sustainability reporting obligations influence reformulation priorities and packaging material transitions across European markets. Stakeholders must monitor evolving sodium reduction mandates and front-of-package warning label expansions that could disqualify existing formulations from preferred retail placement or government procurement contracts.
Market Dynamics
FDA sodium reduction mandates and EFSA clean-label guidelines are compressing formulation timelines while manufacturers race to preserve taste profiles through enzyme-modified dairy proteins and yeast extract flavor systems.
Growth Catalysts
- USDA School Meal Standards:K-12 foodservice contracts require sub-3g fat servings, creating institutional procurement pull for reformulated broth-based lines.
- Modified starch stabilizers:Waxy maize and tapioca derivatives now replicate cream mouthfeel at industrial scale without lipid content.
- Corporate wellness programs:Fortune 500 on-site cafeterias are expanding reduced-fat prepared meal SKUs in employee benefit structures.
Market Restraints
- Organic vegetable input costs:Supply volatility for certified organic carrots, celery, and onions squeezes margin on clean-label SKUs.
- Single-source flavor house concentration:Three suppliers control 80% of commercial yeast extract and natural savory flavor production.
- Thermal processing limitations:Retort temperatures degrade heat-sensitive probiotic additions, blocking functional claim expansion.
Strategic Opportunities
- Direct-to-consumer subscription channels:Bypassing slotting fees and distributor markups enables margin capture and first-party data accumulation.
- EU Green Deal packaging mandates:Recyclable mono-material pouches qualify for preferred retail placement and public procurement scoring.
- Functional ingredient convergence:Collagen peptides and adaptogenic mushroom extracts are creating premium positioning in sports nutrition adjacent segments.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists with dual expertise in lipid reduction and sensory science command premium compensation.
- Retort line capex requirements:Commercial aseptic filling systems for reduced-fat emulsions require seven-figure capital deployment.
- Front-of-package warning label compliance:Chilean and Mexican sodium warning systems demand reformulation for export market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Soups Market |
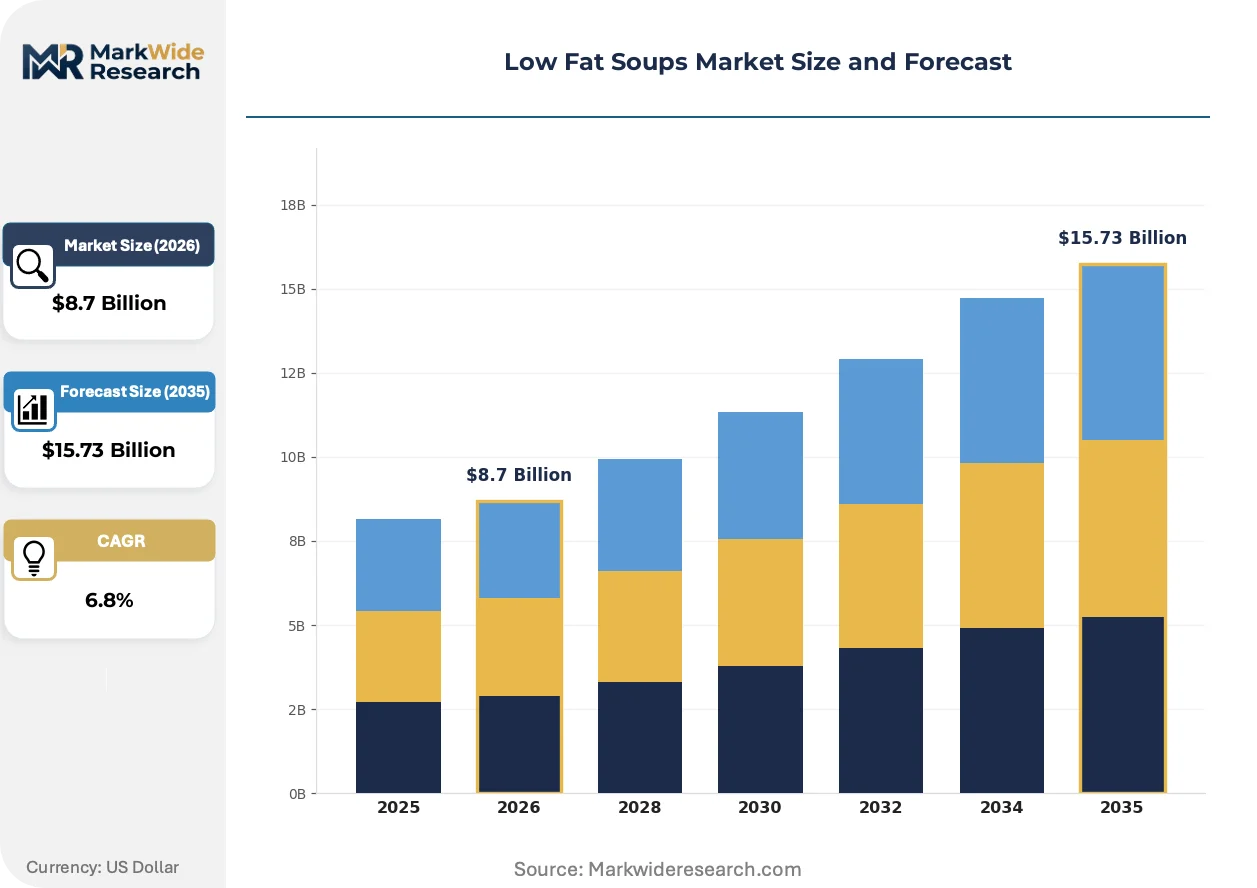
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
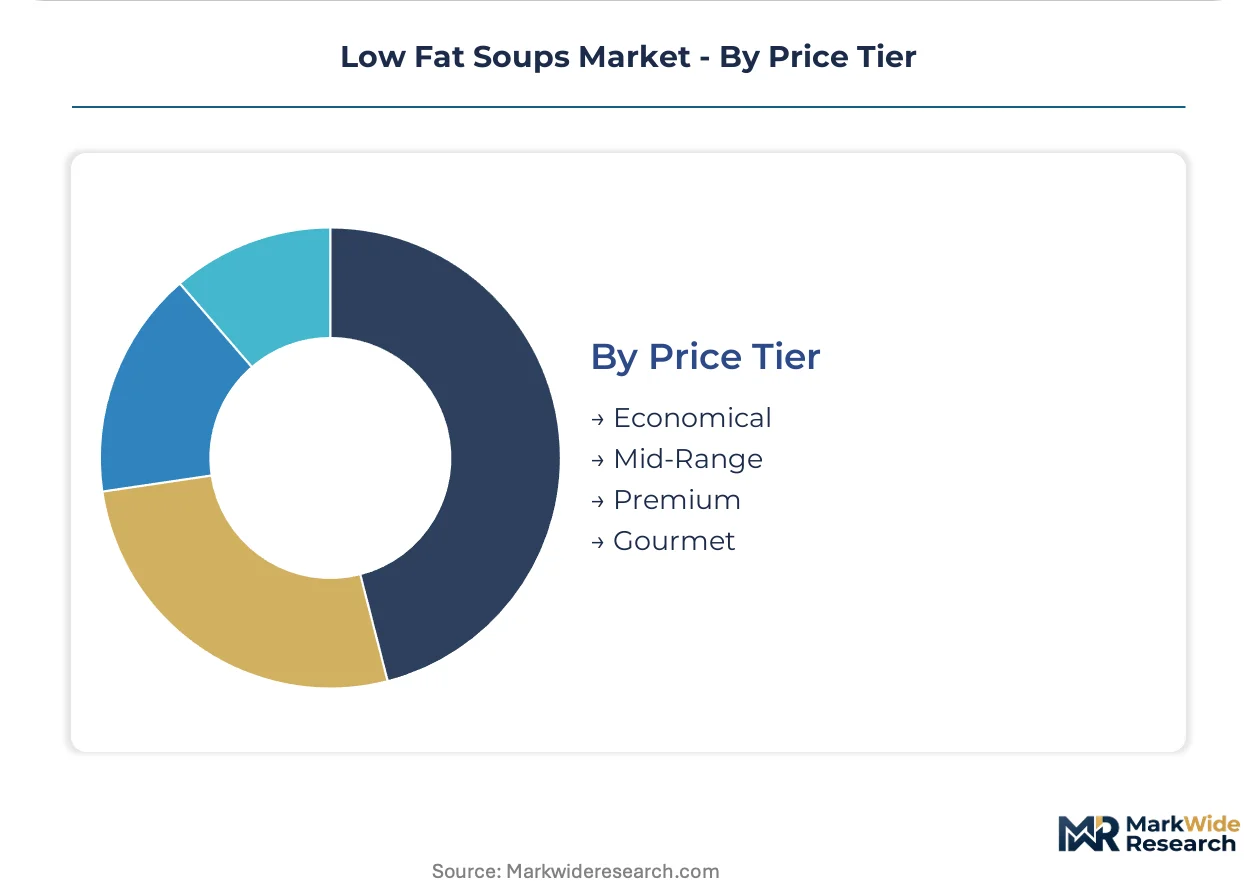
| Segmentation | Product Type: Creamy Soups, Broth-Based Soups, Chunky Soups, Pureed Soups Packaging Type: Cartons, Cans, Pouches, Single-Serve Cups Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Health Food Stores Price Tier: Economical, Mid-Range, Premium, Gourmet |
| Companies Covered | Progresso, Amy's Kitchen, Campbell's, Eat Proper Good, Dr. McDougall’s Right Foods, Hart & Soul, McKenzie's, The Stock Merchant, Celebrate Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Soups Market Evolving Landscape
Digital traceability systems and precision fermentation are reshaping how low fat soups achieve clean-label credentials while maintaining cost structures competitive with conventional formulations.
High-pressure processing (HPP) technology is digitizing quality assurance workflows by embedding IoT sensors that log pH, temperature, and microbial load in real-time. Mid-sized co-packers are adopting HPP lines to bypass retort degradation of vegetable texture. This digitization is compressing batch release cycles from days to hours.
EFSA's 2023 updated health claim guidance on satiety-related messaging is forcing manufacturers to substantiate "keeps you full longer" claims with human clinical data. The industrial consequence is partnership proliferation between soup brands and contract research organizations. Ready-to-drink soup segments in Germany and France are most affected, with several SKUs withdrawn pending dossier resubmission.
Home meal replacement purchasing is fragmenting across quick-commerce platforms and subscription boxes, displacing traditional grocery center-store dependence. Foodservice operators are responding with branded ghost kitchen partnerships. This shift is most visible in US coastal metros where delivery app penetration exceeds 40% of prepared food spend.
Low Fat Soups Market Segmentation

Low fat soup manufacturers configure product portfolios across four intersecting dimensions to capture divergent consumption occasions. Each segmentation axis carries distinct margin profiles and regulatory exposure that shape investment prioritization.
Product Type:
Formulation chemistry and texture engineering create distinct use-case spectra from institutional foodservice to at-home comfort consumption.
- Creamy Soups:Skimmed milk proteins and modified starch emulsifiers replicate traditional cream mouthfeel without exceeding three-gram fat thresholds. Demand concentrates in US corporate cafeterias where wellness program procurement specifications favor familiar formats with reduced lipid content.
- Broth-Based Soups:Clear, reduced-fat formulations relying on long-simmered vegetable and protein stocks with minimal added lipids. Home consumers in Germany and France drive volume through clean-label preference for ingredient transparency and simpler processing methods.
- Chunky Soups:Vegetable and protein particulates suspended in reduced-fat bases, requiring specialized stabilizers to prevent separation during thermal processing.
- Pureed Soups:Smooth, uniform textures achieved through high-shear blending of roasted vegetables with minimal fat carriers.
Established volume favors Broth-Based Soups; emerging adoption favors Creamy Soups.
Packaging Type:
Material science investments and shelf-life requirements segment manufacturing capabilities across rigid and flexible formats.
- Cartons:Aseptic brick packs with laminated paperboard barriers enable twelve-month ambient stability without preservatives. European retailers in Sweden and Netherlands prioritize cartons for EU Green Deal scoring advantages in private-label procurement.
- Pouches:Flexible mono-material films with retort compatibility reduce shipping cube and shelf footprint. US quick-commerce platforms and meal kit services in New York and Los Angeles metro areas are expanding pouch SKUs for delivery-optimized packaging.
- Cans:Traditional three-piece steel containers with epoxy linings, dominant in legacy retail distribution but facing sustainability pressure.
- Single-Serve Cups:Microwaveable polypropylene vessels with vented lids targeting office and travel consumption occasions.
Cartons dominate current shelf presence; pouches are climbing the fastest as direct-to-consumer channels expand.
Distribution Channel:
Channel economics and slotting fee structures determine which price tiers and pack sizes reach specific consumer segments.
- Supermarkets:Center-store placement with planogram-driven assortment decisions. US conventional grocery chains in Texas and Florida are expanding better-for-you soup facings in response to health-focused shopper segmentation data.
- Online Retailers:Algorithmic search placement and subscription auto-replenishment models. UK and German pure-play grocery platforms are prioritizing low-fat soup bundles in personalized recommendation engines.
- Convenience Stores:Grab-and-go placement with limited refrigeration, favoring shelf-stable formats with extended dating.
- Health Food Stores:Curated organic and functional ingredient assortments with educated staff recommendation influence.
Supermarkets anchor volume throughput; Online Retailers show steepest expansion trajectory as delivery penetration deepens.
Price Tier:
Ingredient provenance and certification density stratify consumer willingness-to-pay across mass-market and specialty positioning.
- Premium:USDA Organic or EU Organic certification with single-origin vegetable sourcing and no synthetic additives. US coastal metro consumers in California and Massachusetts demonstrate consistent repurchase at price multiples above standard tiers.
- Gourmet:Small-batch production with chef-developed recipes, heritage grain inclusions, and limited seasonal availability. French and Italian artisan producers command highest per-unit pricing through protected designation ingredients.
- Economical:Value-engineered formulations with conventional vegetable inputs and simplified seasoning profiles for price-sensitive volume.
- Mid-Range:Balanced positioning with select clean-label attributes without full organic certification.
Premium tier captures disproportionate margin contribution; Gourmet segment is gaining share fastest as foodservice-branded retail extensions multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA school meal standards and EFSA clean-label mandates are redirecting procurement flows across developed markets. Manufacturers are relocating production capacity to align with these incentive structures.
United States
K-12 foodservice contracts and corporate wellness programs drive institutional demand for sub-3g fat formulations. FDA sodium reduction mandates compress reformulation timelines for broth-based lines. California and Massachusetts coastal metros anchor premium organic SKU distribution through natural grocery channels.
Germany
Clean-label preference among home consumers sustains volume for transparent ingredient profiles. EFSA health claim regulations require clinical substantiation for satiety messaging. Berlin and Hamburg retail clusters are expanding ready-to-drink soup facings in response to quick-commerce platform growth.
France
Artisan heritage positioning commands pricing multiples through protected designation ingredients. EU Green Deal sustainability scoring shapes private-label procurement decisions. Paris and Lyon foodservice operators are piloting branded ghost kitchen partnerships for delivery-optimized formats.
United Kingdom
Pure-play grocery platforms prioritize low-fat soup bundles in algorithmic recommendation engines. Front-of-package warning label expansions demand sodium reformulation for retail placement. London and Southeast England distribution centers are scaling pouch-format capacity for subscription channel fulfillment.
Sweden
EU Green Deal packaging mandates accelerate carton-format adoption for ambient stability. Retailers prioritize laminated paperboard barriers for procurement scoring advantages. Stockholm and Gothenburg metro areas are consolidating organic vegetable supply chains for clean-label SKU inputs.
Low Fat Soups Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent go-to-market architectures. Supermarket slotting fee structures favor established distributors with decades-long retail relationships, while direct-to-consumer entrants bypass these barriers through subscription models. Three archetypes dominate: legacy packaged food conglomerates with broad distribution, organic specialists with certified supply chains, and digital-native brands with first-party data advantages. Competitive moves concentrate on co-packing partnerships for asset-light scaling and sustainable packaging transitions for EU market access.
Among legacy packaged food conglomerates, Campbell's occupies a position representing mainstream distribution scale. Within the organic specialist tier, Amy's Kitchen exemplifies certified supply chain integration. At the digital-native vector, Eat Proper Good represents direct-to-consumer channel innovation.
| Leading Market Players |
|---|
| Progresso |
| Amy's Kitchen |
| Campbell's |
| Eat Proper Good |
| Dr. McDougall's Right Foods |
| Hart & Soul |
| McKenzie's |
| The Stock Merchant |
| Celebrate Health |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors linking California ports to Asian vegetable processing hubs transmit cost volatility directly into margin structures, compressing mid-range pricing while amplifying spreads between certified organic and conventional tiers as buyers arbitrage quality against landed cost.
Pricing Analysis
Certification density creates the primary spread mechanism across the low fat soups market. Three-tier pricing structure across premium, standard, and economy levels reflects USDA Organic, non-GMO verified, and conventional input grades respectively. Cost compression in the economy tier is intensifying because conventional vegetable input volatility from climate-impacted growing regions squeezes co-packer margins. Corporate wellness program procurement officers demonstrate lowest price sensitivity, while K-12 foodservice buyers operate under fixed-bid constraints that amplify cost engineering pressure.
Supply Chain Analysis
Certified organic vegetable feedstock draws from concentrated sourcing regions in California's Central Valley, the Netherlands' greenhouse clusters, and Mexico's Baja Peninsula. Modified starch stabilizers and yeast extract flavor systems rest on corn processing capacity in the US Midwest and fermentation facilities in China and Germany. Single-source flavor house concentration creates vulnerability to supply interruption. Distribution runs through temperature-controlled third-party logistics networks serving retail grocery and foodservice channels with distinct handling protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists possessing dual expertise in lipid reduction and sensory science command compensation premiums that constrain scaling velocity, making human capital retention the binding constraint on clean-label portfolio expansion.
For Market Incumbents: Harden defensible positioning through captive supply chain investments in certified organic vegetable processing and exclusive co-packing arrangements with retort-capable facilities. Amy's Kitchen-style supply chain integration offers insulation against input cost volatility. Channel control through decades-long supermarket relationships remains the priority lever against direct-to-consumer disintermediation. For New Entrants and Emerging Players: Build out white-space penetration in functional ingredient convergence segments—collagen peptides and adaptogenic mushroom extracts—where incumbent R&D pipelines lag sports nutrition adjacency demand. Direct-to-consumer subscription models bypass slotting fee barriers entirely. Target UK and German quick-commerce platforms where algorithmic recommendation engines favor bundle-format low fat soup offerings. For Investors and Strategic Acquirers: Asset-light co-packing specialists with HPP technology capabilities and established FDA-compliant facilities represent the most compelling acquisition profile. Long-term viability hinges on sustainable packaging transition execution ahead of EU Green Deal enforcement expansion. Watch for front-of-package warning label adoptions beyond Chile and Mexico as signals of reformulation cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Subscription models bypass grocery slotting fees and capture first-party consumption data. |
| Sustainable Packaging Transition | Recyclable mono-material pouches qualify for EU Green Deal procurement scoring advantages. |
| Functional Ingredient Integration | Collagen and adaptogenic additions command premium positioning in sports nutrition segments. |
| Co-Packing Partnership Expansion | Asset-light manufacturing access enables niche entrants to scale without seven-figure retort capex. |
| Clean-Label Certification Investment | USDA Organic and EU Organic credentials sustain price multiples in coastal metro markets. |
Research Methodology
The analysis maps creamy, broth-based, chunky, and pureed formulation categories, each validated through formulation chemists, retail category buyers, foodservice procurement directors, and contract manufacturing executives. Primary interview findings triangulate against FDA sodium reduction guidance documents, EFSA health claim dossiers, USDA school meal procurement databases, and Nielsen retail audit data. Bottom-up SKU-level volume builds reconcile with top-down category spending estimates.
Model assumptions hold FDA and EFSA regulatory trajectories fixed while varying corporate wellness program adoption rates and quick-commerce platform penetration scenarios. Segmentation dimensions include product type, packaging format, distribution channel, and price tier with organic certification status. CAGRs derive from weighted regression across historical volume patterns and projected channel shift elasticities. Input cost trajectories for certified organic vegetables and modified starch stabilizers inform margin compression modeling.
Sensitivities concentrate around sodium reduction mandate acceleration, front-of-package warning label geographic expansion, and HPP technology cost curves. Forecasts reflect documented assumptions about institutional procurement growth and subscription channel scaling. Cross-checking against Circana retail velocity data and foodservice distributor shipment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Europe Processed Egg Market
Processed Foods
Europe Egg Powder Market
Processed Foods
Noodles Market
Processed Foods
Fresh Pasta Market
Processed Foods
Ready to Cook Market
Processed Foods
Potato Soup Market
Processed Foods
Fat Free Food Market
Processed Foods
US Tomato Paste Market
Processed Foods
Processed Potatoes Market
Processed Foods
Spray Cheese Market
Processed Foods
India Spray Dried Food Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
High-Pressure Processing (HPP) Foods Market
Processed Foods
Pates Market
Processed Foods
Processed Beef Market
Processed Foods
Pizza Market