
 Global Organic Soup Market | 2026-2036
Global Organic Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Soup Market Foresight
Clean-label processing is tilting supply chains toward shorter ingredient decks and thermal preservation methods that maintain nutritional claims without synthetic additives. Amy's Kitchen leverages its dedicated organic manufacturing infrastructure to sustain batch consistency across a broad SKU range. Campbell Soup Company anchors conventional retail distribution while competing through dedicated organic sub-brands. Pacific Foods differentiates via aseptic carton packaging that extends shelf stability without refrigeration.
Organic soup comprises prepared food products formulated from certified organic agricultural inputs, processed under thermal or dehydration methods that yield shelf-stable or refrigerated ready-to-serve matrices with mandated residue thresholds. The category serves commercial and residential end-users seeking convenience aligned with organic certification integrity. Canned soup occupies the dominant volume position due to established supply chains and consumer familiarity, though chilled soup captures expanding margin pools through premium positioning in urban retail. Dry soup competes on storage efficiency and shipping economics, while Tetra Pack formats gain traction as retailers optimize shelf-space productivity against glass jar alternatives.
USDA Organic certification governs raw material sourcing and handling protocols for products entering the United States, while the EU Organic Regulation enforces equivalent standards across European Economic Area markets. FDA labeling requirements intersect with organic claims to shape permissible health-related marketing. The National Organic Program maintains the integrity of the seal that controls consumer trust and price realization. Stakeholders must monitor evolving definitions of organic processing aids as certifiers tighten interpretations around incidental additives.
Market Dynamics
Clean-label thermal processing is compressing formulation cycles as certifiers tighten interpretations around incidental additives, forcing manufacturers to validate shorter ingredient decks without sacrificing shelf stability.
Growth Catalysts
- EU Organic Regulation alignment:Harmonized standards across European Economic Area markets reduce cross-border compliance duplication, accelerating SKU rationalization for multinational suppliers.
- Aseptic carton adoption:Extended ambient shelf stability without refrigeration opens convenience-store and foodservice channels previously closed to chilled formats.
- German discounter penetration:Deep certified organic SKU placement in Aldi and Lidl networks normalizes price accessibility for mass-market consumers.
Market Restraints
- Organic ingredient cost volatility:Certified vegetable and grain inputs trade at premiums to conventional commodities, compressing gross margins when harvest yields fluctuate.
- USDA National Organic Program audit density:Annual inspection requirements and residue testing protocols add fixed compliance overhead regardless of production scale.
- Glass jar displacement lag:Established retail shelving infrastructure and consumer familiarity slow Tetra Pack format substitution despite logistics advantages.
Strategic Opportunities
- Urban chilled soup corridors:Premium positioning in London, New York, and Tokyo convenience networks captures margin pools from time-constrained professionals.
- FDA-FTC health claim convergence:Clarified permissible marketing around nutritional integrity enables differentiated positioning against conventional processed alternatives.
- Direct-to-subscription channels:Monthly delivery models bypass slotting fee structures that disadvantage smaller organic labels in conventional grocery.
Industry Challenges
- Thermal process engineering talent scarcity:Expertise in clean-label preservation without synthetic stabilizers concentrates among legacy canning specialists.
- Multi-certification audit fatigue:Simultaneous USDA Organic, EU Organic, and private retailer standard compliance creates documentation redundancy.
- Legacy ERP integration friction:Batch traceability requirements for organic chain-of-custody strain aging manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Soup Market |
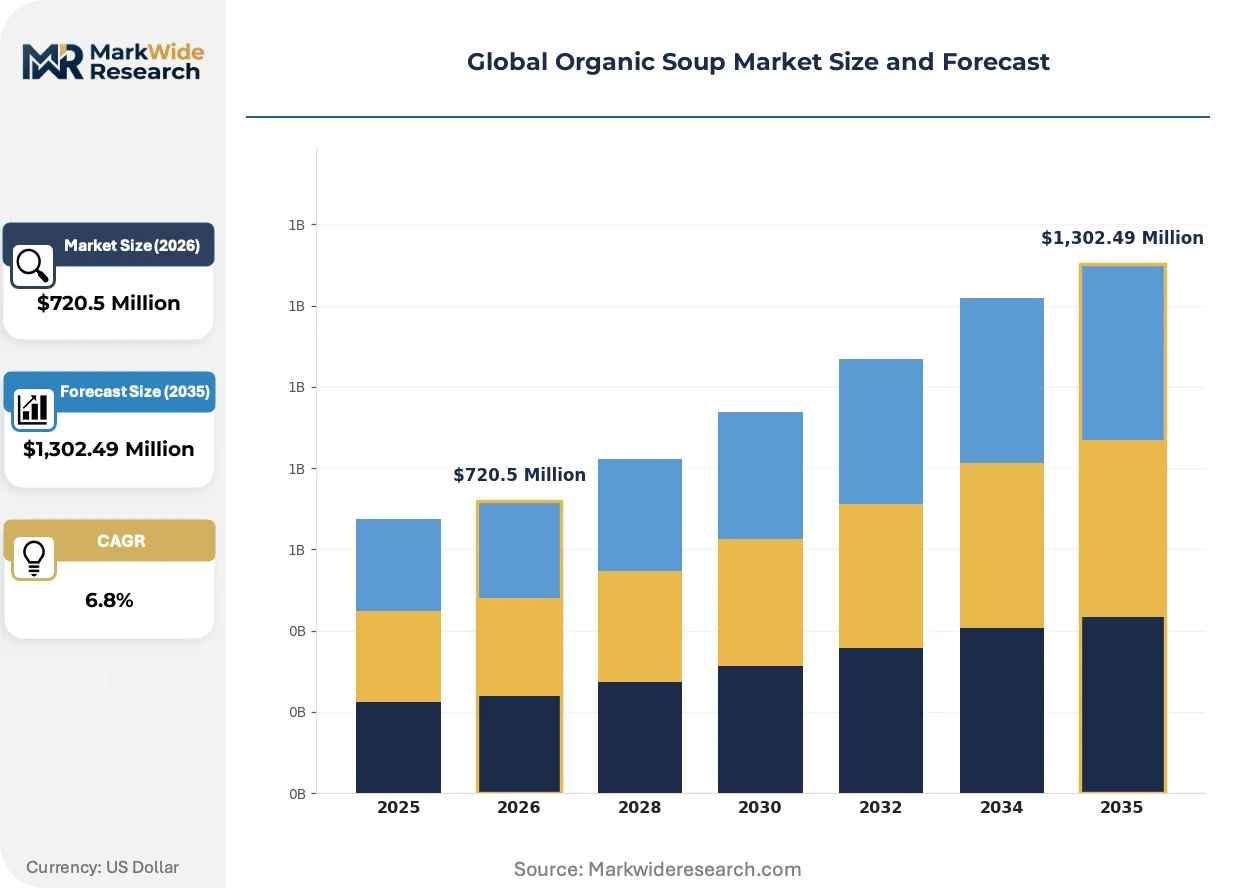
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,302.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Soup, Dry Soup, Chilled Soup, Ready-to-Eat Soup Ingredient Source: Vegetables, Legumes, Grains, Broths Packaging Type: Plastic Container, Glass Jar, Tetra Pack, Pouch Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Farmers' Markets |
| Companies Covered | Amy's Kitchen, Campbell Soup Company, Pacific Foods, The Hain Celestial Group, Health Valley Organic, Nestlé S.A., General Mills Inc., Kraft Heinz Company, Trader Joe's Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Soup Market Shifts & Advancements
Processing technology convergence is collapsing the traditional trade-off between shelf stability and ingredient simplicity, enabling new competitive positioning across ambient and chilled formats.
High-pressure processing is hybridizing with aseptic filling lines to deliver refrigerated soups with clean labels and extended codes. Premium urban retailers in the United States and United Kingdom are prioritizing these SKUs for prepared-foods sections. The technology is compressing the gap between canned convenience and fresh-perceived quality, forcing legacy thermal canners to accelerate equipment refresh cycles.
EU F-Gas Regulation phase-down mandates are accelerating refrigeration infrastructure replacement across European retail and foodservice. Operators face capital decisions between low-global-warming-potential systems and ambient-stable product formats. Chilled soup suppliers dependent on cold-chain integrity face distribution cost pressure, while Tetra Pack and retort pouch alternatives gain shelf-space reconsideration.
Buyer concentration among omnichannel grocery platforms is consolidating assortment decisions into fewer procurement teams. Independent organic brands face gatekeeper compression as Amazon Fresh, Instacart, and Carrefour's digital arms prioritize private-label and exclusive SKUs. Germany and France exhibit the most pronounced platform consolidation, with discounter digital integration accelerating share capture by vertically integrated suppliers.
Global Organic Soup Market Segmentation
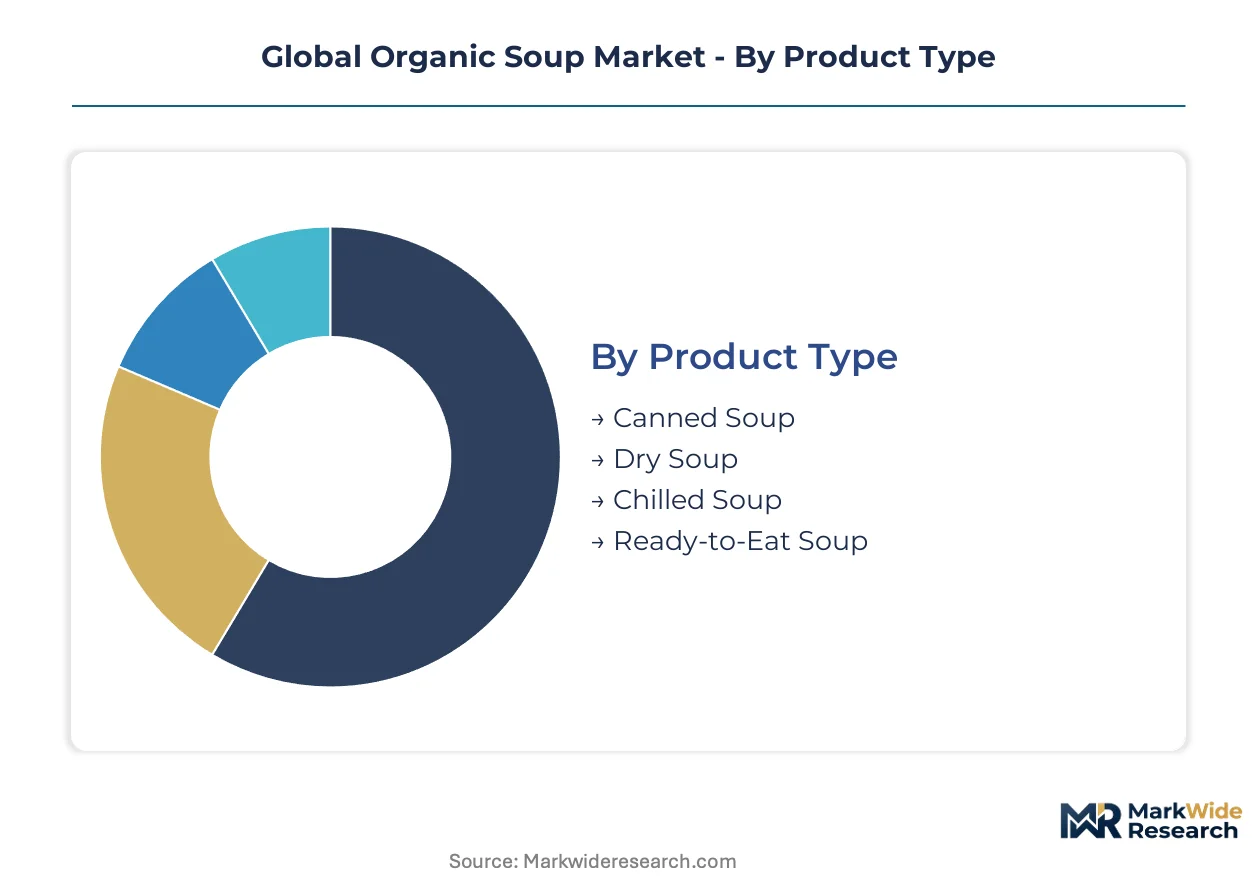
Organic soup segmentation reveals how format choices, ingredient sourcing, and channel access shape margin capture across consumer occasions. Each dimension carries distinct supply chain requirements and certification burdens that determine competitive viability.
Product Type:
Volume concentration across formats reflects thermal processing maturity and cold-chain infrastructure availability in target markets.
- Canned Soup:Metal-container preservation using retort sterilization delivers ambient stability without refrigeration dependency. German discounter networks and US conventional grocery channels anchor demand for this format due to established supply chains and price accessibility.
- Chilled Soup:High-pressure processing and aseptic filling extend refrigerated shelf life while preserving fresh-perceived quality. Urban convenience corridors in London, New York, and Tokyo drive premium positioning for time-constrained professionals seeking meal solutions.
- Dry Soup:Dehydrated matrices concentrate flavor through spray-drying or freeze-drying, optimizing shipping economics and pantry storage duration.
- Ready-to-Eat Soup:Shelf-stable or refrigerated single-serve formats target immediate consumption occasions in foodservice and grab-and-go retail.
Canned soup commands the established base. The steepest expansion runs through chilled soup.
Ingredient Source:
Certification requirements and harvest volatility concentrate procurement risk differently across agricultural input categories.
- Vegetables:Certified organic tomatoes, carrots, onions, and leafy greens constitute the primary volume input for puree-based and chunky formulations. California's Central Valley and Spain's Murcia region supply dominant shares of organic vegetable inputs for North American and European manufacturing.
- Broths:Slow-simmered bone or vegetable stocks deliver foundational flavor matrices that differentiate premium positioning. Clean-label positioning in UK and US markets drives demand for bone broths with declared collagen content and reduced sodium profiles.
- Legumes:Organic lentils, chickpeas, and beans provide protein fortification and texture variation in plant-forward formulations.
- Grains:Rice, quinoa, and ancient wheat varieties extend satiety and enable gluten-free or high-fiber nutritional claims.
Vegetable-based formulations command the established base. Broth-centric positioning captures the steepest margin expansion.
Packaging Type:
Material selection determines logistics economics, shelf-space productivity, and compatibility with thermal processing methods.
- Tetra Pack:Multi-layer aseptic cartons enable ambient distribution without refrigeration while optimizing cube efficiency versus cylindrical alternatives. EU F-Gas Regulation phase-down pressures are accelerating retailer reconsideration of this format against chilled glass.
- Pouch:Flexible retort or spouted stand-up formats reduce material weight and enable microwave heating convenience. Japanese convenience store channels and North American camping/outdoor segments favor this configuration for portability.
- Glass Jar:Premium perception and infinite recyclability sustain positioning in specialty retail, though breakage risk and shipping weight constrain mass-market penetration.
- Plastic Container:Polypropylene or PET tubs dominate chilled soup merchandising in UK and US supermarket prepared-foods sections.
Tetra Pack configurations command the established base. Pouch formats are climbing the fastest.
Distribution Channel:
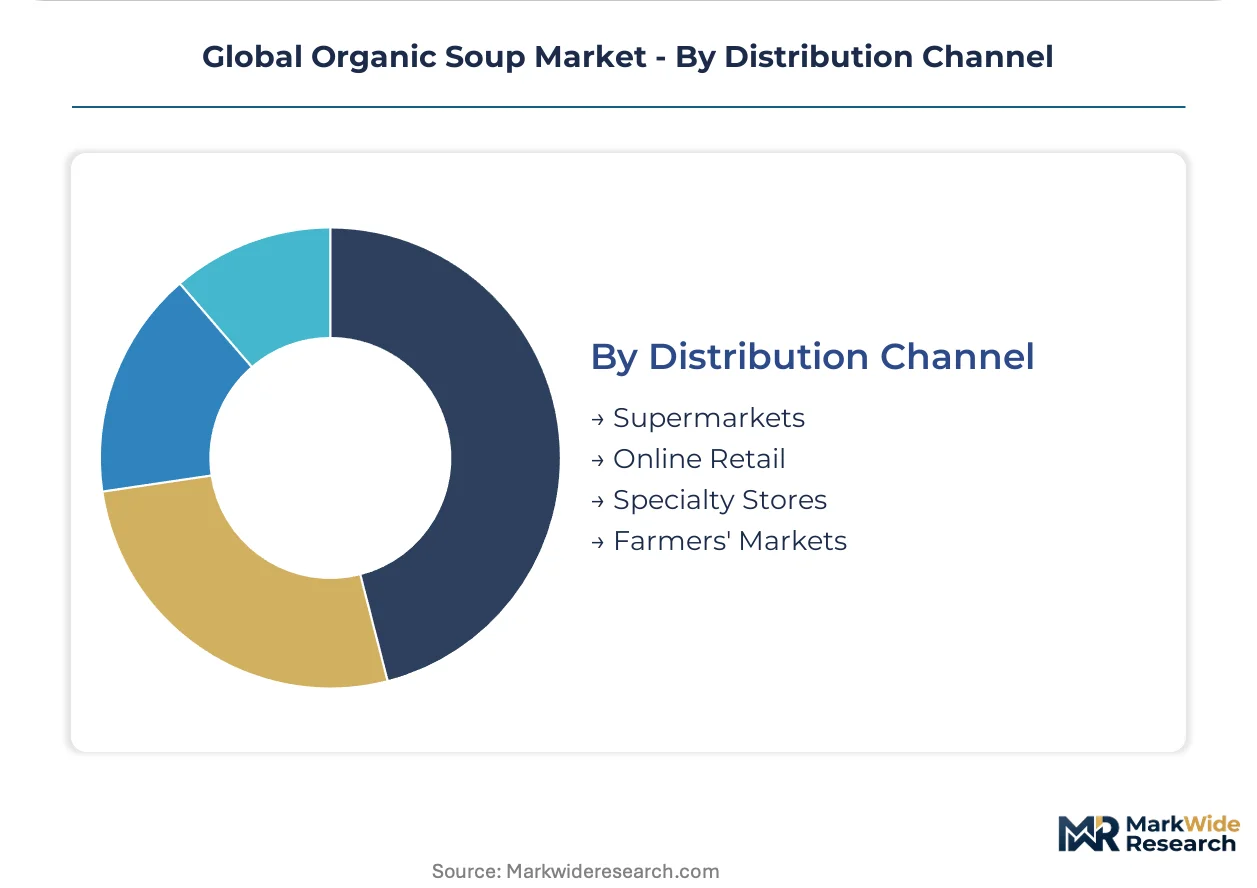
Channel selection determines margin structure, brand control, and exposure to private-label displacement pressures.
- Supermarkets:Conventional grocery chains and organic-focused banners provide dominant volume access through dedicated natural foods sections. Aldi and Lidl networks in Germany normalize price accessibility for certified organic SKUs through streamlined assortment and private-label integration.
- Online Retail:Amazon Fresh, Instacart, and direct-to-subscription models bypass slotting fee barriers facing smaller organic labels. Platform consolidation in France and Germany concentrates procurement decisions into fewer gatekeepers favoring vertically integrated suppliers.
- Specialty Stores:Independent natural foods retailers and co-ops sustain premium positioning for artisan and regional organic soup producers.
- Farmers' Markets:Direct producer-consumer interfaces enable batch-level traceability storytelling and immediate feedback on seasonal formulations.
Supermarket channels command the established base. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German organic soup exports flow into Netherlands and Belgian distribution hubs serving broader European retail networks. Cross-border trade corridors concentrate certified organic volumes through Rotterdam and Antwerp logistics clusters before final-mile delivery.
United States
USDA Organic certification drives procurement decisions for tomato and vegetable inputs from California's Central Valley. FDA labeling requirements intersect with organic claims to constrain permissible health-related marketing. Chicago and Dallas metropolitan areas anchor chilled soup distribution for time-constrained professional segments.
Germany
Aldi and Lidl discounter networks normalize price accessibility through deep certified organic SKU placement. EU Organic Regulation shapes formulation standards across domestic supply chains. Berlin and Munich urban corridors capture premium chilled soup demand from convenience-oriented consumers.
United Kingdom
Bone broth positioning with declared collagen content drives clean-label differentiation in London and Southeast retail. FSA enforcement of organic marketing claims tightens permissible nutritional assertions. Manchester and Birmingham distribution hubs consolidate ambient and chilled format warehousing.
Japan
Pouch format adoption concentrates in Tokyo and Osaka convenience store channels seeking portability. METI guidance on sustainable packaging influences retailer format selection. Nagoya industrial corridor hosts aseptic filling equipment serving domestic and export markets.
France
Carrefour digital platform consolidation concentrates procurement decisions for organic prepared foods. ANSM oversight of organic processing aids shapes permissible ingredient decks. Lyon and Marseille logistics clusters distribute Tetra Pack formats across Southern European markets.
Global Organic Soup Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. The vendor base fragments between vertically integrated food conglomerates and dedicated organic manufacturers with certified production infrastructure. Three archetypes dominate: discounter-aligned volume suppliers, premium chilled specialists, and private-label contract manufacturers. Competitive moves concentrate on aseptic packaging technology licensing and direct-to-subscription channel bypass of conventional grocery slotting fees.
Within the dedicated organic tier, Amy's Kitchen and Pacific Foods exemplify manufacturing-specialist positioning against diversified conglomerates. Campbell Soup Company occupies a position bridging conventional retail distribution with organic sub-brand development. These anchors represent divergent bets on thermal processing heritage versus clean-label format innovation.
| Leading Market Players |
|---|
| Amy's Kitchen |
| Campbell Soup Company |
| Pacific Foods |
| The Hain Celestial Group |
| Health Valley Organic |
| Nestlé S.A. |
| General Mills Inc. |
| Kraft Heinz Company |
| Trader Joe's Company |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down mandates compress refrigeration infrastructure economics across European retail networks, forcing simultaneous recalibration of chilled soup price premiums and accelerated format migration toward ambient-stable alternatives. This regulatory chokepoint widens pricing tier spreads between cold-chain-dependent and Tetra Pack formats while reshaping procurement geography toward Southern European aseptic filling clusters.
Pricing Analysis
Current-generation aseptic carton technology commands 15-25% shelf-price premiums over legacy canned formats, while next-generation high-pressure processing lines for chilled soup capture the steepest margin pools in urban convenience corridors. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and cold-chain dependency, with USDA Organic and EU Organic dual-certified SKUs anchoring the premium tier. Cost compression in economy-tier canned soup intensifies because German discounter networks normalize mass-market price accessibility. Foodservice buyers exhibit highest price sensitivity due to volume procurement leverage, while direct-to-subscription residential consumers accept premium positioning for batch-traceability storytelling.
Supply Chain Analysis
Export-control regimes on aseptic filling equipment limit technology transfer to emerging market manufacturers, concentrating advanced packaging capability among Italian, German, and Japanese equipment suppliers. Organic vegetable inputs draw from California's Central Valley, Spain's Murcia region, and Mexico's Baja California peninsula, with certified tomato and carrot harvest volatility transmitting directly to formulation cost structures. Single-source vulnerability concentrates in California drought exposure for organic tomato paste supply. Distribution runs through Rotterdam and Antwerp logistics clusters for European cross-border fulfillment, with Chicago and Dallas metropolitan areas anchoring North American chilled soup final-mile networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic soup penetration in convenience-store and foodservice channels remains underdeveloped relative to conventional retail, with aseptic carton format adoption creating early-cycle expansion runway for suppliers bypassing cold-chain infrastructure constraints.
For Market Incumbents: Build dedicated organic manufacturing moats through backward integration into certified vegetable procurement in California and Spain, insulating margin structures from commodity volatility. Amy's Kitchen and Pacific Foods demonstrate how captive aseptic filling infrastructure defends batch consistency across SKU proliferation. Capacity addition in Mexico's Baja California corridor reduces tariff exposure on organic tomato inputs. Certification investment in simultaneous USDA Organic and EU Organic compliance streamlines cross-border SKU rationalization against audit fatigue. For New Entrants and Emerging Players: Mid-market chilled soup corridors in Tokyo and Osaka convenience networks represent the most penetrable entry point, where pouch format portability commands premium positioning against established canner heritage. Direct-to-subscription monthly delivery models bypass slotting fee structures that disadvantage smaller labels in Amazon Fresh and Instacart gatekeeper environments. Foodservice white-space in European corporate catering channels offers volume offtake without retail shelf-space competition. For Investors and Strategic Acquirers: FDA-FTC health claim convergence around nutritional integrity marketing reshapes the acquisition landscape toward clean-label specialists with validated thermal process engineering talent. Long-term viability across the projection horizon favors vertically integrated suppliers with in-house aseptic packaging capability and certified organic agricultural sourcing. The signal to watch is EU Organic Regulation tightening on incidental additive interpretations, which would force equipment refresh cycles among legacy canners and create distressed acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Packaging Technology Licensing | Pacific Foods' carton expertise opens convenience-store channels previously closed to chilled formats. |
| Direct-to-Subscription Channel Launch | Monthly delivery models bypass Instacart slotting fees disadvantaging smaller organic labels. |
| Dual-Certification Compliance Investment | Simultaneous USDA Organic and EU Organic validation accelerates cross-border SKU rationalization. |
| High-Pressure Processing Line Deployment | Hybrid aseptic filling extends refrigerated codes for London and New York urban corridors. |
| Certified Organic Agricultural Integration | Backward control over California Central Valley tomato supply reduces harvest volatility exposure. |
Research Methodology
A spread of perspectives from brand managers at organic soup manufacturers, category buyers at Aldi and Lidl networks, supply planners at aseptic filling equipment vendors, and procurement leads at foodservice distributors converged on the working assumptions shaping this analysis. Primary interview intelligence combined with secondary validation from USDA National Organic Program audit records, EU Organic Regulation implementation guidance, Nielsen retail audit data for prepared foods sections, and customs trade data for organic vegetable inputs. Bottom-up SKU-level volume builds triangulated against top-down category spending estimates from grocery platform disclosures.
Demand-supply balance framing anchored the analytical approach across the analysis window, with segmentation modeled by product type, packaging format, distribution channel, and ingredient sourcing geography. CAGRs derived from fitted growth curves incorporating organic certification penetration rates, aseptic carton adoption velocities, and discounter private-label expansion trajectories. Forecast inputs included EU F-Gas Regulation implementation timelines affecting refrigeration infrastructure replacement and METI sustainable packaging guidance influencing Japanese retailer format selection.
Macroeconomic conditions sit as an overlay; deviation in organic commodity price indices, cross-border tariff regimes, or cold-chain energy costs would shift the trajectory. Forecasts reflect documented assumptions around certification standard stability and thermal processing technology diffusion rates. Material shifts in EU Organic Regulation additive interpretations or USDA National Organic Program audit density would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Organic Yeast Market
Organic Food and Beverages
Saudi Arabia Organic Food Market
Organic Food and Beverages
Australia Organic Food Market
Organic Food and Beverages
Organic Coconut Sugar Market
Organic Food and Beverages
Organic Rice Syrup Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Organic Coconut Syrup Market
Organic Food and Beverages
South Africa Organic Food Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
United States Organic Skin Care Market
Organic Food and Beverages
Japan Organic Food Market
Organic Food and Beverages
Organic Beverages Market
Organic Food and Beverages
Global Organic Coconut Water Market
Organic Food and Beverages
Organic Cocoa Market