
 Sugar-Free Ice Cream Market | 2026-2036
Sugar-Free Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar-Free Ice Cream Market Analysis
Retail buyer concentration is rebalancing as supermarket private labels and direct-to-consumer subscription channels fragment what once flowed through legacy CPG distributors. Unilever PLC leverages its freezer-case shelf-space agreements to sustain multinational reach across conventional grocers. Rebel Creamery LLC anchors the ultra-low-carb segment with erythritol-based formulations that dominate keto-aligned consumer tribes. Kroger Co. competes through its Simple Truth private-label line, which occupies premium endcap positioning in over two thousand stores.
Sugar-free ice cream denotes frozen dessert formulations containing no sucrose, typically employing sugar alcohols, high-intensity sweeteners, or fiber-based bulking agents to achieve comparable freezing-point depression and mouthfeel. Manufacturers achieve functional parity through controlled overrun rates between twenty and sixty percent, balancing aeration with the depressed freezing curves of polyol sweeteners. The ingredient-type dimension shows natural sweeteners leading volume growth as monk fruit and allulose displace legacy aspartame formulations, while dairy-based bases retain margin concentration despite faster expansion in milk-alternative variants. Distribution through online retail channels registers the fastest structural growth, though supermarkets still control the bulk of cold-chain fulfillment infrastructure.
The FDA governs added-sugar disclosure and nutrient-content claims, while the USDA administers organic certification standards that overlap with clean-label sweetener positioning. State-level cottage-food laws and interstate dairy compacts create fragmented compliance terrain for regional producers scaling beyond local markets. Stakeholders must monitor evolving WHO guidance on non-sugar sweeteners and pending EPA assessments of erythritol manufacturing byproducts to anticipate the next wave of formulation constraints and competitive repositioning.
Market Dynamics
Reformulation pressure from the FDA's updated Nutrition Facts labeling requirements for added sugars is compressing legacy aspartame portfolios while accelerating monk fruit and allulose adoption across North American manufacturing lines.
Growth Catalysts
- Diabetes-prevention dietary guidelines:The USDA's Dietary Guidelines for Americans now explicitly counsel reduced added-sugar intake, pulling ketogenic and pre-diabetic consumers toward erythritol-sweetened frozen desserts in retail grocery.
- Clean-label sweetener technology:Monk fruit extract and allulose production scale-up is lowering unit costs for natural high-intensity alternatives, eroding the cost gap with synthetic formulations.
- Direct-to-consumer subscription channels:Cold-chain logistics specialization is enabling keto-aligned brands to bypass conventional freezer-case slotting fees and capture lifetime value through recurring revenue.
Market Restraints
- Erythritol input cost volatility:Corn-derived feedstock prices fluctuate with biofuel policy shifts, squeezing margin on the category's dominant bulk sweetener.
- Freezing-point depression limitations:Polyol sweeteners depress freezing curves more aggressively than sucrose, requiring precise overrun control that constrains texture parity in artisanal-scale production.
- Interstate dairy compact fragmentation:State-level milk pricing orders create compliance friction for regional producers scaling beyond cottage-food law exemptions.
Strategic Opportunities
- Pediatric and school-food channels:USDA Smart Snacks in School standards create procurement pull for low-glycemic desserts in district foodservice, an underpenetrated institutional segment.
- Allulose-gravity fermentation advances:Enzymatic conversion efficiency gains are automating cost reduction for this rare sugar, opening formulation flexibility beyond erythritol's cooling aftertaste.
- Retail pharmacy cold-case placement:CVS Health and Walgreens Boots Alliance are expanding frozen food sections adjacent to diabetes care products, creating channel adjacency for therapeutic-positioned brands.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise in polyol-protein interactions and cryoprotectant systems concentrates with retiring dairy industry veterans, constraining R&D velocity for emerging brands.
- Organic certification timeline compression:USDA National Organic Program compliance for sweetener supply chains requires 36-month transition periods that mismatch venture-backed growth timelines.
- Cold-chain last-mile integration:DTC fulfillment demands dry-ice logistics capabilities that conflict with carrier sustainability pledges, forcing packaging reinvestment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar-Free Ice Cream Market |
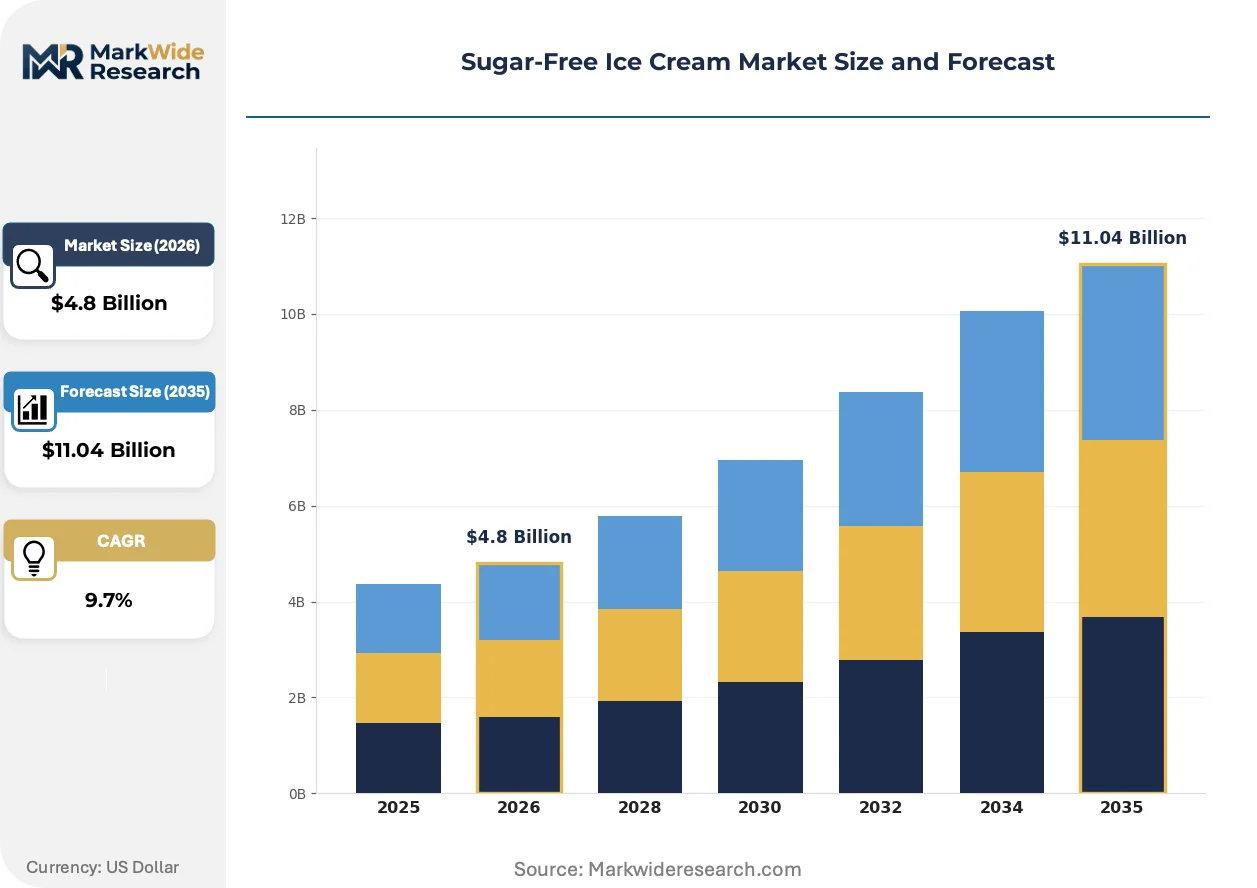
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Serve, Scoop, Sandwich, Bar Ingredient Type: Natural Sweeteners, Artificial Sweeteners, Milk Alternatives, Dairy Packaging Type: Cup, Tub, Cone, Multi-Packs Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops |
| Companies Covered | Arctic Zero Inc., Rebel Creamery LLC, Unilever PLC, Enlightened, Kroger Co., Nestle SA, Halo Top Creamery, So Delicious, Danone SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar-Free Ice Cream Market Emerging Trajectories
Precision fermentation and enzymatic bioprocessing are collapsing the cost curve for rare sugars while clean-label mandates restructure formulation hierarchies across conventional and alternative retail channels.
Continuous enzymatic conversion systems for allulose production are automating throughput scaling that previously required batch fermentation. Mid-sized manufacturers in the natural products sector are adopting these systems to reduce per-unit conversion costs. This automation is compressing the price premium against erythritol and accelerating portfolio diversification beyond single-sweetener dependency.
REACH registration requirements for novel food enzymes are extending approval timelines for European market entry of next-generation sweetener manufacturing inputs. The European Food Safety Authority's expanded data demands on protein stability and allergenicity are delaying commercialization schedules. Dairy-alternative frozen dessert producers targeting German and French retail are reformulating with existing-approved inputs rather than awaiting novel enzyme clearance.
Subscription-based replenishment models are displacing impulse freezer-case purchases among ketogenic diet adherents. Direct-to-consumer brands are capturing predictable demand through auto-ship programs that bypass supermarket slotting fees and endcap rental economics. This channel migration concentrates most visibly in coastal United States metropolitan markets where cold-chain logistics density supports reliable residential delivery.
Sugar-Free Ice Cream Market Segmentation
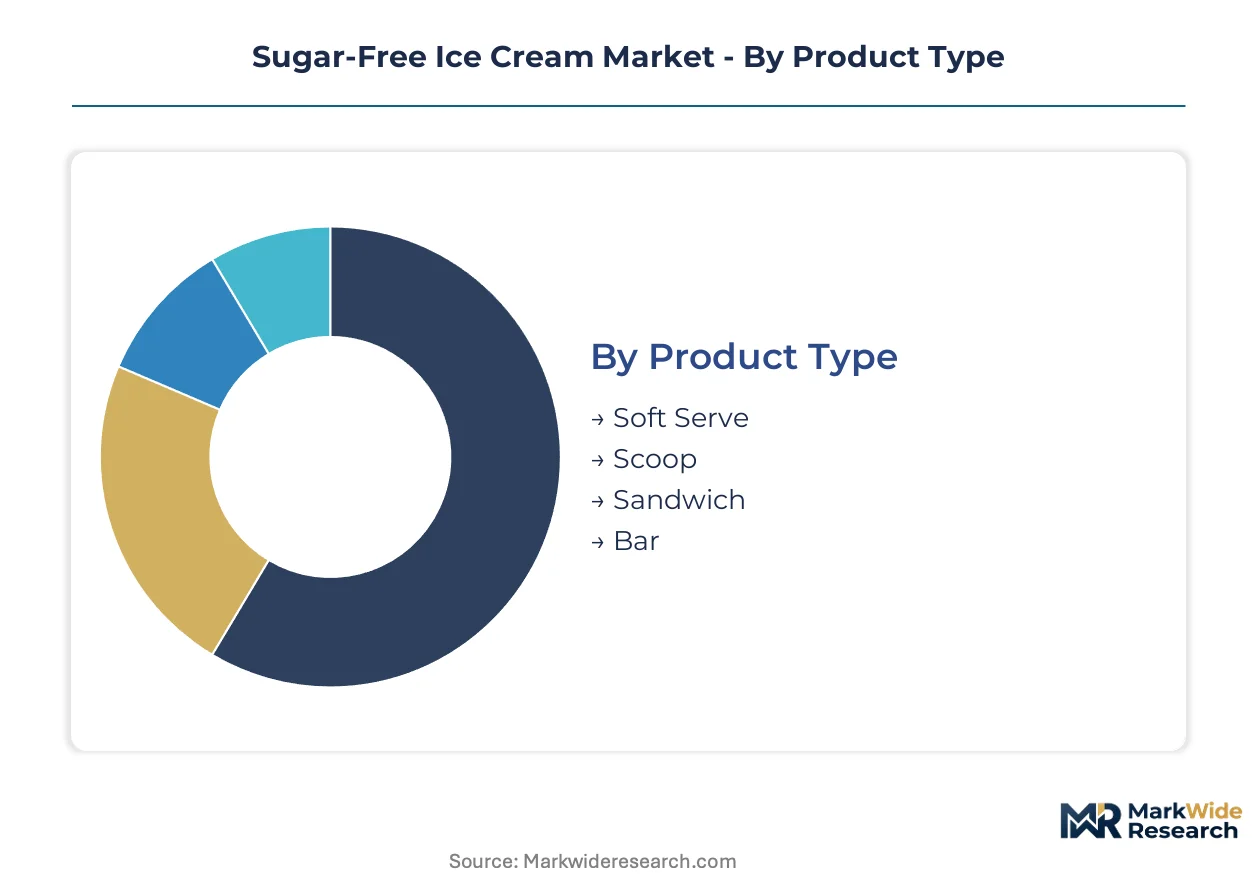
Sugar-free ice cream manufacturers calibrate formulation, packaging, and channel strategy against distinct consumer occasions and dietary compliance requirements. Each segment carries unique cold-chain demands and margin structures that reshape competitive positioning across retail and foodservice environments.
Product Type:
Supply concentration for freezing-point depression expertise clusters with industrial-scale manufacturers capable of precise overrun control across format variants.
- Scoop:Traditional pint and half-gallon formats rely on controlled aeration between twenty and sixty percent overrun to balance texture with polyol freezing curve depression. Demand concentrates in United States retail grocery, where ketogenic diet adherents prioritize portion-controlled home consumption and private-label penetration is deepest.
- Bar:Individual stick formats require cryoprotectant systems to prevent ice crystal formation during thermal shock from manufacturing through last-mile frozen distribution. Coastal United States metropolitan markets show strongest subscription channel adoption, driven by single-serve convenience and DTC auto-ship program growth.
- Soft Serve:Foodservice equipment-dependent format serving immediate-consumption occasions in quick-service restaurants and cinema concessions.
- Sandwich:Cookie-encased formats demanding dual-texture stability between wafer moisture content and filling freeze-thaw resistance.
Today's leader: Scoop. Tomorrow's challenger: Bar.
Ingredient Type:
Cost tier stratification separates premium natural-extraction formulations from commodity synthetic alternatives, with mid-tier positioning collapsing as clean-label mandates harden.
- Natural Sweeteners:Monk fruit extract and allulose formulations command formulation premiums as enzymatic conversion efficiency gains compress price gaps with erythritol. United States manufacturing lines show fastest adoption curves, pulled by FDA added-sugar labeling disclosure requirements and ketogenic lifestyle positioning.
- Dairy:Milk-fat-based formulations retain margin concentration through protein-stabilized texture systems and established cold-chain infrastructure. Northeast and Midwest United States dairy compacts supply regional processors with Grade A milk pricing advantages under Federal Milk Marketing Orders.
- Artificial Sweeteners:Aspartame and sucralose portfolios facing reformulation pressure from clean-label retail buyers and district-level school foodservice procurement standards.
- Milk Alternatives:Oat, coconut, and almond protein bases expanding fastest through allergen-free positioning and vegan dietary compliance, though cryoprotectant requirements increase formulation complexity.
Natural Sweeteners gain share fastest. Dairy defends margin concentration.
Packaging Type:
Volume throughput economics favor multi-unit formats for subscription channel fulfillment, while single-serve packaging absorbs disproportionate last-mile logistics cost.
- Tub:Cylindrical containers dominate retail freezer-case facings through stackable logistics and premium endcap positioning. United States supermarket chains allocate shelf space based on velocity thresholds that favor established private-label and national brand velocities.
- Multi-Packs:Four-to-six unit configurations align with DTC subscription replenishment cycles and family-size consumption patterns. Cold-chain density in California and New York metropolitan corridors enables reliable residential delivery without dry-ice packaging cost escalation.
- Cup:Single-serve portion control packaging for immediate-consumption and foodservice dispensing applications.
- Cone:Pre-filled wafer formats requiring moisture-barrier packaging to prevent sogginess through distribution.
Tub controls shelf presence. Multi-Packs climb the fastest.
Distribution Channel:
Customer type fragmentation splits between planned replenishment subscribers and impulse-driven freezer-case purchasers, with channel-specific margin structures reshaping brand investment priorities.
- Supermarkets:Conventional grocers retain bulk cold-chain fulfillment infrastructure and control endcap rental economics that determine new brand visibility. Slotting fee structures in United States retail favor multinational CPG scale or captive private-label programs like Kroger's Simple Truth positioning.
- Online Retail:Direct-to-consumer and third-party marketplace channels bypass slotting fees through cold-chain logistics specialization. Subscription auto-ship models concentrate lifetime value capture among ketogenic diet adherents in United States coastal markets with residential delivery density.
- Convenience Stores:Immediate-consumption occasions with limited freezer-case space favoring high-velocity single-serve formats.
- Specialty Shops:Natural products retailers and diabetic supply stores offering curated assortment and therapeutic positioning adjacency.
Supermarkets anchor volume. Online Retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States retail channels pull volume at scale unmatched by Canadian or Mexican counterparts, while European regulatory frameworks accelerate clean-label reformulation timelines faster than North American benchmarks.
United States
Ketogenic diet adherence and diabetes-prevention guidelines from the USDA drive household penetration of erythritol-sweetened pints in suburban markets. The FDA's updated Nutrition Facts labeling requirements for added sugars compress legacy aspartame portfolios. Cold-chain logistics density in California and New York metropolitan corridors enables subscription auto-ship models to bypass conventional freezer-case slotting fees.
Germany
REACH registration requirements for novel food enzymes extend approval timelines for next-generation sweetener manufacturing inputs. The European Food Safety Authority's expanded data demands on protein stability delay commercialization schedules. Dairy-alternative frozen dessert producers targeting Berlin and Munich retail are reformulating with existing-approved inputs rather than awaiting novel enzyme clearance.
United Kingdom
Clean-label retail buyer mandates accelerate monk fruit and allulose adoption across manufacturing lines serving Tesco and Sainsbury's freezer cases. The Food Standards Agency enforces strict additive disclosure requirements that reshape formulation hierarchies. London-based direct-to-consumer brands leverage dense residential delivery networks to capture ketogenic diet adherents through recurring revenue models.
Canada
Health Canada's nutrition labeling regulations align with FDA added-sugar disclosure standards, pulling reformulation investment northward. Provincial dairy marketing boards under federal supply management create pricing friction for regional producers scaling beyond cottage-food exemptions. Toronto and Vancouver metropolitan clusters concentrate cold-chain infrastructure for DTC fulfillment.
Japan
Functional food positioning and geriatric dietary compliance drive demand for low-glycemic frozen desserts in convenience retail. The Ministry of Health, Labour and Welfare maintains strict additive approval lists that constrain formulation flexibility. Osaka and Nagoya industrial corridors host precision fermentation scale-up for rare sugar production serving domestic and export markets.
Sugar-Free Ice Cream Market Vendor Landscape
United States producers anchor one tier; European multinational specialists hold freezer-case shelf-space agreements across conventional grocers. The vendor base splits between scale-driven CPG conglomerates with captive private-label programs and venture-backed direct-to-consumer challengers bypassing slotting economics. Three archetypes dominate: multinational CPG platforms with endcap rental leverage, keto-aligned subscription specialists with cold-chain logistics mastery, and supermarket captive private-label operators with velocity-based shelf allocation. Portfolio diversification into monk fruit and allulose formulations and geographic expansion through subscription auto-ship models constitute the dominant competitive moves.
Within the multinational CPG tier, Unilever PLC and Nestle SA occupy positions defined by freezer-case shelf-space agreements and conventional grocery channel density. Rebel Creamery LLC exemplifies the keto-aligned subscription specialist archetype, anchoring ultra-low-carb positioning through direct-to-consumer channels. Kroger Co. represents supermarket captive private-label strategy, leveraging Simple Truth velocity thresholds across over two thousand stores.
| Leading Market Players |
|---|
| Arctic Zero Inc. |
| Rebel Creamery LLC |
| Unilever PLC |
| Enlightened |
| Kroger Co. |
| Nestle SA |
| Halo Top Creamery |
| So Delicious |
| Danone SA |
| Others |
Supply Flow & Price Mechanics
Clean-label certification tiers split the sugar-free ice cream landscape into premium monk fruit and allulose formulations versus commodity erythritol portfolios, with each tier commanding distinct supply chain investments in enzymatic conversion infrastructure versus corn-derived feedstock hedging.
Pricing Analysis
Capacity additions in enzymatic allulose production are reshaping price floors for natural sweetener formulations as continuous conversion systems compress unit costs against legacy erythritol benchmarks. Three-tier pricing structure across premium monk fruit, standard allulose, and economy erythritol levels reflects certification grade and freezing-point depression performance. Pricing pressure stems from corn feedstock volatility squeezing erythritol margins. Ketogenic subscription consumers show lowest price sensitivity while conventional retail grocery buyers concentrate price negotiation leverage.
Supply Chain Analysis
Dry-ice logistics costs dominate last-mile economics for direct-to-consumer frozen fulfillment, constraining subscription channel expansion beyond coastal metropolitan cold-chain density clusters. Corn supply concentrates in United States Midwest agricultural corridors, monk fruit extraction anchors in southern Chinese provinces, and allulose enzymatic conversion scales through Osaka and Nagoya industrial zones. Erythritol production draws from biofuel policy-exposed feedstock markets. Single-source vulnerability concentrates in cryoprotectant additive supply. Distribution runs through supermarket freezer-case slotting fee structures and DTC cold-chain specialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates with brands capturing clean-label premium positioning as enzymatic allulose conversion automation collapses input cost curves for natural sweetener formulations.
For Market Incumbents: To counter subscription channel displacement of impulse freezer-case purchases, secure captive monk fruit and allulose supply through backward integration into enzymatic conversion partnerships, and defend shelf-space velocity through private-label line extensions with premium endcap positioning. For New Entrants and Emerging Players: Begin with pediatric and school-foodservice procurement channels where USDA Smart Snacks standards create underpenetrated institutional demand, leveraging therapeutic positioning adjacency in retail pharmacy cold-case placement to bypass conventional supermarket slotting economics. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation scale-up specialists mastering rare sugar enzymatic conversion efficiency, with long-term viability hinging on regulatory clearance velocity for novel food enzymes across EFSA and FDA jurisdictions. Watch REACH registration timeline compression as inflection signal for European market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Allulose Capacity Expansion | Continuous conversion automation collapses price premiums against erythritol across North American manufacturing lines. |
| Direct-to-Consumer Cold-Chain Buildout | Dry-ice logistics specialization enables subscription auto-ship models to bypass supermarket slotting fee structures. |
| Retail Pharmacy Freezer Placement | CVS Health and Walgreens diabetes care adjacency creates therapeutic positioning channel for low-glycemic brands. |
| Pediatric School-Foodservice Certification | USDA Smart Snacks compliance opens institutional procurement pull in underpenetrated district foodservice segments. |
| Monk Fruit Supply Backward Integration | Captive extraction partnerships secure clean-label input cost stability against volatile corn-derived erythritol feedstock. |
Methodological Framework
Bottom-up retail channel modeling reconciled against top-down sweetener manufacturing tracking forms the analytical core, combining primary interviews with frozen dessert brand managers, supermarket category buyers, cold-chain logistics specialists, and enzymatic conversion technology providers with secondary validation through FDA labeling guidance documents, USDA Dietary Guidelines, and Nielsen retail audit data.
Historical trendline analysis of natural sweetener adoption curves and polyol price elasticity informs projection frameworks across product type, ingredient category, packaging format, and distribution channel segmentation dimensions. CAGRs derive from regression-adjusted growth rate synthesis incorporating ketogenic diet adherence survey data and diabetes-prevention guideline implementation timelines.
Several conditions sit outside the modeled scope, including pending EPA assessments of erythritol manufacturing byproducts and evolving WHO guidance on non-sugar sweeteners. Forecasts reflect assumptions about enzymatic conversion efficiency gains and cold-chain logistics density expansion that biofuel policy shifts or carrier sustainability pledges could revise. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Global Potato Flake Market
Processed Foods
Global Malted Milk Market
Processed Foods
Chocolate Filling Market
Processed Foods
Low Fat Soups Market
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Block Margarine Market
Processed Foods
Soup & Broth Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Margarine Market
Processed Foods
Casual Marinated Products Market
Processed Foods
Imitation Whipped Cream Market
Processed Foods
Broth Market
Processed Foods
Global Take Out Fried Chicken Market
Processed Foods
US Processed Pumpkin Market