
 Global Potato Flake Market | 2026-2036
Global Potato Flake Market Size, Share, and Industry Trends Forecast 2026-2036
Global Potato Flake Market Outlook
The Netherlands is rewriting competitive dynamics in potato flake manufacturing through expanded processing corridors in Flevoland and Noord-Brabant. Aviko Rixona leverages its integrated starch-to-flake operations across Dutch and Belgian facilities. McCain Foods anchors North American supply through its extensive grower-contracting network. Emsland Group differentiates via specialty flake grades tailored to European bakery applications.
Potato flakes consist of cooked, mashed, and drum-dried or air-dried potato solids, typically retaining 6-8% moisture content for extended shelf stability and instant reconstitution. Industrial buyers deploy them as thickening agents, binder ingredients, and texture modifiers across formulated foods. Instant potato flakes command the largest volume share within product type segmentation due to their dominance in food service rehydration systems. Dehydrated potato flakes are gaining fastest in processed foods as manufacturers seek clean-label alternatives to modified starches. Organic potato flakes capture premium shelf positioning in retail channels, though supply constraints limit volume scaling.
EU REACH compliance and FDA food additive regulations govern residual processing aids and heavy metal thresholds in cross-border flake trade. BIS certification requirements in India are tightening for imported dehydrated potato products, redirecting some sourcing toward domestic processors. Stakeholders must monitor evolving moisture-content standards in major import jurisdictions and assess backward integration into regional potato supply bases before capacity commitments solidify.
Market Dynamics
EU F-Gas Regulation mandates are forcing industrial flake processors to abandon conventional refrigerant-based drying systems. This regulatory pressure is compressing capital deployment timelines and advantaging processors with early heat-pump or thermal storage investments.
Growth Catalysts
- Snack Reformulation Mandates:Food service operators in India and Southeast Asia are replacing fried potato bases with reconstituted flake alternatives to meet trans-fat reduction targets.
- REACH Compliance Arbitrage:European processors with certified clean-label flake grades capture shelf space as modified starch faces additive scrutiny under EFSA guidelines.
- Quick-Service Localization:Burger chains and QSR networks in India are mandating domestic flake procurement, accelerating food processing infrastructure buildout.
Market Restraints
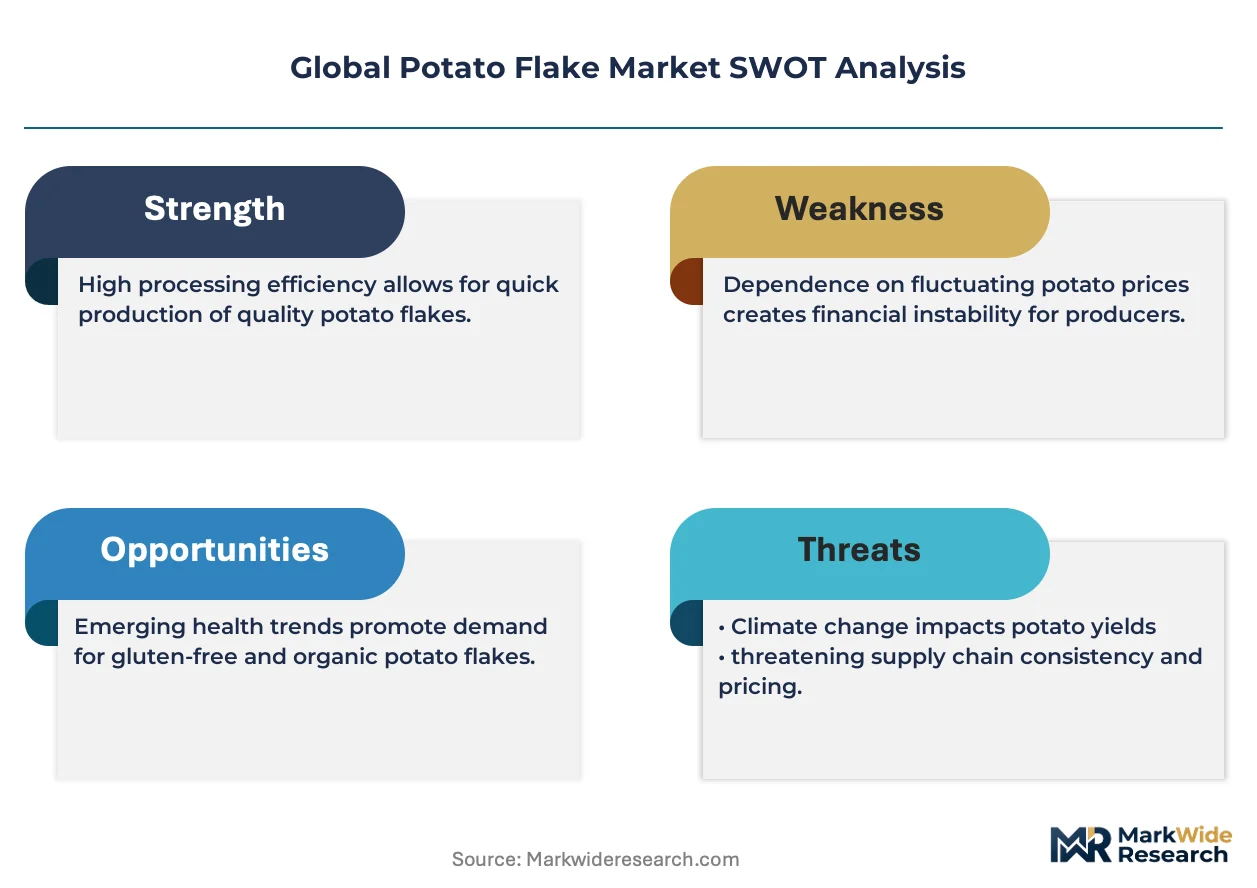
- Input Cost Volatility:Natural gas and electricity price spikes in the Netherlands and Belgium directly compress drum-drying margins for flake manufacturers.
- Supply Concentration Risk:Processing-grade potato contracting concentrates among three Dutch-Belgian starch-flake integrated groups, creating procurement bottlenecks.
- Moisture Specification Friction:Divergent residual moisture standards between FDA and BIS certification regimes force dual-line production or exclusion from key import markets.
Strategic Opportunities
- Organic Grade Scaling:Premium retail channels in Germany and France absorb organic flake volumes at price multiples, though certified seed potato supply limits expansion.
- Heat-Pump Drying Convergence:Integration of industrial heat pumps with solar thermal arrays enables processors to market near-zero Scope 2 flake production.
- Direct Food Service Distribution:Bypassing ingredient distributors, flake processors are establishing captive supply contracts with institutional catering networks in India.
Industry Challenges
- Process Engineering Talent Scarcity:Drum-drying optimization and heat-recovery system design expertise concentrates among retiring specialists in Dutch processing corridors.
- Capex Intensity for Compliance:F-Gas-compliant drying retrofits require eight-figure euro investments that strain mid-scale processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Potato Flake Market |
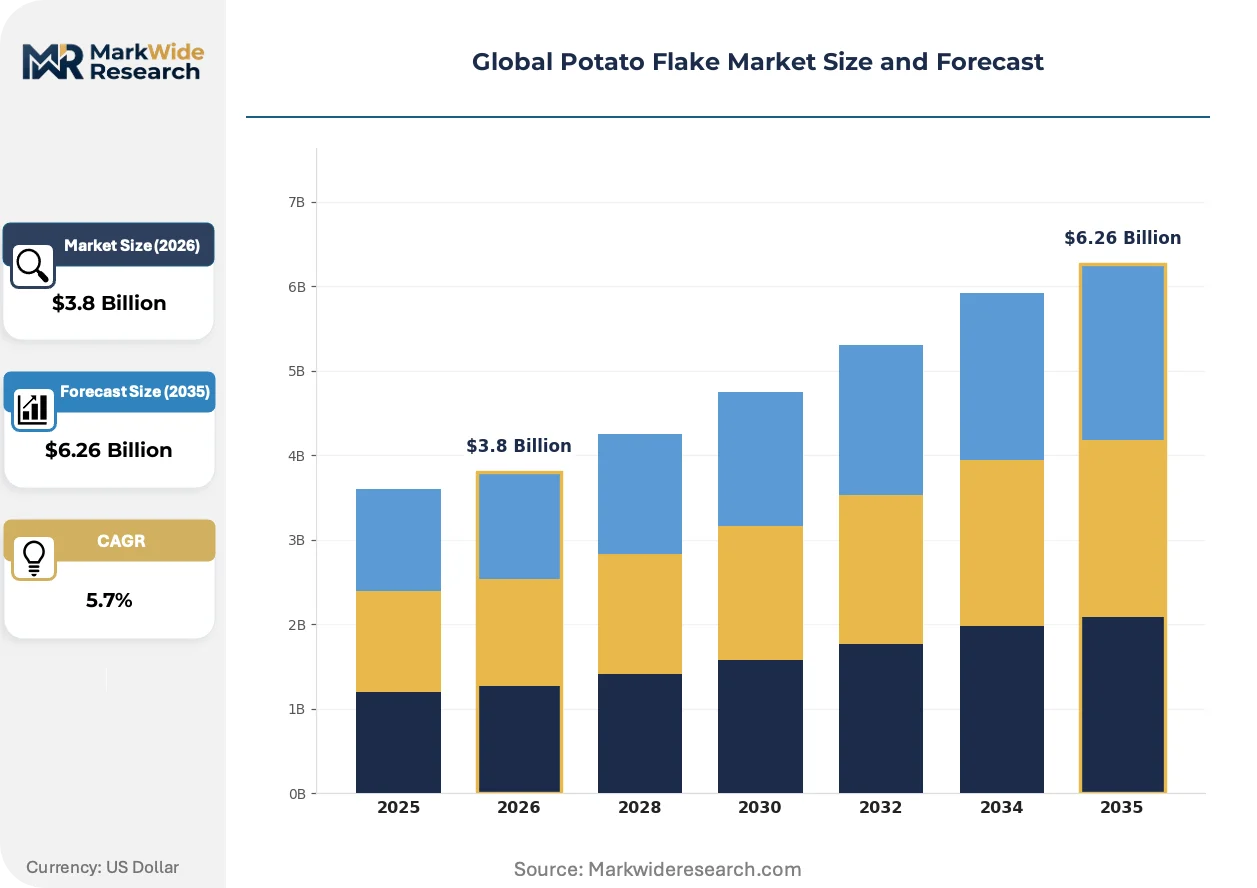
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Potato Flakes, Dehydrated Potato Flakes, Organic Potato Flakes, Flavored Potato Flakes End Use: Food Service, Retail, Processed Foods, Snacks Packaging Type: Bulk Packaging, Retail Packaging, Pouches, Sachets Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Aviko Rixona, Emsland Group, McCain Foods, Clarebout Potatoes, PepsiCo (Frito-Lay Division), Lamb Weston Holdings, Mydibel, Goodrich Cereals, J.R. Simplot Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Potato Flake Market Strategic Shifts
Digital twin modeling is virtualizing process control across flake manufacturing, enabling real-time moisture optimization and predictive maintenance. This shift compresses quality variance and extends equipment lifecycles.
Advanced sensor arrays coupled with machine-learning control systems are virtualizing traditional drum-drying operations. Snack manufacturers in Germany and the Netherlands deploy these systems to lock moisture content within 0.3 percentage points of specification. The technology is virtualizing quality assurance labor and collapsing batch rejection rates.
EU F-Gas Regulation phase-down schedules are accelerating industrial heat-pump adoption in Belgian and Dutch processing facilities. Manufacturers face 2027 deadlines for refrigerant replacement or facility closure. Organic and clean-label flake grades absorb the capital cost pass-through most readily, redirecting investment toward premium production lines.
Food service buyers are consolidating supplier relationships around dual-certified processors capable of serving both European and Indian regulatory regimes. Large-scale institutional caterers in India now require BIS-certified flake supply with traceability documentation. This consolidation is compressing the viable supplier base and advantaging processors with multi-jurisdiction compliance infrastructure.
Global Potato Flake Market Segmentation
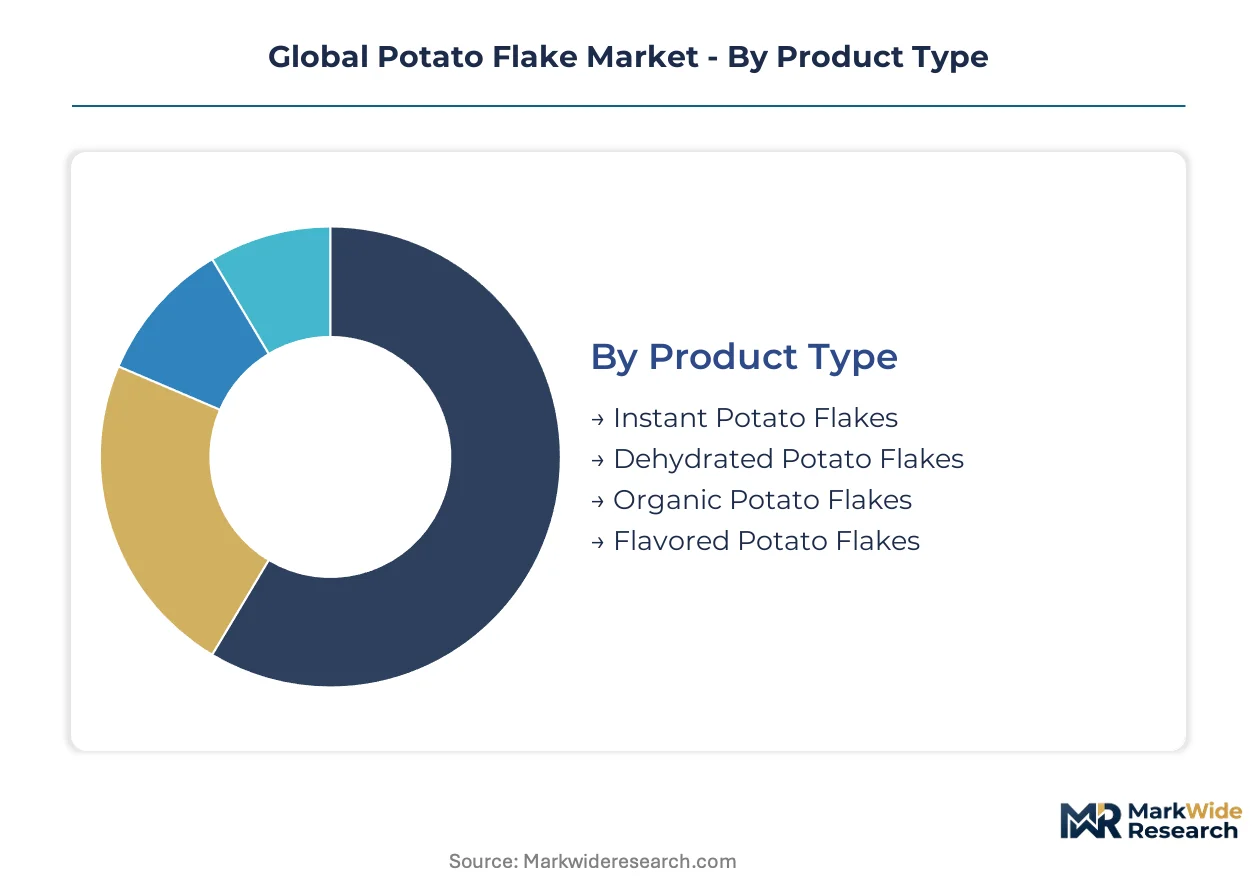
Product differentiation across moisture content, reconstitution speed, and certification grade determines procurement patterns in potato flake markets. Buyers segment supply by technical specification rather than brand, creating tiered sourcing strategies across food manufacturing verticals.
Product Type:
Cost tier differentiation separates commodity-grade flakes from premium-certified alternatives, with processing method and input potato quality driving price multiples.
- Instant Potato Flakes:Pre-cooked and drum-dried to 6-8% moisture, these flakes rehydrate in under two minutes with minimal agitation. Demand concentrates in North American and European food service institutional kitchens where labor reduction offsets per-kilogram premiums. The segment holds installed capacity.
- Dehydrated Potato Flakes:Air-dried or low-temperature processed to preserve cellular structure, these flakes suit clean-label processed foods seeking modified starch replacement. German and Dutch snack manufacturers are rotating up the share rankings as EFSA additive scrutiny intensifies.
- Organic Potato Flakes:Certified organic supply chains from seed potato through drying command retail premiums in France and Germany, though certified acreage constraints limit volume scaling.
- Flavored Potato Flakes:Pre-seasoned variants with butter, cheese, or herb inclusions target convenience-oriented retail segments in Japan and South Korea.
Instant grades dominate food service procurement volumes. Dehydrated variants are climbing the fastest in clean-label reformulation pipelines.
End Use:
Application requirements dictate moisture specifications, with each vertical enforcing distinct reconstitution performance and shelf-stability thresholds.
- Food Service:Institutional caterers and quick-service chains in India specify BIS-certified flakes with batch traceability documentation for rehydration systems. This segment holds installed capacity.
- Processed Foods:Soup, sauce, and ready-meal manufacturers in Belgium and the Netherlands deploy flakes as binder ingredients, with REACH-compliant clean-label grades gaining formulation share fastest.
- Retail:Supermarket channels in Germany absorb instant and flavored variants for home preparation, with organic SKUs commanding shelf positioning premiums.
- Snacks:Extruded and sheeted snack manufacturers in India replace fried potato bases with reconstituted flake alternatives to meet trans-fat reduction mandates.
Food service channels anchor volume procurement. Processed foods application is expanding most quickly on clean-label substitution demand.
Packaging Type:
Volume scale and handling requirements separate industrial bulk from consumer-facing formats, with moisture barrier specifications varying by distribution environment.
- Bulk Packaging:Multi-ton flexible intermediate bulk containers and lined paper sacks serve food manufacturers with dedicated reconstitution equipment. This segment holds installed capacity.
- Retail Packaging:Boxed and bagged formats for supermarket shelves incorporate oxygen scavengers and nitrogen flushing for 18-24 month shelf stability.
- Pouches:Stand-up and flat pouches target convenience-oriented retail segments in urban Indian markets with single-meal portioning.
- Sachets:Individual-serve packets for institutional food service and airline catering prioritize portion control and waste reduction.
Bulk packaging dominates industrial procurement. Pouch formats are gaining share fastest in emerging market retail expansion.
Distribution Channel:
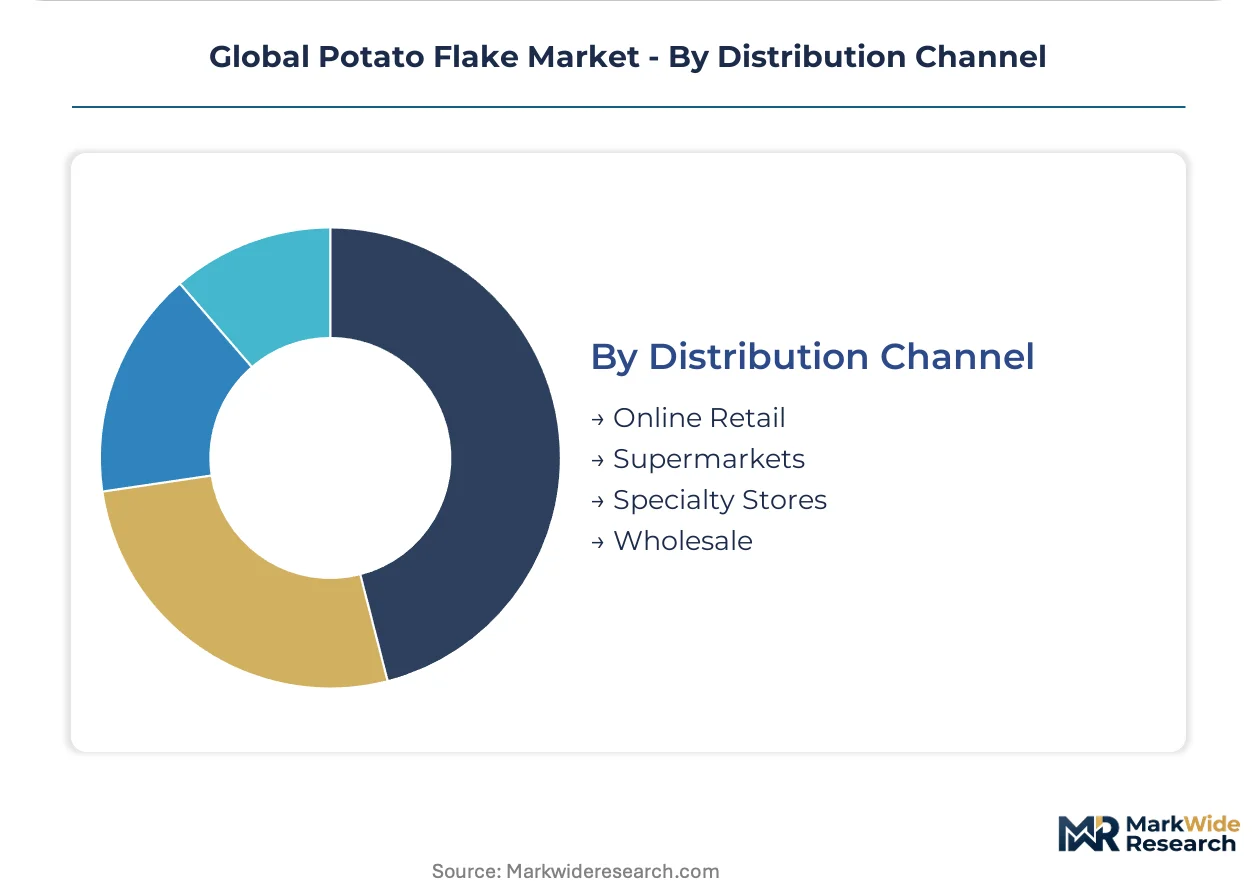
Customer type and order scale determine channel selection, with certification documentation requirements filtering available supply sources.
- Wholesale:Ingredient distributors in the Netherlands and Belgium consolidate flake supply from integrated starch processors for onward sale to mid-scale food manufacturers. This segment holds installed capacity.
- Supermarkets:Mass retail chains in France and Germany stock branded and private-label instant flakes, with organic SKUs occupying premium shelf positioning.
- Online Retail:Direct-to-consumer platforms in India and Japan enable specialty and organic flake access beyond traditional retail footprints.
- Specialty Stores:Gourmet and natural food retailers in Germany curate organic and heirloom potato varietal flakes for premium consumer segments.
Wholesale channels anchor B2B volume flows. Online retail is rotating up the share rankings in emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: European buyers prioritize clean-label certification and REACH-compliant supply chains, while Indian procurement emphasizes BIS traceability for institutional food service, and North American demand centers on instant rehydration formats for labor-constrained kitchens.
Netherlands
Integrated starch-to-flake processors dominate procurement through grower-contracting networks in Flevoland and Noord-Brabant. EU F-Gas Regulation mandates are compressing capital deployment timelines for drum-drying retrofits. Emsland Group and Aviko Rixona anchor processing capacity across Dutch-Belgian corridor facilities.
India
Quick-service restaurant chains and institutional caterers are mandating domestic flake procurement as food processing infrastructure scales. BIS certification requirements for imported dehydrated potato products are tightening, redirecting sourcing toward domestic processors. Maharashtra and Gujarat processing clusters are expanding capacity to serve localized QSR supply contracts.
Germany
Snack manufacturers are rotating toward dehydrated flake grades as EFSA additive scrutiny intensifies against modified starches. REACH compliance arbitrage advantages European processors with certified clean-label supply. Bavaria and Baden-Württemberg bakery applications absorb specialty flake grades at formulation premiums.
United States
Food service institutional kitchens anchor volume demand for instant rehydration formats where labor reduction offsets per-kilogram premiums. FDA food additive regulations govern residual processing aids in cross-border flake trade. Idaho and Washington potato-growing regions supply McCain Foods and Lamb Weston processing networks.
Belgium
Heat-pump drying convergence with solar thermal arrays is enabling near-zero Scope 2 flake production claims. Natural gas and electricity price spikes are compressing drum-drying margins for conventional processors. Mydibel occupies processing capacity within the Dutch-Belgian integrated starch corridor.
Global Potato Flake Market Competitive Environment
Capability concentration sits with integrated starch-to-flake processors possessing backward control over seed potato supply and certified clean-label production lines; scale advantage sits with multinational food manufacturers with captive grower networks and institutional distribution reach. The market structures around three tiers: integrated Dutch-Belgian processors, North American frozen-food conglomerates with flake divisions, and regional specialists serving single jurisdictions. Dominant competitive moves include F-Gas-compliant drying retrofits requiring eight-figure capital commitments, and direct food service distribution contracts bypassing ingredient wholesalers in emerging markets.
Among integrated European processors, Aviko Rixona and Emsland Group exemplify the capability-concentrated tier with starch-to-flake operations spanning Dutch and Belgian facilities. McCain Foods anchors the scale-driven North American segment through extensive grower-contracting networks. These three represent divergent strategic positions: European integration around specialty grades and regulatory compliance, versus North American volume anchoring through food service distribution density.
| Leading Market Players |
|---|
| Aviko Rixona |
| Emsland Group |
| McCain Foods |
| Clarebout Potatoes |
| PepsiCo (Frito-Lay Division) |
| Lamb Weston Holdings |
| Mydibel |
| Goodrich Cereals |
| J.R. Simplot Company |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Maharashtra and Gujarat processing clusters is compressing supplier bargaining power and forcing price premiums on BIS-certified flake contracts. Dutch drum-drying facilities running at 90%-plus utilization are passing through natural gas cost spikes to European bakery and snack manufacturers.
Pricing Analysis
Long-term offtake agreements anchor procurement between integrated starch processors and institutional food service buyers in India and the Netherlands. Three-tier pricing structure across organic-certified, REACH-compliant clean-label, and commodity-grade instant flakes separates certification investment levels from volume scale discounts. Cost compression in standard-grade segments is intensifying because F-Gas retrofit capital requirements concentrate among mid-scale operators. Quick-service restaurant chains in India exhibit highest price sensitivity due to localized procurement mandates, while German organic retail channels absorb premiums with minimal volume elasticity.
Supply Chain Analysis
Processing-grade potato feedstock draws from contracted acreage concentrated in the Netherlands, Belgium, and Idaho. Drum-drying energy inputs, organic seed potato certification, and moisture-barrier packaging materials constitute critical cost components. Single-source vulnerability runs through the Dutch-Belgian starch-flake integrated corridor where three processor groups control 80% of EU supply. Distribution runs through wholesale ingredient distributors in the Netherlands consolidating multi-origin supply for onward sale to mid-scale European food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The potato flake market is approaching a platform-economics inflection as digital twin standardization across Dutch processing facilities creates interoperability moats that lock in food service buyer ecosystems.
For Market Incumbents: Pre-empt heat-pump drying convergence by retrofitting Flevoland and Noord-Brabant facilities before 2027 regulatory deadlines compress capital access for mid-tier competitors. Backward integration into certified organic seed potato supply secures premium-grade positioning as French and German retail channels tighten provenance requirements. Channel control through direct food service contracts in India bypasses distributor margin extraction.
For New Entrants and Emerging Players: Build out BIS-certified processing capacity in Maharashtra to capture quick-service restaurant localization mandates before incumbent Dutch-Belgian groups establish joint ventures. The most penetrable white space sits in dehydrated clean-label flake supply for German snack reformulation pipelines. A go-to-market angle targeting institutional caterers with batch-traceability documentation and captive logistics outperforms commodity wholesale positioning.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated starch-to-flake processors with multi-jurisdiction compliance infrastructure spanning EU REACH and Indian BIS certification regimes. Long-term viability hinges on regulatory arbitrage capability across divergent moisture-content standards rather than volume scale alone. The signal to watch is consolidation momentum among Maharashtra processing clusters as domestic QSR procurement mandates harden.
| Strategic Initiative | Industry Significance |
|---|---|
| F-Gas-Compliant Drying Retrofit | EU Regulation mandates heat-pump adoption by 2027, advantaging early capital deployers in Dutch corridor. |
| Backward Integration into Organic Seed Supply | Certified acreage scarcity in France and Germany limits premium-grade scaling without upstream control. |
| Direct Food Service Distribution | Bypassing wholesale distributors in India captures margin and locks in BIS-traceability-dependent QSR contracts. |
| Digital Twin Process Virtualization | Real-time moisture optimization at Aviko Rixona and Emsland Group facilities collapses quality variance. |
| Dual-Certification Infrastructure Buildout | Simultaneous EU REACH and Indian BIS compliance compresses viable supplier base to integrated processors. |
Study Parameters
A spread of perspectives from drum-drying process engineers, food service procurement directors at Indian QSR chains, ingredient distribution managers in the Netherlands, and regulatory affairs specialists at ECHA converged on the working assumptions. Primary fieldwork combined facility site assessments across Flevoland and Maharashtra with structured interviews. Secondary validation drew from EU F-Gas Regulation implementation tracking, BIS certification disclosure databases, EFSA additive guidance documents, and customs trade flow records. Bottom-up capacity utilization estimates and top-down demand segmentation were triangulated against cross-referenced stakeholder inputs.
Demand-supply-balance modeling across the projection horizon anchored volume forecasts to food service institutional procurement patterns, snack reformulation pipeline velocities, and clean-label substitution elasticities in German processed foods. Segmentation dimensions spanned product type, end-use vertical, packaging format, and regional regulatory cluster. CAGRs were derived from iterative reconciliation of historical capacity expansion patterns with announced retrofit timelines and localized procurement mandate enforcement trajectories. Heat-pump adoption curves and organic seed potato supply constraints constituted industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed processors entering BIS certification pipelines would shift outcomes beyond modeled bounds. Cross-checking against EU ETS carbon price trajectories and Indian PLI scheme disbursement schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Ready-To-Whip Toppings Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Processed Meat Market
Processed Foods
Processed Superfruits Market
Processed Foods
Egg White Cubes Market
Processed Foods
Processed Potatoes Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
Soup Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Tomato Puree Market
Processed Foods
Chocolate Filling Market
Processed Foods
Processed Cashew Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
South America Processed Meat Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Global Dried Processed Food Market