
 Europe Soup Market | 2026-2036
Europe Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Soup Market Foresight
Poland's soup manufacturing base is narrowing the cost gap with Western European production, drawing co-packing contracts from brands seeking supply chain flexibility. Nestle SA leverages its chilled distribution network to dominate fresh soup shelves across France and the United Kingdom. Unilever plc sustains margin leadership in dry soup through Knorr's brand equity and recipe heritage in Central Europe. Baxters Food Group Ltd. anchors premium positioning in Scotland and Northern England with traditional broth formulations.
Europe soup encompasses liquid or semi-liquid food preparations manufactured through thermal processing, dehydration, or blast-chilling, typically containing water, vegetables, proteins, and seasonings at moisture contents ranging from 85% in fresh formats to below 5% in dry concentrates, designed for convenient consumption across retail and foodservice channels. Dry soup retains the largest volume share due to extended shelf stability and low logistics costs, though fresh soup captures expanding margin pools as retailers prioritize chilled perimeter categories. Pouch packaging grows fastest among container types, displacing metal cans in premium and organic segments where consumer convenience and microwave compatibility drive preference. Vegetable-based formulations lead ingredient type splits, reflecting EFSA-influenced dietary guidelines and sustained plant-forward menu development across European foodservice operators.
EFSA front-of-pack nutrition labeling and EU Green Deal packaging directives compel reformulation toward reduced sodium and recyclable or reduced-plastic formats, directly influencing R&D allocation and supplier qualification criteria. REACH chemical compliance and national health claims frameworks in France and Germany further constrain ingredient sourcing and marketing vocabulary for cross-border brands. Stakeholders must monitor evolving Extended Producer Responsibility schemes and carbon border adjustments that will reshape competitive cost structures for imported versus regionally manufactured soup products.
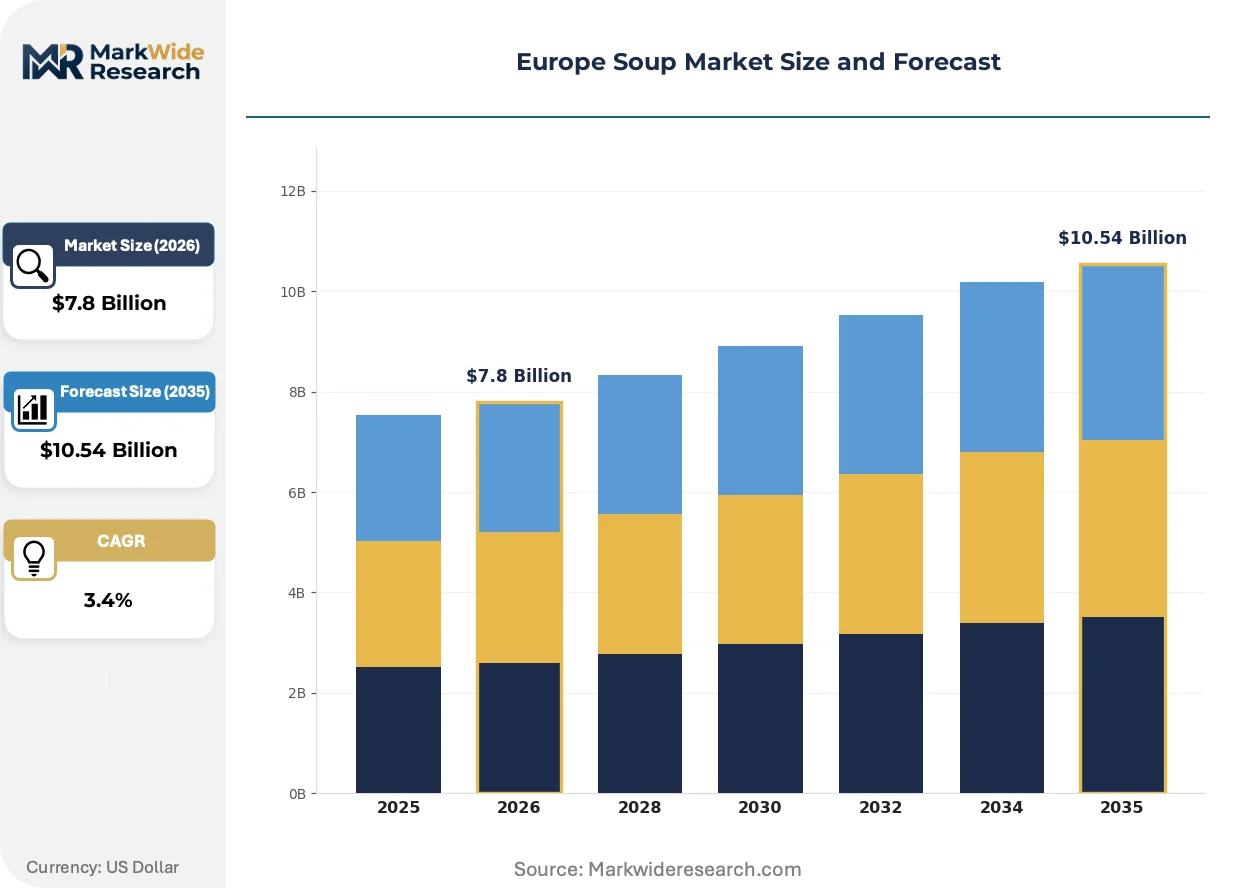
Market Dynamics
EFSA front-of-pack nutrition labeling and EU Green Deal packaging mandates are forcing simultaneous reformulation and sustainable packaging transitions across European soup manufacturing, compressing R&D timelines and supplier qualification windows.
Growth Catalysts
- EU Green Deal packaging mandates:The directive accelerates recyclable and reduced-plastic format adoption, creating first-mover advantages for manufacturers with compliant pouch and carton technologies.
- Health-conscious urban consumers in Germany and France:Clean-label demand pulls fresh soup expansion into chilled retail perimeters, expanding margin pools beyond stable dry soup categories.
- Blast-chilling technology adoption:Extended shelf-life without preservatives enables broader distribution of premium fresh formats across national borders.
Market Restraints
- Input cost volatility in vegetable proteins and dairy:Weather-driven supply fluctuations compress margins for cream-based and protein-fortified formulations.
- Supply concentration in Western European retail channels:Supermarket private-label dominance in France and the United Kingdom limits branded pricing power and shelf access.
- REACH chemical compliance complexity:Cross-border brands face ingredient sourcing constraints and restricted marketing vocabulary under ECHA frameworks.
Strategic Opportunities
- Poland's emerging manufacturing base:Narrowing cost gaps with Western production attract co-packing contracts seeking supply chain flexibility and tariff-advantaged sourcing.
- Extended Producer Responsibility scheme expansion:Early compliance investments position manufacturers for competitive cost structures under evolving carbon border adjustments.
- Plant-forward menu development:EFSA-influenced dietary guidelines create white space for vegetable-based formulations targeting foodservice operators.
Industry Challenges
- Reformulation talent scarcity:Sodium reduction expertise and clean-label stabilization chemistry skills command premium wages in tight labor markets.
- Legacy canning asset stranding:Metal can production lines face accelerated obsolescence as pouch packaging captures premium and organic segment growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Soup Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $10.54 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Soup, Frozen Soup, Dry Soup, Fresh Soup Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice Ingredient Type: Vegetable-Based, Meat-Based, Seafood-Based, Organic Packaging Type: Cartons, Cans, Pouches, Jars |
| Companies Covered | Unilever plc, The Kraft Heinz Company, Campbell Soup Company, Nestle SA, Premier Foods plc, Baxters Food Group Ltd., Conagra Brands, Inc., General Mills, Inc., GB Foods SA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Soup Market Shifts & Advancements
Microwave-compatible pouch formats and high-pressure processing are compressing traditional thermal processing timelines, while regulatory pressure on sodium and packaging waste rewrites formulation and sourcing priorities.
Retort pouch technology with self-venting films is collapsing the convenience gap between shelf-stable and fresh soup categories. German and French retailers are expanding chilled perimeter space for these formats. The structural consequence is margin compression for metal can suppliers and accelerated line conversion investments.
EFSA front-of-pack nutrition labeling rules are mandating sodium disclosure thresholds that force reformulation of legacy recipes. Manufacturers are deploying potassium chloride blends and umami-enhancing yeast extracts to maintain palatability. Central European dry soup portfolios face the steepest compliance timelines given Knorr's entrenched recipe heritage.
Urban French and British consumers are consolidating purchases around supermarket private-label fresh soups, displacing branded loyalty with quality-perception parity. Discounters in Germany are replicating this model with accelerated private-label development. The channel shift is most visible in London and Paris metropolitan retail networks where chilled soup penetration exceeds national averages.
Europe Soup Market Segmentation
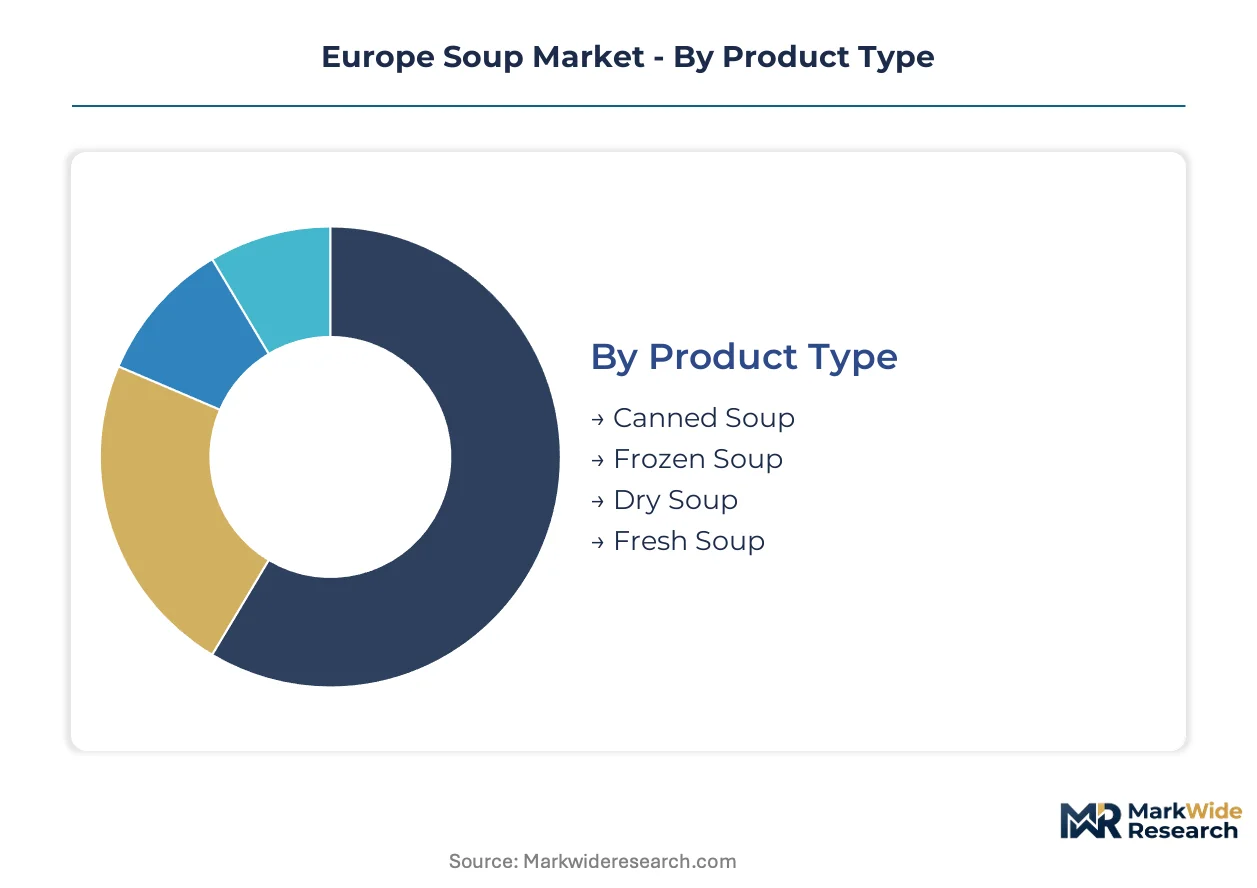
Soup segmentation in Europe reflects divergent convenience needs and regulatory pressures. Product format and packaging choices determine shelf positioning, margin structure, and compliance burden across national retail networks.
Product Type:
Mature dry formats dominate volume throughput while fresh segments accelerate on margin expansion.
- Dry Soup:Dehydrated formulations with moisture content below 5% enable extended ambient storage and low-cost logistics. Central European households sustain Knorr's entrenched recipe heritage, though EFSA sodium disclosure thresholds force aggressive reformulation of legacy portfolios.
- Fresh Soup:Blast-chilled preparations at 85% moisture content occupy expanding chilled perimeter space in French and British supermarkets. Clean-label positioning commands price premiums as urban consumers consolidate purchases around private-label quality parity.
- Canned Soup:Thermal-processed metal-container formats retain foodservice penetration but face retail displacement.
- Frozen Soup:Cryogenic preservation extends distribution reach for premium formulations with limited ambient stability.
Dry soup handles the majority of throughput; fresh soup is the fastest mover on share.
Distribution Channel:
Channel concentration shapes pricing power and brand access across Western European retail hierarchies.
- Supermarkets:Dominant retail channel with private-label development accelerating in France, the United Kingdom, and Germany. Discounter expansion replicates quality-perception parity models, compressing branded shelf access in metropolitan London and Paris networks.
- Foodservice:Out-of-home operators drive vegetable-based formulation demand under EFSA-influenced dietary guidelines.
- Online Retail:Direct-to-consumer platforms gain traction for subscription-based organic and premium specialty formats.
- Convenience Stores:Limited assortment focuses on single-serve ambient and chilled impulse purchases.
Supermarkets handle the majority of throughput; foodservice is climbing the fastest on volume contribution.
Ingredient Type:
Plant-forward positioning aligns with regulatory nutrition guidance and sustainability messaging requirements.
- Vegetable-Based:Formulations lead ingredient splits across retail and foodservice, reflecting sustained menu development by European operators seeking EFSA compliance pathways.
- Organic:Certified ingredient sourcing attracts pouch packaging adoption and premium positioning in German and French organic retail networks.
- Meat-Based:Traditional protein fortification faces input cost volatility and sodium reduction complexity.
- Seafood-Based:Niche positioning in coastal Mediterranean markets with supply concentration challenges.
Vegetable-based formulations handle the majority of throughput; organic is expanding most quickly on share.
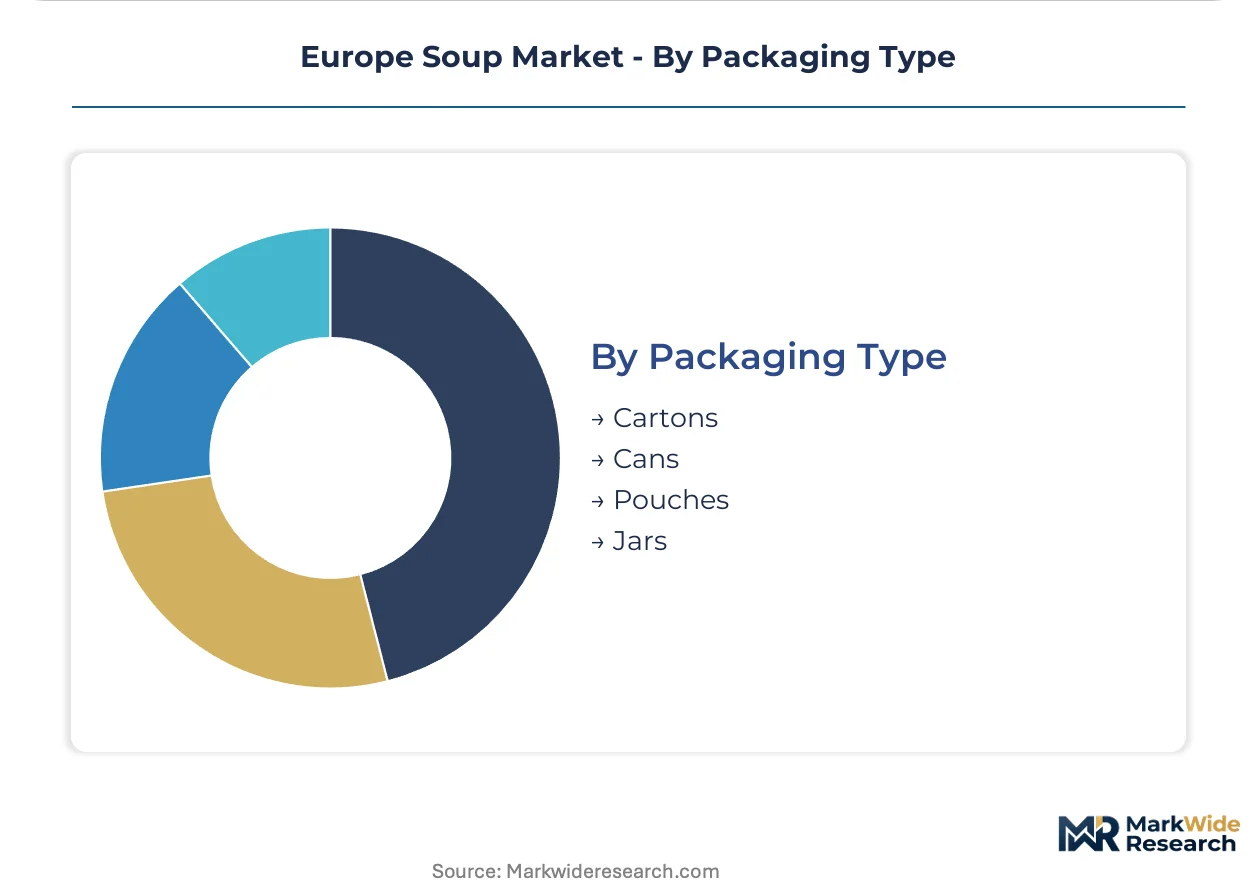
Packaging Type:
EU Green Deal mandates accelerate format transitions with compliance timelines compressing supplier qualification windows.
- Pouches:Retort pouch technology with self-venting films collapses convenience gaps between shelf-stable and fresh categories. Microwave compatibility drives German and French retailer expansion of chilled perimeter space for these formats.
- Cartons:Recyclable fiber-based containers align with carbon border adjustment preparedness and Extended Producer Responsibility scheme evolution.
- Cans:Metal containers face accelerated obsolescence as line conversion investments redirect toward flexible formats.
- Jars:Glass packaging retains premium organic positioning with higher logistics cost burdens.
Pouches handle the majority of new investment throughput; cartons are gaining share fastest on regulatory alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western European retail networks concentrate demand for premium fresh formats, while Central European manufacturing assets exploit cost advantages in dry soup production. National regulatory frameworks and retailer consolidation patterns create divergent competitive access across the region.
Germany
Urban consumers in Berlin and Munich drive clean-label fresh soup demand through discounter and supermarket channels. EFSA front-of-pack nutrition labeling rules force sodium reduction reformulation across legacy dry portfolios. The Rhine-Ruhr industrial corridor hosts pouch packaging line conversions as manufacturers abandon metal can assets.
France
Paris metropolitan retail networks exhibit the highest chilled soup penetration rates in Europe, consolidating purchases around private-label quality parity. ANSM and DGCCRF enforcement of health claims frameworks restricts cross-border marketing vocabulary. The Île-de-France region anchors Nestle SA's chilled distribution dominance through refrigerated logistics hubs.
United Kingdom
London and Southeast England supermarket chains accelerate private-label development, compressing branded shelf access for ambient and fresh formats. Extended Producer Responsibility schemes under Environment Agency guidance reshape packaging compliance costs. Scotland's Baxters Food Group Ltd. maintains premium broth positioning in Northern England through traditional recipe heritage.
Poland
Warsaw and Łódź manufacturing zones attract co-packing contracts from Western European brands seeking supply chain flexibility. REACH chemical compliance through ECHA frameworks constrains ingredient sourcing for export-bound production. The country's narrowing cost gap with Western European production drives foreign direct investment in blast-chilling capacity.
Italy
Milan and Northern Italian foodservice operators sustain vegetable-based formulation demand under EFSA-influenced dietary guidelines. Ministry of Health enforcement of national health claims frameworks parallels French and German regulatory stringency. The Emilia-Romagna region concentrates artisanal broth production for premium export channels.
Europe Soup Market Competitive Landscape
Multinational packaged food conglomerates and regional heritage specialists split the market into consolidated premium tiers and fragmented private-label supply bases. Nestle SA and Unilever plc anchor the multinational tier through chilled distribution networks and dry soup brand equity respectively. Three archetypes dominate: scale-driven multinationals with captive retail relationships, regional heritage brands with recipe-based differentiation, and private-label manufacturers with cost-optimized pouch production. Competitive intensity manifests through portfolio diversification into adjacent ready-meal categories and accelerated line conversion from metal cans to flexible formats.
Within the multinational tier, Nestle SA exemplifies scale-driven fresh soup positioning through refrigerated logistics dominance in France and the United Kingdom, while Unilever plc anchors dry soup heritage through Central European brand recognition. Among regional specialists, Baxters Food Group Ltd. occupies a heritage-positioned niche in Scotland and Northern England. The competitive dynamic between these archetypes intensifies as pouch packaging adoption collapses traditional format boundaries.
| Leading Market Players |
|---|
| Unilever plc |
| The Kraft Heinz Company |
| Campbell Soup Company |
| Nestle SA |
| Premier Foods plc |
| Baxters Food Group Ltd. |
| Conagra Brands, Inc. |
| General Mills, Inc. |
| GB Foods SA |
| Others |
Supply & Pricing Matrix
Rhine-Alpine corridor freight dynamics compress margin structures for soup manufacturers sourcing vegetable proteins from Central Europe while simultaneously enabling price differentiation between pouch-packaged premium formats and metal-can economy tiers.
Pricing Analysis
EFSA front-of-pack nutrition labeling dictates the pricing tier structure across European soup markets, separating clean-label fresh formats commanding shelf-space premiums from sodium-heavy legacy portfolios facing reformulation cost absorption. Three-tier pricing stratifies across premium organic pouch lines, standard chilled private-label offerings, and economy dry concentrate sachets. Pricing pressure intensifies in the standard tier as discounters in Germany and France replicate quality-perception parity. Foodservice operators exhibit lowest price sensitivity due to menu positioning requirements, while metropolitan retail consumers in London and Paris show highest elasticity.
Supply Chain Analysis
Vegetable feedstock supply concentrates in Poland, Spain, and the Netherlands for soup manufacturing inputs, with protein fortification materials drawing from German and French dairy processing clusters. Blast-chilling equipment and retort pouch films hinge on specialized suppliers in Italy and Germany. Tariff exposure through evolving carbon border adjustments presents structural risk for brands importing Asian-manufactured packaging substrates. Distribution runs through refrigerated logistics hubs anchored by Nestle SA's Île-de-France network and Unilever plc's Central European dry goods infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent soup manufacturers face substitution pressure from adjacent ready-meal categories and meal-kit services eroding the convenience positioning that once protected shelf-stable formats.
For Market Incumbents: Pre-empt pouch packaging obsolescence of metal can assets by accelerating line conversion investments in Poland's emerging manufacturing zones. Secure backward integration into blast-chilling capacity to defend margin structures against co-packing competition. EFSA sodium disclosure thresholds threaten Knorr's entrenched recipe heritage; reformulation R&D must outpace compliance timelines. For New Entrants and Emerging Players: Establish a beachhead in organic vegetable-based pouches targeting German and French discounter private-label supply gaps. Poland's co-packing market offers lowest barrier to production scale without captive distribution infrastructure. Direct-to-consumer subscription models bypass supermarket shelf access constraints that limit branded penetration in London and Paris metropolitan networks. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates divesting non-core soup portfolios amid ready-meal category convergence. Mid-cap Polish manufacturers with REACH-compliant export capabilities and installed pouch lines represent highest viability over the five-to-ten year horizon. Signal to monitor: Extended Producer Responsibility scheme implementation velocity reshaping packaging compliance cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Pouch Packaging Line Conversion | Retort technology investments capture premium shelf space as EFSA rules accelerate metal can displacement. |
| Blast-Chilling Capacity Expansion | Extended shelf-life without preservatives enables cross-border distribution of fresh formats from Polish manufacturing zones. |
| Clean-Label Reformulation Partnership | Potassium chloride and umami extract sourcing agreements secure sodium reduction compliance without palatability sacrifice. |
| Private-Label Supply Contracting | Discounter channel partnerships in Germany and France lock in volume commitments amid branded shelf compression. |
| Extended Producer Responsibility Pre-Compliance | Early recyclable format adoption positions manufacturers for competitive cost structures under evolving EU Green Deal mandates. |
Research Methodology
Operator-level perspectives from category buyers at French and British supermarket chains, procurement directors at Central European dry soup manufacturers, chilled logistics operators, and EFSA regulatory consultants anchored the qualitative base. Secondary validation drew from EU customs trade databases, EFSA nutrition labeling guidance documents, SEC filings of listed packaged food conglomerates, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category expenditure estimates.
Scenario-bracketing around regulatory compliance timelines and packaging transition velocities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, packaging type, ingredient category, and distribution channel. CAGRs derived from historical trajectory analysis adjusted for policy-driven inflection points. Forecast inputs incorporated blast-chilling technology diffusion rates and private-label penetration curves in metropolitan retail networks.
Stress conditions across vegetable protein input cost volatility, carbon border adjustment implementation timing, and discounter channel expansion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EFSA enforcement consistency and EU Green Deal packaging mandate adherence. Cross-checking against Circana retail measurement data and national health claims enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Tomato Puree Market
Processed Foods
Processed Cashew Market
Processed Foods
Noodles Market
Processed Foods
Processed Peanut Market
Processed Foods
Instant Cooking Food Market
Processed Foods
Broth Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
South America Processed Meat Market
Processed Foods
Apple Butter Market
Processed Foods
US Processed Pumpkin Market
Processed Foods
United States Ice Cream Market
Processed Foods
Egg White Cubes Market
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Global Dried Processed Food Market
Processed Foods
Europe Egg Powder Market
Processed Foods
Processed Mango Products Market