
 South America Processed Meat Market | 2026-2036
South America Processed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
South America Processed Meat Market Analytics
Buyer concentration among Brazilian and Argentine food service operators is rebalancing as independent restaurants and ghost kitchen networks fragment procurement volumes. JBS S.A. leverages its integrated cattle-to-retail platform to sustain margin control across fresh and processed divisions. BRF S.A. anchors its position through poultry specialization and branded retail penetration. Marfrig Global Foods S.A. competes via beef-centric processed portfolios and export-grade certification capacity.
Processed meat comprises animal proteins subjected to curing, smoking, fermentation, thermal processing, or mechanical restructuring to extend shelf life, enhance flavor, or enable portion standardization, with sodium content, water activity, and residual nitrite levels serving as critical safety parameters. Sausage and bacon segments lead volume contribution due to breakfast and quick-service ubiquity, while premium and organic quality tiers capture expanding margin pools as Brazilian retailers reposition assortments toward clean-label positioning. Distribution through supermarkets and wholesale channels still dominates value capture, though online penetration accelerates in São Paulo and Buenos Aires metropolitan zones.
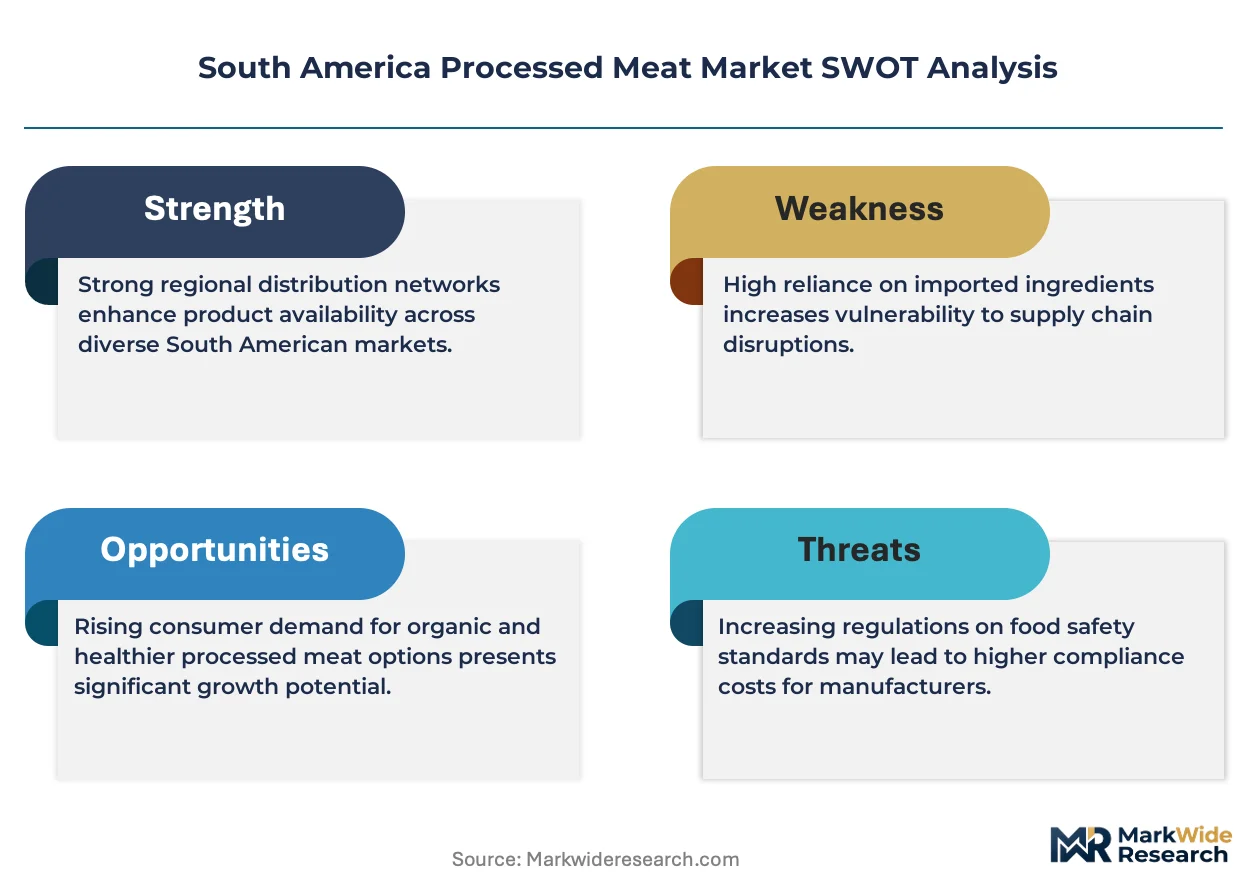
Brazil's MAPA enforces sanitary registration and HACCP compliance for all federally inspected meat processors, while ANVISA governs additive limits and nutritional labeling standards that directly shape product formulation decisions. Argentina's SENASA operates parallel inspection protocols that create cross-border certification friction for integrated South American suppliers. Stakeholders must monitor evolving Mercosur harmonization talks and shifting consumer litigation risk around processed meat health claims to calibrate portfolio and geographic exposure.
Market Dynamics
MAPA's sanitary registration overhaul is compressing cold-chain compliance timelines while fragmenting procurement volumes across Brazil's food service landscape, forcing processors to recalibrate certification capacity against dispersed buyer networks.
Growth Catalysts
- Portion-control protocols:Quick-service operators in São Paulo and Buenos Aires are standardizing pre-sliced bacon and sausage formats to reduce kitchen labor and waste.
- HACCP federal inspection:Brazil's MAPA enforcement is elevating plant certification as a competitive filter, rewarding processors with integrated traceability systems.
- Clean-label repositioning:Supermarket chains across the southeastern industrial corridor are expanding shelf space for reduced-nitrite and organic-tier processed meats.
Market Restraints
- Feed input volatility:Corn and soybean meal price swings in Argentina's Pampas region transmit directly into processor margin pressure.
- Cross-border certification friction:SENASA inspection protocols in Argentina create redundant audit burdens for integrated South American suppliers serving both markets.
- Plant-based substitution:Pea-protein and mycelium-based alternatives are capturing trial among health-conscious consumers in São Paulo's metropolitan zone.
Strategic Opportunities
- Ghost kitchen penetration:Delivery-only food preparation facilities in Buenos Aires are creating demand for single-serve processed meat formats with extended ambient stability.
- Mercosur harmonization:Pending regulatory alignment talks could collapse bilateral certification costs for processors with dual Brazil-Argentina presence.
- High-pressure processing:Cold-pasteurization technology convergence with modified-atmosphere packaging is opening clean-label shelf-stable segments without thermal degradation.
Industry Challenges
- Residual nitrite compliance:ANVISA's tightening additive limits are forcing reformulation cycles that compress product development timelines.
- Cold-chain capex intensity:Federal inspection upgrades require refrigeration infrastructure investments that strain mid-tier processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Processed Meat Market |
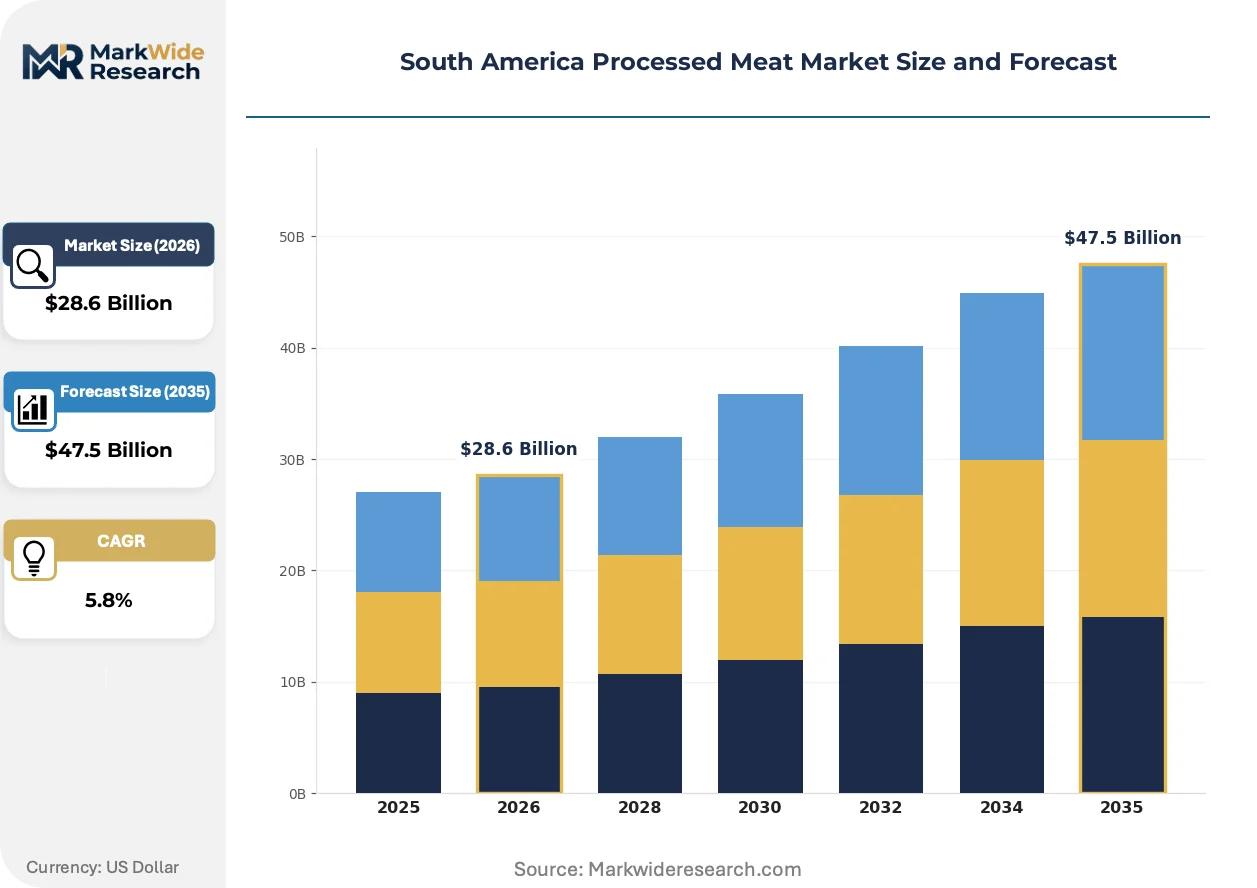
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ham, Sausage, Bacon, Salami End User: Food Service, Retail, Households, Hotels Quality Level: Premium, Standard, Value, Organic Distribution Channel: Supermarkets, Online, Convenience Stores, Wholesale |
| Companies Covered | JBS S.A., BRF S.A., Marfrig Global Foods S.A., Minerva Foods S.A., Aurora Coop, Seara Alimentos Ltda., Frigorífico Concepción S.A., Molinos Río de la Plata S.A., Quickfood S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Processed Meat Market Evolving Landscape
Technology-enabled traceability and regulatory compression are converging to reshape how processed meat moves from slaughterhouse to retail shelf across the Southern Cone.
Blockchain-enabled batch tracking is rewriting supply chain transparency standards in Brazil's federally inspected plants. JBS and BRF are piloting distributed-ledger systems that map cattle origin through retail barcode scanning. This capability is compressing recall response windows and enabling premium pricing for verified-origin product tiers.
ANVISA's updated nutritional labeling mandates are forcing front-of-pack sodium disclosure across all processed meat categories. Reformulation teams are accelerating potassium-chloride substitution trials to maintain flavor profiles under reduced-salt targets. São Paulo-based retailers are responding by carving out dedicated low-sodium planogram sections.
Consolidated food service distributors are fragmenting into specialized protein sourcing platforms serving independent restaurants. Minas Gerais ghost kitchen operators now bypass traditional broadline distributors to contract directly with certified processors for custom portion specifications. This disintermediation is most visible in São Paulo's outer-ring industrial zones where cold-storage micro-fulfillment nodes are proliferating.
South America Processed Meat Market Segmentation
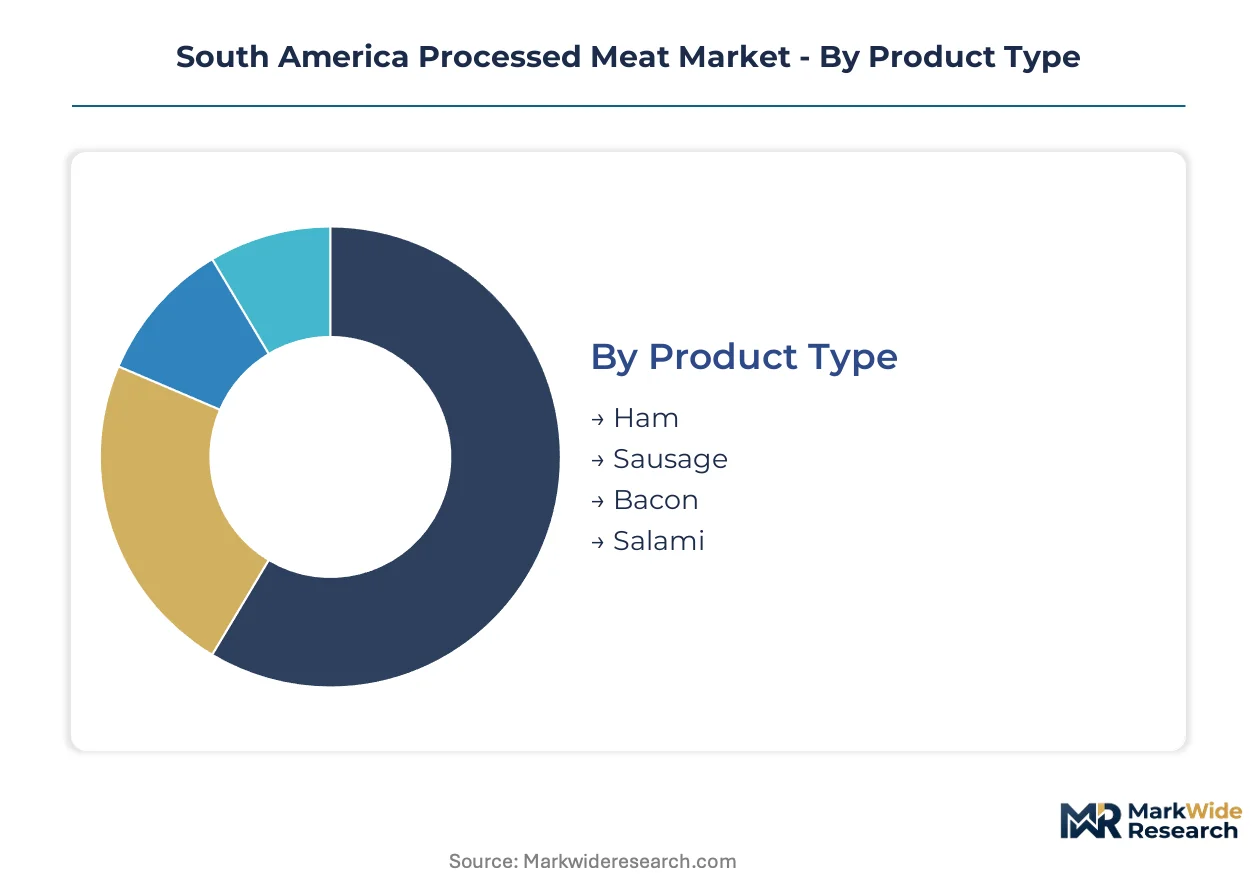
Segmentation in the South America Processed Meat Market reveals how regulatory thresholds and buyer sophistication split procurement patterns across distinct compliance tiers. Each dimension carries specific certification burdens that reshape margin structures and competitive positioning.
Product Type:
Sausage and bacon segments require MAPA's SIF federal inspection for interstate commerce, while ham and salami face additional ANVISA additive scrutiny that extends registration timelines.
- Sausage:Ground meat emulsions stuffed into natural or synthetic casings, then subjected to thermal processing or fermentation. Demand concentrates in São Paulo's quick-service operators who standardize pre-portioned breakfast links to cut kitchen labor. ANVISA's residual nitrite limits are forcing potassium-chloride substitution trials that compress reformulation cycles.
- Bacon:Cured and smoked pork belly strips, with water activity and sodium content serving as critical shelf-life parameters. Buenos Aires ghost kitchen networks are driving single-serve format adoption with extended ambient stability requirements. MAPA's HACCP enforcement elevates plant certification as a competitive filter for suppliers.
- Ham:Whole-muscle curing through brine injection or dry-salt application, with moisture-protein ratios governed by federal standards.
- Salami:Fermented and dried sausage varieties requiring controlled humidity environments and extended aging protocols.
Leading the category by volume: Sausage. Growing fastest: Bacon.
End User:
Procurement scale and specification complexity vary sharply across buyer types, with food service operators fragmenting into specialized sourcing platforms.
- Food Service:Restaurant chains, institutional caterers, and ghost kitchen operators purchasing portion-controlled formats for labor reduction. São Paulo's independent restaurants now bypass broadline distributors to contract directly with certified processors for custom specifications.
- Retail:Supermarket and hypermarket chains controlling shelf-space allocation and clean-label positioning across Brazil's southeastern industrial corridor.
- Households:Individual consumers selecting processed meats through traditional retail or accelerating online channels in metropolitan zones.
- Hotels:Hospitality operators sourcing breakfast proteins and banquet preparations with consistent quality tiers.
Highest procurement fragmentation: Food Service. Steepest channel shift: Retail toward online penetration.
Quality Level:
Price stratification aligns with certification depth, as organic and premium tiers require verified-origin traceability systems that reward integrated processors.
- Premium:Verified-origin products with blockchain-enabled batch tracking commanding shelf-space premiums in São Paulo retailers.
- Standard:Mass-market tiers meeting baseline MAPA sanitary registration without specialized additive or sourcing claims.
- Value:Price-focused segments prioritizing volume scale over extended shelf-life or clean-label positioning.
- Organic:Certified production excluding synthetic additives, with demand expanding as Brazilian retailers reposition assortments toward health-positioned offerings.
Widest margin spread: Premium versus Value. Gaining share fastest: Organic.
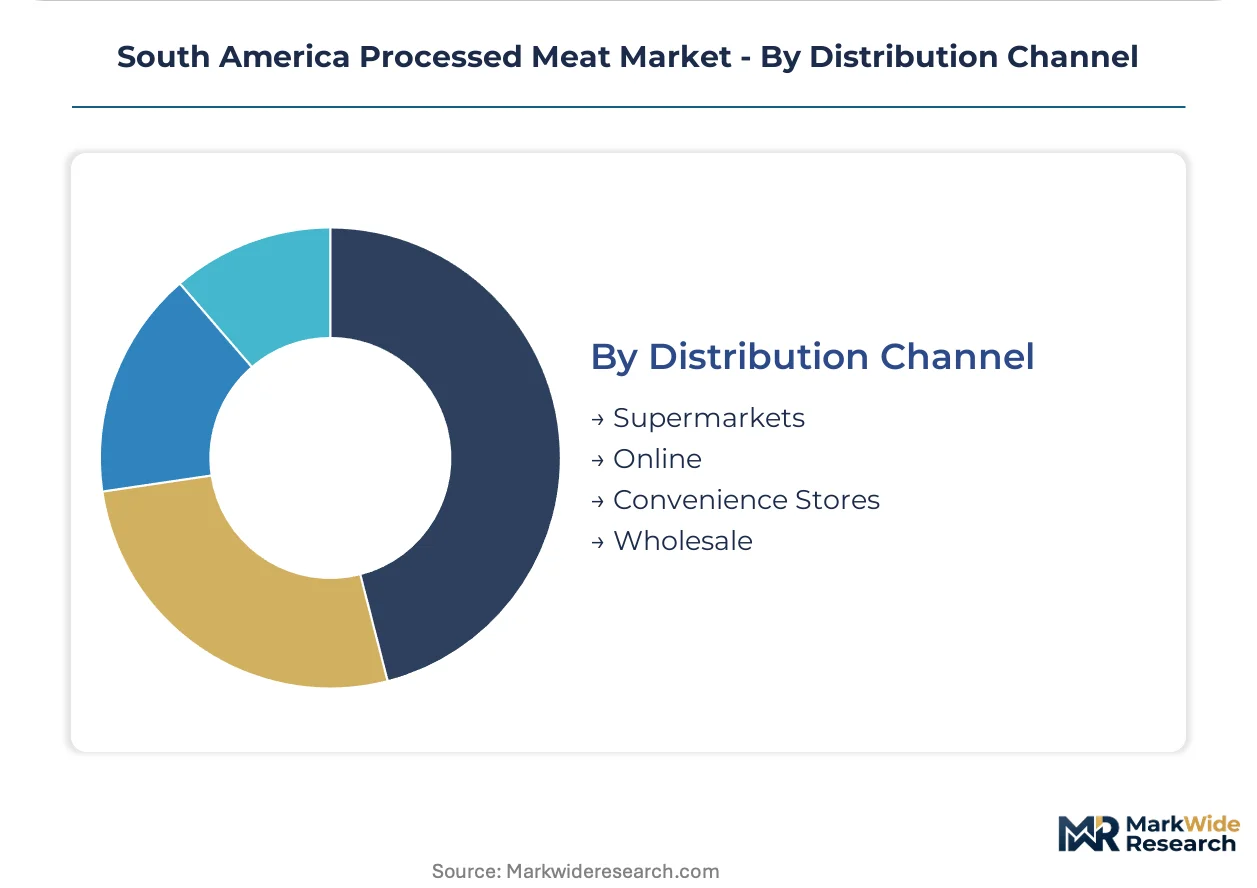
Distribution Channel:
Cold-chain infrastructure requirements and buyer concentration patterns determine channel economics, with federal inspection upgrades straining mid-tier processor balance sheets.
- Supermarkets:Dominant value capture through controlled planogram allocation, with dedicated low-sodium sections emerging in response to ANVISA labeling mandates.
- Online:Accelerating penetration in São Paulo and Buenos Aires metropolitan zones, requiring modified-atmosphere packaging for last-mile stability.
- Convenience Stores:Small-format retail prioritizing ambient-stable and single-serve processed meat formats.
- Wholesale:Traditional broadline distribution facing disintermediation as specialized protein platforms fragment procurement volumes.
Current volume leader: Supermarkets. Channel expanding most quickly: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's Pampas region anchors feed grain supply for the Southern Cone protein complex. Corn and soybean meal price swings transmit directly into processor margin pressure across Brazil, Argentina, Chile, and Uruguay. Cold-chain infrastructure gaps in secondary cities create distribution friction that concentrates value capture in coastal metropolitan zones.
Brazil
São Paulo's quick-service operators standardize pre-sliced bacon and sausage formats to cut kitchen labor and waste. MAPA enforces sanitary registration and HACCP compliance for all federally inspected meat processors, elevating plant certification as a competitive filter. The southeastern industrial corridor spanning São Paulo and Minas Gerais concentrates demand as ghost kitchen networks fragment procurement volumes across certified suppliers.
Argentina
Buenos Aires ghost kitchen operators drive single-serve processed meat formats with extended ambient stability requirements. SENASA operates inspection protocols that create redundant audit burdens for integrated suppliers serving both Argentine and Brazilian markets. The Pampas grain belt feeds processor operations while cross-border certification friction limits operational scale for mid-tier players.
Chile
Santiago metropolitan retailers expand shelf space for reduced-nitrite and organic-tier processed meats as clean-label positioning accelerates. The national agricultural service enforces residue monitoring programs that shape import acceptance criteria for Brazilian and Argentine suppliers. Cold-storage micro-fulfillment nodes proliferate in outer-ring industrial zones to serve delivery-only food preparation facilities.
Uruguay
Montevideo-based processors leverage Mercosur trade access to supply Brazilian and Argentine retail chains with grass-fed beef derivatives. The national meat institute governs export-grade certification that enables premium positioning in neighboring markets. Coastal processing clusters face feed input dependency on Argentine grain imports that compress margins during commodity price spikes.
Colombia
Bogotá food service distributors fragment into specialized protein sourcing platforms serving independent restaurants and institutional caterers. The national food and drug surveillance institute governs additive limits that extend product registration timelines for imported processed meats. Andean cold-chain infrastructure investments strain mid-tier processor balance sheets while concentrating value in capital-region distribution hubs.
South America Processed Meat Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-label and plant-adjacent positioning. The market structures around three maturity tiers: integrated cattle-to-retail platforms sustaining margin control, poultry-specialized processors anchoring branded retail penetration, and beef-centric portfolios competing via export-grade certification capacity. Strategic moves concentrate on backward integration into feed operations and geographic expansion through Mercosur trade access.
Within the integrated platform tier, JBS S.A. and BRF S.A. exemplify divergent specialization strategies—one spanning cattle and processed divisions, the other anchoring poultry dominance. Marfrig Global Foods S.A. occupies a position emphasizing beef-centric processed portfolios. These three S.A.-structured entities represent distinct archetypes: diversified protein integration, species-specific vertical control, and export-certification scale.
| Leading Market Players |
|---|
| JBS S.A. |
| BRF S.A. |
| Marfrig Global Foods S.A. |
| Minerva Foods S.A. |
| Aurora Coop |
| Seara Alimentos Ltda. |
| Frigorífico Concepción S.A. |
| Molinos Río de la Plata S.A. |
| Quickfood S.A. |
| Others |
Value Network & Pricing Analysis
Backward integration into feed operations and captive cattle supply anchors both cost position and pricing power for integrated processors across Brazil's southeastern corridor. JBS S.A. and Marfrig Global Foods S.A. leverage in-house production of corn-fed and grass-fed protein inputs to buffer margin erosion when Argentine Pampas grain prices spike.
Pricing Analysis
Warranty-like certification bundling separates premium-tier processors from unbundled standard offerings. Three-tier pricing structure across premium, standard, and economy levels tracks MAPA federal inspection grade and ANVISA additive compliance depth. Cost compression in the value tier intensifies because feed input volatility transmits directly from Argentina's Pampas region. Ghost kitchen operators in São Paulo show highest price sensitivity; retailers in the organic tier show least.
Supply Chain Analysis
Workforce availability constraints in São Paulo and Minas Gerais processing clusters elevate automation capex for mid-tier players. Supply concentrates in Brazil, Argentina, and Uruguay, with Brazilian plants drawing from Argentine grain imports and domestic cattle herds. Single-source vulnerability runs through cross-border feed dependency. Distribution runs through federally inspected cold-chain nodes to supermarket and food service buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive supply of feed inputs and certified processing capacity determines who captures margin across volatile commodity cycles.
For Market Incumbents: Anticipate plant-based substitution pressure by accelerating high-pressure processing deployment for clean-label shelf-stable formats. Deepen backward integration into Minas Gerais feedlot operations to reduce Argentine grain import exposure. Prioritize blockchain-enabled batch tracking investment to defend premium-tier positioning against emerging traceability-focused entrants. For New Entrants and Emerging Players: Launch via direct-to-ghost-kitchen distribution in Buenos Aires and São Paulo outer-ring zones where traditional broadline distributors have retreated. Target single-serve ambient-stable formats for delivery-only operators as the most penetrable white space. Pursue organic certification pathways to capture shelf-space expansion in southeastern Brazilian retailers repositioning toward health-positioned assortments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated protein platforms seeking geographic expansion through Mercosur trade access. Long-term viability hinges on processors with dual Brazil-Argentina certification capacity and cold-chain infrastructure that meets MAPA's compressed compliance timelines. Monitor ANVISA additive limit announcements as the critical inflection signal for reformulation cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Operations | Captive corn and soybean supply buffers Argentine Pampas price volatility for integrated processors. |
| Blockchain-Enabled Traceability Deployment | JBS and BRF pilot distributed-ledger systems to compress recall windows and enable premium pricing tiers. |
| High-Pressure Processing Adoption | Cold-pasteurization convergence with modified-atmosphere packaging opens clean-label shelf-stable segments. |
| Ghost Kitchen Direct Distribution | Minas Gerais operators bypass broadline distributors to contract directly with certified processors. |
| Mercosur Harmonization Lobbying | Pending regulatory alignment talks could collapse bilateral certification costs for dual-presence suppliers. |
Research Methodology
Independent corroboration across processor procurement directors, MAPA inspection officials, and ANVISA regulatory affairs leads underwrites the qualitative findings. Secondary validation draws from MAPA sanitary registration databases, ANVISA additive limit filings, and trade flow records through Brazil's southeastern ports. Bottom-up volume estimates from plant-level capacity triangulate against top-down expenditure patterns from food service distributors.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span product type, quality tier, end-use sector, and distribution channel. CAGRs derive from regression against feed input cost indices and regulatory compliance cost trajectories. Forecast inputs include MAPA inspection capacity expansion schedules and ANVISA reformulation mandate timelines.
Feed price spikes, regulatory harmonization delays, and plant-based substitution acceleration are the dominant revision risks. Forecasts reflect assumptions about cold-chain infrastructure investment pacing and Mercosur negotiation progress. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Ready to Serve Prefabricated Dishes Market
Processed Foods
Block Margarine Market
Processed Foods
Instant Curry Market
Processed Foods
United States Food Spread Market
Processed Foods
Low Fat Vegetable Soups Market
Processed Foods
Fruit Processing Market
Processed Foods
Processed Egg Market
Processed Foods
Global Pasta Market
Processed Foods
Processed Cashew Market
Processed Foods
Artisanal Ice Cream Market
Processed Foods
Egg Powder Market
Processed Foods
Chocolate Filling Market
Processed Foods
Low-Fat Desserts to Buy Market
Processed Foods
Processed Fruit Bases Market
Processed Foods
Fermented Food and Drinks Market
Processed Foods
United States Processed Meat Market