
 Engineering Ceramics Market | 2026-2036
Engineering Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Engineering Ceramics Market Analysis
The EU Green Deal is rebalancing procurement priorities across European industrial ceramics buyers toward low-carbon manufacturing certifications. Morgan Advanced Materials leverages its vertical integration in thermal ceramics to sustain pricing power across aerospace supply chains. CoorsTek, Inc. anchors North American production of high-purity alumina components for semiconductor fabrication equipment. Kyocera Corporation dominates electronic ceramic substrates through captive material science capabilities in Japan.
Engineering ceramics are inorganic, non-metallic materials engineered for extreme thermal, mechanical, and chemical performance, typically sintered at temperatures exceeding 1600°C to achieve full densification and crystalline stability. Their primary industrial purpose is to replace metals in environments where corrosion resistance, electrical insulation, or thermal shock tolerance exceeds metallic limits. Alumina and silicon carbide occupy the largest volume positions due to mature supply chains and cost-effective processing routes into substrates and wear components. Silicon nitride is expanding fastest in bearing and turbine applications where fracture toughness requirements exceed alumina capabilities. Zirconia commands premium positioning in biomedical implants and precision oxygen sensors where phase transformation toughening delivers unmatched reliability.
REACH compliance in Europe, EPA emissions enforcement in the United States, and China's GB standards on industrial material purity collectively shape product formulation, testing protocols, and market access requirements for engineering ceramics manufacturers. FDA device regulations and EMA medical device directives further constrain biomedical-grade zirconia and hydroxyapatite formulations, creating certification moats around qualified suppliers. Stakeholders must monitor evolving carbon border adjustment mechanisms and regional critical mineral policies to anticipate raw material cost shifts and qualification timeline extensions.
Market Dynamics
Ceramic matrix composite adoption in aerospace turbine thermal barriers is compressing qualification timelines and forcing suppliers to reconfigure sintering capacity toward fiber-reinforced architectures rather than monolithic legacy grades.
Growth Catalysts
- EPA emissions enforcement:Stricter tailpipe standards accelerate ceramic catalyst substrate deployment across automotive exhaust systems, with OEMs specifying higher cell density cordierite formulations.
- Semiconductor fabrication equipment:Precision engineering clusters in Germany drive specialty alumina and silicon carbide procurement for wafer handling components and chamber liners.
- Sintering automation:Continuous furnace technology is displacing batch processing in high-volume alumina substrate manufacturing, reducing energy intensity and lot-to-lot variability.
Market Restraints
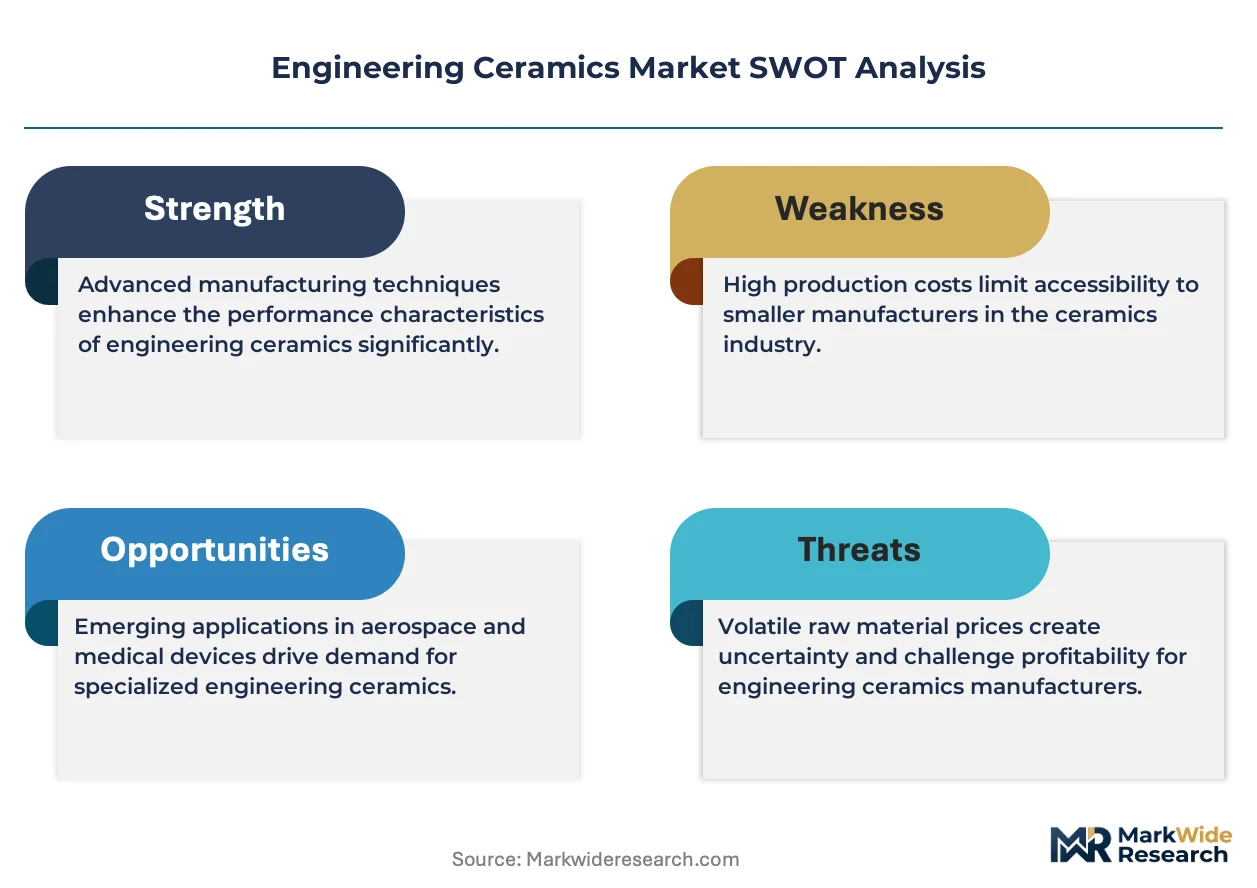
- Raw material concentration:High-purity alumina supply concentrates in bauxite-refining corridors vulnerable to export licensing shifts, creating input cost volatility for substrate manufacturers.
- Energy intensity:Sintering temperatures exceeding 1600°C require natural gas or electric arc furnaces with limited geographic availability of qualified utility infrastructure.
- Technical substitution:Advanced metallic superalloys with thermal barrier coatings compete for turbine blade applications where ceramic matrix composites face qualification timeline compression.
Strategic Opportunities
- India industrialization:PLI scheme incentives for semiconductor and defense manufacturing create qualified demand for engineered ceramic components previously imported from Japan and Germany.
- EU Green Deal carbon border adjustments:Low-carbon manufacturing certifications are rebalancing procurement priorities toward European suppliers with verified Scope 3 emissions data.
- Additive manufacturing convergence:Binder jetting of silicon carbide is enabling near-net-shape turbine vanes that reduce post-sintering machining requirements and material waste.
Industry Challenges
- Materials science talent scarcity:Sintering process engineers with ceramic matrix composite expertise command premium compensation and limited geographic mobility.
- Biomedical certification timelines:FDA device regulations and EMA medical device directives extend qualification periods for zirconia implant grades to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineering Ceramics Market |
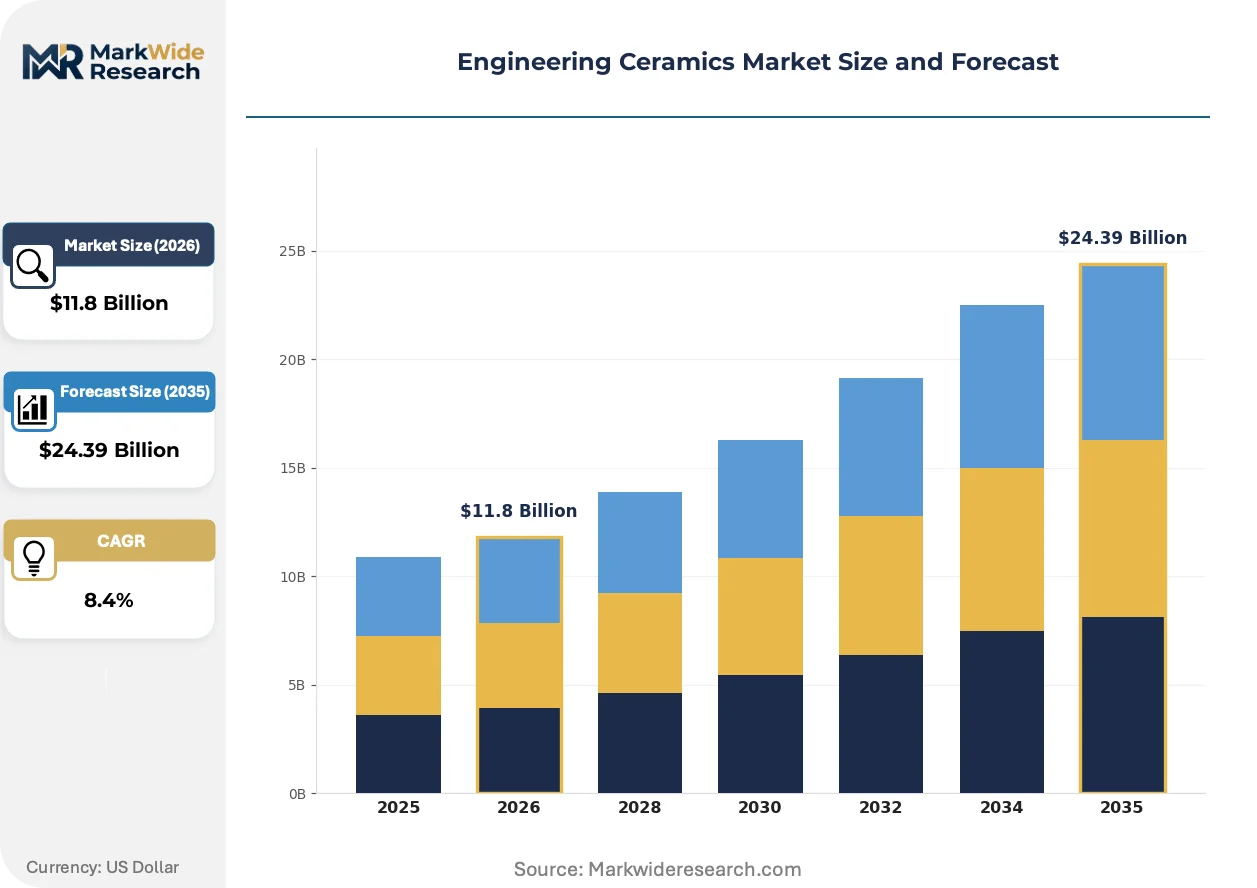
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Zirconia, Silicon Nitride, Silicon Carbide Application: Aerospace, Electronics, Biomedical, Automotive End User: Manufacturers, Research Institutions, Aerospace Companies, Medical Facilities Form: Powder, Coatings, Components, Tiles |
| Companies Covered | Morgan Advanced Materials, Saint-Gobain Ceramic Materials, CoorsTek, Inc., Rauschert Group, NGK Insulators, Kyocera Corporation, 3M Advanced Materials, Corning Incorporated, CeramTec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineering Ceramics Market Emerging Trajectories
Processing technology convergence and regulatory carbon accounting are compressing traditional supply chain configurations while opening qualification pathways for novel ceramic architectures.
Silicon nitride bearing technology delivers fracture toughness exceeding alumina capabilities for high-speed spindle applications. Machine tool OEMs in Japan and Germany are specifying silicon nitride hybrid bearings for 40,000+ RPM machining centers. This material substitution is converging with predictive maintenance sensor integration to enable condition-based replacement rather than scheduled overhaul intervals.
REACH compliance in Europe mandates full substance disclosure across ceramic precursor supply chains, including sintering aids and dopant chemistries. Formulation transparency requirements are forcing raw material suppliers to restructure technical data packages and third-party testing protocols. Biomedical-grade zirconia producers face the steepest documentation burden under EMA medical device directives.
Consolidated procurement by aerospace tier-one suppliers is displacing fragmented spot purchasing for ceramic matrix composite preforms. Long-term offtake agreements with minimum volume commitments now dominate thermal barrier component sourcing. This contracting model shift is most visible in Germany and the United States, where turbine manufacturers bundle ceramic procurement with adjacent superalloy casting programs.
Engineering Ceramics Market Segmentation
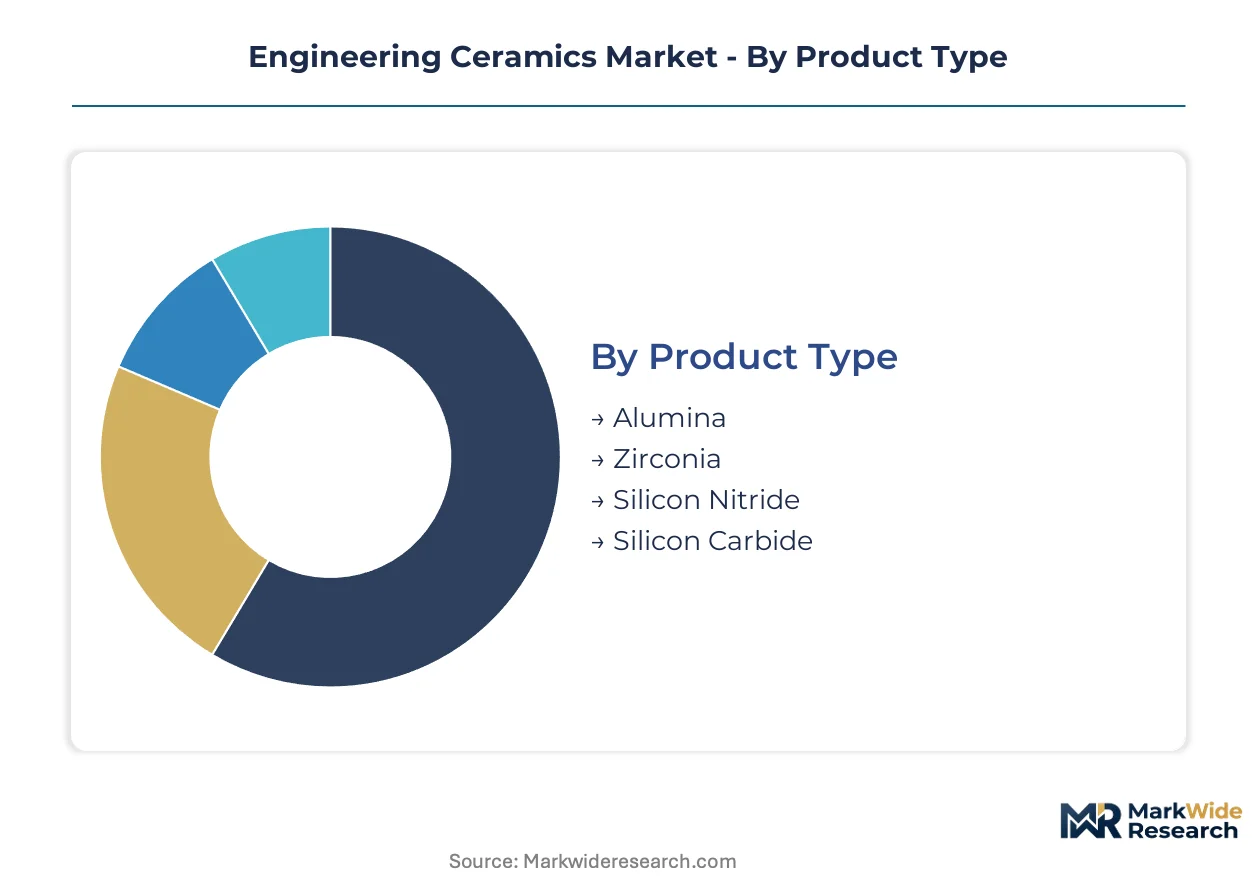
Engineering ceramics segmentation reveals how certification burdens, thermal performance thresholds, and end-use reliability requirements fragment procurement specifications across industrial buyers. Material selection directly determines which regulatory pathways manufacturers must navigate, from FDA device clearances to REACH substance disclosures.
Product Type:
REACH substance disclosure requirements in Europe and FDA device regulations in the United States impose divergent testing protocols across ceramic chemistries, with biomedical grades facing the steepest documentation burden.
- Alumina:High-purity aluminum oxide sintered above 1600°C delivers cost-effective thermal stability and electrical insulation. Precision engineering clusters in Germany specify alumina substrates for semiconductor wafer handling equipment, with procurement concentrating where continuous furnace automation reduces lot-to-lot variability.
- Zirconia:Phase transformation toughening enables fracture resistance unmatched in oxide ceramics. Biomedical implant manufacturers in the United States and Europe source yttria-stabilized grades under FDA and EMA device directives, with qualification timelines extending 18-24 months for permanent implant applications.
- Silicon Nitride:Japanese and German machine tool OEMs specify hybrid bearings for 40,000+ RPM spindles where fracture toughness exceeds alumina limits.
- Silicon Carbide:Extreme thermal shock tolerance positions this material for aerospace turbine thermal barriers and automotive exhaust catalyst substrates.
Leading the category by volume: Alumina. Growing fastest: Silicon nitride in bearing and turbine applications.
Application:
End-use thermal environments and regulatory exposure determine margin structures, with aerospace and biomedical commanding premium pricing over automotive and electronics.
- Aerospace:Ceramic matrix composite thermal barriers in turbine engines face compressed qualification timelines as manufacturers shift from monolithic legacy grades to fiber-reinforced architectures. Long-term offtake agreements with minimum volume commitments now dominate sourcing from tier-one suppliers in Germany and the United States.
- Electronics:Kyocera Corporation's captive material science capabilities anchor substrate production in Japan, with alumina and silicon carbide procurement concentrating for wafer handling components and chamber liners.
- Biomedical:EMA medical device directives and FDA regulations constrain zirconia and hydroxyapatite formulations, creating certification moats around qualified suppliers.
- Automotive:EPA emissions enforcement accelerates ceramic catalyst substrate deployment across exhaust systems, with OEMs specifying higher cell density cordierite formulations.
Volume concentration: Automotive catalyst substrates. Steepest expansion trajectory: Aerospace thermal barrier components.
End User:
Procurement sophistication varies sharply, with aerospace companies and medical facilities demanding full supply chain transparency while manufacturers prioritize cost stability.
- Manufacturers:Industrial machinery producers in Germany's Stuttgart and Munich clusters drive specialty ceramic procurement for precision engineering applications, with EU Green Deal carbon border adjustments rebalancing priorities toward suppliers with verified Scope 3 emissions data.
- Research Institutions:Additive manufacturing convergence in binder jetting of silicon carbide originates from university-industry partnerships developing near-net-shape turbine vanes.
- Aerospace Companies:Consolidated procurement by tier-one suppliers displaces fragmented spot purchasing for ceramic matrix composite preforms.
- Medical Facilities:Implant manufacturers face extended qualification periods under FDA and EMA directives, with documentation burden falling heaviest on biomedical-grade zirconia producers.
Dominant procurement volume: Manufacturers. Fastest qualification timeline compression: Aerospace companies bundling ceramic procurement with superalloy casting programs.
Form:
Processing technology and post-sintering machining requirements create distinct cost structures across delivery formats.
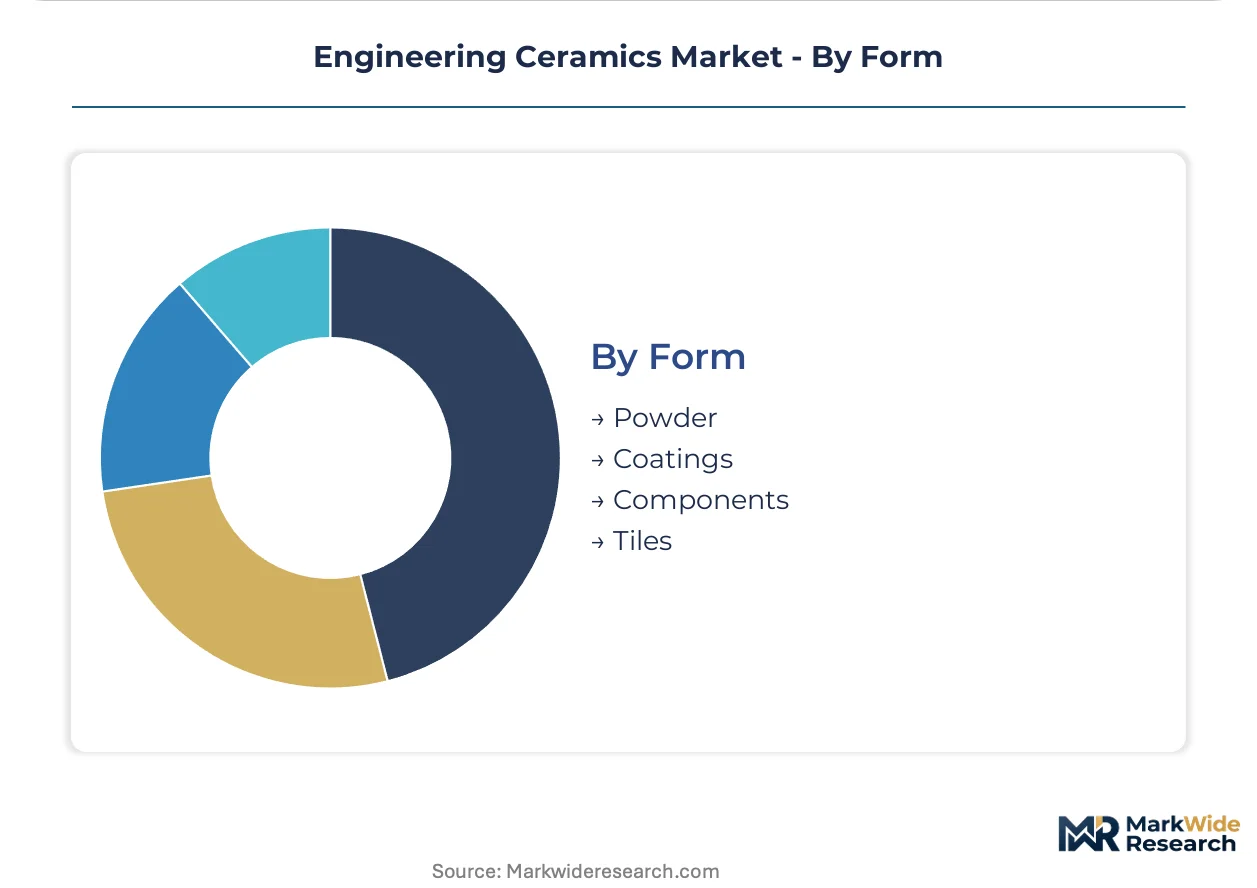
- Powder:High-purity alumina powder supply concentrates in bauxite-refining corridors vulnerable to export licensing shifts, creating input cost volatility for substrate manufacturers in Germany and Japan.
- Coatings:Thermal barrier coatings compete with ceramic matrix composites for turbine blade applications where metallic superalloys face technical substitution pressure.
- Components:Near-net-shape silicon carbide vanes from binder jetting additive manufacturing reduce post-sintering machining requirements and material waste.
- Tiles:Continuous furnace technology in high-volume alumina tile manufacturing reduces energy intensity compared to batch processing routes.
Highest volume throughput: Powder for substrate manufacturing. Fastest technology shift: Components from additive manufacturing convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart and Munich anchor European precision engineering demand for specialty ceramics, while aerospace clusters in the United States and Japan drive thermal barrier procurement. Regulatory carbon accounting and semiconductor fabrication expansion are redistributing procurement priorities across three continents.
Germany
Precision engineering clusters around Stuttgart and Munich drive specialty alumina and silicon carbide procurement for semiconductor fabrication equipment and industrial machinery. EU Green Deal carbon border adjustments rebalancing procurement priorities toward suppliers with verified Scope 3 emissions data. REACH compliance mandates full substance disclosure across ceramic precursor supply chains, forcing raw material suppliers to restructure technical data packages.
United States
EPA emissions enforcement accelerates ceramic catalyst substrate deployment across automotive exhaust systems, with OEMs specifying higher cell density cordierite formulations. Aerospace tier-one suppliers in the Southeast and Pacific Northwest consolidate procurement through long-term offtake agreements with minimum volume commitments. FDA device regulations constrain biomedical-grade zirconia formulations, creating certification moats around qualified suppliers.
Japan
Kyocera Corporation's captive material science capabilities anchor electronic ceramic substrate production, with machine tool OEMs specifying silicon nitride hybrid bearings for 40,000+ RPM machining centers. METI industrial policy supports domestic sintering automation and continuous furnace technology adoption. Nagoya and Osaka industrial corridors concentrate precision ceramic component manufacturing for export markets.
China
GB standards on industrial material purity shape product formulation and testing protocols for domestic and export-oriented manufacturers. Dual carbon goals and provincial emissions targets are compressing sintering capacity expansion timelines in traditional ceramic production zones. Yangtze River Delta clusters are pivoting toward high-purity alumina substrates for semiconductor fabrication equipment.
India
PLI scheme incentives for semiconductor and defense manufacturing create qualified demand for engineered ceramic components previously imported from Japan and Germany. Karnataka and Tamil Nadu industrial corridors attract sintering capacity investments targeting domestic aerospace and electronics supply chains. BIS standards adoption is accelerating qualification timelines for imported ceramic matrix composite preforms.
Engineering Ceramics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and application-complexity dimensions. The vendor base organizes into three tiers: vertically integrated material science conglomerates with captive sintering capacity, mid-scale specialists focused on single ceramic chemistries, and regional fabricators serving spot-market demand. Consolidated procurement by aerospace and automotive OEMs is compressing the middle tier through long-term offtake requirements. Strategic moves center on backward integration into high-purity powder supply and additive manufacturing technology licensing.
Among European material science conglomerates, Morgan Advanced Materials and CeramTec GmbH exemplify the vertically integrated archetype with in-house thermal ceramics production. CoorsTek, Inc. anchors North American positioning in high-purity alumina components. Kyocera Corporation represents the captive electronics-focused model dominant in Japanese substrate markets.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Saint-Gobain Ceramic Materials |
| CoorsTek, Inc. |
| Rauschert Group |
| NGK Insulators |
| Kyocera Corporation |
| 3M Advanced Materials |
| Corning Incorporated |
| CeramTec GmbH |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in Germany and Japan anchor supply discipline through multi-generational capital allocation patience, insulating premium-grade alumina and silicon nitride pricing from quarterly earnings pressure while spot-market powder traders absorb volatility.
Pricing Analysis
Yield-guarantee contracts dominate aerospace thermal barrier procurement, with ceramic matrix composite preforms priced against turbine engine uptime performance rather than per-kilogram metrics. Three-tier pricing structure across biomedical implant, semiconductor fabrication, and industrial machinery tiers separates FDA-certified zirconia from standard alumina substrates. Cost compression in automotive catalyst substrates intensifies as EPA enforcement drives volume scale. Medical facilities exhibit lowest price sensitivity due to 18-24 month qualification lock-in, while automotive OEMs negotiate aggressively on cordierite cell density specifications.
Supply Chain Analysis
Direct-to-OEM channels handle aerospace and semiconductor buyer demand, bypassing distributor markups for ceramic matrix composite preforms and high-purity alumina substrates. Production concentrates in Germany, Japan, and China, with bauxite-refining corridors in Australia and Guinea feeding alumina powder dependencies. Single-source vulnerability runs through high-purity precursor supply qualified for FDA and EMA biomedical grades. Distribution runs through long-term offtake agreements with minimum volume commitments, displacing fragmented spot purchasing for thermal barrier components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players pursue backward integration into high-purity alumina powder supply to escape bauxite-refining corridor volatility.
For Market Incumbents: Anchor pricing power through captive sintering capacity expansion in Germany and Japan, where precision engineering clusters concentrate procurement. Defend against additive manufacturing substitution by qualifying binder-jetted silicon carbide architectures ahead of turbine OEM specification shifts. Prioritize EMA and FDA certification moat deepening for biomedical-grade zirconia to extend 18-24 month qualification barriers. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian aerospace and defense procurement creates entry space previously occupied by Japanese and German imports. Target PLI scheme beneficiaries in Karnataka and Tamil Nadu with localized sintering capacity for ceramic matrix composite preforms. Pursue university-industry partnerships for binder jetting technology licensing to bypass capital-intensive continuous furnace infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale specialists with single-chemistry focus in European precision engineering corridors. Five-to-ten year viability hinges on carbon border adjustment mechanism positioning under EU Green Deal implementation. Monitor BIS standards adoption acceleration in India as inflection signal for import substitution opportunity scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Powder Supply | Morgan Advanced Materials and CeramTec GmbH secure alumina precursor cost stability against bauxite export licensing shifts. |
| Continuous Furnace Automation Deployment | Kyocera Corporation and NGK Insulators reduce energy intensity and lot-to-lot variability in high-volume substrate manufacturing. |
| Additive Manufacturing Technology Licensing | University-industry partnerships in Germany and Japan enable near-net-shape silicon carbide turbine vane production. |
| Long-term Offtake Agreement Structuring | Aerospace tier-one suppliers in the United States and Germany consolidate procurement with minimum volume commitments. |
| Biomedical Certification Investment | Qualified suppliers build FDA and EMA device directive moats around yttria-stabilized zirconia implant grades. |
Methodological Framework
Independent corroboration across sintering process engineers, aerospace procurement directors, and semiconductor fabrication equipment specialists underwrites the qualitative findings. Primary interviews with ceramic matrix composite program managers, thermal ceramics R&D leads, and medical device regulatory affairs officers combined with secondary validation from EPA enforcement disclosures, EMA medical device directive filings, and METI industrial policy documentation. Bottom-up triangulation across powder supplier production estimates and top-down reconciliation against end-use equipment shipment data anchored volume projections.
Rate-of-change decomposition across material type, application thermal environment, and end-user procurement sophistication dimensions modeled expansion trajectories throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against macro industrial production indices. Industry-specific forecast inputs incorporated continuous furnace technology adoption curves and carbon border adjustment mechanism implementation timelines.
Inputs from aerospace tier-one supplier procurement databases and semiconductor fabrication equipment OEMs were available through the study window; gaps in biomedical implant manufacturer volume disclosures introduce uncertainty bands around zirconia grade projections. Practitioners should monitor PLI scheme disbursement acceleration in India and REACH substance disclosure enforcement tightening in Europe for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Zirconium Dioxide Market
Ceramics
Hot-Pressed Aluminum Titanate Ceramics Market
Ceramics
Titanium Carbide Market
Ceramics
Cement Castables Market
Ceramics
Ceramic Kilns Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Wollastonite Market
Ceramics
Glazed Bricks Market
Ceramics
North America Barium Carbonate Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Low Temperature Co-Fired Ceramic (LTCC) Market
Ceramics
Fly Ash and Ceramic Microsphere Market
Ceramics
Lithium Zirconate Market
Ceramics
Solid-Ion Conductors Market