
 Europe Data Center Cooling Market | 2026-2036
Europe Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Data Center Cooling Market Insights
Software-defined thermal management is broadening what data center operators purchase alongside hardware. Schneider Electric SE leverages its EcoStruxure platform to bundle predictive analytics with physical infrastructure. Vertiv Group Corp. anchors its European position through service contracts that integrate thermal optimization with power distribution. Stulz GmbH specializes in custom air-handling configurations for colocation facilities across the DACH region.
Europe data center cooling encompasses engineered systems that regulate temperature, humidity, and airflow within mission-critical IT environments using refrigerant-based, water-based, or dielectric-fluid architectures operating at precision tolerances of ±1°C. These systems prevent thermal throttling of processors and protect uptime for cloud, telecom, and enterprise workloads. Liquid cooling captures margin pools as AI servers exceed 500W per chip and air-cooled designs hit physical limits. Colocation providers represent the fastest-growing end-user channel as wholesale leasing absorbs hyperscale expansion. Automated control systems command premium pricing by integrating real-time sensor networks with machine-learning-driven setpoint optimization.
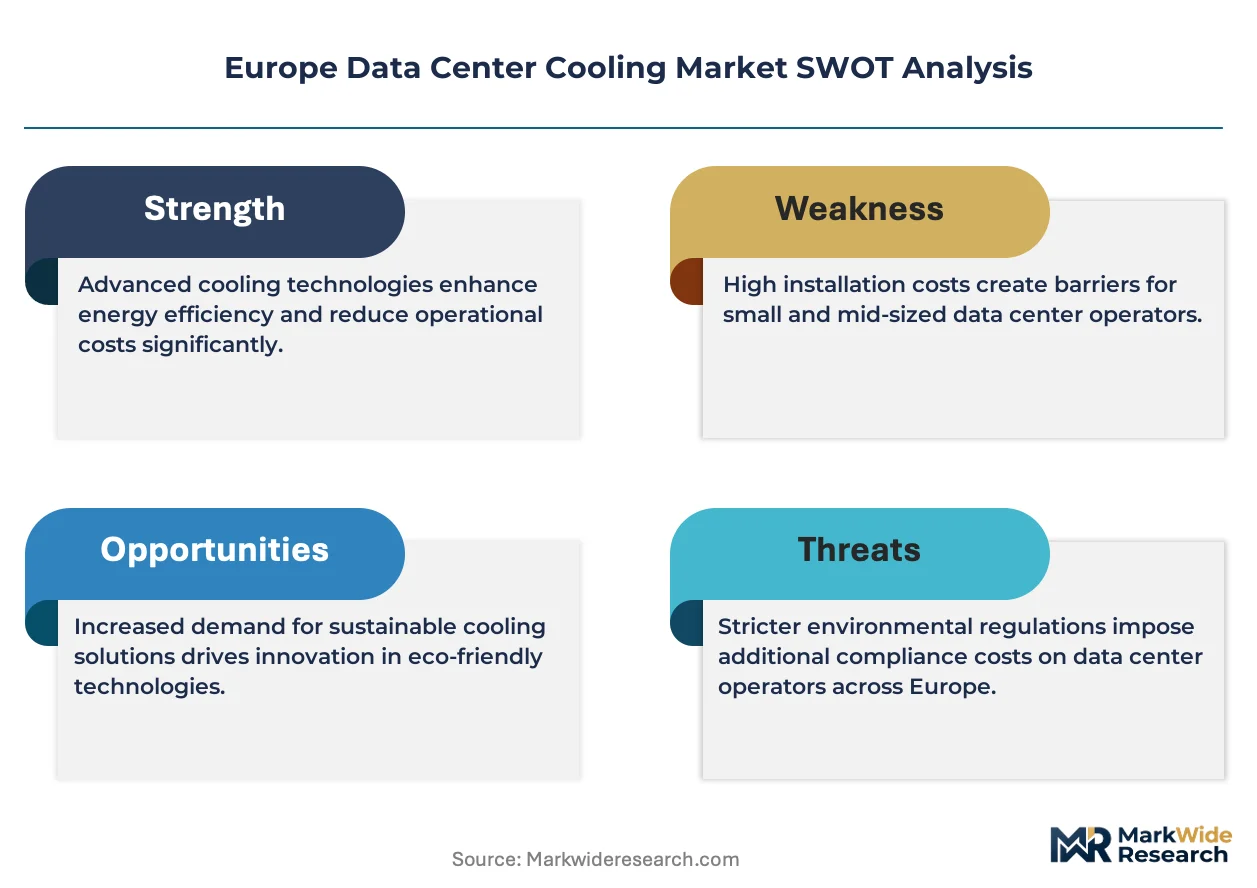
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants with GWP above 150 in new stationary cooling equipment, pushing vendors toward natural refrigerants and two-phase immersion fluids. ECHA REACH compliance adds substance-testing burdens for dielectric coolants entering the European market. CE marking under the MDR framework for embedded monitoring hardware affects control-system certification pathways. Stakeholders must track how the EU AI Act's transparency requirements intersect with thermal telemetry data governance in autonomous cooling platforms.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant choice sets while AI training clusters above 500W per chip render air-cooled designs thermally obsolete, forcing a synchronous overhaul of cooling architectures and supplier qualifications across the continent.
Growth Catalysts
- AI Training Cluster Density:Hyperscale operators in Frankfurt and Amsterdam are specifying direct-to-chip liquid cooling for GPU racks exceeding 100kW per enclosure, creating specification pull-through for precision flow-control systems.
- EU Green Deal Decarbonization Mandates:The framework's 2030 efficiency targets are requiring PUE below 1.2 for new facilities, disqualifying conventional chiller-based designs from public procurement and green bond financing.
- Dielectric Fluid Innovation:Engineered fluorocarbon substitutes and synthetic single-phase fluids are opening two-phase immersion retrofits for legacy raised-floor facilities without structural reinforcement.
Market Restraints
- Refrigerant Supply Concentration:Natural refrigerant production for ammonia and CO2 systems concentrates in German and Austrian chemical suppliers, creating price volatility when allocation tightens.
- Dielectric Fluid REACH Burden:ECHA substance registration and toxicity testing timelines extend 18-24 months for new immersion coolants, blocking rapid formulation iteration.
- Air-Cooled Residual Entrenchment:Enterprise colocation contracts signed before 2022 often specify air-handling unit refresh cycles, delaying liquid cooling conversion until 2027-2028 lease events.
Strategic Opportunities
- Poland and Nordic Edge Expansion:Warsaw and Oslo are attracting hyperscale backup regions where free-air cooling availability reduces mechanical refrigeration capex by half versus Frankfurt baselines.
- CSRD Thermal Telemetry Integration:The Corporate Sustainability Reporting Directive's scope 2 disclosure granularity is creating demand for cooling-system-level carbon accounting software bundled with hardware.
- Immersion-as-a-Service Models:Fluid vendors are piloting dielectric coolant leasing with reclamation guarantees, converting capex-heavy tank retrofits into operational expenditure for mid-size colocation operators.
Industry Challenges
- Thermal-Fluid Engineering Talent Scarcity:Two-phase heat transfer and dielectric chemistry expertise resides in aerospace and semiconductor equipment sectors, requiring cross-industry recruitment or 12-18 month training pipelines.
- Legacy BMS Integration Friction:Proprietary cooling control protocols from 2015-2019 facilities resist API standardization, forcing middleware development for unified thermal optimization.
- CE-MDR Hardware Recertification:Embedded sensor networks and edge-computing thermal controllers face reclassification as medical device components when deployed in healthcare-adjacent data centers, extending approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Data Center Cooling Market |
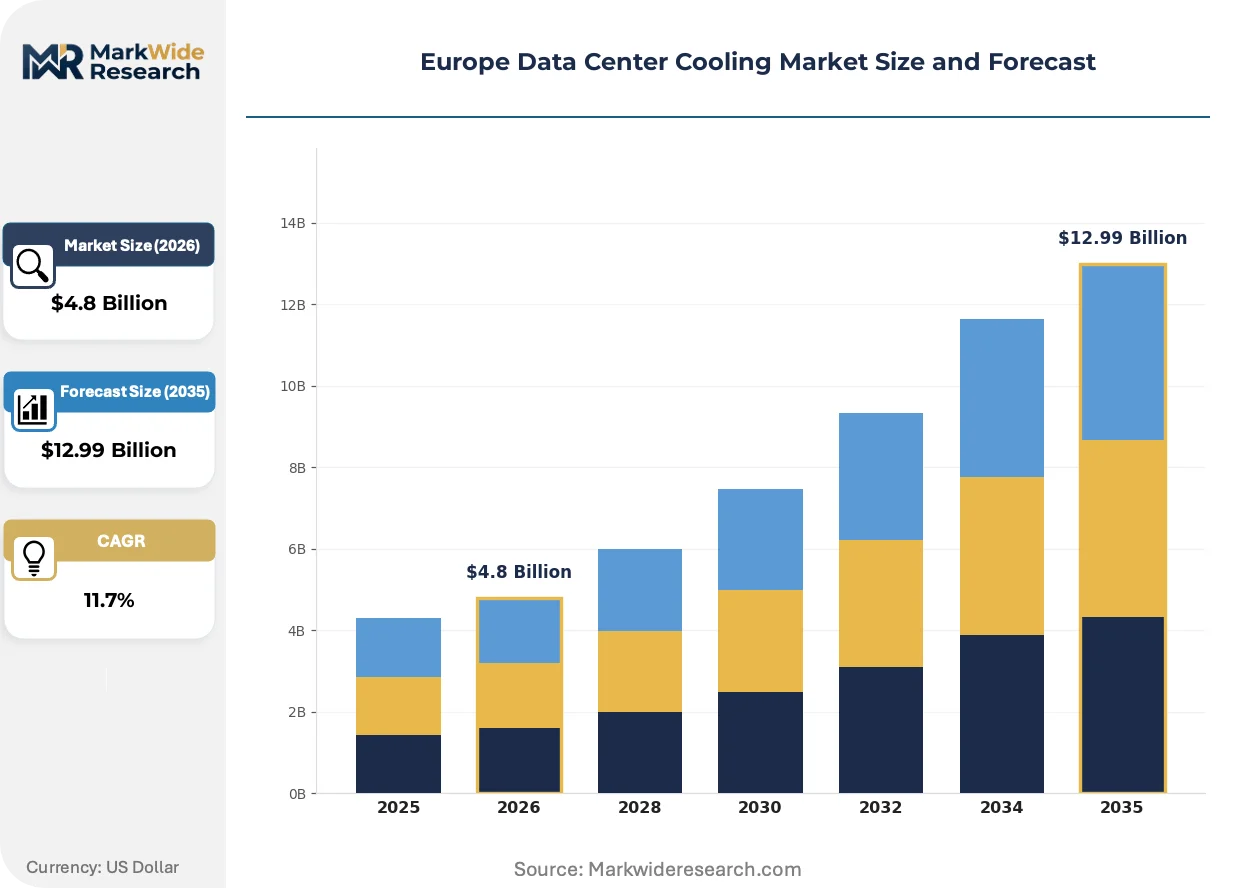
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Air Cooling, Liquid Cooling, Hybrid Cooling, Immersion Cooling End User: Cloud Service Providers, Telecom Companies, Enterprises, Colocation Providers Geothermal Application: Direct Use, Ground Source Heat Pumps, Aquifer Thermal Energy Storage, Borehole Thermal Energy Storage Control System: Automated Control Systems, Manual Control Systems, Environmental Monitoring Systems, Energy Management Systems |
| Companies Covered | Vertiv Group Corp., Schneider Electric SE, Rittal GmbH & Co. KG, Stulz GmbH, Asetek A/S, Airedale International Air Conditioning Ltd., Johnson Controls International plc, Daikin Europe NV, Alfa Laval AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Data Center Cooling Market Trends and Innovations
Precision cooling architectures are bifurcating between ultra-high-density liquid loops for AI training and software-optimized air systems for inference and enterprise workloads, with regulatory chemistry constraints dictating fluid selection across both paths.
Direct-to-chip cold plates with micro-channel copper geometries are electrifying thermal design power ceilings from 300W to 800W per processor without vapor compression augmentation. Hyperscale operators in Paris and Frankfurt are standardizing these loops for NVIDIA and AMD accelerator deployments. The shift is compressing demand for perimeter computer room air handlers and reallocating specification authority from mechanical contractors to chip thermal architects.
The EU F-Gas Regulation's 2027 phase-down deadline for refrigerants with GWP above 150 is banning R410A and R134a from new stationary cooling equipment. Equipment vendors are engineering propane and ammonia chillers with charge-limiting safety enclosures for German and Dutch facilities. Colocation providers are responding by accelerating depreciation schedules on installed R410A-based infrastructure to avoid stranded asset risk.
Colocation procurement teams are unbundling thermal optimization from hardware supply, separating controls software, fluid management, and mechanical infrastructure into distinct contract vehicles. Wholesale hyperscale tenants in Amsterdam are demanding cooling performance guarantees with liquidated damages clauses rather than equipment specifications. This pattern concentrates in Netherlands and Ireland facilities where power purchase agreements already separate electrons from grid infrastructure.
Europe Data Center Cooling Market Segmentation
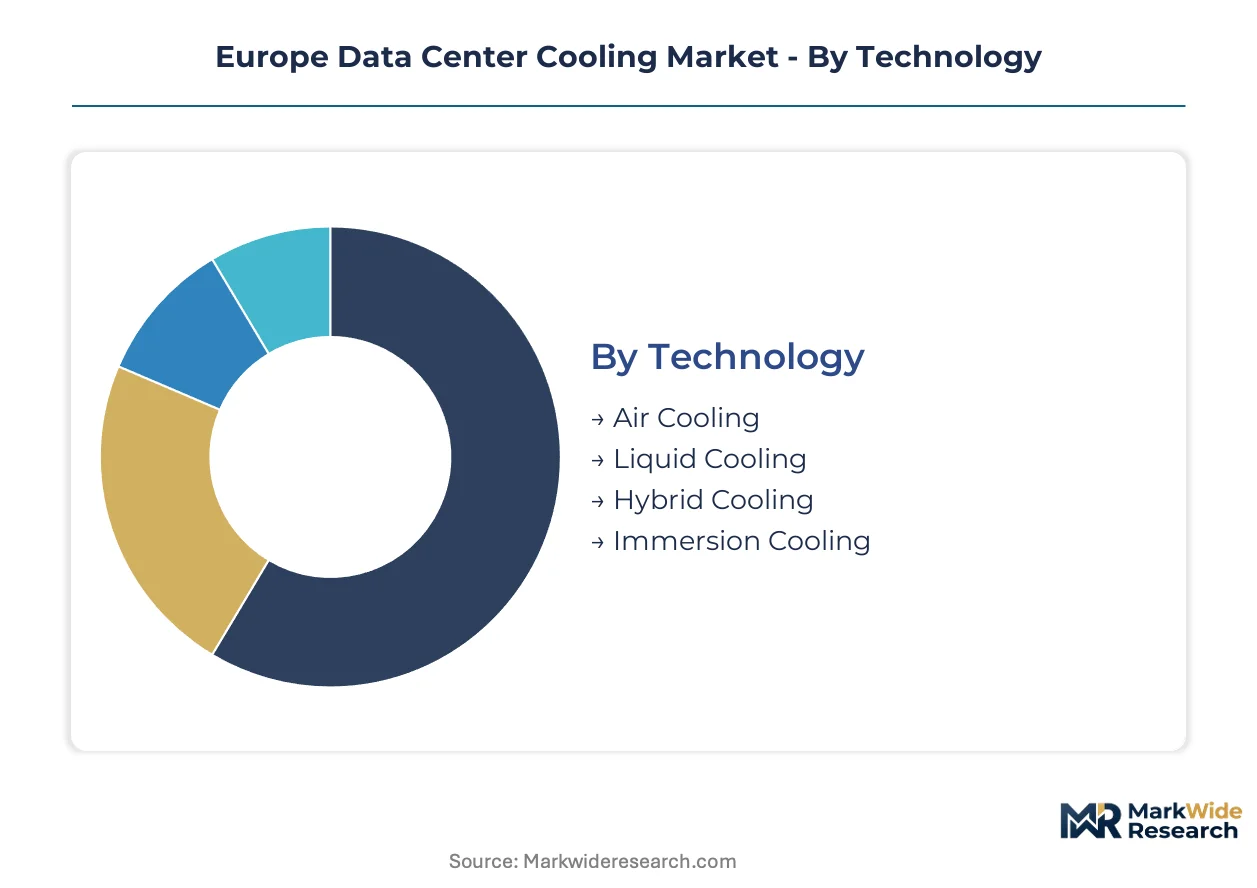
Cooling architecture selection in European data centers hinges on thermal design power thresholds and regulatory chemistry constraints. Procurement patterns diverge sharply between hyperscale operators retrofitting for AI clusters and enterprise facilities extending legacy air-cooled infrastructure.
Technology:
Volume deployment concentrates in air-cooled systems, while premium specification flows toward liquid and immersion architectures for high-density compute.
- Air Cooling:Perimeter computer room air handlers and in-row cooling units dominate legacy raised-floor facilities across Frankfurt and Amsterdam. Enterprise colocation contracts signed before 2022 lock in refresh cycles that delay conversion to liquid alternatives until lease events occur.
- Liquid Cooling:Direct-to-chip cold plates with micro-channel copper geometries handle processor thermal design power from 300W to 800W without vapor compression augmentation. Hyperscale operators in Paris and Frankfurt specify these loops for NVIDIA and AMD accelerator deployments.
- Hybrid Cooling:Combines air-handling for baseline loads with liquid loops for peak thermal events. Dutch facilities leverage this architecture to bridge legacy infrastructure with AI-ready specifications.
- Immersion Cooling:Two-phase dielectric fluid systems enable 100kW-plus rack densities without structural reinforcement. REACH registration timelines for new coolants constrain rapid deployment across the region.
Mature deployment sits with Air Cooling. Newer deployment is concentrated in Liquid Cooling.
End User:
Customer type determines specification authority, with wholesale tenants driving performance guarantees and enterprise buyers accepting standardized equipment packages.
- Cloud Service Providers:Hyperscale operators in Germany, France, and the Netherlands demand precision flow-control systems for GPU racks exceeding 100kW per enclosure. Direct procurement relationships with cooling vendors bypass traditional mechanical contractors.
- Colocation Providers:Wholesale leasing absorbs hyperscale expansion across Amsterdam, Frankfurt, and Dublin. These operators unbundle thermal optimization from hardware supply, separating controls software and fluid management into distinct contract vehicles.
- Enterprises:Financial services and manufacturing firms in the DACH region maintain on-premise facilities with conservative refresh timelines. Air-cooled designs persist due to capital budget constraints and risk-averse procurement committees.
- Telecom Companies:Edge data centers for 5G infrastructure deploy compact air-handling units with limited redundancy. Facilities prioritize footprint reduction over thermal efficiency in urban constraint zones.
Specification authority concentrates with Cloud Service Providers. Margin expansion is concentrated in Colocation Providers.
Control System:
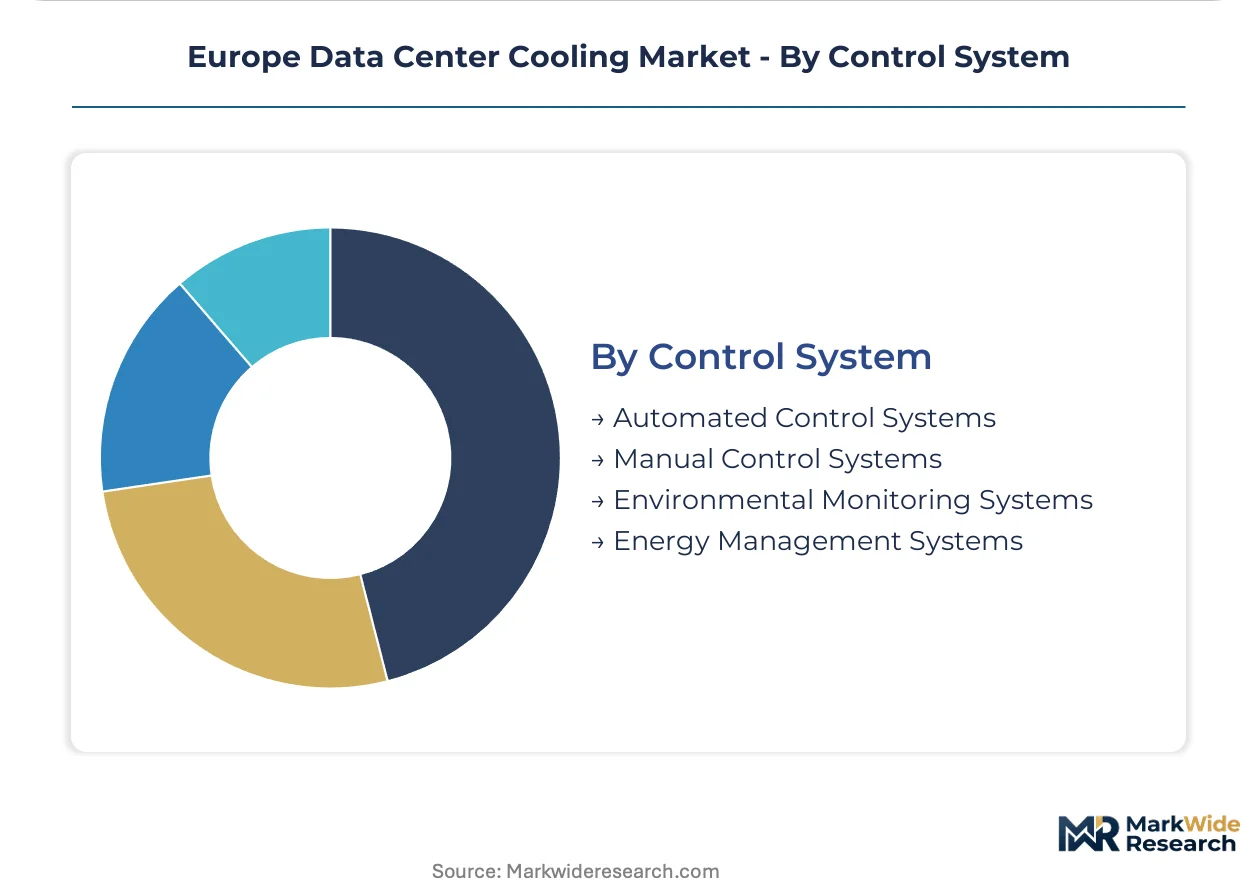
Intelligence layers command premium pricing as operators integrate real-time sensor networks with machine-learning-driven setpoint optimization.
- Automated Control Systems:Machine-learning platforms adjust cooling output based on workload prediction and external weather data. Schneider Electric's EcoStruxure bundles predictive analytics with physical infrastructure across German deployments.
- Energy Management Systems:Software platforms track PUE and carbon intensity for CSRD compliance. Dutch facilities integrate these systems with power purchase agreements to optimize scope 2 disclosure granularity.
- Environmental Monitoring Systems:Distributed sensor networks report temperature, humidity, and airflow at rack-level resolution. CE-MDR recertification requirements delay deployment in healthcare-adjacent data centers.
- Manual Control Systems:Operator-adjusted setpoints persist in smaller facilities without dedicated engineering staff. These systems face obsolescence as EU Green Deal efficiency mandates tighten.
Procurement velocity is highest for Automated Control Systems. Regulatory tailwinds favor Energy Management Systems.
Geothermal Application:
Geothermal integration remains nascent, with Nordic and Alpine facilities piloting subsurface thermal exchange to reduce mechanical refrigeration capex.
- Ground Source Heat Pumps:Closed-loop borehole systems exchange heat with stable subsurface temperatures year-round. Oslo hyperscale facilities leverage this architecture to achieve PUE below 1.2 without refrigerant-based chillers.
- Aquifer Thermal Energy Storage:Seasonal heat storage in underground water-bearing layers buffers cooling demand peaks. Dutch geological conditions favor pilot deployments near Amsterdam data center clusters.
- Borehole Thermal Energy Storage:Drilled shafts store surplus heat for winter recovery or cooling capacity for summer peaks. German facilities integrate these systems with district heating networks.
- Direct Use:Natural geothermal springs provide passive cooling in volcanic regions. Iceland's data center corridor exploits this resource, though geographic constraints limit replication across continental Europe.
Proven deployment concentrates in Ground Source Heat Pumps. Pilot activity clusters in Aquifer Thermal Energy Storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cooling equipment production concentrates in Germany and the Netherlands while hyperscale consumption spreads across Frankfurt, Amsterdam, and Paris. Facility construction outpaces domestic manufacturing capacity for precision flow-control systems. Operators source direct-to-chip cold plates from specialized fabricators in Bavaria and North Brabant.
Germany
Frankfurt's banking sector drives demand for Tier IV facilities with PUE below 1.2. The EU F-Gas Regulation accelerates ammonia chiller adoption across Hesse and Bavaria. Munich hyperscale campuses deploy propane-based systems with charge-limiting safety enclosures.
Netherlands
Amsterdam's AMS-IX ecosystem attracts wholesale colocation requiring 100kW-plus rack densities. REACH compliance timelines delay dielectric fluid deployment near Schiphol. Eindhoven-region manufacturers supply micro-channel cold plates to Paris and Frankfurt operators.
France
Paris cloud regions expand GPU clusters for generative AI training above 500W per chip. The EU Green Deal mandates efficiency thresholds for new Île-de-France facilities. Lyon engineering consultancies specialize in two-phase immersion retrofits for legacy raised-floor sites.
Ireland
Dublin's temperate climate enables free-air cooling for nine months annually. ECHA substance registration burdens block rapid coolant innovation for local immersion pilots. Microsoft and Amazon campuses in County Meath anchor hyperscale specification authority.
Poland
Warsaw emerges as a backup region for Frankfurt latency-sensitive workloads. Lower mechanical refrigeration capex versus German baselines attracts edge facility investment. Katowice industrial zones repurpose steel plant electrical infrastructure for data center substations.
Europe Data Center Cooling Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across cooling architecture supply. Equipment fabricators with captive foundry capacity dominate liquid cooling hardware while software-optimized control vendors capture recurring service revenue. The market structures around three archetypes: integrated infrastructure conglomerates, precision cooling specialists, and dielectric fluid chemists. Consolidation pressures intensify as hyperscale operators bypass mechanical contractors for direct vendor relationships. Technology licensing agreements proliferate between European equipment makers and Asian pump manufacturers.
Within the integrated infrastructure tier, Schneider Electric SE and Vertiv Group Corp. exemplify platform bundling strategies that combine predictive analytics with physical equipment supply. Stulz GmbH occupies a specialist position anchored in German engineering heritage for custom air-handling configurations. These three entities represent divergent responses to the unbundling trend separating thermal optimization software from mechanical hardware procurement.
| Leading Market Players |
|---|
| Vertiv Group Corp. |
| Schneider Electric SE |
| Rittal GmbH & Co. KG |
| Stulz GmbH |
| Asetek A/S |
| Airedale International Air Conditioning Ltd. |
| Johnson Controls International plc |
| Daikin Europe NV |
| Alfa Laval AB |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists across Bavaria and North Brabant anchor precision flow-control manufacturing, concentrating supply discipline while hyperscale procurement teams extract performance-guarantee concessions that compress hardware margins. This ownership pattern feeds selective capacity expansion into direct-to-chip cold plates while pricing pressure migrates toward software-optimized control layers.
Pricing Analysis
Cost-down pressure on precision cooling hardware accelerates because hyperscale operators in Frankfurt and Amsterdam unbundle thermal optimization from equipment procurement, forcing mechanical vendors into liquidated-damages contracts. Three-tier pricing structure across premium liquid-cooled, standard hybrid, and economy air-handling levels separates vendors by certification grade and flow-control precision. Price differentiation rests on CE-MDR compliance for embedded sensors and REACH registration status for dielectric fluids. Cloud service providers exhibit lowest price sensitivity as they prioritize thermal guarantees; enterprise colocation buyers drive hardest bargain on refresh-cycle equipment.
Supply Chain Analysis
CE-MDR recertification requirements and REACH substance registration gate access to European data center cooling markets, extending approval timelines for embedded sensor networks and new dielectric formulations. Manufacturing concentrates in Germany, the Netherlands, and Denmark, with micro-channel copper cold plates sourcing from Bavarian fabricators and control systems assembly in Eindhoven. Raw material dependencies center on high-purity copper for thermal exchange, engineered fluorocarbon substitutes for immersion fluids, and rare-earth elements for precision pumps. Single-source vulnerability concentrates in ammonia and CO2 refrigerant supply from Austrian chemical producers. Distribution runs through direct vendor relationships with hyperscale operators and mechanical contractor channels for enterprise retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as cooling vendors capture upstream control over dielectric fluid chemistry and downstream service revenue through performance-contracting models.
For Market Incumbents: To counter unbundling trends that separate hardware from software procurement, deepen captive production of micro-channel cold plates in Bavaria and secure exclusive REACH-registered fluid formulations through backward integration into specialty chemical supply. Anchor defensive positioning by embedding predictive analytics platforms into long-term service contracts with Amsterdam colocation providers. For New Entrants and Emerging Players: Direct-to-chip liquid cooling retrofit services for legacy Frankfurt and Paris facilities represent the most penetrable white-space target, bypassing incumbent lock-in on new construction. Poland's Warsaw corridor offers geographic entry point with lower certification burden and hyperscale backup-region demand. Lead generation through thermal audit SaaS tools builds specification authority before hardware engagement. For Investors and Strategic Acquirers: REACH registration approval for novel dielectric coolant formulations is the leading indicator that immersion-cooling specialist acquisition targets possess defensible chemistry IP. Long-term viability favors vertically integrated platforms combining hardware fabrication with software-defined thermal management. Watch for hyperscale direct-procurement contract announcements as inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Fluid Chemistry | REACH-registered formulations lock out competitors from two-phase immersion retrofits in Frankfurt clusters. |
| Performance-Contracting Model Expansion | Liquidated-damages guarantees align vendor incentives with hyperscale PUE targets under EU Green Deal mandates. |
| CE-MDR Certification Fast-Track | Accelerated sensor-network approval opens healthcare-adjacent data center verticals in Germany and France. |
| Poland Manufacturing Footprint | Warsaw-region production reduces logistics cost to Nordic backup facilities and edge deployment zones. |
| Thermal Telemetry SaaS Launch | CSRD-compliant carbon accounting software bundles capture recurring revenue from Dutch colocation operators. |
Research Methodology
Trade association filings from Cefic and Bitkom, ECHA substance registration databases, and hyperscaler capex disclosures formed the secondary backbone, cross-referenced against primary interviews with data center engineering directors, thermal systems procurement leads, colocation facility managers, and dielectric fluid R&D specialists. Bottom-up equipment shipment tallies and top-down facility construction pipelines were triangulated to anchor volume estimates.
Historical trendline analysis across installed cooling capacity and PUE reporting thresholds informed the projection framework, with segmentation modeling across air, liquid, hybrid, and immersion architectures plus control system intelligence tiers. CAGRs were derived from facility pipeline tracking and regulatory deadline alignment. Forecast inputs included F-Gas Regulation phase-down schedules and AI training cluster density specifications from NVIDIA and AMD deployment data.
The model holds under stable REACH registration timelines and continued hyperscale direct-procurement patterns; deviation in refrigerant supply allocation or CE-MDR recertification delays would shift equipment deployment curves. Forecasts reflect documented assumptions on regulatory compliance costs and thermal design power trajectories. A model refresh is warranted upon material change in EU AI Act transparency requirements affecting thermal telemetry data governance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
China Data Center Cooling Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Singapore Data Center Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
South Korea Data Center Cooling Market