
 Global Thermal Management Technologies Market | 2026-2036
Global Thermal Management Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermal Management Technologies Market Intelligence
The direct-to-OEM sales channel for high-performance cooling systems is rewriting traditional supply agreements. Delta Electronics, Inc. leverages its manufacturing scale in power systems to provide integrated thermal solutions directly to electronics producers. In contrast, Parker-Hannifin Corporation differentiates through its portfolio of specialized thermal interface materials for aerospace and industrial clients. Laird Thermal Systems Inc. occupies a niche by focusing on thermoelectric modules for precision cooling in medical and telecom equipment.
Thermal management technologies are components and systems designed to dissipate waste heat from electronic and mechanical devices to maintain optimal performance. They function via conduction, convection, and radiation, using materials like copper and aluminum to transfer thermal energy away from critical components. Demand for Liquid Cooling Systems is rising in Data Centers, where they manage higher heat densities than traditional heat sinks. Active Cooling technologies, such as thermoelectric coolers, are essential for precise temperature control in Power Electronics and semiconductor applications.
Product design is shaped by regulations like the EU's RoHS directive, which restricts hazardous materials in electronic components, including certain solders and finishes. In parallel, China's GB standards for energy efficiency and US EPA rules on refrigerants influence the selection of cooling fluids and system power consumption. Future competitiveness depends on developing solutions that meet stricter thermal performance targets while adhering to a complex and evolving global compliance landscape.
Market Dynamics
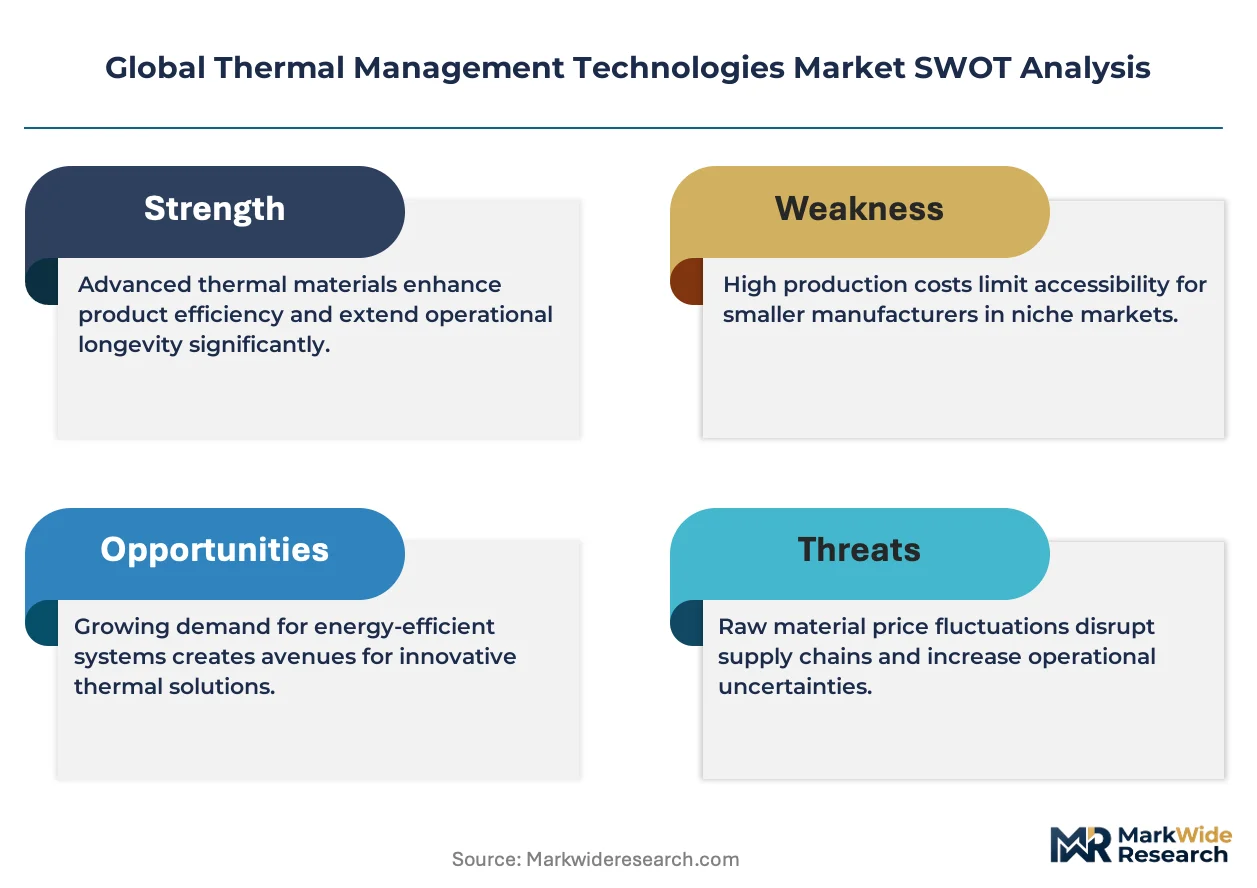
The market's central force is the collision between escalating thermal density in electronics, driven by AI and data centers, and tightening environmental regulations. This conflict shapes material science, component design, and system architecture across the value chain, forcing a re-evaluation of traditional cooling methods.
Growth Catalysts
- Data Center Efficiency Mandates:The EU Green Deal and similar initiatives compel data center operators to adopt more efficient technologies, such as direct liquid cooling, to reduce power usage effectiveness (PUE) metrics and meet sustainability targets.
- 5G Infrastructure Deployment:The global rollout of 5G networks necessitates compact, high-performance thermal management for base stations and edge computing nodes, which feature higher component density and power consumption than previous generations.
- Wide-Bandgap Semiconductors:The adoption of Gallium Nitride (GaN) and Silicon Carbide (SiC) devices in power electronics and EVs enables higher power densities, creating a direct need for superior thermal interface materials and heat sinks.
Market Restraints
- Material Cost Volatility:The high and fluctuating costs of key materials like copper and specialty polymers create margin pressure for manufacturers of heat sinks and thermal interface materials, impacting final system pricing.
- Regulatory Fragmentation:Navigating disparate regulations, such as Europe's RoHS directive and China's GB standards for electronics, complicates product design and lengthens certification cycles, acting as a barrier to market entry.
- Technical Integration Limits:Integrating advanced liquid cooling systems into legacy air-cooled data center infrastructure presents significant technical and logistical challenges, slowing adoption in brownfield sites despite clear performance benefits.
Strategic Opportunities
- Immersion Cooling for HPC:The rise of specialized high-performance computing (HPC) workloads, including AI training and cryptocurrency mining, creates a significant opportunity for single-phase and two-phase immersion cooling solutions.
- Sustainable Dielectric Fluids:There is a growing market for developing biodegradable and recyclable dielectric fluids that comply with stringent environmental standards like the EU's F-Gas Regulation while delivering high thermal performance.
- Electronics Manufacturing in India:India's Production Linked Incentive (PLI) scheme is fostering a domestic electronics manufacturing ecosystem, presenting a new, high-volume market for thermal management components beyond established centers in East Asia.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:A shortage of engineers skilled in both thermodynamics and power electronics design hampers the development of integrated thermal solutions, especially for complex applications like electric vehicle powertrains.
- Liquid Cooling Standardization Gaps:The absence of industry-wide standards for liquid cooling manifolds, quick-disconnect fittings, and coolant chemistries creates interoperability problems, slowing enterprise adoption in multi-vendor data center environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermal Management Technologies Market |
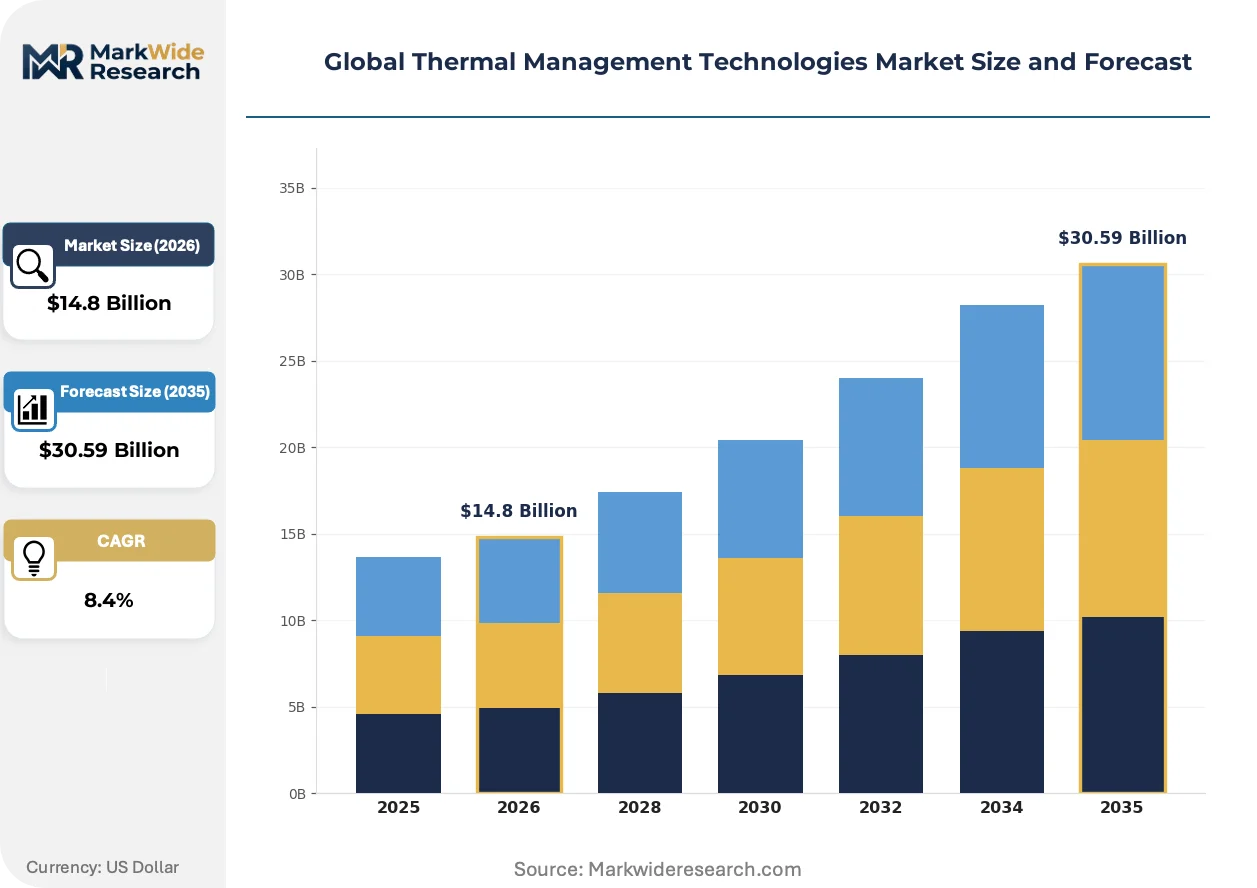
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $30.59 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Sinks, Thermoelectric Coolers, Liquid Cooling Systems, Phase Change Materials Technology: Active Cooling, Passive Cooling, Forced Convection, Heat Pipe Technology, Vapor Chamber Application: Semiconductor Devices, LED Lighting, Power Electronics, Data Centers, Aerospace Equipment End User: Consumer Electronics Manufacturers, OEMs, Telecommunication Companies, Automotive Tier-1 Suppliers |
| Companies Covered | Honeywell International Inc., Henkel AG & Co. KGaA, Advanced Cooling Technologies, Inc., Gentherm Incorporated, Autoneum Holding AG, Parker-Hannifin Corporation, Delta Electronics, Inc., Laird Thermal Systems Inc., Boyd Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermal Management Technologies Market Strategic Shifts & Innovations
Material science innovations and a system-level design philosophy are fundamentally altering thermal management. The focus is shifting from discrete components to integrated solutions that address both heat dissipation and environmental compliance simultaneously, pushing boundaries in performance and sustainability.
Two-phase immersion cooling submerges entire servers in a dielectric fluid that boils on chip surfaces, efficiently removing massive heat loads. Hyperscale data centers and specialized AI compute farms are the primary adopters, driven by extreme power densities. This technology is collapsing the traditional boundary between the server chassis, the cooling system, and the data hall infrastructure itself.
The EU’s forthcoming Ecodesign for Sustainable Products Regulation (ESPR) extends beyond energy efficiency to mandate component reparability and material circularity. This forces manufacturers to design thermal solutions, like fan assemblies and heat sinks, for easier disassembly and replacement. Consumer electronics and server manufacturers are most impacted, redesigning products to avoid integrated, non-serviceable cooling components to achieve compliance.
A significant demand-side shift involves electronics OEMs moving from transactional component procurement to deep co-development partnerships with thermal specialists. This model displaces the standard request-for-quote process for off-the-shelf heat sinks and fans with collaborative design cycles. This trend is most prominent in the electric vehicle sector for battery thermal systems and in the aerospace industry for custom avionics cooling.
Global Thermal Management Technologies Market Segmentation
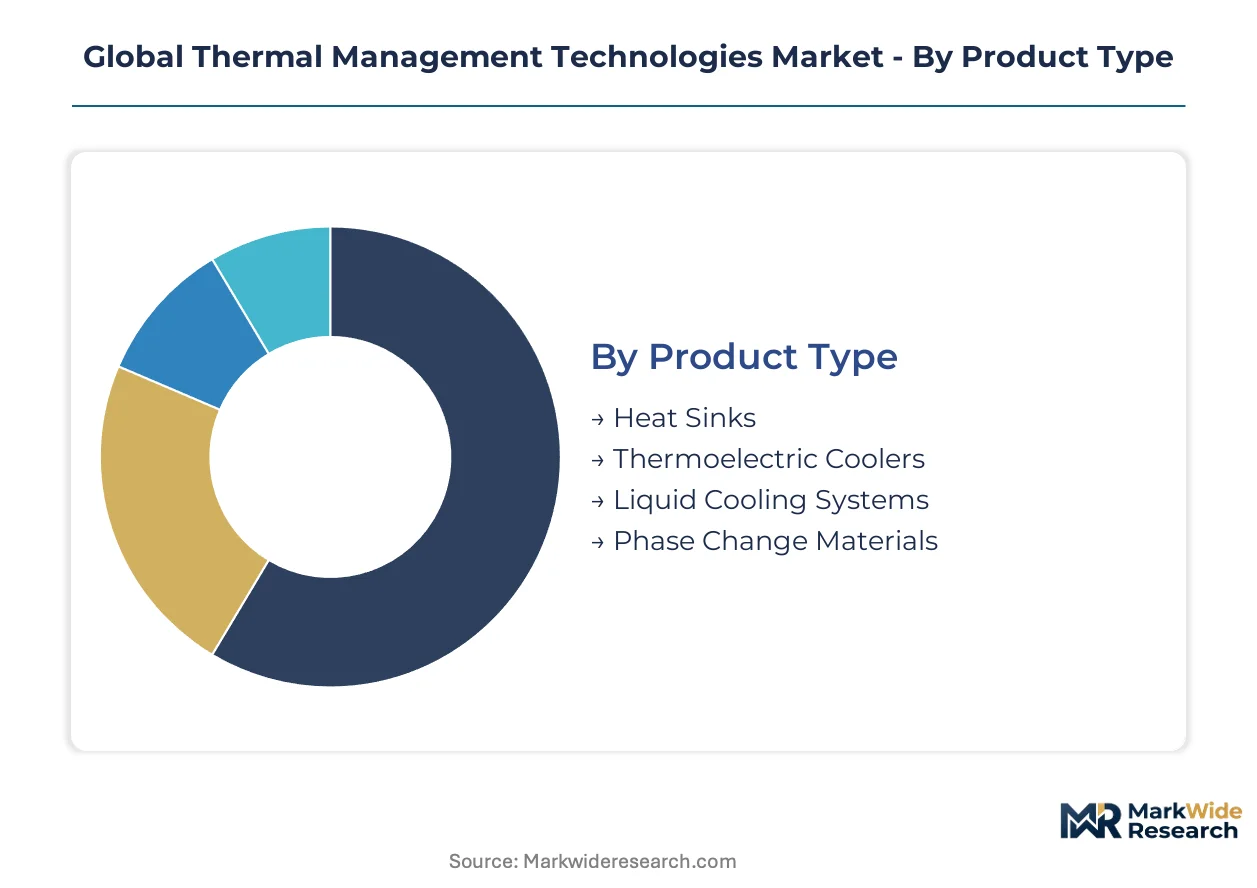
Understanding the Global Thermal Management Technologies Market through segmentation reveals how diverse cooling demands shape product development and market dynamics. Each segment reflects specific performance requirements, material considerations, and regulatory compliance needs across various industries. This granular view highlights areas of innovation and established demand patterns.
Product Type:
The product type segment spans from mature, widely adopted solutions to emerging, high-performance cooling systems.
- Heat Sinks:These passive devices, typically made from aluminum or copper, increase the surface area for heat dissipation through convection and radiation. Demand remains strong in consumer electronics and industrial machinery due to their cost-effectiveness and reliability.
- Thermoelectric Coolers:Utilizing the Peltier effect, these solid-state devices provide precise temperature control for sensitive components in medical diagnostics and telecommunications equipment. Laird Thermal Systems Inc. specializes in these modules for niche applications.
- Liquid Cooling Systems:These systems circulate a coolant, often water or a dielectric fluid, through cold plates attached to heat-generating components. Hyperscale data centers in the US and Europe increasingly adopt liquid cooling to manage extreme heat densities from AI workloads.
- Phase Change Materials:These materials absorb and release latent heat during a phase transition, offering temporary thermal buffering for electronics in applications with intermittent high power loads.
Heat Sinks handle the majority of throughput; Liquid Cooling Systems are the fastest mover on share.
Technology:
The technology segment distinguishes between methods based on their operational principles and control capabilities across different cooling requirements.
- Active Cooling:These technologies require external power to operate, such as fans, pumps, or thermoelectric coolers, providing dynamic and precise temperature regulation. Power electronics in electric vehicles and 5G base stations depend on active cooling for optimal performance.
- Passive Cooling:Relying on natural convection, conduction, and radiation without external power input, passive solutions like heat sinks offer simplicity and high reliability. LED lighting and low-power consumer electronics frequently incorporate passive cooling designs.
- Forced Convection:This method enhances heat transfer by using mechanical means, typically fans, to move air or other fluids over heated surfaces. Server racks and industrial control systems utilize forced convection for efficient heat removal.
- Heat Pipe Technology:Heat pipes transfer thermal energy through the phase change of a working fluid within a sealed vacuum-sealed tube, offering high thermal conductivity. Laptops and some compact industrial equipment leverage heat pipes for localized heat spreading.
- Vapor Chamber:Similar to heat pipes but with a flat, planar structure, vapor chambers spread heat rapidly across a larger area. High-performance graphics cards and advanced smartphones integrate vapor chambers for effective hot spot management.
Active Cooling solutions command the highest value share, while Passive Cooling methods maintain the largest volume.
Application:
This segment highlights where thermal management solutions are deployed, reflecting varying environmental and performance demands.
- Semiconductor Devices:Thermal management ensures stable operating temperatures for microprocessors and memory chips, directly impacting performance and longevity.
- LED Lighting:Effective heat dissipation prevents lumen degradation and extends the lifespan of LED components in commercial and automotive lighting.
- Power Electronics:These applications involve high power densities, requiring robust cooling for components like IGBTs and MOSFETs in industrial drives and renewable energy inverters. The adoption of wide-bandgap semiconductors in Germany and Japan drives demand for advanced thermal interface materials.
- Data Centers:Managing the immense heat generated by servers, storage, and networking equipment is critical for operational efficiency and reliability in large facilities. Hyperscale data centers in China and the US are rapidly deploying direct liquid cooling to reduce Power Usage Effectiveness (PUE).
- Aerospace Equipment:Cooling solutions for avionics and satellite systems must operate reliably under extreme temperature variations and strict weight constraints.
Data Centers represent a substantial and expanding application area, while Power Electronics applications are experiencing the steepest expansion trajectory.
End User:
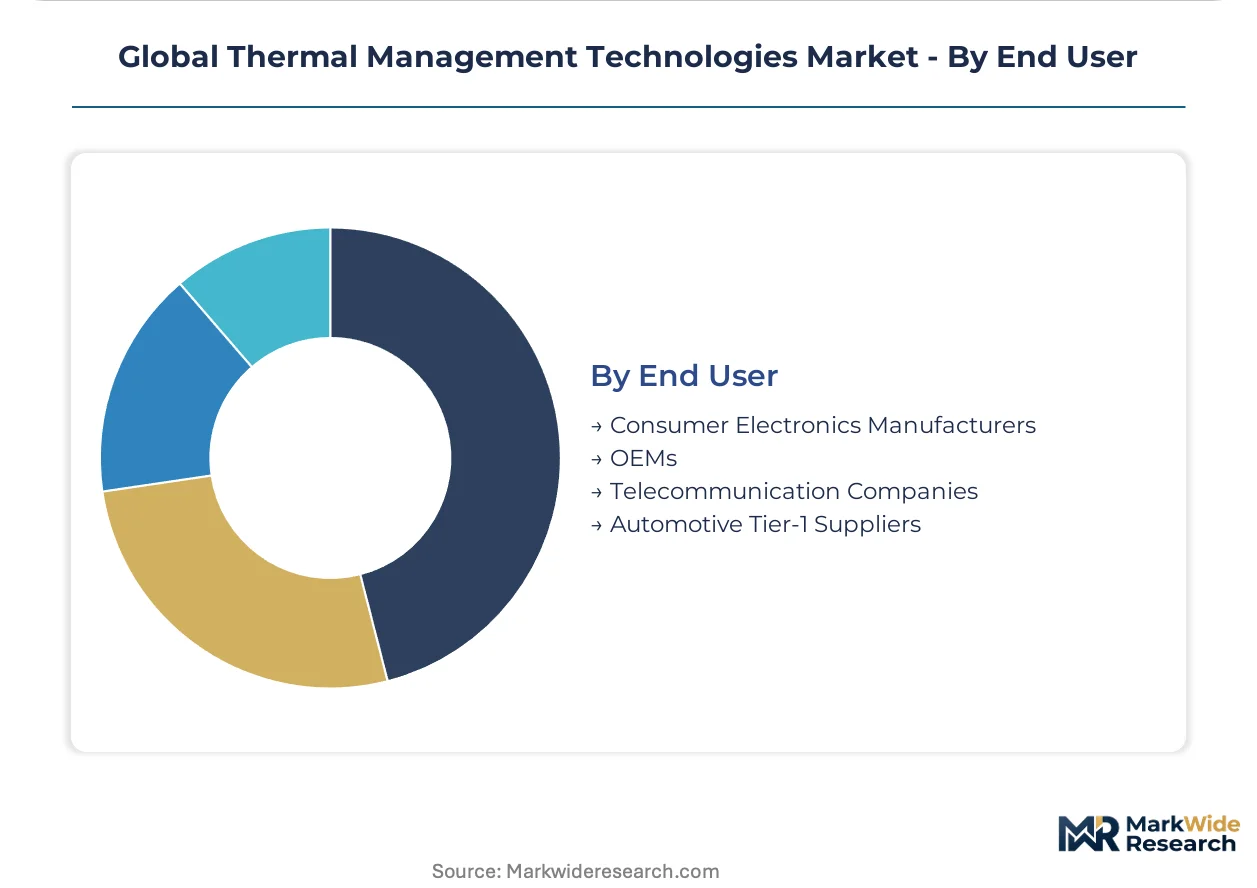
The end-user segment identifies the primary industries and organizations procuring thermal management technologies, each with unique procurement and integration needs.
- Consumer Electronics Manufacturers:These companies integrate cooling solutions into devices like smartphones, laptops, and gaming consoles to enhance performance and user comfort.
- OEMs:Original Equipment Manufacturers integrate thermal solutions into their final products, often requiring custom designs and high-volume supply agreements. Delta Electronics, Inc. provides integrated solutions directly to electronics producers, leveraging its manufacturing scale.
- Telecommunication Companies:These firms deploy thermal management in network infrastructure, including 5G base stations, data centers, and edge computing nodes, to ensure reliable operation. The global rollout of 5G networks in India and Southeast Asia drives demand for compact, high-performance cooling.
- Automotive Tier-1 Suppliers:These suppliers provide thermal management systems for electric vehicle battery packs, power inverters, and infotainment systems.
OEMs drive significant volume through integrated solutions, while Telecommunication Companies are rapidly expanding their thermal management procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry exists between East Asian manufacturing hubs and Western markets for advanced thermal management solutions. China's scaled production capacity often dictates component costs, while European and US markets emphasize performance and compliance premiums. This dynamic influences global pricing and supply chain strategies.
China
China's rapidly growing electronics manufacturing sector and expanding hyperscale data centers, driven by AI workloads, create substantial demand for thermal management. The country's GB standards for energy efficiency and dual carbon goals compel the adoption of advanced cooling solutions. Manufacturing hubs in the Yangtze River Delta continue to drive high-volume component production and integration.
United States
The United States sees strong demand for thermal management in hyperscale data centers, high-performance computing, and aerospace equipment. US EPA rules on refrigerants and energy efficiency mandates for data centers influence system design and fluid selection. Silicon Valley and Texas data center clusters are primary deployment sites for advanced liquid cooling systems.
Germany
German demand for thermal management is concentrated in power electronics for electric vehicles and industrial machinery, alongside wide-bandgap semiconductor applications. The EU Green Deal, RoHS directive, and the forthcoming Ecodesign for Sustainable Products Regulation (ESPR) shape product development. Bavaria and Baden-Württemberg industrial regions are centers for automotive and power electronics innovation, requiring robust thermal solutions.
India
India's significant 5G infrastructure deployment, coupled with the Production Linked Incentive (PLI) scheme fostering domestic electronics manufacturing, drives new demand for thermal management. BIS standards and national energy efficiency directives guide product development for local markets. Bengaluru and Chennai electronics manufacturing ecosystems are integrating these components into a diverse range of devices.
Japan
Precision cooling for advanced semiconductor devices, power electronics, and compact industrial equipment defines the Japanese market for thermal management. METI initiatives for energy efficiency and stringent JIS standards influence product design and material choices. Technology clusters in Tokyo and Osaka focus on developing and integrating high-performance thermal solutions for domestic and export markets.
Global Thermal Management Technologies Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical materials and sub-assemblies. The market presents a tiered structure, with large diversified conglomerates offering comprehensive solutions alongside niche players focusing on specific technologies. Strategic archetypes include integrated solution providers, specialized material innovators, and precise module manufacturers. Portfolio diversification, technology licensing, and strategic partnerships are dominant competitive moves among established firms seeking to expand their market footprint.
Within the integrated solution provider archetype, Delta Electronics, Inc. exemplifies a player leveraging manufacturing scale in power systems to deliver thermal solutions directly to electronics producers, often customizing offerings for high-volume clients. Parker-Hannifin Corporation occupies a position as a specialized material innovator, differentiating through its extensive portfolio of thermal interface materials for demanding aerospace and industrial clients. Laird Thermal Systems Inc. represents a niche specialist, focusing on advanced thermoelectric modules designed for precision cooling in sensitive medical and telecommunication equipment. These companies collectively anchor different segments of the value chain, from high-volume integration to specialized component supply.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Henkel AG & Co. KGaA |
| Advanced Cooling Technologies, Inc. |
| Gentherm Incorporated |
| Autoneum Holding AG |
| Parker-Hannifin Corporation |
| Delta Electronics, Inc. |
| Laird Thermal Systems Inc. |
| Boyd Corporation |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes' cost dynamics influence both East Asian supply concentration and downstream price differentiation for thermal management components. This economic reality shapes procurement strategies for electronics manufacturers globally.
Pricing Analysis
Configured-to-order pricing for high-performance thermal solutions contrasts with transactional pricing for standard components. Price differentiation stems from customization level for aerospace clients, material certification requirements like RoHS, and volume scale for consumer electronics. Cost compression in standard heat sinks intensifies due to material cost volatility for copper and aluminum. Telecommunication companies procuring 5G base station cooling show lower price sensitivity compared to consumer electronics manufacturers.
Supply Chain Analysis
Contract manufacturing concentration in China's Yangtze River Delta and Japan's precision component hubs provides significant capacity for thermal management technologies. The supply chain relies on critical inputs like specialty polymers, copper, and dielectric fluids. Material cost volatility represents a significant structural risk for manufacturers of heat sinks and thermal interface materials. Distribution runs through direct-to-OEM agreements for integrated solutions and specialized distributors for niche thermoelectric modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is at a platform-economics inflection, driven by the need for interoperability in advanced liquid cooling ecosystems within hyperscale data centers.
For Market Incumbents:
Insulate core market share by deepening co-development partnerships with electric vehicle and aerospace OEMs, integrating thermal solutions early in product design cycles. Invest in advanced material science R&D, particularly for sustainable dielectric fluids and wide-bandgap semiconductor compatible thermal interface materials. This strategy mitigates the threat from emerging liquid cooling technologies and tightening environmental regulations like the EU's ESPR.
For New Entrants and Emerging Players:
India's burgeoning electronics manufacturing ecosystem, fostered by the PLI scheme, offers a significant underpenetrated market for thermal management components. Target specialized applications like immersion cooling for high-performance computing or precision cooling for medical diagnostics. A go-to-market angle focusing on niche, high-value solutions that address extreme power densities or stringent environmental compliance provides differentiation.
For Investors and Strategic Acquirers:
The EU’s Ecodesign for Sustainable Products Regulation (ESPR) reshapes the acquisition landscape, favoring companies with circular design capabilities for thermal components. Long-term viability rests on the fundamental need for heat dissipation in increasingly power-dense electronics. Target specialized material innovators or niche module manufacturers with strong IP in sustainable coolants or advanced thermoelectric technologies. Quarterly review of material commodity prices and new energy efficiency mandates is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Sustainable Dielectric Fluids | This initiative addresses environmental compliance and opens new markets in eco-conscious data centers. |
| Expand Direct Liquid Cooling Portfolio | This move capitalizes on escalating heat densities in AI workloads and hyperscale data centers. |
| Invest in Wide-Bandgap TIMs R&D | This strategy supports the adoption of GaN and SiC devices in power electronics and electric vehicles. |
| Secure Raw Material Supply Agreements | This action mitigates margin pressure caused by the high and fluctuating costs of copper and specialty polymers. |
| Establish Regional Manufacturing Hubs | This initiative reduces logistics costs and improves responsiveness to local market demands in areas like India. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with R&D directors, procurement leads, data center managers, and thermal engineers. This primary input was rigorously validated against secondary data sources, including SEC 10-K filings, national energy efficiency reports from the EU and US EPA, and industry association publications. The analysis employed both bottom-up and top-down triangulation to ensure robust market sizing and forecasting.
The forecast was calibrated using historical market performance and future growth projections across the analysis window, integrating a comprehensive analytical framework. Key segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from a compound growth model factoring technology adoption rates, such as direct liquid cooling, and capital expenditure trends like 5G infrastructure deployment rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized material innovators or new entrants in immersion cooling would shift outcomes. Geopolitical shifts impacting raw material supply or unforeseen regulatory changes in major markets represent specific risk factors. Quarterly review of material commodity prices and new energy efficiency mandates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
AI-Driven Lighting Controls Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
Airflow Management Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
IoT Energy Management Market
Energy Management Systems
North America Energy Management Systems Market