
 North America Residential Lighting Control System Market | 2026-2036
North America Residential Lighting Control System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Residential Lighting Control System Market Insights
Platform licensing revenue from proprietary control ecosystems is reshaping margin pools across the North America residential lighting control system market. Lutron Electronics Co., Inc. leverages its Clear Connect wireless protocol to sustain premium positioning in whole-home automation. Signify N.V. competes through the Wiz and Hue platforms, extending its reach beyond hardware into recurring software services. Acuity Brands, Inc. anchors its strategy in specification-grade commercial-grade technology adapted for high-end residential channels.
A residential lighting control system comprises networked devices that regulate artificial illumination through centralized or distributed command interfaces, typically operating via low-voltage wiring or mesh radio protocols in the 2.4 GHz spectrum with dimming ranges from one to one hundred percent. These systems serve the primary commercial purpose of reducing energy consumption, enabling scene programming, and integrating with broader building management or voice-activated home automation platforms. Smart switches and dimmers command the largest installed base, though motion sensors represent the fastest-growing product category as code-mandated vacancy sensing expands across jurisdictions. Wireless technology dominates new installations, while hybrid architectures that combine wired backbone reliability with wireless endpoint flexibility capture the highest-margin retrofit projects.
The U.S. Department of Energy enforces minimum efficacy standards under the Energy Policy and Conservation Act, while the Federal Communications Commission regulates radio-frequency emissions for wireless control devices; California Title 24 building codes mandate automatic daylight harvesting and occupancy-responsive controls in residential spaces above defined square footage thresholds. The National Electrical Code, updated through the National Fire Protection Association, shapes installation practices and product certification requirements across all fifty states. Stakeholders must monitor evolving state-level net-zero building mandates and utility demand-response program designs to anticipate where control system specifications will tighten next.
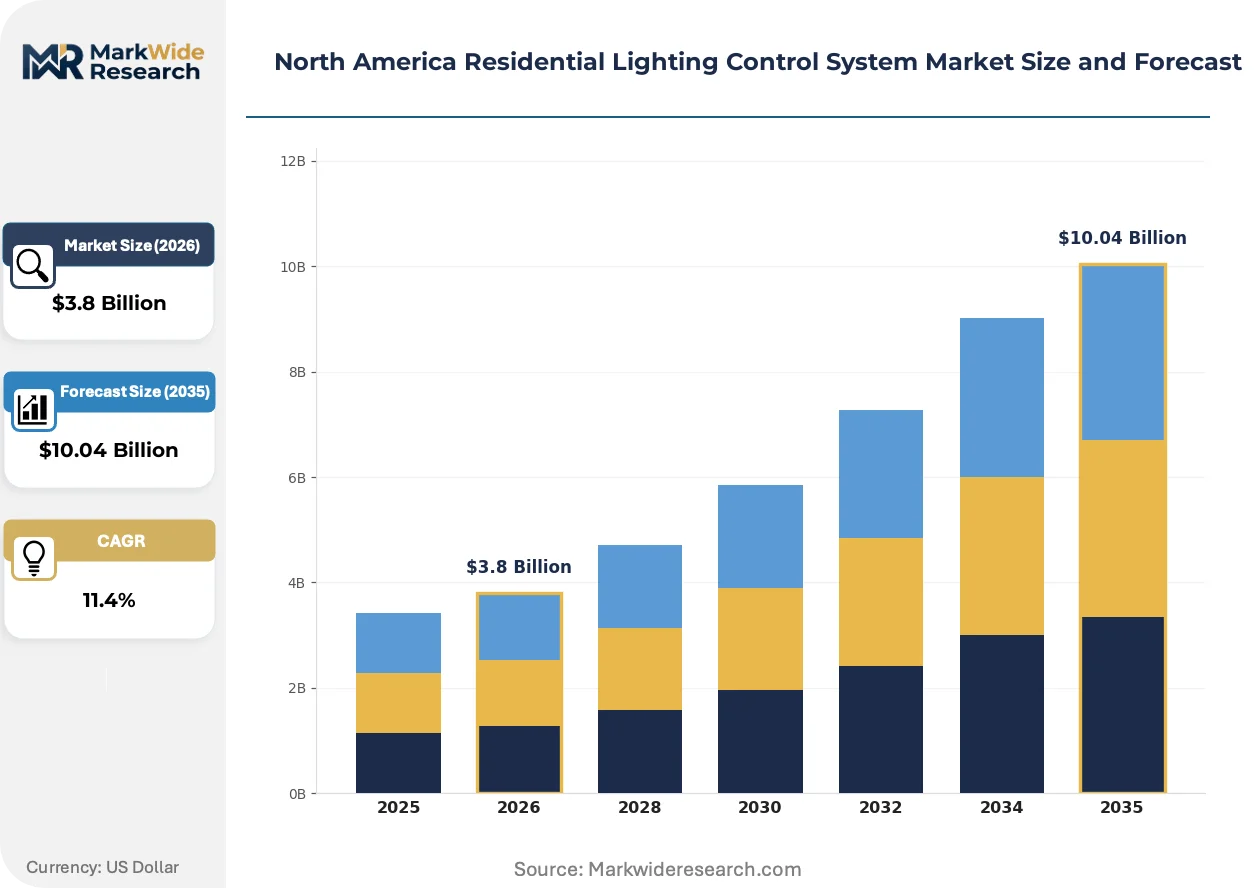
Market Dynamics
Platform licensing revenue from proprietary control ecosystems is collapsing the traditional hardware-centric margin structure across the North America residential lighting control system market. Vendors now compete on recurring software services rather than one-time equipment sales.
Growth Catalysts
- Title 24 Building Codes:California's mandatory automatic daylight harvesting and occupancy-responsive controls for residential spaces above defined square footage thresholds are forcing control system upgrades in new construction and major renovations.
- Utility Rebate Programs:Demand-response incentive structures in Texas and California accelerate connected lighting infrastructure deployment by offsetting upfront hardware costs for single-family homeowners.
- Mesh Radio Protocols:2.4 GHz wireless technology adoption eliminates retrofit wiring costs, expanding addressable market penetration in existing residential stock.
Market Restraints
- Semiconductor Input Volatility:Radio-frequency chip supply concentration in East Asian foundries creates component availability risk for wireless control device manufacturers.
- Interoperability Friction:Proprietary protocols like Clear Connect fragment the ecosystem, forcing consumers into single-vendor lock-in and slowing mass-market adoption.
- Copper Wiring Cost Escalation:Hybrid architecture backbone installations face margin pressure from sustained high-voltage conductor commodity prices.
Strategic Opportunities
- Vacancy Sensing Mandate Expansion:Jurisdictions beyond California adopting code-mandated motion sensor requirements create geographic white space for sensor category growth.
- Voice-Activated Platform Convergence:Integration between lighting controls and Amazon Alexa or Google Home ecosystems enables subscription-based scene programming services.
- Net-Zero Building Trajectory:State-level mandates in New York and Massachusetts targeting residential decarbonization will tighten control system specifications and premiumize product mix.
Industry Challenges
- Low-Voltage Installation Certification:NEC Article 725 compliance complexity and state-level electrician licensing variation create contractor qualification bottlenecks.
- Legacy Incandescent Compatibility:Dimming range calibration across mixed-load installations demands field commissioning expertise that installer networks struggle to scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Residential Lighting Control System Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Switches, Dimmers, Motion Sensors, Smart Plugs Technology: Wired, Wireless, Hybrid, Z-Wave End User: Homeowners, Property Managers, Builders, Architects Installation Type: New Construction, Retrofit, DIY, Professional |
| Companies Covered | Acuity Brands, Inc., Lutron Electronics Co., Inc., Signify N.V., Eaton Corporation plc, Honeywell International Inc., Legrand North America LLC, Leviton Manufacturing Co., Inc., Crestron Electronics, Inc., Hubbell Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Residential Lighting Control System Market Trends and Innovations
Wireless mesh architectures are collapsing installation cost structures and enabling retrofit penetration at scale. Three concurrent developments are reshaping competitive positioning and technology investment priorities across the value chain.
Matter protocol standardization is collapsing fragmentation between proprietary smart home ecosystems. The interoperability framework enables cross-platform device discovery and command routing, allowing lighting controls to function across Apple HomeKit, Google Home, and Amazon Alexa without manufacturer-specific bridges. Single-family homeowners in Texas and California are prioritizing Matter-certified devices, forcing legacy protocol vendors to adapt or cede mass-market share.
The U.S. Department of Energy's appliance efficiency standards under the Energy Policy and Conservation Act are tightening minimum efficacy requirements for connected lighting loads. These regulations compress allowable standby power consumption for control devices, driving semiconductor redesign toward ultra-low-power radio architectures. California Title 24 enforcement has accelerated most aggressively, with building departments rejecting permits for non-compliant control specifications.
Builder procurement consolidation is compressing vendor count in new construction channels. National production homebuilders in Arizona and Florida are standardizing on single-source lighting control packages to streamline subcontractor management and reduce warranty exposure. This concentration is displacing distributor-led specification influence, forcing manufacturers to secure direct national account contracts or exit volume residential segments entirely.
North America Residential Lighting Control System Market Segmentation
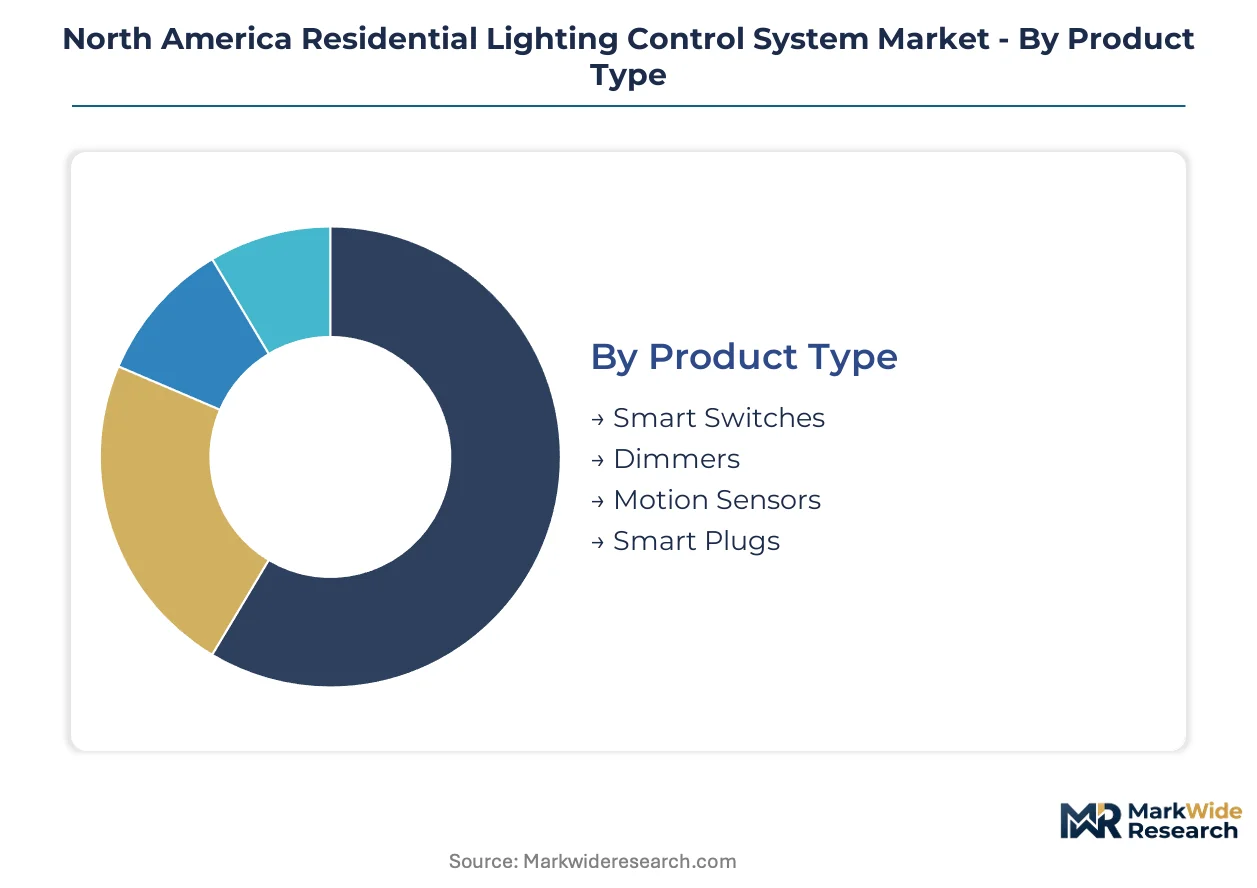
Product architecture and customer channel configuration determine margin capture and technology roadmap priorities across the North America residential lighting control system market. Segmentation reveals where specification-grade specifications command premium positioning versus where volume throughput drives supplier economics.
Product Type:
Cost tier stratification separates specification-grade hardware from mass-market commodity controls in residential channels.
- Smart Switches:Wall-mounted relay devices enabling on/off control and basic scheduling through 2.4 GHz mesh or wired low-voltage interfaces. Demand concentrates in Texas new construction where national production homebuilders standardize on single-source packages to streamline subcontractor management.
- Dimmers:Phase-cut or 0-10V control modules with one to one hundred percent dimming range calibration. California Title 24 compliance mandates are forcing upgrades in major renovations, particularly in single-family homes above defined square footage thresholds.
- Motion Sensors:Passive infrared and ultrasonic vacancy detection devices. Fastest-growing category as code-mandated occupancy-responsive controls expand beyond California into Texas and other jurisdictions.
- Smart Plugs:Outlet-level retrofit devices enabling lamp and appliance control without hardwired installation. Popular in DIY retrofit channels where homeowners seek plug-and-play automation without electrician involvement.
Smart switches hold installed capacity. Motion sensors are rotating up the share rankings.
Technology:
Installation flexibility and reliability requirements segment the market across infrastructure investment levels.
- Wired:Low-voltage control wiring per NEC Article 725 standards delivering deterministic signal transmission without radio-frequency interference. Preferred in California high-end residential where Title 24 daylight harvesting mandates demand guaranteed uptime.
- Wireless:2.4 GHz mesh radio protocols eliminating retrofit wiring costs and expanding addressable market penetration in existing residential stock. Texas and California homeowners prioritize Matter-certified devices for cross-platform compatibility.
- Hybrid:Wired backbone architectures with wireless endpoint flexibility. Capture highest-margin retrofit projects where reliability demands meet installation cost constraints.
- Z-Wave:Sub-GHz proprietary mesh protocol operating outside congested 2.4 GHz spectrum. Sustains niche positioning among early smart home adopters seeking vendor ecosystem lock-in.
Wired technology holds installed capacity. Wireless is rotating up the share rankings.
End User:
Customer type determines specification influence, procurement scale, and service attachment potential.
- Homeowners:Single-family residential decision-makers purchasing through retail, e-commerce, or contractor channels. Fastest-growing adopter segment as smart home integration becomes standard in new construction.
- Property Managers:Multi-family and rental portfolio operators seeking centralized control and energy cost recovery. Demand concentrates in Texas utility rebate territories where demand-response incentives offset hardware investment.
- Builders:National production homebuilders and regional custom developers. Procurement consolidation in Arizona and Florida is compressing vendor count and displacing distributor-led specification influence.
- Architects:Design professionals specifying control systems in custom residential and high-end renovation projects. Influence channel through direct manufacturer relationships and continuing education programming.
Homeowners hold installed capacity. Property managers are rotating up the share rankings.
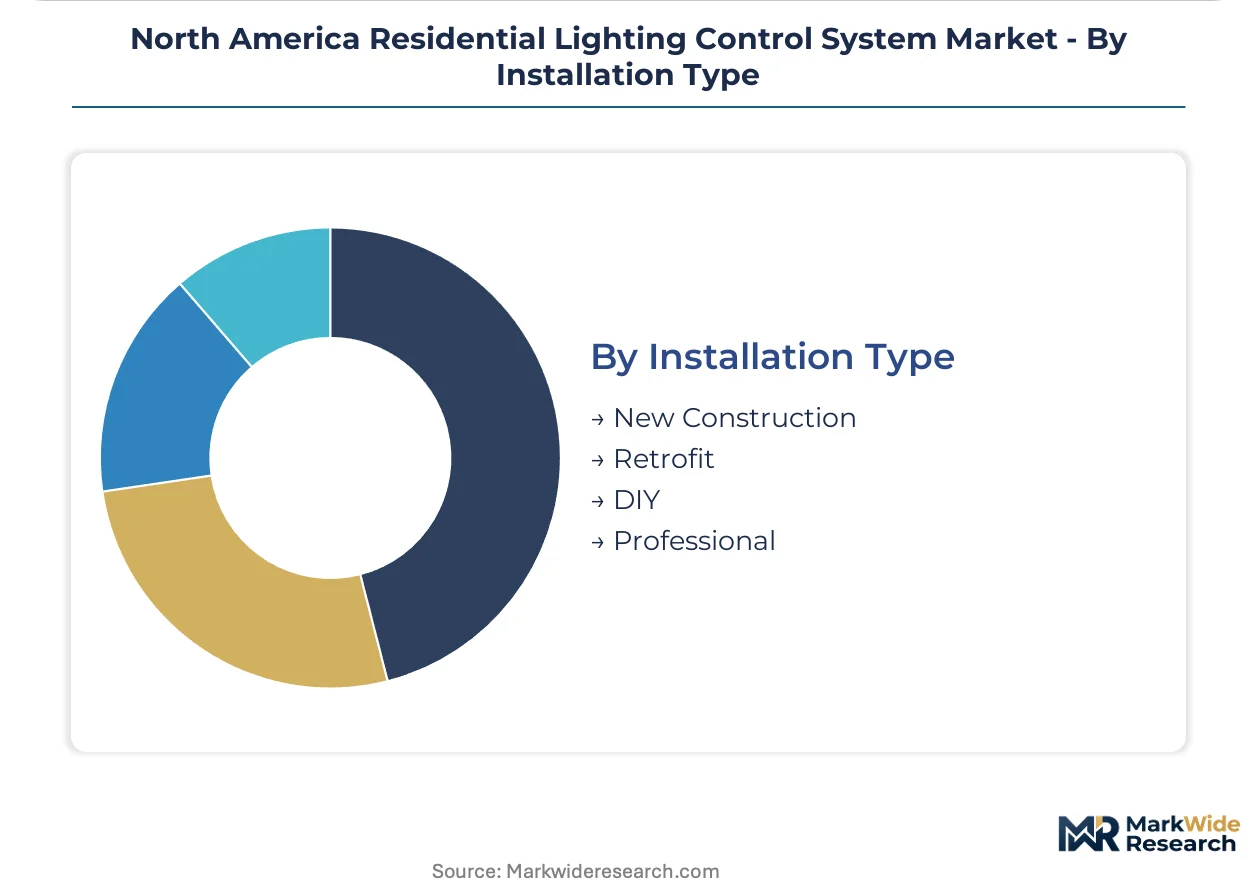
Installation Type:
Project delivery method shapes margin structure, certification requirements, and customer acquisition economics.
- New Construction:Control system installation during electrical rough-in phase. California and Texas building code mandates are accelerating connected lighting infrastructure deployment in this channel.
- Retrofit:Wireless and hybrid architecture deployment in existing residential stock. Mesh radio protocols eliminate wiring costs and expand addressable market penetration.
- DIY:Consumer self-installation of smart switches, plugs, and wireless sensors. Growth channel as Matter protocol standardization reduces technical complexity and bridge requirements.
- Professional:Electrician and low-voltage contractor installation per NEC Article 725 and state licensing requirements. State-level licensing variation creates contractor qualification bottlenecks.
New construction holds installed capacity. Retrofit is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America, with the United States prioritizing whole-home automation integration while Canada emphasizes energy-code compliance and Mexico concentrates on cost-optimized retrofit penetration.
United States
Single-family homeowners in Texas and California drive demand through utility rebate programs and Title 24 building code mandates. The U.S. Department of Energy enforces minimum efficacy standards under the Energy Policy and Conservation Act. Dallas-Fort Worth and Houston metro areas concentrate new construction deployment where national production homebuilders standardize on connected lighting packages.
California
Daylight harvesting and occupancy-responsive control mandates for residential spaces above defined square footage thresholds force system upgrades in renovations. Title 24 building codes administered by the California Energy Commission reject permits for non-compliant specifications. Los Angeles and San Francisco Bay Area building departments lead enforcement stringency, accelerating premium product mix shifts.
Texas
Demand-response incentive structures from ERCOT-aligned utilities offset upfront hardware costs for single-family homeowners. The Public Utility Commission of Texas oversees rebate program designs that favor connected lighting infrastructure. Austin and Dallas metropolitan construction volumes create favorable deployment conditions for wireless mesh protocol adoption.
Canada
Provincial energy efficiency programs in Ontario and British Columbia drive adoption through point-of-sale incentives for ENERGY STAR-certified controls. Natural Resources Canada administers minimum performance standards for lighting equipment. Toronto and Vancouver residential construction channels concentrate specification-grade demand for hybrid wired-wireless architectures.
Mexico
Cost-optimized wireless retrofit solutions penetrate middle-income housing stock in Mexico City and Monterrey metro areas. CONUEE national energy efficiency standards create baseline demand for basic dimming and scheduling functionality. Guadalajara and Querétaro emerging residential developments show nascent interest in smart home integration through DIY installation channels.
North America Residential Lighting Control System Market Competitive Landscape
Capability concentration sits with specification-grade technology developers; scale advantage sits with mass-market hardware suppliers. The market structures around three tiers: premium whole-home automation specialists, mid-market wireless platform providers, and value-oriented electrical device manufacturers. Two strategic moves dominate competitive dynamics: proprietary protocol licensing to capture recurring software revenue, and direct national account contracting with production homebuilders to bypass distributor influence.
Within the premium automation tier, Lutron Electronics Co., Inc. and Crestron Electronics, Inc. represent specification-grade positioning anchored in proprietary wireless ecosystems. Signify N.V. occupies a platform-centric position extending reach through software service attachments. Acuity Brands, Inc. exemplifies commercial-grade technology adaptation for high-end residential channels. These three players illustrate how vendor strategies diverge between hardware-centric and recurring-revenue business models.
| Leading Market Players |
|---|
| Acuity Brands, Inc. |
| Lutron Electronics Co., Inc. |
| Signify N.V. |
| Eaton Corporation plc |
| Honeywell International Inc. |
| Legrand North America LLC |
| Leviton Manufacturing Co., Inc. |
| Crestron Electronics, Inc. |
| Hubbell Incorporated |
| Others |
Pricing and Supply Chain Analysis
The Port of Los Angeles-Long Beach freight corridor's container cost volatility cascades through lighting control supply chains, amplifying margin pressure for manufacturers reliant on East Asian semiconductor inputs while enabling price premiums for vendors with captive North American assembly capacity.
Pricing Analysis
Long-term offtake agreements between national production homebuilders and control system manufacturers anchor volume pricing, while spot-market procurement in DIY channels sustains higher per-unit margins. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade whole-home systems from mass-market wireless devices and private-label commodity controls. Pricing pressure stems from copper wiring cost escalation in hybrid architecture deployments, compressing margins for retrofit specialists. Single-family homeowners in utility rebate territories exhibit lowest price sensitivity due to incentive offset, whereas DIY retrofit purchasers in Mexico demonstrate highest elasticity.
Supply Chain Analysis
Radio-frequency chip fabrication concentrates in Taiwan, South Korea, and mainland China, creating input dependency for wireless control device manufacturers. Supply chains draw from silicon wafer foundries, rare-earth magnet suppliers for sensor actuators, and copper conductor producers for wired backbone components. Single-source vulnerability in 2.4 GHz transceiver chipsets exposes vendors to geopolitical disruption and allocation constraints. Distribution runs through electrical wholesale distributors serving contractor channels, direct national account contracts with production homebuilders, and retail big-box stores capturing DIY demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Matter protocol standardization is disrupting proprietary ecosystem lock-in, creating a regulatory-technology inflection that rewards interoperability investment and punishes closed-protocol vendors across the North America residential lighting control system market.
For Market Incumbents: Build switching-cost moats through Matter-certified platform licensing that captures recurring software revenue and resists disintermediation. Acquire wireless protocol engineering talent in Austin and Dallas to defend against emerging entrants with cloud-native architectures. Secure direct national account contracts with Arizona and Florida production homebuilders to preempt distributor channel displacement.
For New Entrants and Emerging Players: Mid-market multi-family property managers in Texas ERCOT territories represent the most penetrable entry point, combining demand-response incentive alignment with centralized procurement scale. DIY retrofit channels in Mexico City and Monterrey offer geographic white space with lower incumbent saturation. Pursue voice-activated platform convergence as primary go-to-market angle, leveraging Amazon Alexa and Google Home ecosystem integration to bypass proprietary hardware development.
For Investors and Strategic Acquirers: Carve-out targets emerge from commercial lighting conglomerates with undermonetized residential divisions and dormant wireless protocol IP. Long-term viability favors vendors with software service attachment rates above hardware replacement cycles. Watch California Title 24 enforcement stringency as signal for regulatory premiumization trajectory and specification-grade margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-platform interoperability enables market share capture from proprietary ecosystem vendors. |
| Direct National Account Contracting | Bypasses distributor influence as Arizona and Florida production homebuilders consolidate procurement. |
| Software Service Subscription Launch | Recurring revenue from scene programming and energy analytics offsets hardware margin compression. |
| Ultra-Low-Power Radio Redesign | U.S. Department of Energy standby power standards force semiconductor architecture investment. |
| Voice-Activated Platform Integration | Amazon Alexa and Google Home convergence enables premium positioning in DIY retrofit channels. |
Research Methodology
A spread of perspectives from lighting control system manufacturers, electrical contractor network managers, production homebuilder procurement directors, and utility demand-response program administrators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against U.S. Department of Energy appliance efficiency filings, California Energy Commission Title 24 compliance databases, National Electrical Code update records, and utility rebate program design documents. Bottom-up unit shipment estimates triangulated against top-down construction permit data across Texas, California, Arizona, and Florida metropolitan areas.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation dimensions including product architecture, technology protocol, end-user channel, and installation type. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory mandate timing and utility incentive program cycles. Forecast inputs incorporated single-family housing starts, multi-family permit volumes, and Title 24 enforcement stringency indices from Los Angeles and San Francisco Bay Area building departments.
Stress conditions across semiconductor allocation constraints, copper commodity price volatility, and California regulatory acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against National Association of Home Builders smart home adoption surveys and utility rebate program participation statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
Southeast Asia Cooling Systems Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Grid Operations Management Software Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
Energy Management in Data Centers Market