
 US Energy Management Systems Market | 2026-2036
US Energy Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Energy Management Systems Market Insights
Energy-as-a-service and third-party financing is narrowing the capital barrier for mid-sized facility operators seeking enterprise-grade control platforms. Schneider Electric leverages its EcoStruxure architecture to sustain integrated software-hardware positions across commercial portfolios. Johnson Controls International PLC anchors its competitiveness through deep building automation integration that extends from HVAC into lighting and security domains. Siemens AG competes on digital twin capabilities that differentiate its offerings in industrial energy optimization.
Energy management systems encompass software platforms, control hardware, and analytics services that monitor, control, and optimize energy consumption across distributed assets, typically integrating with building automation protocols such as BACnet or Modbus for real-time equipment communication. These systems serve primarily to reduce operational expenditure, manage demand charges, and maintain power quality in complex electrical environments. Cloud-based deployments are capturing the fastest expansion as subscription models lower upfront commitment and enable continuous algorithmic improvement, while on-premises installations retain dominance in defense, critical infrastructure, and data center applications where cybersecurity policies restrict external connectivity. IoT-enabled technology is reshaping competitive dynamics by embedding granular sub-metering and predictive maintenance into standard offerings.
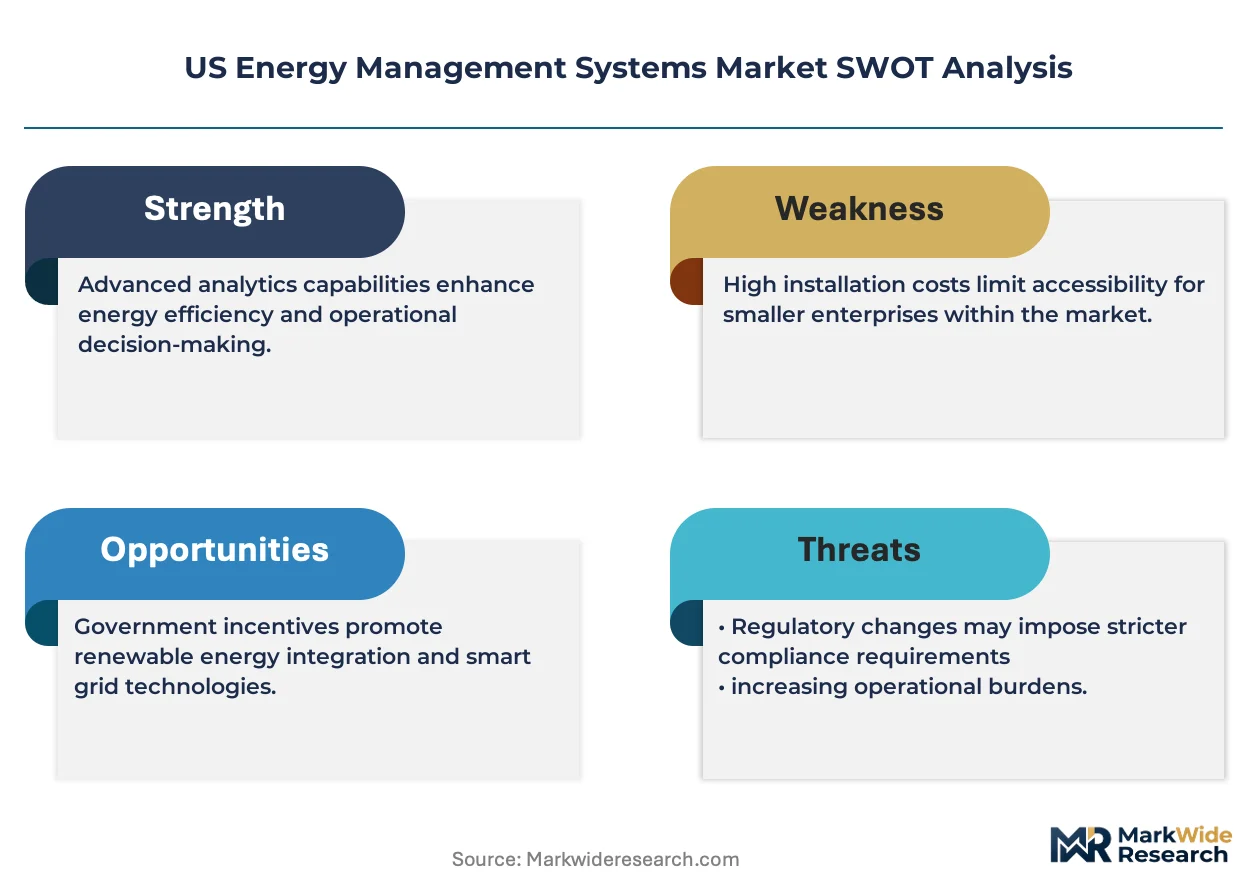
The Department of Energy's appliance and equipment standards program, alongside FERC Order 2222 enabling distributed energy resource aggregation, and state-level building performance standards such as New York Local Law 97, collectively elevate EMS from operational convenience to regulatory compliance infrastructure. EPA ENERGY STAR certification requirements for commercial buildings further hardwire metering and verification capabilities into procurement specifications. Stakeholders must monitor how state utility commission rulings on virtual power plant participation reshape the revenue stack that EMS platforms can capture beyond simple kilowatt-hour savings.
Market Dynamics
FERC Order 2222 is collapsing the traditional boundary between behind-the-meter EMS and wholesale market participation, forcing platform vendors to architect for bidirectional revenue streams rather than static efficiency gains.
Growth Catalysts
- Inflation Reduction Act tax credits:Section 179D deductions for energy-efficient commercial building retrofits compress payback periods for integrated control platform investments.
- California Title 24 mandates:State-level building performance standards require automated demand response capability in new commercial construction above 50,000 square feet.
- Virtual power plant aggregation:Utility commission rulings in Texas and New York enable EMS platforms to capture capacity payments beyond kilowatt-hour savings.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundry dominance in industrial-grade microcontrollers creates 26-32 week lead times for control hardware procurement.
- Cybersecurity compliance friction:NERC CIP requirements for critical infrastructure operators impose audit costs that deter cloud-native EMS adoption in data center and defense verticals.
- Copper and rare earth price volatility:Input cost swings for power conditioning equipment and permanent magnet motors compress hardware margins unpredictably.
Strategic Opportunities
- Mid-market facility financing gap:Energy-as-a-service subscription models open enterprise-grade platforms to operators of 50,000-200,000 square foot commercial buildings previously priced out of capital purchase.
- Industrial digital twin convergence:Integration of EMS with process simulation platforms creates new optimization layers for chemical and food processing facilities.
- New York Local Law 97 carbon penalties:Building performance standards generate compliance-driven replacement cycles for legacy pneumatic control systems in Manhattan commercial stock.
Industry Challenges
- BACnet/IP migration complexity:Facilities with 1980s-era proprietary fieldbus architectures face 18-24 month integration timelines for cloud-connected analytics overlays.
- Controls engineering talent scarcity:Retiring workforce of building automation technicians outpaces HVAC-electrical-software cross-training pipeline in secondary metro markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Energy Management Systems Market |
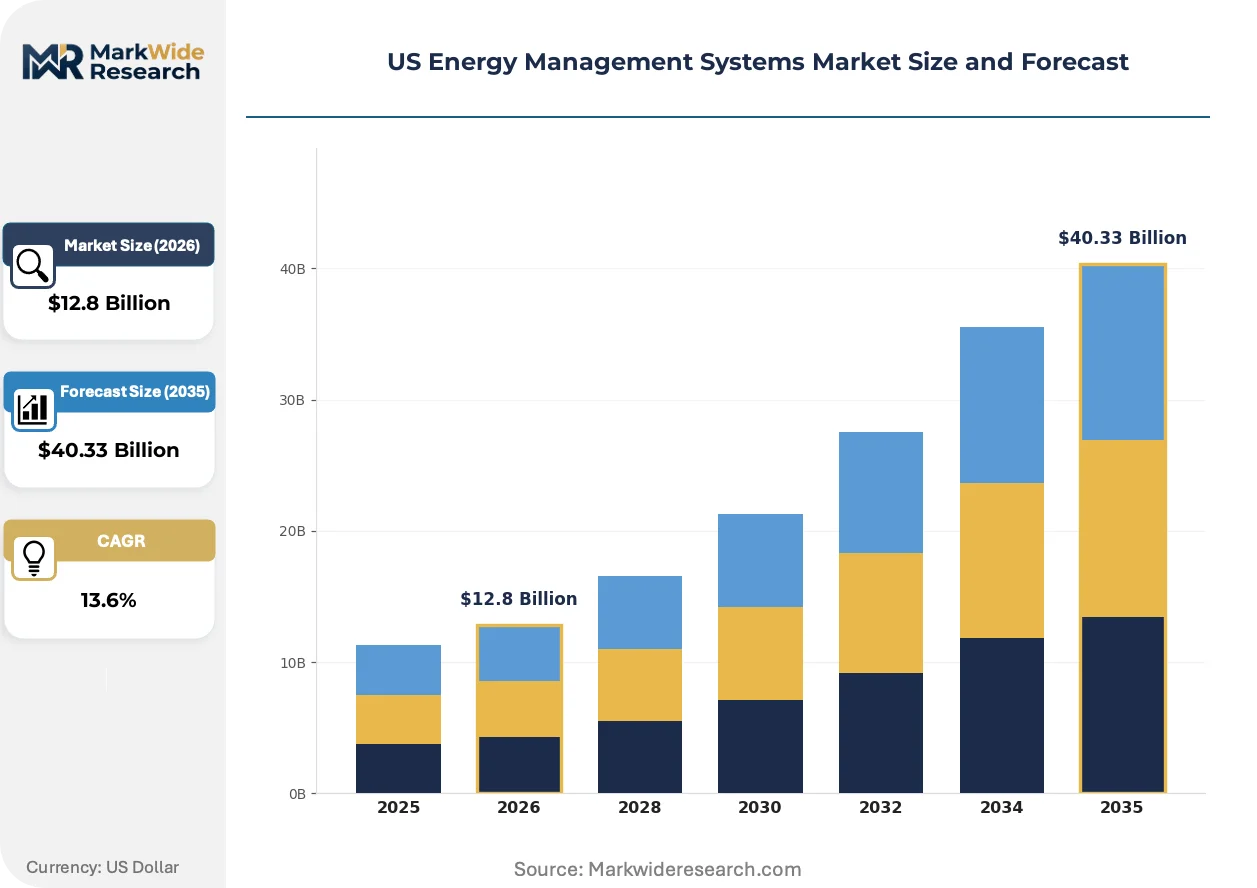
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $40.33 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions Technology: Cloud-Based, On-Premises, Hybrid, IoT-Enabled Application: Commercial Buildings, Industrial Sectors, Residential Spaces, Utilities End User: Energy Providers, Facility Managers, Homeowners, Government Agencies |
| Companies Covered | Schneider Electric, Siemens AG, Honeywell International Inc., Johnson Controls International PLC, ABB Ltd, General Electric Company, Eaton Corporation, Emerson Electric Company, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Energy Management Systems Market Trends and Innovations
Edge-native artificial intelligence is collapsing the latency constraints that previously forced energy optimization decisions into centralized cloud architectures, redistributing computational load toward substation and equipment-level processors.
Digital twin technology is collapsing the distinction between design-phase simulation and operational optimization in industrial EMS deployments. Chemical processing and cold chain logistics operators now require physics-based models that synchronize with real-time sensor feeds. This convergence compresses commissioning timelines and enables predictive control strategies that anticipate thermal mass behavior rather than reacting to deviation.
EPA ENERGY STAR certification requirements for commercial buildings are hardwiring metering and verification capabilities into procurement specifications. Portfolio managers now treat interval-grade sub-metering as a baseline compliance infrastructure rather than an efficiency upgrade. California and New York building codes are accelerating this shift by mandating automated fault detection for systems above 100 tons cooling capacity.
Third-party ownership structures are displacing capital purchase as the dominant acquisition pathway for mid-sized commercial operators. Equipment vendors and independent service providers now capture recurring revenue through performance-linked contracts that guarantee demand charge reductions. This model concentrates fastest in Texas and Florida markets where utility rate volatility amplifies the value proposition of outsourced risk management.
US Energy Management Systems Market Segmentation
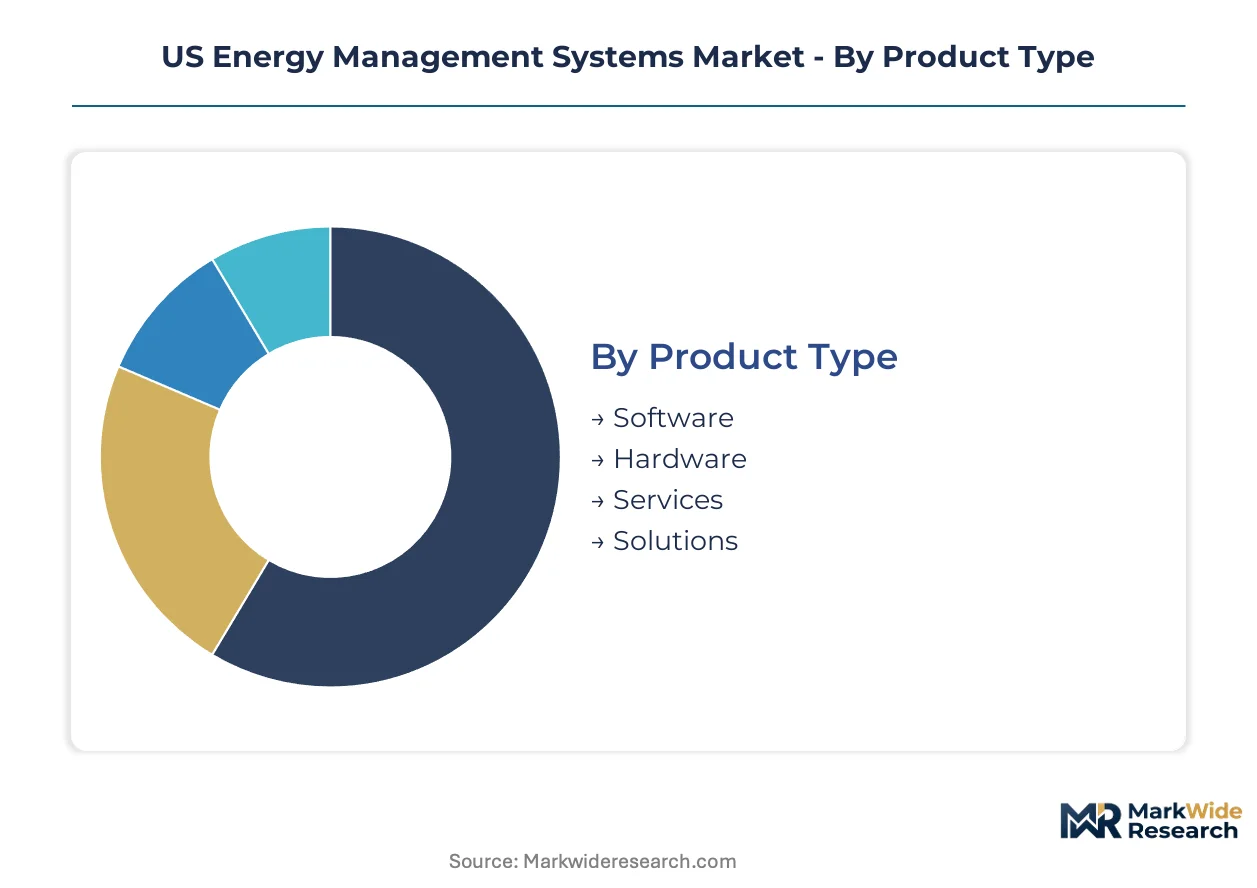
Segmentation in the US Energy Management Systems market reveals how procurement patterns diverge across deployment models, customer sophistication, and regulatory exposure. Understanding these fault lines enables vendors to calibrate pricing architectures and channel strategies for distinct buyer ecosystems.
Product Type:
Cost tier differentiation separates capital-intensive hardware purchases from recurring software subscriptions and outcome-based service contracts.
- Software:Platforms deliver energy analytics, demand forecasting, and automated control algorithms through subscription or perpetual licensing models. California and New York facility operators prioritize cloud-native software stacks to satisfy Local Law 97 and Title 24 automated demand response mandates.
- Hardware:Physical components encompass programmable logic controllers, power quality meters, and edge computing nodes that interface with building automation protocols. Procurement concentrates among Texas industrial operators and data center developers seeking on-premises control architectures that satisfy NERC CIP cybersecurity requirements.
- Services:Implementation, commissioning, and ongoing optimization support bridge deployment gaps for mid-market facility operators lacking in-house controls engineering capacity.
- Solutions:Integrated bundles combining software, hardware, and services capture procurement from government agencies and large commercial portfolios seeking single-accountability vendor relationships.
Hardware commands the established base. The steepest expansion runs through software subscriptions.
Technology:
Deployment architecture determines latency constraints, cybersecurity exposure, and total cost of ownership across customer verticals.
- Cloud-Based:Centralized platforms enable continuous algorithmic improvement and remote portfolio management through browser-based dashboards. Demand concentrates among multi-site retail and office operators in Florida and Texas markets where utility rate volatility amplifies the value of real-time optimization.
- On-Premises:Localized servers and closed-network architectures satisfy defense, critical infrastructure, and financial services operators subject to FERC and NERC data sovereignty requirements.
- Hybrid:Split architectures process sensitive operational data locally while pushing anonymized analytics to cloud layers for benchmarking and machine learning refinement.
- IoT-Enabled:Distributed sensor networks and edge-native processors embed granular sub-metering and predictive maintenance into standard EMS offerings.
On-premises deployments retain the compliance-driven core. IoT-enabled architectures are climbing the fastest as sensor costs decline and 5G connectivity expands.
Application:
End-use environment shapes specification requirements from thermal mass characteristics to integration complexity with existing building automation.
- Commercial Buildings:Office, retail, and hospitality portfolios deploy EMS to manage demand charges, automate demand response, and maintain ENERGY STAR certification. California Title 24 mandates above 50,000 square feet accelerate replacement of legacy pneumatic controls.
- Industrial Sectors:Chemical processing, food manufacturing, and cold chain logistics operators require physics-based digital twin integration that synchronizes with process simulation platforms.
- Residential Spaces:Single-family and multi-family installations focus on utility bill management and smart home integration rather than complex demand charge optimization.
- Utilities:Grid operators and load-serving entities deploy EMS as aggregation platforms for virtual power plant participation under FERC Order 2222.
Commercial buildings command the revenue base. Industrial sectors are gaining share fastest through digital twin convergence.
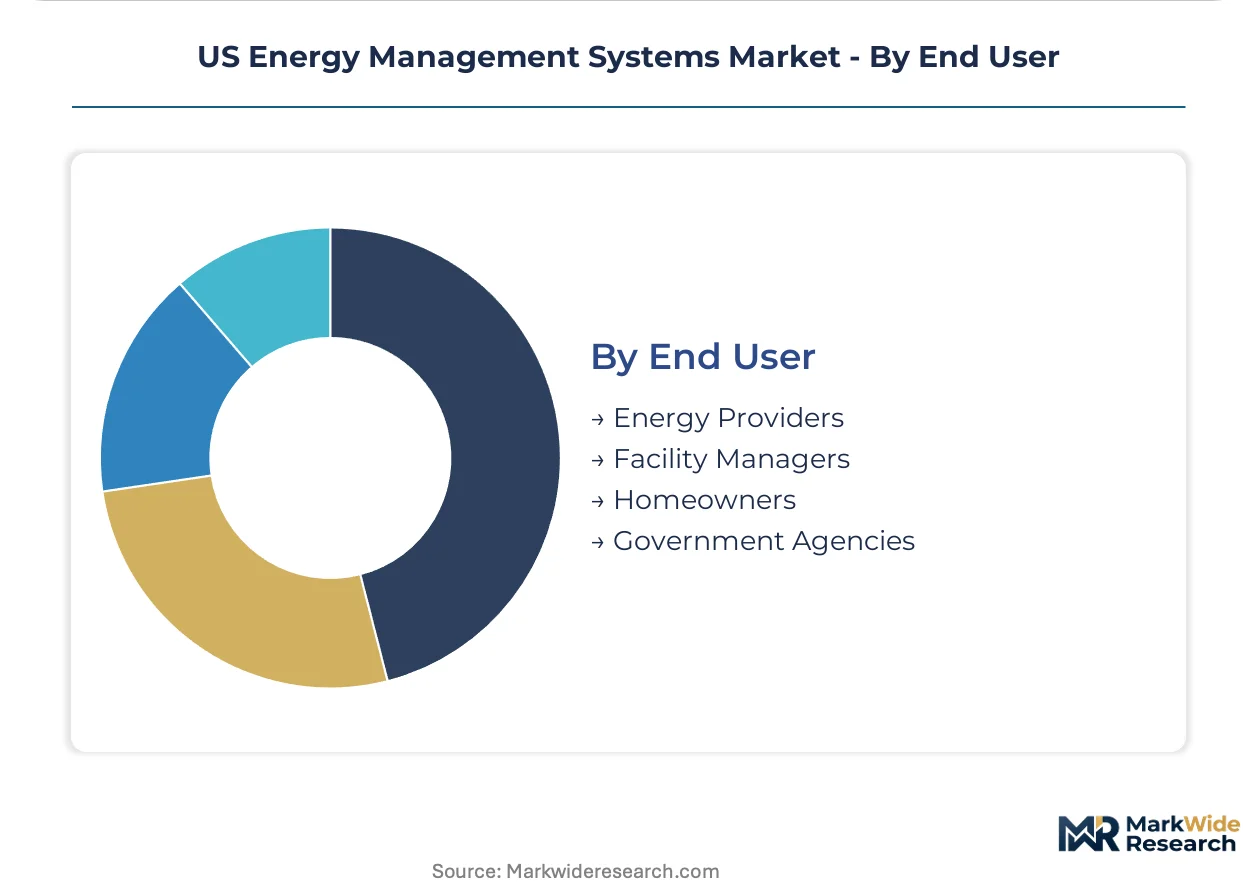
End User:
Customer organizational type determines procurement authority, financing preference, and compliance pressure intensity.
- Energy Providers:Utilities and retail energy suppliers deploy EMS platforms for grid-edge visibility and distributed resource orchestration. Texas and New York commission rulings on virtual power plant participation reshape their procurement priorities toward bidirectional revenue capture.
- Facility Managers:Third-party property management firms and corporate real estate operators prioritize interoperability with existing BACnet infrastructure and outcome-based service contracts.
- Homeowners:Residential adopters respond to utility rebate programs and time-of-use rate structures rather than regulatory mandates.
- Government Agencies:Federal, state, and municipal purchasers face Inflation Reduction Act Section 179D deduction requirements and executive order carbon reduction targets.
Facility managers command the transaction volume base. Energy providers are expanding most quickly as wholesale market participation rules mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Energy Management Systems market exhibits pronounced regional concentration driven by divergent utility rate structures, state regulatory mandates, and industrial density patterns that reshape procurement priorities across sub-national markets.
California
Automated demand response mandates under Title 24 and aggressive carbon neutrality targets accelerate EMS deployment across commercial portfolios exceeding 50,000 square feet. The California Energy Commission enforces building performance standards that hardwire sub-metering into new construction specifications. Silicon Valley data center clusters and Los Angeles commercial real estate drive premium-tier platform adoption for grid-edge optimization.
Texas
Extreme weather volatility and ERCOT market restructuring amplify demand for behind-the-meter control systems capable of bidirectional revenue capture. The Public Utility Commission of Texas enables virtual power plant participation rules that reshape EMS procurement toward aggregation-ready architectures. Houston petrochemical corridors and Dallas-Fort Worth logistics hubs anchor industrial-grade digital twin deployments.
New York
Local Law 97 carbon penalties generate compliance-driven replacement cycles for legacy pneumatic controls in Manhattan commercial stock. The New York State Department of Public Service mandates interval-grade metering for buildings above 25,000 square feet. The New York Metro corridor concentrates financial services and healthcare facility operators prioritizing cybersecurity-hardened on-premises architectures.
Pacific Northwest
Hydropower-dominated rate structures and progressive decarbonization mandates from Oregon and Washington utility commissions sustain steady EMS adoption across technology and manufacturing verticals. The Bonneville Power Administration incentivizes demand response participation that collapses payback periods for industrial control investments. Seattle and Portland metropolitan areas cluster software-native deployments targeting portfolio-scale optimization.
Southeast
Rapid commercial construction growth and utility rebate programs in Florida and Georgia expand addressable market for mid-sized facility operators previously priced out of enterprise platforms. State utility commissions in the region approve time-of-use rate pilots that elevate demand charge management value propositions. Atlanta and Miami commercial corridors concentrate third-party ownership structures displacing capital purchase pathways.
US Energy Management Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, controllers, and edge processors. The US EMS market structures around three strategic archetypes: diversified industrial conglomerates with building automation heritage, pure-play software vendors with cloud-native architectures, and energy-as-a-service operators capturing recurring revenue through performance contracts. Consolidation pressure intensifies as FERC Order 2222 collapses boundaries between efficiency software and wholesale market participation, forcing capability expansion through strategic partnerships and technology licensing rather than organic development.
Within the diversified industrial tier, Schneider Electric and Siemens AG occupy positions exemplifying integrated software-hardware strategies, while Johnson Controls International PLC represents deep building automation integration extending across HVAC, lighting, and security domains. These three anchors demonstrate how legacy control expertise translates into platform consolidation advantages as procurement shifts toward single-accountability vendor relationships.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| Honeywell International Inc. |
| Johnson Controls International PLC |
| ABB Ltd |
| General Electric Company |
| Eaton Corporation |
| Emerson Electric Company |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Taiwan-based foundry concentration in industrial-grade microcontrollers funnels pricing power toward semiconductor suppliers while compressing margins for EMS hardware vendors serving NERC CIP-constrained data center operators. This upstream bottleneck cascades into extended procurement timelines that reshape how platform vendors structure subscription versus capital purchase offerings.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade positioning for FERC Order 2222-compliant aggregation platforms, while economy tiers serve mid-market facility operators through energy-as-a-service subscriptions. Price differentiation hinges on cybersecurity hardening depth and after-sales optimization bundling. Pricing pressure stems from copper and rare earth input volatility squeezing power conditioning equipment margins. Government agencies exhibit lowest price sensitivity due to Inflation Reduction Act compliance mandates, whereas third-party facility managers face acute pressure to demonstrate demand charge reduction guarantees.
Supply Chain Analysis
Upstream feedstock dependencies center on Taiwan, South Korea, and China for microcontroller fabrication, copper refining, and rare earth magnet processing. The hardware tier draws from concentrated semiconductor foundry capacity, power quality component suppliers, and edge computing node manufacturers. Single-source vulnerability in Taiwan-based industrial microcontroller supply creates 26-32 week procurement exposure. Distribution runs through direct OEM channels for large commercial portfolios and independent service providers for mid-market energy-as-a-service deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FERC Order 2222 is collapsing traditional boundaries between efficiency software and wholesale market participation, creating a high-growth disruption window as platform vendors race to architect bidirectional revenue capture capabilities.
For Market Incumbents: Harden cybersecurity certification depth to defend against pure-play cloud-native entrants targeting NERC CIP-compliant verticals. Prioritize backward integration into edge computing hardware to secure microcontroller supply continuity against Taiwan foundry concentration. Expand energy-as-a-service financing capacity to capture mid-market facility operators migrating from capital purchase models.
For New Entrants and Emerging Players: Establish a beachhead in Texas and Florida commercial corridors where utility rate volatility amplifies demand charge management value propositions. Target 50,000-200,000 square foot facility operators previously priced out of enterprise platforms. Pursue white-label partnerships with existing building automation integrators to bypass BACnet/IP migration complexity barriers.
For Investors and Strategic Acquirers: Capital is best deployed toward software-native platforms with demonstrated virtual power plant aggregation capabilities and recurring revenue infrastructure. Long-term viability favors vendors bridging operational technology and wholesale market participation. Monitor state utility commission rulings on distributed energy resource compensation as the critical inflection signal for platform valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Virtual Power Plant Certification | FERC Order 2222 compliance unlocks capacity payment revenue streams beyond kilowatt-hour savings. |
| Edge-Native AI Deployment | Substation-level processing collapses latency constraints that previously forced cloud-centralized architectures. |
| Energy-as-a-Service Financing | Performance-linked contracts capture mid-market operators previously excluded from capital purchase pathways. |
| Digital Twin Integration | Physics-based process simulation convergence creates new optimization layers for chemical processing facilities. |
| BACnet/IP Migration Services | 1980s-era fieldbus integration expertise commands premium pricing in Local Law 97 compliance cycles. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and facility management executives; and secondary validation through EIA consumption data, FERC Order 2222 implementation filings, state utility commission rulings, and building automation industry association reports. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from Inflation Reduction Act incentive allocation patterns and commercial construction permit databases.
Forecast inputs incorporated deployment model adoption curves, state regulatory mandate phase-in schedules, and utility rate structure evolution across the projection horizon. Segmentation dimensions modeled include product type tier, technology architecture, application environment, and end-user organizational category. CAGRs were derived through logistic diffusion curves fitted to historical adoption patterns in comparable building automation technology markets, with cross-validation against equipment vendor revenue disclosures and utility demand response program enrollment trajectories.
Sensitivities concentrate around semiconductor supply continuity, state-level building performance standard enforcement intensity, and virtual power plant market rule finalization timelines. Cross-checking against EIA commercial building energy consumption surveys and state utility commission interconnection queue data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Smart Cooling Systems Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
Smart Utilities Management Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
India Home Ventilation System Market
Energy Management Systems
Meter Data Management System Market
Energy Management Systems
North America Home Energy Management System (HEMS) Market
Energy Management Systems
North America Residential Lighting Control System Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Advanced Server Energy Monitoring Tools Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Smart Climate Control Market