
 Global Data Colocation Market | 2026-2036
Global Data Colocation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Colocation Market Foresight
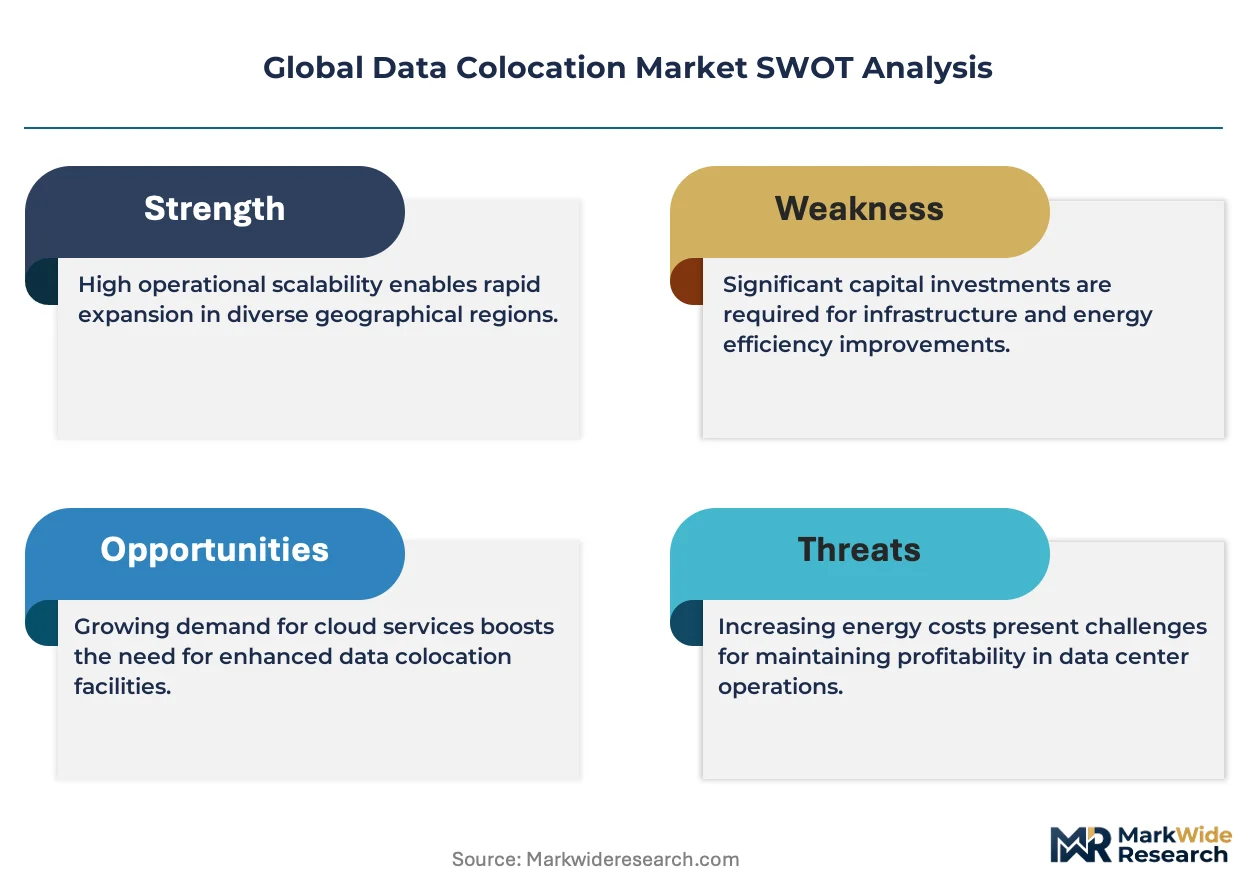
Immersion cooling fluid chemistry is shifting from synthetic hydrocarbons to dielectric mineral oils in hyperscale deployments, cutting energy intensity for thermal management by roughly one-third. Equinix leverages interconnection density across its metro campuses to sustain premium pricing in financial exchanges. Digital Realty anchors global capacity through its PlatformDIGITAL architecture, competing on cross-connect velocity rather than raw megawatt scale. CyrusOne specializes in powered-shell deliveries with shorter commissioning cycles, differentiating against build-to-suit timelines from generalist operators.
Data colocation denotes the commercial practice of leasing secure, environmentally controlled physical space—measured in rack units, cages, or dedicated suites—within multi-tenant facilities where power density ranges from 5 kW to 50 kW per rack and redundant substations feed dual-path electrical architecture, purpose-built to host computing, storage, and networking equipment for organizations avoiding capital-intensive private facility construction. Hybrid colocation deployments lead volume growth as enterprises straddle on-premises control with burst capacity into leased footprints, while cage space commands outsized margins due to physical segregation requirements from financial and healthcare tenants. Rack space remains the mature workhorse segment, though remote hands services are expanding fastest as edge locations proliferate beyond easy technician reach.
The U.S. EPA's ENERGY STAR certification for data centers and the EU's Energy Efficiency Directive establish operational baselines that filter market access toward operators with documented power usage effectiveness below 1.4. China's MIIT imposes GB-standard efficiency thresholds on new facility approvals, compressing viable supply in Beijing and Shanghai to retrofit-ready brownfield sites. India's CEA mandates renewable purchase obligations for large commercial consumers, redirecting colocation procurement toward operators with captive solar or wind offtake agreements. Stakeholders must weigh sovereign data localization mandates against the operational complexity of fragmented national compliance regimes.
Market Dynamics
Hyperscale cloud providers are compressing commissioning cycles from 24 months to 12 months, forcing third-party operators to pre-position powered shells and modular substations ahead of signed leases. This velocity imperative is restructuring capital deployment patterns across the colocation value chain.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating retrofit demand for low-global-warming-potential cooling systems in Frankfurt and Amsterdam facilities.
- AI training clusters:GPU-intensive workloads from autonomous vehicle developers and large language model operators are pulling 30-50 kW rack densities into leased footprints previously spec'd at 10 kW.
- India's CEA renewable mandates:Commercial consumers above 100 MW must source 40% of power from solar or wind, redirecting colocation procurement toward operators with captive renewable offtake.
Market Restraints
- Copper and electrical steel volatility:Transformer lead times have extended to 80-100 weeks, constraining dual-path substation delivery for new builds.
- Limited qualified EPCs:Mission-critical data center construction concentrates among a handful of specialized contractors in Northern Virginia and Singapore, creating bidding congestion.
- Grid interconnection queues:Utility substation upgrades in London and Dublin face 36-48 month delays, freezing expansion timelines regardless of capital availability.
Strategic Opportunities
- Saudi Arabia's giga-project corridor:NEOM and King Salman Energy Park are greenfield zones with subsidized land and power, attracting pre-commitment from cloud operators seeking Middle East latency positioning.
- Liquid cooling retrofits:Dielectric mineral oil immersion systems are opening upgrade revenue streams in 5-10 year-old facilities previously built for air-cooled densities.
- Japan's METI carbon-neutral data center certification:The 2030 compliance deadline is creating premium pricing tiers for operators with documented PUE below 1.2 and 100% renewable matching.
Industry Challenges
- Critical facilities engineering talent scarcity:Experienced commissioning engineers for 400 kV substations and hyperscale cooling loops command 40% salary premiums, stretching operator opex.
- Legacy BMS integration complexity:Brownfield facilities in London and Tokyo require middleware layers to bridge 1990s-era building management systems with modern DCIM platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Colocation Market |
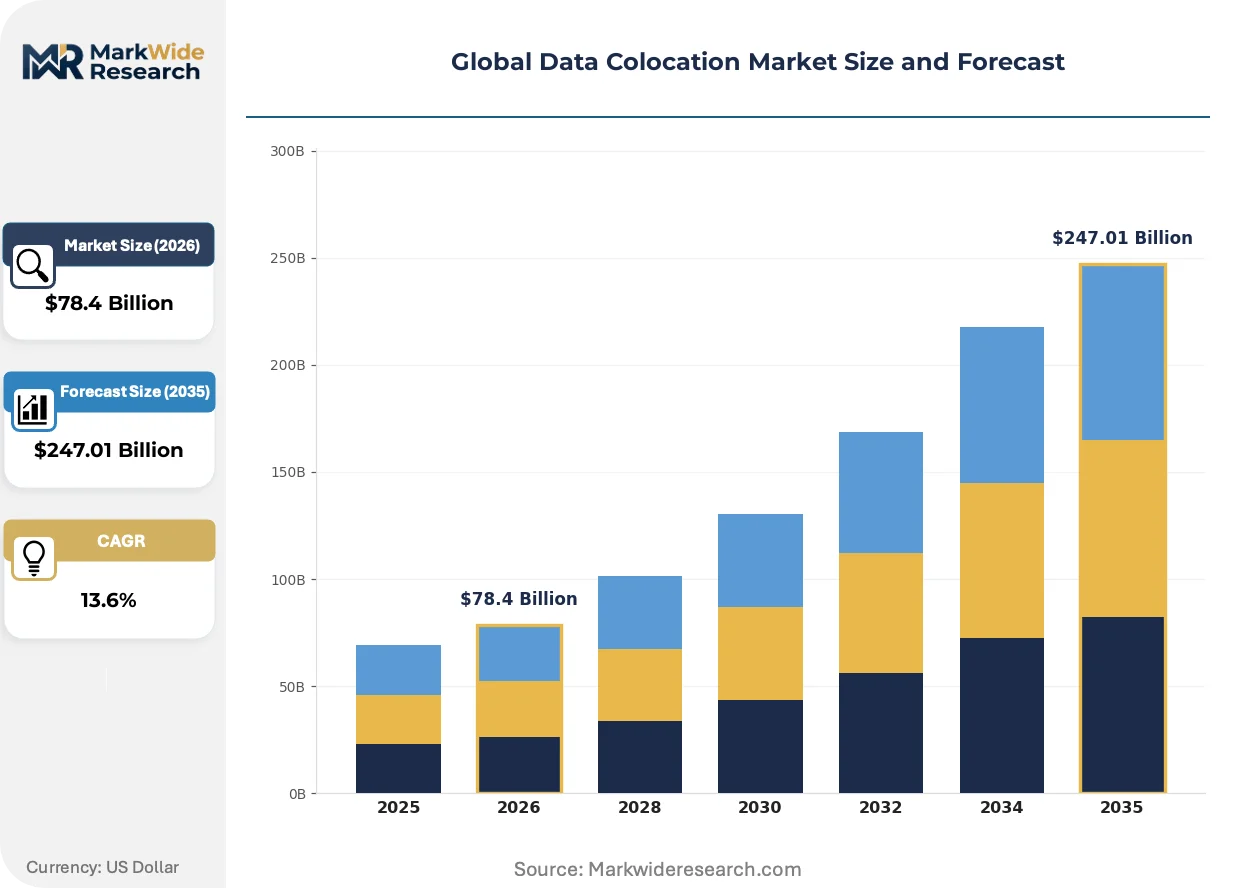
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Private Data Centers, Managed Services, Hybrid Colocation, Dedicated Hosting Solution: Rack Space, Cage Space, Cross Connects, Remote Hands, Power Provisioning Application: Cloud Service Providers, Content Delivery Networks, Financial Exchanges, IT Enterprises End User: Telecommunications Firms, Media Companies, Government Agencies, Educational Institutions |
| Companies Covered | Equinix, Digital Realty, NTT Global Data Centers, CyrusOne, ST Telemedia Global Data Centres, QTS Data Centers, China Telecom, Iron Mountain, CoreSite Realty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Colocation Market Shifts & Advancements
Cooling technology and power architecture are converging to support density thresholds that exceed legacy air-cooled limits. Operators are re-engineering facility designs around thermal and electrical modularity rather than static capacity planning.
Single-phase immersion cooling using engineered dielectric mineral oils is modularizing deployment patterns for AI and HPC workloads. Hyperscale tenants in Northern Virginia and Singapore are specifying tank-based cooling as standard for racks above 40 kW. This approach is compressing mechanical infrastructure footprints by two-thirds while eliminating chilled water loops entirely.
Europe's F-Gas Regulation is mandating refrigerant phase-downs that eliminate R-410A and R-134a from new data center cooling systems by 2030. Operators in Frankfurt and Amsterdam are retrofitting existing facilities with CO2-based chillers and adiabatic cooling to maintain leasing eligibility. Financial services tenants are embedding F-Gas compliance clauses into 10-year lease agreements, transferring retrofit risk to facility owners.
Enterprise procurement teams are consolidating vendor relationships around operators offering bundled cross-connect and cloud exchange access. Buyers in healthcare and capital markets are prioritizing facilities with on-site AWS, Azure, and Google Cloud presence over standalone colocation. This preference consolidation is visible most acutely in Singapore, where cloud-adjacent cage space commands 25% rate premiums over generic wholesale.
Global Data Colocation Market Segmentation
Segmentation in data colocation reveals how certification burdens, power density requirements, and latency sensitivity fragment procurement patterns across tenant types. Understanding these divisions exposes where margin concentrates and where commoditization threatens operator returns.
Deployment:
EPA ENERGY STAR certification filters private data center deployments, while hybrid colocation carries dual compliance obligations across on-premises and leased footprints. Managed services require SOC 2 Type II attestation for financial services tenants.
- Private Data Centers:Single-tenant facilities where enterprises retain full operational control over 10-50 MW deployments. Demand concentrates among autonomous vehicle developers in Northern Virginia seeking sub-10 millisecond latency to cloud training clusters, though transformer lead times now stretch beyond facility construction schedules.
- Hybrid Colocation:Split architectures combining owned core infrastructure with burst capacity into leased footprints. Financial exchanges in Frankfurt and Singapore are expanding hybrid footprints to meet F-Gas Regulation cooling mandates while preserving on-premises matching engine control.
- Managed Services:Operator-delivered server administration, patching, and monitoring layered atop physical space. Healthcare systems in the US embed HIPAA business associate agreements into managed service contracts, raising procurement complexity.
- Dedicated Hosting:Single-tenant server leasing without shared infrastructure exposure. Media companies prioritize dedicated hosting for content ingestion nodes requiring guaranteed bandwidth symmetry.
Leading the category by volume: Hybrid Colocation. Growing fastest: Managed Services.
Solution:
Margin stratification runs deepest in physical segregation tiers, where cage space commands rate premiums against standardized rack offerings. Remote hands services carry technician certification requirements that vary by jurisdiction.
- Cage Space:Physically segregated enclosures with dedicated access controls for 4-12 rack deployments. Financial exchanges in London and Singapore pay 20-35% premiums for cage space to satisfy regulatory audit requirements for physical asset separation.
- Rack Space:Standardized 42U-52U vertical mounting in shared halls, the baseline unit of colocation commerce. Cloud service providers in Northern Virginia consume rack space in 500-unit blocks, compressing per-unit pricing through volume commitments.
- Cross Connects:Physical fiber or copper interlinks between tenant cages and cloud on-ramps. Content delivery networks in Frankfurt prioritize facilities with dense cross-connect fabrics to minimize interconnection latency.
- Remote Hands:Technician-delivered reboot, cable, and diagnostic services for unmanned edge locations. Telecommunications firms expanding into secondary Indian cities depend on remote hands to avoid local hiring.
- Power Provisioning:Contracted megawatt blocks with 99.999% uptime SLAs and dual-path substation feeds. GPU cluster operators in Amsterdam now specify 50 kW per rack power provisioning, triple legacy air-cooled densities.
Cage space captures the highest margin per square meter. Remote hands services are climbing the fastest as edge proliferation outpaces technician availability.
Application:
Application type dictates cooling architecture: AI training clusters require immersion systems, while financial matching engines prioritize redundant substations over density.
- Cloud Service Providers:Hyperscale tenants leasing 5-50 MW footprints for regional availability zones. AWS, Azure, and Google Cloud pre-commit to powered shells in Saudi Arabia's NEOM corridor to secure Middle East latency positioning ahead of competitors.
- Financial Exchanges:Low-latency matching engines and market data distribution nodes. Tokyo and London exchanges specify facilities within 500 meters of fiber exchanges, accepting 30% rate premiums for microsecond advantages.
- Content Delivery Networks:Distributed caching nodes for video and software delivery. Netflix and Akamai prioritize secondary European markets with renewable power matching to satisfy EU Green Deal procurement clauses.
- IT Enterprises:General corporate workloads migrating from owned facilities. Manufacturing enterprises in Germany select colocation operators with documented PUE below 1.3 to align with supply chain carbon disclosure requirements.
Cloud service providers dominate committed megawatts. Financial exchanges show the steepest expansion trajectory as electronic trading volumes compound.
End User:
End user type determines data sovereignty exposure: government agencies face localization mandates, while media companies prioritize bandwidth economics.
- Telecommunications Firms:Mobile core network functions and edge computing infrastructure. Singapore carriers are consolidating distributed central offices into carrier-neutral colocation to reduce real estate overhead.
- Government Agencies:Classified and unclassified workloads with sovereign data requirements. India's Ministry of Defence mandates domestic colocation for strategic data, excluding cross-border facilities.
- Media Companies:Post-production rendering and global content distribution. Studios in Los Angeles lease high-density cages for real-time collaborative editing, requiring sub-5 millisecond synchronization.
- Educational Institutions:Research computing and administrative systems. University consortia in the UK pool procurement to negotiate collective renewable power matching with colocation operators.
Telecommunications firms lead the category by committed power. Government agencies are expanding most quickly as classified cloud migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud providers concentrate leasing activity in Northern Virginia, Singapore, and Frankfurt, with transformer lead times and F-Gas cooling mandates now dictating site selection timelines.
United States
Autonomous vehicle developers and AI training cluster operators drive 30-50 kW rack density demand across Northern Virginia's Data Center Alley. The EPA's ENERGY STAR certification filters private facility deployments toward operators with documented PUE below 1.4. Chicago and Dallas-Fort Worth emerge as secondary markets where CyrusOne and Digital Realty pre-position powered shells to capture hyperscale overflow.
Germany
Financial exchanges in Frankfurt's Rhine-Main corridor expand hybrid footprints to meet EU F-Gas Regulation cooling mandates while preserving on-premises matching engine control. The country's national efficiency regulator imposes operational baselines that compress viable supply to retrofit-ready brownfield sites in Berlin and Munich. Manufacturing enterprises select colocation operators with documented PUE below 1.3 to align with supply chain carbon disclosure requirements.
Singapore
Cloud-adjacent cage space commands 25% rate premiums over generic wholesale as enterprise procurement teams prioritize facilities with on-site AWS, Azure, and Google Cloud presence. The country's national telecommunications regulator governs data sovereignty frameworks that redirect government workloads toward domestic facilities. ST Telemedia Global Data Centres anchors capacity expansion to capture carrier-neutral consolidation from mobile network operators.
India
The CEA mandates renewable purchase obligations for commercial consumers above 100 MW, redirecting colocation procurement toward operators with captive solar or wind offtake agreements in Mumbai and Chennai. State-level data localization requirements from the Ministry of Defence exclude cross-border facilities for strategic workloads. NTT Global Data Centers and domestic operators compete on documented renewable matching to satisfy enterprise procurement clauses.
Saudi Arabia
NEOM and King Salman Energy Park attract pre-commitment from cloud operators seeking Middle East latency positioning with subsidized land and power. The national investment ministry governs giga-project corridor development with streamlined permitting for hyperscale deployments. Equinix and Digital Realty evaluate powered shell commitments to anchor regional platform availability ahead of competitor entry.
Global Data Colocation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with interconnection density and powered shell velocity emerging as distinct competitive vectors. The vendor base concentrates among facility operators with dual-path substation expertise and documented compliance with EU F-Gas and EPA ENERGY STAR regimes. Three archetypes dominate: metro campus interconnectors, wholesale powered shell specialists, and carrier-neutral platform architects. M&A activity targets brownfield retrofit capacity in London and Tokyo, while strategic partnerships secure transformer allocation priority amid 80-100 week lead times.
Within the metro campus tier, Equinix leverages interconnection density across global facilities to sustain premium pricing in financial exchange adjacencies. Digital Realty anchors cross-border capacity through platform architecture competing on connect velocity rather than raw megawatt scale. CyrusOne occupies a position among powered shell specialists with shorter commissioning cycles, differentiating against build-to-suit timelines from generalist operators. These three exemplify how competitive positioning converges on thermal modularity and electrical redundancy as AI workloads displace legacy air-cooled densities.
| Leading Market Players |
|---|
| Equinix |
| Digital Realty |
| NTT Global Data Centers |
| CyrusOne |
| ST Telemedia Global Data Centres |
| QTS Data Centers |
| China Telecom |
| Iron Mountain |
| CoreSite Realty |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation compliance gates both qualified supply and premium-tier pricing access, as operators in Frankfurt and Amsterdam retrofit facilities with CO2-based chillers to maintain leasing eligibility while financial services tenants embed compliance clauses into long-term agreements. This environmental mandate stratifies the vendor base between certified operators commanding rate premiums and legacy facilities facing accelerated obsolescence.
Pricing Analysis
The volume-versus-margin split separates hyperscale cloud providers consuming rack space in 500-unit blocks from financial exchanges paying 20-35% premiums for physically segregated cage space. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and power density specifications, with cloud-adjacent facilities in Singapore capturing 25% rate premiums over generic wholesale. Cost compression in standard rack tiers intensifies because transformer lead times stretch substation delivery, while GPU cluster operators show least price sensitivity as they specify 50 kW per rack power provisioning.
Supply Chain Analysis
Reverse-logistics flows for transformer refurbishment and cooling system component recovery are extending equipment lifecycles as original equipment lead times stretch beyond facility construction schedules. Supply concentrates in the United States, Germany, and Singapore, where specialized EPC contractors for mission-critical data center construction face bidding congestion. Copper and electrical steel dependencies, alongside 80-100 week transformer procurement timelines, create single-source vulnerability for dual-path substation architecture. Distribution runs through direct operator-tenant contracting for hyperscale commitments, with modular component sourcing from electrical infrastructure specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where transformer allocation priority and F-Gas retrofit capital requirements are forcing weaker capitalized operators toward acquisition or exit.
For Market Incumbents: Extend interconnection density advantages in metro campuses like Northern Virginia and Singapore to sustain premium pricing against wholesale competitors. Pre-position powered shells in secondary markets including Chicago and Dallas-Fort Worth to capture hyperscale overflow demand. Secure captive renewable offtake agreements to satisfy India's CEA mandates and Germany's supply chain carbon disclosure requirements. For New Entrants and Emerging Players: Begin with liquid cooling retrofit services for 5-10 year-old facilities in London and Tokyo, where legacy BMS integration complexity deters incumbent expansion. Target Saudi Arabia's NEOM corridor for greenfield powered shell development, leveraging subsidized land and power to anchor regional platform availability. Lead with immersion cooling deployment expertise as AI training clusters displace legacy air-cooled densities. For Investors and Strategic Acquirers: Pre-commitment volume from hyperscale cloud providers to Saudi giga-projects is the leading indicator that Middle East latency positioning will command sustained rate premiums. Brownfield retrofit capacity in European F-Gas compliance zones represents the highest-conviction acquisition archetype. Monitor transformer lead time normalization as the signal for resumed greenfield development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Powered Shell Pre-Positioning | Captures hyperscale overflow in Chicago and Dallas-Fort Worth secondary markets. |
| Liquid Cooling Retrofit Deployment | Opens upgrade revenue streams in aging Frankfurt and Amsterdam facilities. |
| Captive Renewable Offtake Agreements | Satisfies India's CEA mandates for Mumbai and Chennai procurement. |
| Metro Campus Interconnection Expansion | Sustains premium pricing for Equinix in financial exchange adjacencies. |
| F-Gas Compliance Certification Investment | Maintains leasing eligibility for Frankfurt operators under EU phase-down rules. |
Research Methodology
Document review covered SEC filings from publicly traded operators, hyperscaler capex disclosures, and EU regulatory filings, complemented by interviews with data center development executives, critical facilities engineers, enterprise procurement officers, and EPC contractors. Secondary validation drew from FERC interconnection queue data, EPA ENERGY STAR certification records, and customs data for electrical infrastructure imports. Bottom-up facility-level capacity tracking and top-down regional demand modeling were triangulated to anchor volume estimates.
Historical commissioning timelines were cross-referenced against panel input from substation engineers and cooling system specialists to model deployment velocity across the projection horizon. Segmentation dimensions included deployment type, solution tier, application workload, and end-user vertical, with power density specifications and certification status as industry-specific forecast inputs. CAGRs were derived from facility pipeline analysis and tenant commitment tracking.
Underlying measurement precision varies by segment; hyperscale cloud provider commitments carry tighter precision than enterprise hybrid migration forecasts. Projections reflect assumptions around transformer lead time normalization, F-Gas retrofit capital availability, and grid interconnection queue clearance. Practitioners should monitor pre-commitment volumes to Saudi giga-projects and renewable offtake agreement signings for early signals of regional competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
Switzerland Data Center Server Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
Indonesia Data Center Physical Security Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
France Data Center Server Market
Data Center Infrastructure
APAC Green Data Center Market