
 Smart Air Cleaners Market | 2026-2036
Smart Air Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Air Cleaners Market Insights
EPA indoor air quality guidelines are decoupling certification requirements from legacy testing protocols, raising engineering barriers for new entrants. Honeywell International Inc. leverages its building automation heritage to bundle air cleaners with HVAC retrofit contracts. Dyson sustains premium positioning through proprietary bladeless airflow architectures and direct-to-consumer channel control. Xiaomi anchors volume tiers by integrating purifiers into its Mi Home ecosystem, competing on price-accessible connectivity rather than filtration performance alone.
Smart air cleaners combine sensor arrays, connected control modules, and multi-stage filtration media to monitor and remediate airborne particulates, volatile organic compounds, and biological contaminants in enclosed spaces. HEPA-integrated units dominate value capture due to medical-grade certification requirements, while UV-C augmentation represents the fastest-expanding technology layer as hospitals and schools mandate pathogen suppression. Portable form factors lead residential volume, though commercial deployments of ceiling-mounted and wall-mounted systems command superior margin pools through installation-service bundling and centralized facility management integration.
FCC certification governs wireless connectivity modules in US-sold units, while EPA Energy Star labeling shapes procurement criteria for institutional buyers; China's GB standards and MIIT IoT security rules dictate product architecture for Asia-bound manufacturing. The EU F-Gas Regulation and MDR-equivalent performance claims oversight in Europe are tightening refrigerant-adjacent cooling integrations and medical-adjacent marketing assertions. Stakeholders must monitor divergence between regional electromagnetic compliance and data privacy frameworks as voice control and air quality data telemetry become standard feature requirements.
Market Dynamics
EPA's tightened particulate matter standards are forcing manufacturers to redesign filtration architectures entirely, decoupling certification from legacy testing protocols and raising engineering barriers for new entrants. This regulatory compression is concentrating competitive advantage among firms with existing HVAC integration capabilities and sensor fusion expertise.
Growth Catalysts
- Indoor Air Quality Mandates:EPA Energy Star labeling shapes procurement criteria for institutional buyers across US school districts and healthcare systems, creating specification-driven demand pools.
- China:Urban pollution concerns and smart home integration are driving premium product uptake in tier-one cities, with MIIT IoT security rules accelerating ecosystem lock-in.
- UV-C Augmentation:Pathogen suppression requirements in hospitals and schools are expanding the fastest-growing technology layer beyond HEPA filtration alone.
Market Restraints
- HEPA Media Supply Concentration:Glass microfiber production clusters in Germany and Japan create input vulnerability for manufacturers without backward integration into filtration media.
- FCC Certification Friction:Wireless connectivity modules in US-sold units face electromagnetic compliance timelines that extend product launch cycles by 8-14 months.
- Refrigerant-Adjacent Cooling Bans:EU F-Gas Regulation restricts integrated cooling architectures, eliminating a margin-expanding feature set for Europe-bound product lines.
Strategic Opportunities
- India:BIS certification gaps in residential air quality devices create first-mover advantage for firms establishing local testing partnerships before mandatory standards finalize.
- Voice Control Convergence:Integration of air quality telemetry with smart speaker ecosystems opens channel partnerships beyond traditional appliance retail.
- Outcome-Based Facility Contracts:Ceiling-mounted commercial systems bundled with centralized facility management integration command superior margin pools through installation-service anchoring.
Industry Challenges
- Sensor Calibration Talent Scarcity:PM2.5 and VOC sensor fusion engineering requires rare cross-disciplinary expertise in atmospheric chemistry and embedded systems.
- Multi-Jurisdiction Certification Parallel Processing:Simultaneous FCC, CE marking, and GB standard compliance creates timeline coordination complexity for product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Air Cleaners Market |
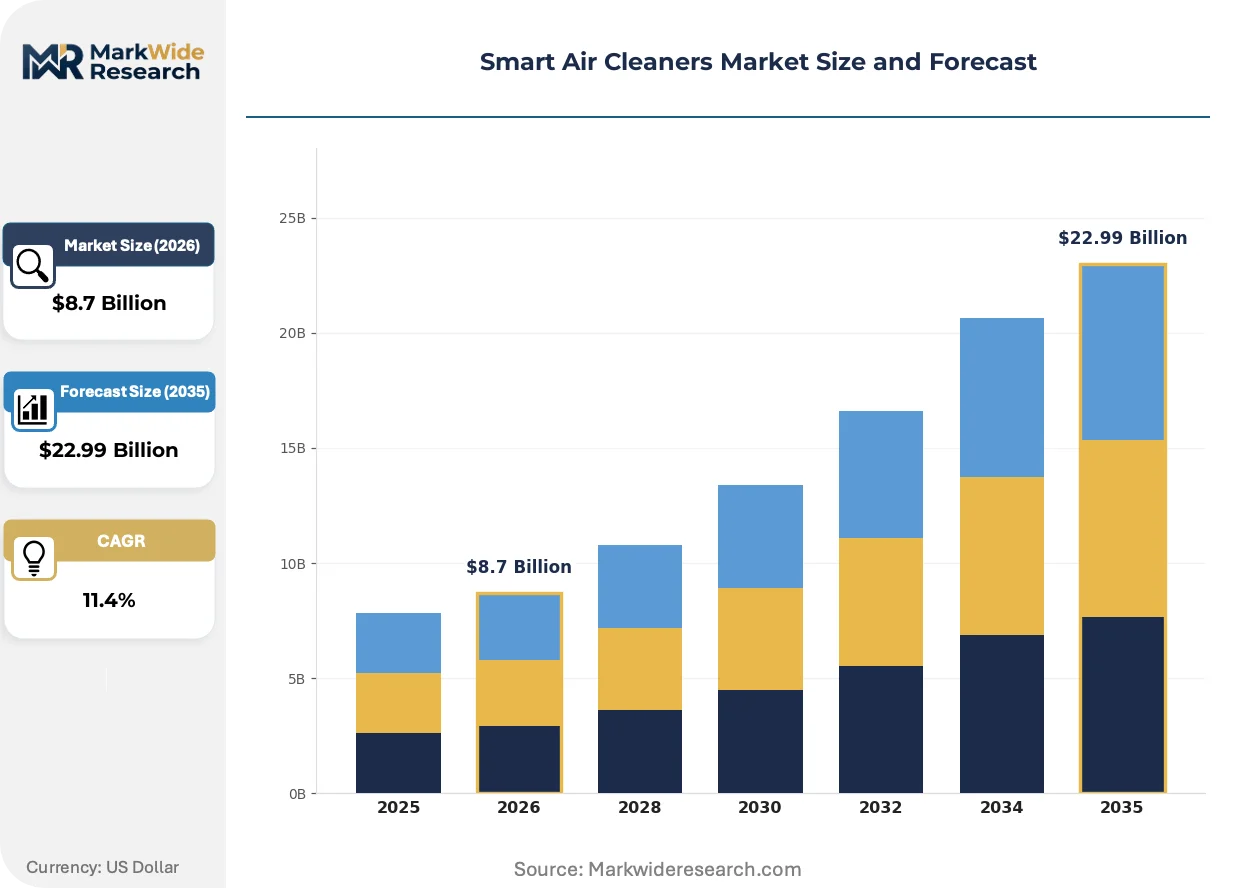
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wall-mounted, Ceiling-mounted, Smart IoT Technology: HEPA, UV-C, Activated Carbon, Ionizer End User: Residential, Commercial, Industrial, Educational Feature: Wi-Fi Enabled, Voice Control, Air Quality Monitoring, Mobile App Integration |
| Companies Covered | Honeywell International Inc., Koninklijke Philips N.V., Dyson, Xiaomi, Blueair, Coway Co., Ltd., Sharp Corporation, LG Electronics, Daikin Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Air Cleaners Market Trends and Innovations
Filtration architectures are fragmenting into stackable subsystems as manufacturers race to accommodate diverging regional contaminant profiles and certification requirements. This decomposition is enabling faster product iteration but complicating supply chain coordination.
Multi-stage filtration media is modularizing into discrete cartridge units with standardized mechanical interfaces. Hospitals and premium residential developers are adopting these swappable configurations to reduce downtime during maintenance cycles. This architecture is modularizing the traditional integrated filter housing, compressing replacement part margins while expanding recurring revenue attachment rates.
EU F-Gas Regulation and MDR-equivalent performance claims oversight are tightening refrigerant-adjacent cooling integrations and medical-adjacent marketing assertions in Europe. Manufacturers must now separate cooling functionality from air purification in product architecture or pursue separate certification tracks. Wall-mounted commercial systems without cooling integration are gaining specification share in German and French institutional procurement.
Direct-to-consumer channel control is displacing traditional appliance retail for premium positioning, with buyers expecting air quality data transparency through mobile applications. This shift is most visible in China and South Korea, where Mi Home-style ecosystem integration creates switching costs that brick-and-mortar channels cannot replicate. Traditional distributors are responding with white-label private label programs to retain shelf relevance.
Smart Air Cleaners Market Segmentation
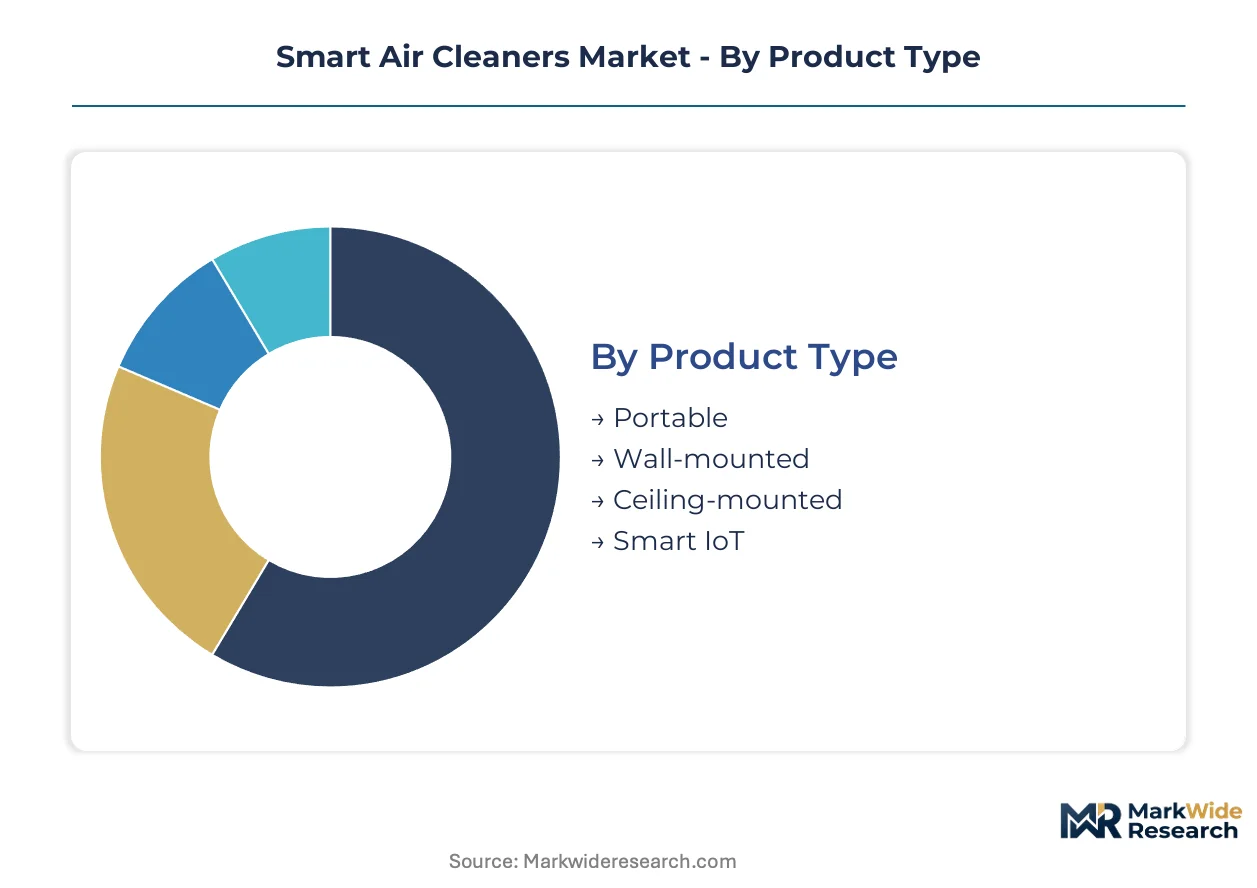
Smart air cleaner segmentation reflects divergent engineering priorities across deployment contexts. Product architecture, filtration technology, and connectivity specifications determine margin capture and regulatory compliance pathways.
Product Type:
Physical form factor dictates installation complexity, sensor placement, and airflow engineering requirements.
- Portable:Freestanding units with castor-mounted chassis dominate residential volume. Demand concentrates in Chinese tier-one cities and US suburban markets where renters prioritize relocation flexibility over fixed infrastructure.
- Ceiling-mounted:Recessed ducting integration enables whole-room circulation without floor footprint consumption. Newer deployment is concentrated in German and French healthcare facilities pursuing centralized facility management integration.
- Wall-mounted:Bracket-fixed systems serve commercial retrofits where floor space commands premium lease rates. These units climb fastest in South Korean office towers and Japanese mixed-use developments.
- Smart IoT:Ecosystem-native architectures with embedded edge computing and API-accessible telemetry. Mature deployment sits with portable form factors. Newer deployment is concentrated in ceiling-mounted commercial systems.
Mature deployment sits with portable units. Newer deployment is concentrated in ceiling-mounted commercial systems.
Technology:
Filtration modality selection determines certification tier, maintenance cadence, and pathogen suppression claims.
- HEPA:Glass microfiber media capturing 99.97% of 0.3-micron particles remains the medical-grade baseline. EPA Energy Star procurement criteria and Chinese hospital specifications sustain demand concentration despite supply chain bottlenecks in German and Japanese media production.
- UV-C:Germicidal irradiation at 253.7 nanometers augments filtration with biological inactivation. US school districts and NHS Trust procurement mandates are accelerating specification fastest.
- Activated Carbon:Porous adsorption media targeting volatile organic compounds and odor molecules. These cartridges gain share in South Korean premium residential developments and UAE hospitality fit-outs.
- Ionizer:Corona discharge generating charged particles for electrostatic precipitation. Mature deployment sits with HEPA-integrated systems. Newer deployment is concentrated in UV-C augmentation layers.
Legacy dominance rests with HEPA certification. Steepest expansion trajectory belongs to UV-C augmentation as institutional pathogen suppression mandates proliferate.
End User:
Buyer sophistication and specification authority vary sharply across deployment contexts.
- Residential:Individual purchase decisions driven by smart home ecosystem compatibility and mobile application transparency. Volume concentrates in Chinese Mi Home integration and US direct-to-consumer channels.
- Commercial:Facility manager procurement with HVAC retrofit bundling and service contract anchoring. These deployments command superior margin pools through installation complexity and centralized management integration.
- Educational:District-level specification with EPA indoor air quality guideline compliance as threshold criteria. US K-12 systems and UK academy trusts are expanding ceiling-mounted procurement fastest.
- Industrial:Process-critical contamination control in semiconductor fabrication and pharmaceutical manufacturing. Mature deployment sits with commercial office fit-outs. Newer deployment is concentrated in educational procurement.
Revenue concentration favors commercial specifications. Volume expansion is accelerating fastest in educational procurement.
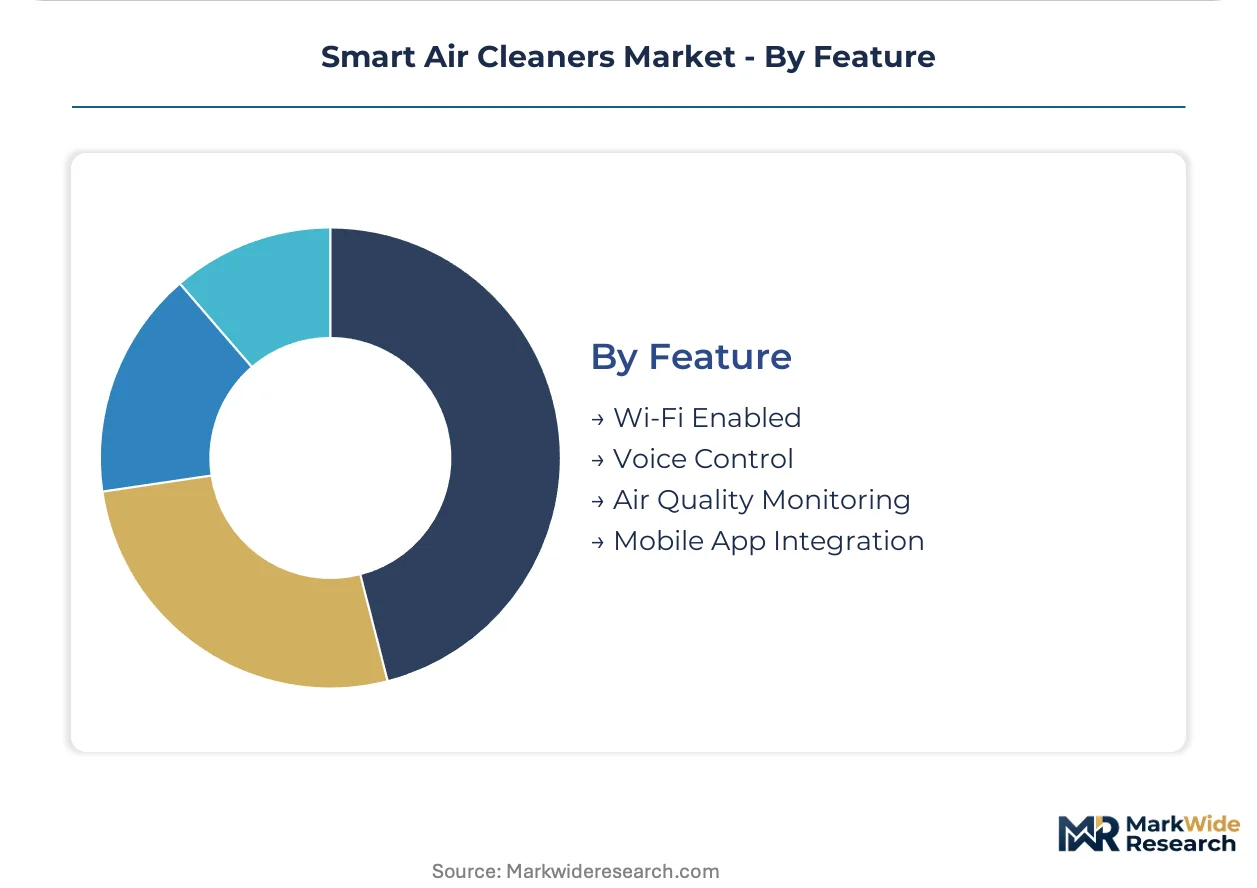
Feature:
Connectivity layer selection determines ecosystem lock-in potential and data telemetry architecture.
- Air Quality Monitoring:PM2.5, VOC, and CO2 sensor arrays with real-time display and threshold alerting. Demand clusters in Chinese premium residential and German institutional specifications where transparency requirements are tightening.
- Wi-Fi Enabled:802.11 connectivity enabling remote control and firmware updates. FCC certification timelines extend launch cycles but remain table stakes for US market entry.
- Mobile App Integration:Native iOS and Android control interfaces with historical data visualization and filter replacement scheduling. These capabilities expand recurring revenue attachment in South Korean and Chinese ecosystem-locked deployments.
- Voice Control:Alexa, Google Assistant, and Siri integration for hands-free operation. Mature deployment sits with Wi-Fi enablement. Newer deployment is concentrated in voice control convergence with smart speaker ecosystem partnerships.
Baseline functionality centers on Wi-Fi connectivity. Feature differentiation is migrating fastest toward voice control integration and air quality telemetry transparency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta free-trade zones concentrate smart air cleaner manufacturing, with tax incentives drawing component suppliers and final assembly operations into clustered industrial parks.
China
Urban pollution concerns in Beijing and Shanghai drive premium residential uptake, with MIIT IoT security rules accelerating ecosystem lock-in for connected devices. GB standards compliance mandates reshape product architecture for domestic and export-bound manufacturing. Shenzhen and Guangzhou anchor the hardware supply chain, where sensor module vendors cluster near final assembly facilities.
United States
EPA Energy Star labeling shapes procurement across school districts and healthcare systems, creating specification-driven demand pools for institutional buyers. FCC certification timelines extend wireless-enabled product launches by 8-14 months. California's South Coast Air Quality Management District enforces the nation's strictest indoor air guidelines, compressing product qualification windows for manufacturers targeting West Coast distribution.
Germany
EU F-Gas Regulation eliminates refrigerant-adjacent cooling integrations from Europe-bound product lines, forcing architecture separation. Wall-mounted commercial systems without cooling functionality gain specification share in German healthcare procurement. Stuttgart and Munich host building automation integrators bundling air cleaners with HVAC retrofit contracts for facility management clients.
Japan
METI efficiency standards and JIS certification requirements sustain premium positioning for domestic manufacturers. Tokyo and Osaka mixed-use developments accelerate wall-mounted commercial deployments where floor space commands premium lease rates. Sharp Corporation and domestic rivals leverage direct-to-consumer channel control through appliance retail networks.
South Korea
Seoul Capital Area office towers drive ceiling-mounted system adoption with centralized facility management integration. MFDS-equivalent performance oversight tightens medical-adjacent marketing claims. Busan-Ulsan manufacturing clusters supply filtration media components to regional assembly operations.
Smart Air Cleaners Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Building automation heritage enables HVAC bundling advantages for diversified industrial groups. Three archetypes dominate: ecosystem-locked consumer electronics platforms, premium direct-to-consumer specialists, and facility management integrators. Competitive moves concentrate on strategic partnerships for sensor fusion capabilities and geographic licensing for regulatory compliance acceleration.
Within the diversified conglomerate tier, Honeywell International Inc. and LG Electronics occupy positions shaped by building automation integration capabilities. Dyson exemplifies the premium direct-to-consumer archetype through proprietary industrial design and channel control. Xiaomi anchors the ecosystem-locked volume tier, competing on price-accessible connectivity rather than filtration performance differentiation alone.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Koninklijke Philips N.V. |
| Dyson |
| Xiaomi |
| Blueair |
| Coway Co., Ltd. |
| Sharp Corporation |
| LG Electronics |
| Daikin Industries, Ltd. |
| Others |
Pricing and Supply Chain Analysis
EPA Energy Star procurement criteria for US school districts and healthcare systems are compressing product qualification windows, forcing manufacturers to absorb certification costs or forfeit institutional contracts. This specification-driven demand concentrates pricing power among firms with pre-qualified filtration architectures and backward integration into sensor modules.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to FCC-certified wireless modules needed for US market entry, while spot inventory of HEPA glass microfiber media trades at discounts when German and Japanese producers flush excess capacity. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade HEPA-UV-C systems from residential Wi-Fi-enabled units and basic ionizer models. Cost compression in the economy tier is intensifying because Xiaomi ecosystem players are subsidizing hardware to capture recurring filter subscription revenue. Educational procurement committees exhibit highest price sensitivity due to district-level budget constraints, while German healthcare facility managers prioritize total cost of ownership over unit acquisition price.
Supply Chain Analysis
HEPA glass microfiber production rests on German and Japanese specialty manufacturers, with sensor module assembly concentrated in Shenzhen and Guangzhou industrial parks. Critical inputs include PM2.5 laser sensors from South Korean vendors, activated carbon from Southeast Asian coconut shell processors, and UV-C LED chips from Taiwanese epitaxy foundries. Single-source vulnerability in German HEPA media creates allocation risk during demand surges from institutional pathogen suppression mandates. Distribution runs through building automation integrators for commercial ceiling-mounted systems, direct-to-consumer platforms for premium portable units, and white-label appliance retail for volume-tier residential products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
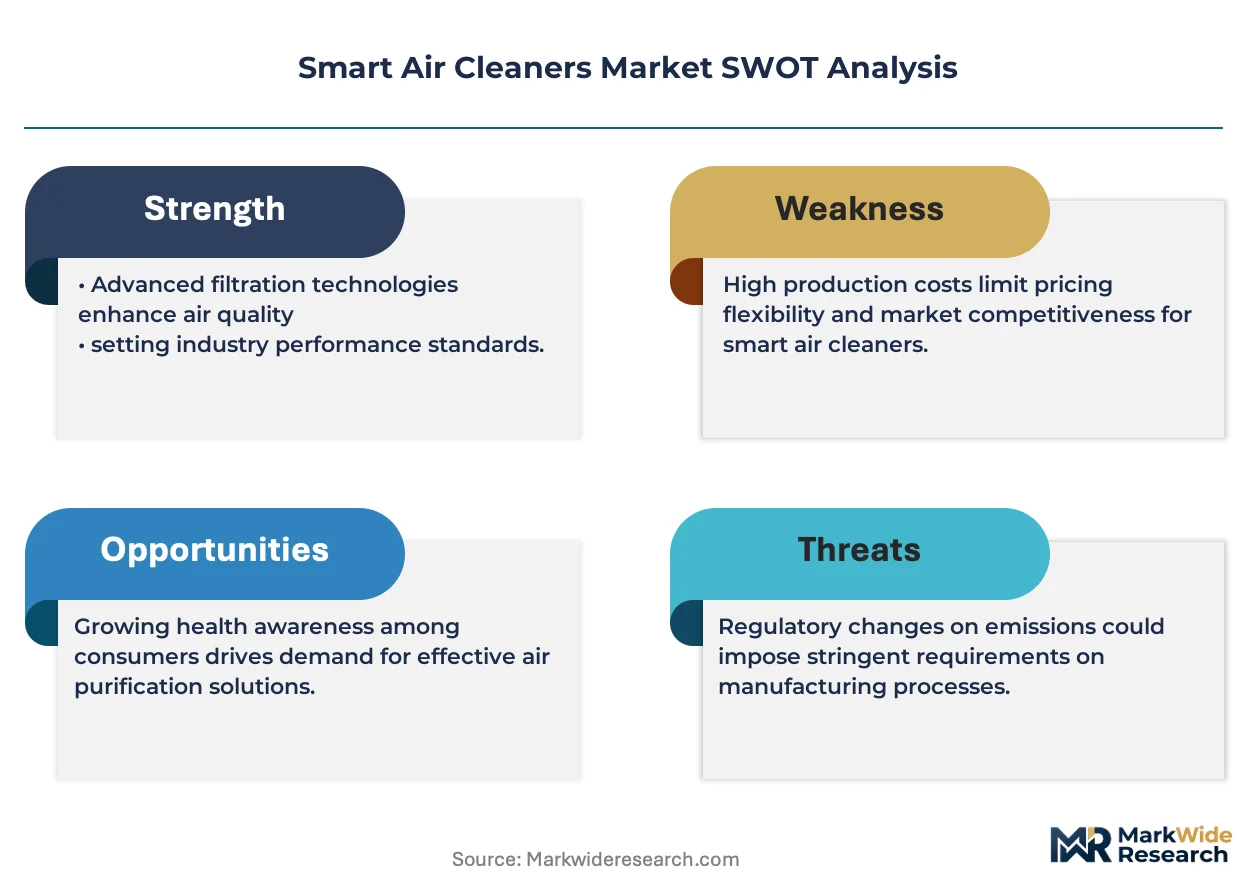
Glass microfiber supply concentration in Germany and Japan props pricing for medical-grade HEPA certification, creating durable margin pools for manufacturers with captive media relationships or long-term offtake agreements.
For Market Incumbents: Anchor defensive positioning through backward integration into PM2.5 sensor calibration capabilities, addressing the talent scarcity threatening product iteration cycles. Pursue exclusive HVAC retrofit bundling contracts with German and French facility management integrators before emerging Asian entrants secure CE marking pathways. Certification investment in simultaneous FCC, GB standard, and MIIT IoT security compliance compresses launch timelines and raises barriers for resource-constrained rivals. For New Entrants and Emerging Players: Capture white-space in Indian residential markets before BIS mandatory standards finalize, establishing local testing partnerships that accelerate future compliance. Target educational procurement in US K-12 districts with specification-compliant ceiling-mounted systems priced below incumbent HVAC bundling packages. Go-to-market through direct-to-consumer voice control integration with Alexa and Google Assistant ecosystems, bypassing traditional appliance retail gatekeepers. For Investors and Strategic Acquirers: The window for entry favors facility management integrators with sensor fusion software capabilities and existing healthcare sector relationships. Long-term viability hinges on exposure to outcome-based air quality contracts rather than transactional hardware sales. Acquisition target archetype: mid-cap specialists with GB standard pre-qualification and Shenzhen supply chain relationships. Watch for EPA indoor air quality guideline expansion beyond particulate matter to volatile organic compound thresholds as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Capability Acquisition | PM2.5 and VOC algorithm development addresses talent scarcity constraining product differentiation. |
| GB Standard Pre-Qualification Investment | MIIT IoT security compliance unlocks Chinese domestic and Asia-export manufacturing volumes. |
| Voice Control Ecosystem Partnership | Alexa and Google Assistant integration creates switching costs that brick-and-mortar channels cannot replicate. |
| Outcome-Based Facility Contract Launch | Centralized air quality telemetry bundling commands premium margins through installation-service anchoring. |
| UV-C LED Chip Supply Agreement | Taiwanese epitaxy foundry relationships secure pathogen suppression technology layer fastest-expanding in institutional procurement. |
Research Methodology
Document review covered EPA Energy Star certification databases, FCC equipment authorization filings, and MIIT IoT security compliance registries, complemented by interviews with HVAC retrofit contractors, facility management software integrators, and hospital procurement committees. Secondary validation drew from Chinese customs export records, German building automation trade association reports, and South Korean MFDS medical device filings. Bottom-up unit shipment estimates from sensor module vendors were triangulated against top-down addressable space calculations from real estate development pipelines.
Unit and value outputs across the projection horizon reflect installed base modeling by form factor, filtration technology tier, and connectivity specification. Segmentation dimensions included deployment context, certification grade, ecosystem integration depth, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis and new build penetration assumptions. Industry-specific forecast inputs incorporated EPA guideline revision timelines and Chinese tier-one city smart home adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to HEPA media supply allocation decisions by German and Japanese producers, and to FCC certification backlog fluctuations affecting wireless-enabled product launches. Forecasts reflect documented assumptions about institutional procurement budget trajectories and residential ecosystem lock-in persistence. A small set of named triggers warrants ongoing watch: BIS standard finalization in India, EU F-Gas Regulation expansion to additional refrigerant categories, and MFDS-equivalent performance claim enforcement actions in South Korea.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Smart Climate Control Market
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Wi-Fi Smart Thermostat Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
EV Smart HVAC System Market
Energy Management Systems
North America Energy Management Systems Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Global Digital Thermostats Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market