
 Asia-Pacific Energy Management System Market | 2026-2036
Asia-Pacific Energy Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Energy Management System Market Analytics
Data center power density requirements across Southeast Asia is expanding the addressable base for monitoring platforms. Schneider Electric SE leverages its EcoStruxure architecture to anchor large-scale deployments across Singapore's digital infrastructure zone. Siemens AG competes through its Desigo portfolio, specializing in building automation integration that extends into energy optimization workflows. Honeywell International Inc dominates the industrial segment with hardware-software bundles that control critical power assets across Japanese automotive plants.
Energy Management Systems comprise sensor networks, control software, and analytics engines that measure, monitor, and optimize electricity, thermal, and mechanical energy flows across facilities. These platforms integrate SCADA protocols, IoT gateways, and machine learning algorithms to automate load scheduling, identify waste patterns, and enforce demand thresholds against utility rate structures. Software and cloud services represent the fastest-expanding revenue pool as utilities shift from perpetual licenses to subscription metering and AI-driven forecasting models. Hardware retains margin concentration at the high end, where precision power quality analyzers and edge controllers command premium positioning in semiconductor fabs and pharmaceutical cleanrooms.
Japan's METI enforces Top Runner standards that compel industrial facilities to benchmark and disclose energy performance, directly stimulating EMS procurement. China's MEE implements dual carbon compliance frameworks that penalize heavy manufacturers exceeding provincial intensity caps, forcing steel and cement operators toward real-time optimization platforms. India's BEE mandates periodic energy audits for designated consumers, creating recurring software and service attach revenue for vendors. Stakeholders must weigh cloud migration timelines against data sovereignty requirements as cross-border energy data flows face emerging localization pressures.
Market Dynamics
China's dual carbon enforcement is compressing deployment timelines for heavy manufacturers, forcing real-time optimization platforms into steel and cement operations that previously relied on manual energy audits.
Growth Catalysts
- India's BEE Designated Consumer Mandate:Periodic energy audit requirements for large industrial facilities create recurring software attach revenue streams for platform vendors.
- Data center power density escalation:Southeast Asian cloud infrastructure operators are retrofitting facilities with granular monitoring to manage thermal loads and utility demand charges.
- Edge AI inference:On-premise machine learning deployment is enabling sub-second load scheduling decisions that cloud latency cannot support.
Market Restraints
- Semiconductor component concentration:Precision power quality analyzers depend on analog-to-digital converters sourced primarily from Taiwanese foundries, exposing lead time volatility.
- Data localization mandates:Cross-border energy data flows face emerging restrictions in China and India that fragment cloud architecture standardization.
- High-precision sensor cost structure:Pharmaceutical cleanroom-grade power monitoring hardware commands 4-5x pricing over standard industrial units, limiting mid-market penetration.
Strategic Opportunities
- Vietnam's industrial corridor expansion:Manufacturing migration from China is creating greenfield EMS deployment opportunities in northern provinces without legacy system integration burden.
- Building-to-grid integration:Convergence of EMS platforms with virtual power plant software is opening utility-facing revenue streams for commercial real estate operators.
- Japan's Top Runner disclosure requirements:Mandatory benchmarking is stimulating demand for continuous monitoring upgrades among automotive and electronics manufacturers.
Industry Challenges
- OT-IT cybersecurity skill scarcity:Facilities struggle to staff teams capable of securing SCADA-protocol networks against ransomware targeting energy infrastructure.
- Legacy BAS integration complexity:Proprietary building automation protocols from 1990s-era Japanese and Korean vendors resist standard API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Energy Management System Market |
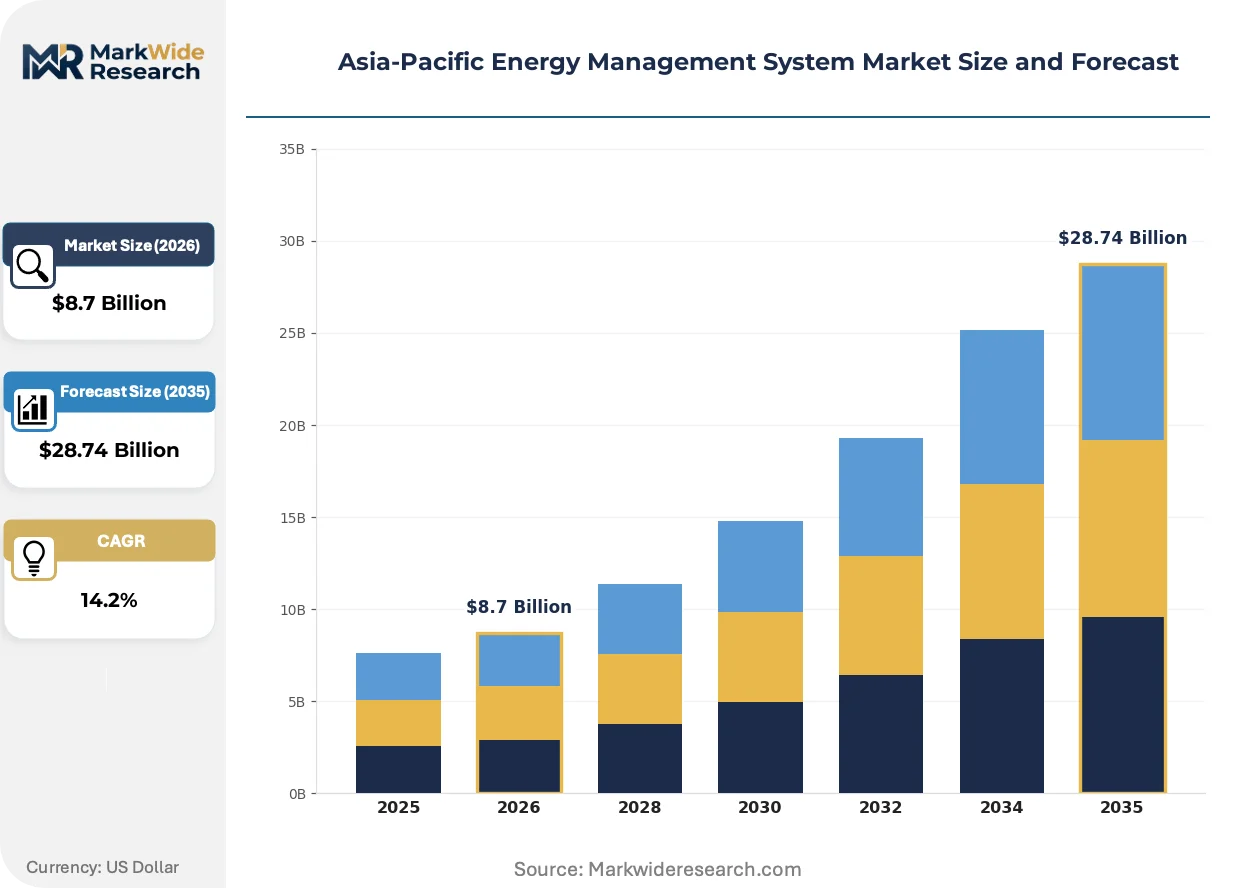
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
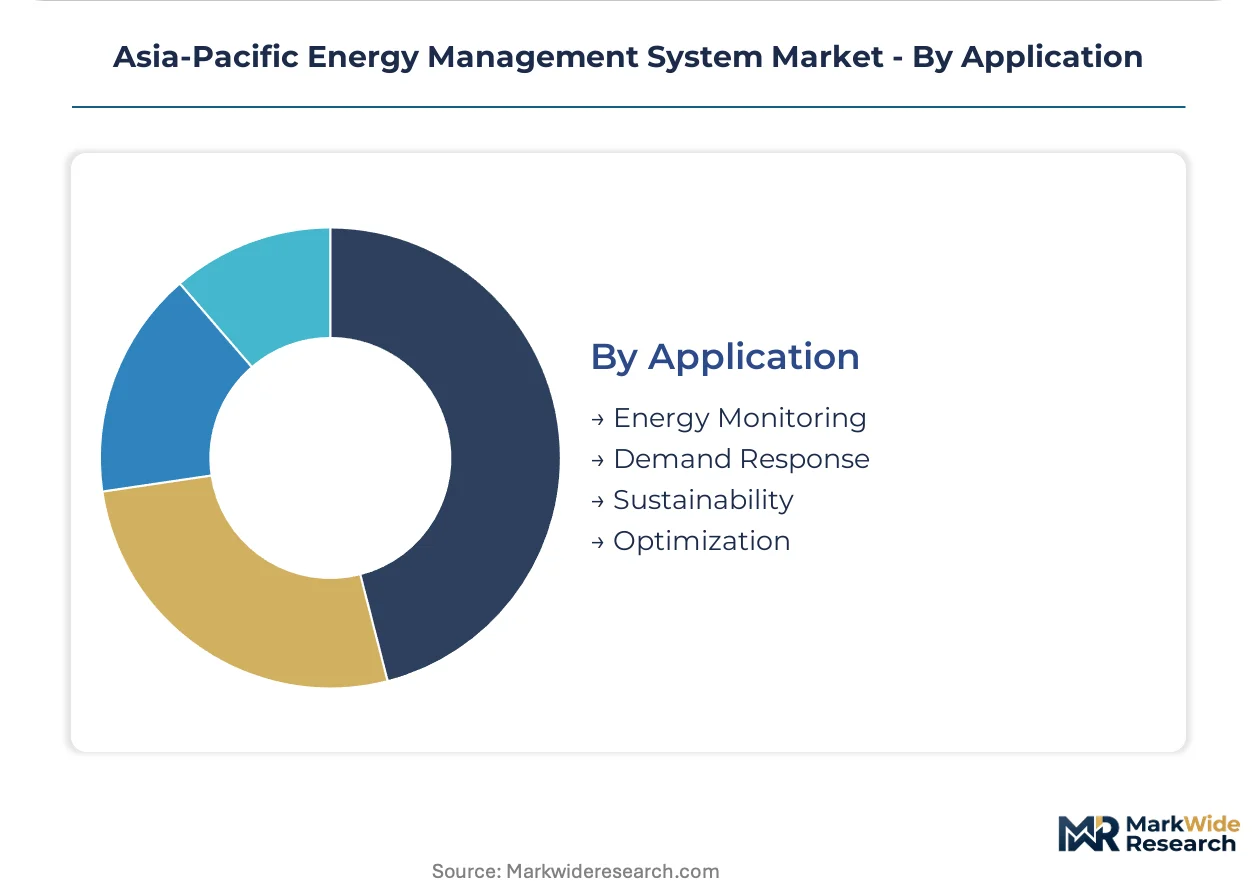
| Segmentation | Product Type: Software, Hardware, Cloud Services, Consulting End User: Manufacturing, Commercial, Residential, Utilities Installation: On-Premise, Cloud-Based, Hybrid, Remote Application: Energy Monitoring, Demand Response, Sustainability, Optimization |
| Companies Covered | Schneider Electric SE, Honeywell International Inc, IBM Corporation, General Electric Company, Siemens AG, Rockwell Automation Inc, ABB Ltd, Emerson Electric Co, Mitsubishi Electric Corp, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Energy Management System Market Evolving Landscape
Digital twin architecture is displacing static energy modeling across Asia-Pacific industrial facilities, compressing the gap between design-phase efficiency targets and operational reality.
Digital twin platforms are electrifying how facility operators simulate thermal and electrical load scenarios before physical commissioning. Semiconductor fabs in South Korea and Taiwan are deploying these virtual replicas to stress-test cooling configurations against projected wafer throughput. The technology is electrifying vendor competitive positioning by binding software subscriptions to measurable efficiency guarantees rather than feature checklists.
China's MEE provincial intensity caps are forcing steel operators toward continuous emissions-linked energy optimization. Heavy manufacturers exceeding carbon intensity thresholds face production curtailments that real-time EMS platforms help avoid. Cement and aluminum smelters in Shandong and Jiangsu provinces are accelerating procurement of integrated monitoring-control systems to maintain operating licenses.
Subscription metering is displacing perpetual license structures across utility and industrial software procurement. Japanese and Australian energy retailers are unbundling hardware from analytics services, selling consumption forecasting as a monthly operational expense. This shift is most visible among commercial building portfolios in Singapore and Sydney, where facilities managers prefer opex-aligned contracts that transfer technology obsolescence risk to vendors.
Asia-Pacific Energy Management System Market Segmentation
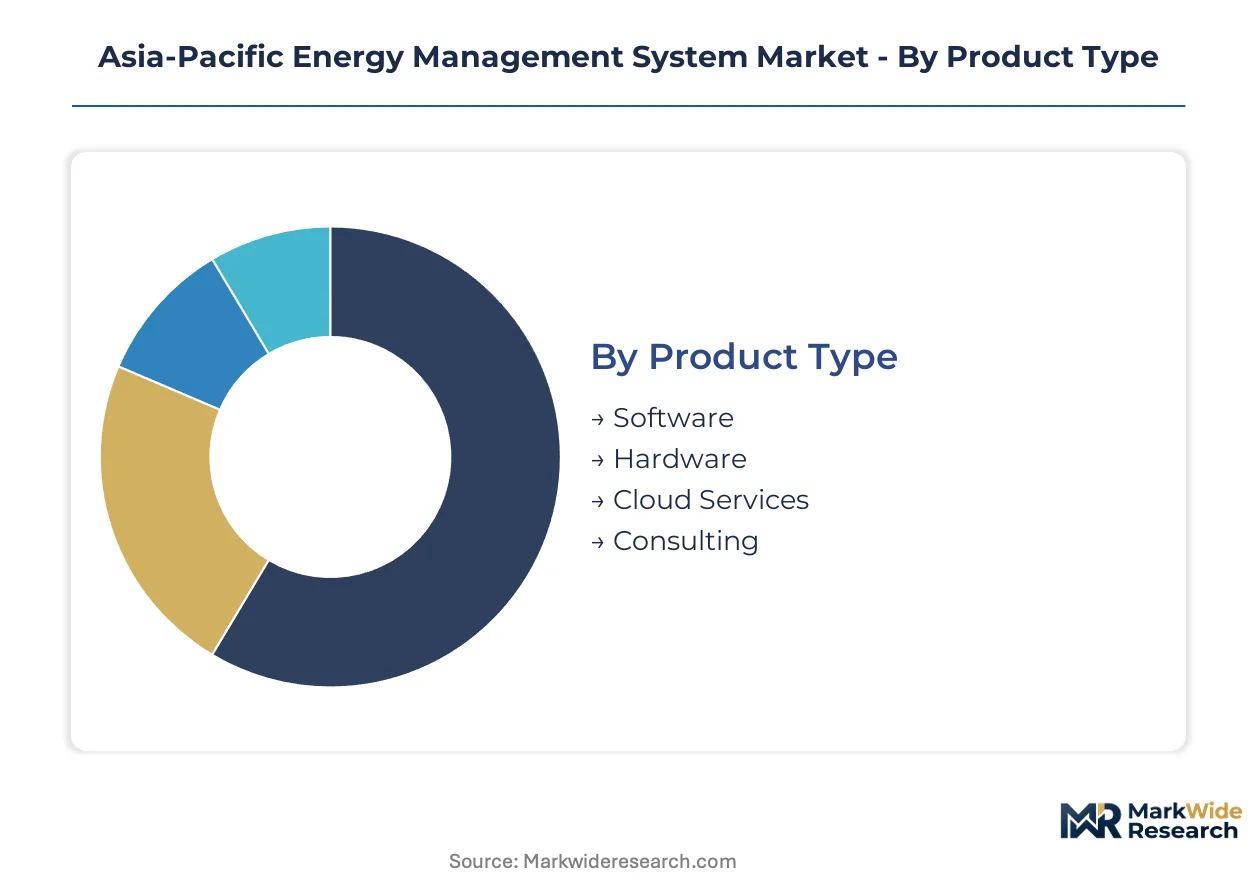
EMS procurement patterns diverge sharply between heavy industrial operators seeking real-time control systems and commercial portfolio managers prioritizing opex-aligned analytics subscriptions. Segmentation reveals how vendor bundling strategies must adapt to fundamentally different buyer economics and technical integration requirements across the Asia-Pacific region.
Product Type:
Buyer procurement authority determines tier selection, with CIO-led commercial accounts favoring cloud-native stacks while plant engineers specify hardware-software bundles.
- Software:Analytics engines and visualization dashboards process SCADA telemetry into actionable load scheduling recommendations. Demand concentrates among Singaporean and Australian data center operators retrofitting thermal management systems to manage utility demand charges and avoid peak pricing penalties.
- Hardware:Sensor networks, edge controllers, and power quality analyzers capture electrical and thermal data streams at the facility level. Japanese automotive plants and South Korean semiconductor fabs drive procurement of precision-grade units that integrate with existing SCADA infrastructure.
- Cloud Services:Subscription-based consumption forecasting and AI-driven anomaly detection delivered through managed platforms.
- Consulting:Energy audit execution, compliance documentation, and platform implementation services tied to India's BEE designated consumer mandates.
Volume sits with hardware; growth tilts toward cloud services.
End User:
Regulatory exposure shapes deployment urgency, with mandated audit regimes forcing procurement timelines that voluntary sustainability programs cannot match.
- Manufacturing:Steel, cement, and chemical facilities deploy integrated monitoring-control systems to comply with China's MEE provincial intensity caps and avoid production curtailments. Gujarat and Maharashtra industrial corridors in India represent concentrated demand as BEE audit deadlines approach.
- Commercial:Office portfolios and retail chains adopt building automation integration for utility demand charge management. Singapore's digital infrastructure zone operators prioritize granular monitoring to handle escalating power density requirements.
- Residential:Smart home energy management through utility-linked demand response programs.
- Utilities:Grid-edge optimization and virtual power plant orchestration platforms for distributed resource management.
Manufacturing commands current spend; commercial applications are expanding most quickly.
Installation:
Data sovereignty constraints and latency requirements fragment architecture preferences across national boundaries.
- On-Premise:Local server deployment with air-gapped security for critical infrastructure protection. Japanese automotive plants specify these configurations to satisfy METI Top Runner disclosure requirements while maintaining operational technology network isolation.
- Cloud-Based:Fully managed SaaS delivery with automatic feature updates and elastic compute scaling. Australian commercial real estate operators prefer opex-aligned contracts that transfer technology obsolescence risk to vendors.
- Hybrid:Edge processing for real-time control with cloud analytics for long-term optimization and reporting.
- Remote:Centralized monitoring of distributed facility portfolios through secure VPN connections.
Hybrid architectures gain share fastest; pure cloud faces headwinds from emerging data localization mandates in China and India.
Application:
Functional priority reflects facility maturity, with greenfield deployments skipping basic monitoring to implement predictive optimization directly.
- Energy Monitoring:Baseline consumption measurement and waste pattern identification through sensor network deployment. Vietnam's northern industrial provinces attract greenfield installations without legacy system integration burden.
- Demand Response:Automated load curtailment and peak shaving in response to utility price signals or grid emergencies. Southeast Asian data center operators retrofit facilities to manage thermal loads against time-of-use electricity tariffs.
- Sustainability:Carbon accounting, emissions reporting, and renewable energy certificate tracking for ESG compliance.
- Optimization:AI-driven continuous adjustment of HVAC, lighting, and process loads to minimize cost and carbon intensity simultaneously.
Monitoring dominates installed base; optimization claims the steepest expansion trajectory as machine learning deployment matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Jurong Innovation District and Vietnam's Bac Ninh industrial zone are concentrating EMS deployment through tax-incentive structures that reward energy-efficient facility design. Special economic zones across Southeast Asia are accelerating platform procurement timelines.
China
Steel and cement manufacturers in Shandong and Jiangsu provinces are deploying real-time optimization platforms to comply with MEE provincial intensity caps. The dual carbon enforcement framework penalizes heavy manufacturers exceeding carbon thresholds with production curtailments. Integrated monitoring-control systems are becoming license-to-operate requirements in these industrial clusters.
India
Gujarat and Maharashtra industrial corridors represent concentrated demand as BEE designated consumer audit deadlines approach. Periodic energy audit mandates for large facilities create recurring software and service attach revenue for platform vendors. Manufacturing facilities across these western states are accelerating deployment to curb electricity intensity and meet compliance thresholds.
Japan
Automotive and electronics manufacturers are upgrading to continuous monitoring systems under METI Top Runner disclosure requirements. METI enforces benchmarking standards that compel industrial facilities to measure and disclose energy performance. Japanese automotive plants specify on-premise configurations with air-gapped security to maintain operational technology network isolation.
South Korea
Semiconductor fabs are deploying precision-grade power quality analyzers that integrate with existing SCADA infrastructure. Thermal management optimization is critical as wafer throughput escalates power density requirements. The country's semiconductor manufacturing clusters are driving procurement of hardware-software bundles for facility-level energy control.
Vietnam
Northern industrial provinces attract greenfield EMS installations without legacy system integration burden. Manufacturing migration from China is creating deployment opportunities in facilities built with native energy optimization architecture. Bac Ninh and Hai Phong industrial zones are emerging as concentrated demand centers for cloud-native monitoring stacks.
Asia-Pacific Energy Management System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated hardware-software providers commanding industrial accounts while pure-play analytics vendors capture commercial building portfolios. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with captive energy automation divisions, pure-play software specialists offering subscription forecasting models, and building automation incumbents extending into energy optimization workflows. M&A activity targets edge AI capabilities and cybersecurity assets for OT-IT convergence. Geographic expansion into Vietnam's northern industrial corridor represents a second competitive vector.
Within the diversified industrial tier, Schneider Electric SE and Siemens AG exemplify the hardware-software bundling approach that dominates manufacturing facility procurement. Honeywell International Inc occupies a position anchoring the industrial automation segment with integrated control systems. These three companies represent contrasting geographic origins and structural approaches to the Asia-Pacific market, with French, German, and US-based entities each leveraging distinct regulatory relationships and channel footprints across the region.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Honeywell International Inc |
| IBM Corporation |
| General Electric Company |
| Siemens AG |
| Rockwell Automation Inc |
| ABB Ltd |
| Emerson Electric Co |
| Mitsubishi Electric Corp |
| Others |
Value Network & Pricing Analysis
Analog-to-digital converter sourcing from Taiwanese foundries feeds through three distinct pricing tiers for precision power quality analyzers, with semiconductor-grade units commanding substantial premiums over standard industrial configurations while cloud-native software subscriptions compress hardware attach rates across Southeast Asian data center deployments.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations for precision power quality analyzers, with spot inventory discounts emerging for standard industrial sensor configurations. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cleanroom-grade units from automotive plant configurations and basic commercial building monitors. Price differentiation hinges on certification grade and after-sales service bundling, with ISO-certified precision hardware capturing margin concentration. Cost compression in mid-market hardware is intensifying because cloud-native software vendors unbundle analytics from sensor procurement. Commercial real estate operators in Singapore and Sydney demonstrate highest price sensitivity through opex-aligned contract preferences, while Japanese semiconductor fabs show lowest sensitivity due to license-to-operate compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese analog-to-digital converter foundries that supply precision sensor components for pharmaceutical and semiconductor-grade deployments. Hardware manufacturing concentrates in China, Japan, and South Korea, with edge controller assembly anchored in Shenzhen and Nagoya industrial corridors. Raw material dependencies span rare earth magnets for sensor housings, high-purity copper for electrical pathways, and silicon substrates for chip fabrication. Tariff exposure on cross-border component flows between China and key ASEAN markets presents structural risk for integrated hardware-software bundles. Distribution runs through authorized system integrators in industrial corridors, direct OEM relationships for large facility deployments, and cloud marketplaces for SaaS-native analytics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive control over edge AI inference chips and precision sensor fabrication determines margin capture across industrial accounts.
For Market Incumbents: Deploy backward integration into analog-to-digital converter supply to secure lead-time advantages against fabless competitors. Establish captive certification laboratories in India and Vietnam to accelerate BEE compliance documentation for designated consumer mandates. Lock in long-term power purchase agreements with Southeast Asian data center operators before pure-play software vendors capture building-to-grid integration workflows. Defensive positioning requires neutralizing the threat of OT-IT cybersecurity specialists that bundle ransomware protection with energy monitoring platforms. For New Entrants and Emerging Players: Edge-native machine learning deployment without cloud dependency offers a technology-first wedge against latency-constrained competitors. Target Vietnam's northern industrial provinces for greenfield installations that bypass legacy BAS integration complexity. Penetrate mid-market pharmaceutical manufacturing in India through subscription-metering models that transfer obsolescence risk from capital-constrained facilities. Go-to-market execution should anchor on channel partnerships with Vietnamese system integrators possessing established relationships in Bac Ninh and Hai Phong industrial zones. For Investors and Strategic Acquirers: MEE provincial intensity cap enforcement in Shandong and Jiangsu is the leading indicator that integrated monitoring-control systems are becoming license-to-operate requirements rather than discretionary efficiency investments. Long-term viability over the coming decade rests on vendor ability to bind software subscriptions to measurable efficiency guarantees through digital twin architectures. Acquisition targets should display captive edge AI capabilities and established cybersecurity frameworks for SCADA-protocol networks. Monitor BEE audit deadline acceleration in Gujarat and Maharashtra as the signal for recurring software attach revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chip Development | Captive inference capability secures sub-second load scheduling decisions for steel and cement operators facing MEE curtailment risk. |
| Cybersecurity Asset Acquisition | OT-IT convergence expertise addresses ransomware targeting energy infrastructure across Japanese automotive SCADA networks. |
| Digital Twin Platform Launch | Virtual replica deployment binds software subscriptions to measurable efficiency guarantees in South Korean semiconductor fabs. |
| Vietnam Channel Partnership | System integrator relationships in Bac Ninh and Hai Phong accelerate greenfield EMS penetration without legacy integration burden. |
| Building-to-Grid Integration | Virtual power plant software convergence opens utility-facing revenue streams for Singapore commercial real estate operators. |
Research Methodology
Document review covered regulatory filings from China's MEE, India's BEE, and Japan's METI, complemented by interviews with facility energy managers at steel and cement operations, data center infrastructure heads, building automation system integrators, and utility demand response program officers. Secondary validation drew from IEA energy efficiency databases, ASEAN industrial statistics, and customs trade data for precision sensor components. Bottom-up facility deployment estimates triangulated against top-down market sizing from utility software procurement disclosures.
Cross-referencing historical deployment patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, end-user industry vertical, installation architecture preference, and application functional priority. CAGRs were derived through regression analysis of disclosed platform subscription growth and hardware shipment volumes. Forecast inputs incorporated MEE provincial intensity cap enforcement timelines and BEE designated consumer audit schedule acceleration.
Several conditions sit outside the modeled scope, including potential semiconductor export control expansions affecting analog-to-digital converter supply, and unforeseen data localization mandate tightening in China and India that could fragment cloud architecture standardization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Europe Advanced Distribution Management System Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
North America Residential Lighting Control System Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
Portable Air Cooler Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Global Personal Cooling Device Market
Energy Management Systems
Southeast Asia Cooling Systems Market