
 Building Energy Management Solution Market | 2026-2036
Building Energy Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Building Energy Management Solution Market Analysis
Cloud-native software is decoupling building energy management from legacy on-premise infrastructure, collapsing deployment costs and expanding addressable building stock. Schneider Electric leverages its EcoStruxure platform to anchor integrated HVAC and lighting control across European commercial portfolios. Johnson Controls sustains R&D intensity in AI-driven fault detection, while Siemens dominates digital twin deployments for industrial facility energy optimization.
A building energy management solution orchestrates real-time monitoring, automated control, and predictive analytics across HVAC, lighting, and distributed energy assets through sensor networks, edge gateways, and cloud-based optimization engines with sub-15-minute data granularity, serving to minimize kilowatt-hour consumption and peak demand charges in commercial and industrial facilities. Cloud-based deployment captures the fastest expansion as remote diagnostics and multi-site dashboards displace on-premise servers, while HVAC control applications retain the largest installed base due to thermal load dominance in building energy profiles. IoT technology layers form the connective foundation, though AI modules are deepening margin pools through predictive maintenance subscriptions.
The EU Green Deal and Energy Performance of Buildings Directive mandate granular energy disclosure and renovation roadmaps across member states, while the EPA's ENERGY STAR certification and ASHRAE Standard 90.1 establish product efficiency baselines in the United States. Japan's METI enforces building energy codes that compel automated monitoring in large commercial structures. Stakeholders must weigh interoperability standards against proprietary ecosystem lock-in as procurement shifts from hardware bundles to recurring software platforms.
Market Dynamics
Cloud-native orchestration platforms are collapsing the cost barrier for multi-site energy management, enabling mid-sized commercial portfolios to access capabilities previously reserved for enterprise-grade installations. This infrastructure shift is compressing deployment timelines from months to weeks while expanding the addressable building stock beyond Class A assets.
Growth Catalysts
- EU Green Deal enforcement:The Energy Performance of Buildings Directive mandates automated monitoring systems and renovation roadmaps across member states, compelling retrofits in aging commercial stock.
- AI-driven fault detection:Machine learning algorithms applied to HVAC telemetry now predict equipment failures 48-72 hours before occurrence, slashing unplanned downtime costs for facility operators.
- Japan's METI building codes:Automated energy monitoring requirements for structures exceeding 3,000 square meters are standardizing sensor deployments in Tokyo, Osaka, and Yokohama commercial districts.
Market Restraints
- Semiconductor input volatility:Edge gateway and sensor controller production faces intermittent chip supply constraints, extending lead times for hardware-dependent deployments.
- Proprietary protocol fragmentation:BACnet, Modbus, and LONworks coexist without full interoperability, forcing integrators to maintain multiple gateway stacks and raising system complexity.
- Cybersecurity liability exposure:Connected building systems create attack surfaces that property insurers increasingly exclude from standard coverage, requiring specialized cyber riders.
Strategic Opportunities
- Industrial facility digital twins:Siemens and emerging vendors are deploying physics-based energy models for manufacturing campuses, opening a whitespace beyond traditional commercial real estate.
- Subscription-based optimization:Predictive analytics delivered as recurring software platforms replace perpetual license sales, capturing lifetime value from building operator relationships.
- Germany's national building performance standards:The tightening of energy disclosure requirements for commercial leases is accelerating landlord investment in automated monitoring infrastructure.
Industry Challenges
- Integration with pneumatic HVAC legacy:Pre-digital heating and cooling systems in 1980s-era buildings resist sensor retrofit without full mechanical replacement, inflating project scope.
- Sub-15-minute data granularity requirements:Real-time optimization engines demand streaming architectures that overwhelm underprovisioned IT networks in older properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Energy Management Solution Market |
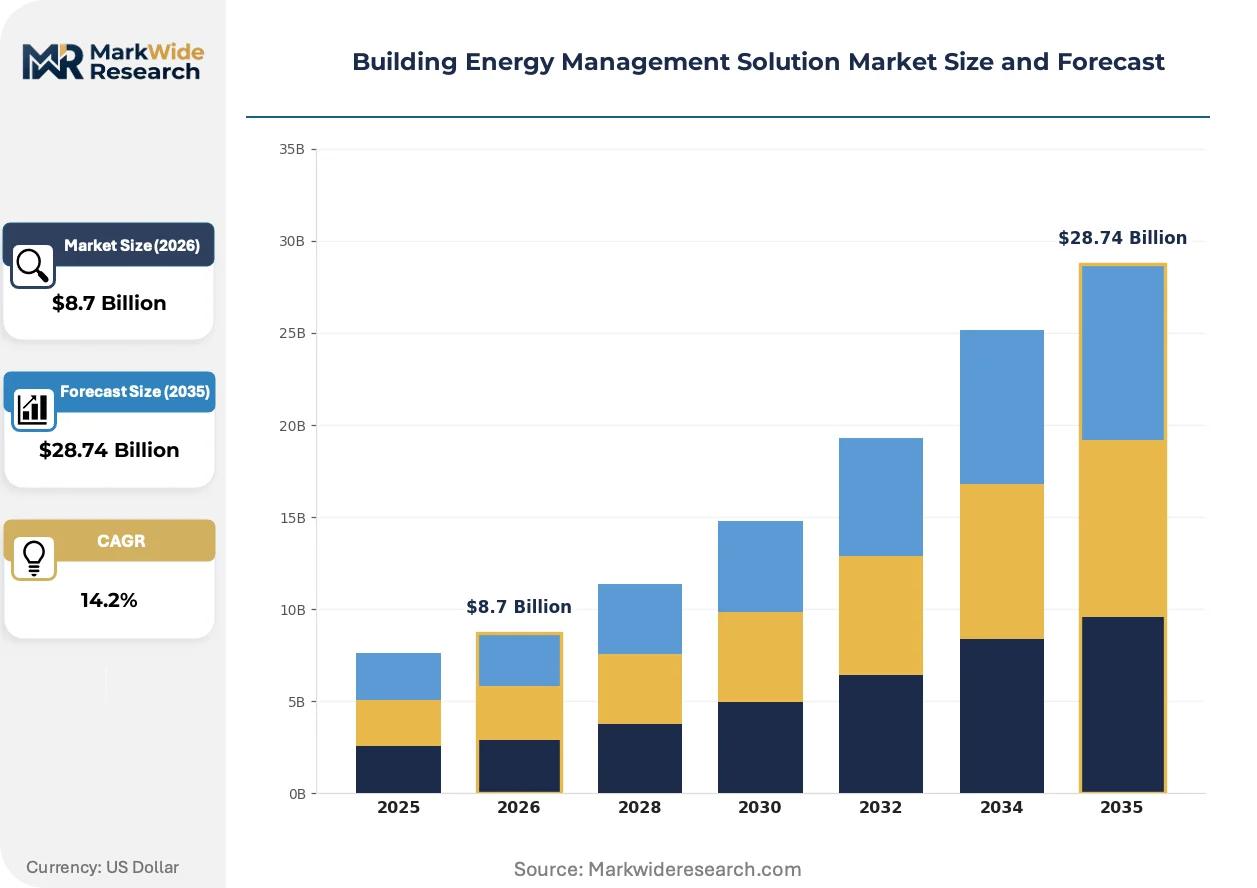
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Cloud Computing, AI, Automation End User: Commercial Buildings, Industrial Facilities, Residential Homes, Educational Institutions Application: HVAC Control, Lighting Management, Energy Analysis, Renewable Integration Deployment: On-premise, Cloud-based, Hybrid, Others |
| Companies Covered | Schneider Electric, Johnson Controls, Honeywell International, Siemens, ABB, Emerson Electric, General Electric, Trane Technologies, Rockwell Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Energy Management Solution Market Emerging Trajectories
Edge computing architectures are redistributing analytical workloads from cloud cores to local gateways, enabling millisecond-latency control decisions while reducing bandwidth costs. This infrastructure evolution is unlocking responsive load management previously impossible under centralized processing models.
Digital twin technology is rewriting how industrial facility operators optimize thermal and electrical loads. Manufacturing campuses in Germany and Japan are deploying physics-based building models that simulate HVAC performance against production schedules. These virtual environments compress commissioning cycles from months to weeks while enabling scenario testing without physical intervention.
The EPA's ENERGY STAR certification program and ASHRAE Standard 90.1 are tightening product efficiency baselines across the United States. Equipment manufacturers must now demonstrate measured performance under partial-load conditions, not just design ratings. Commercial real estate investment trusts are responding by specifying certified hardware in standard procurement templates, filtering non-compliant vendors from bid pools.
Building operators are unbundling energy management from facilities management contracts, creating direct vendor relationships with software platforms. Third-party service providers in the United States and Germany are capturing this disintermediation opportunity, selling optimization-as-a-service to portfolios that previously relied on generalist property managers. This shift concentrates accountability for kilowatt-hour outcomes with specialized technology vendors rather than diversified service conglomerates.
Building Energy Management Solution Market Segmentation
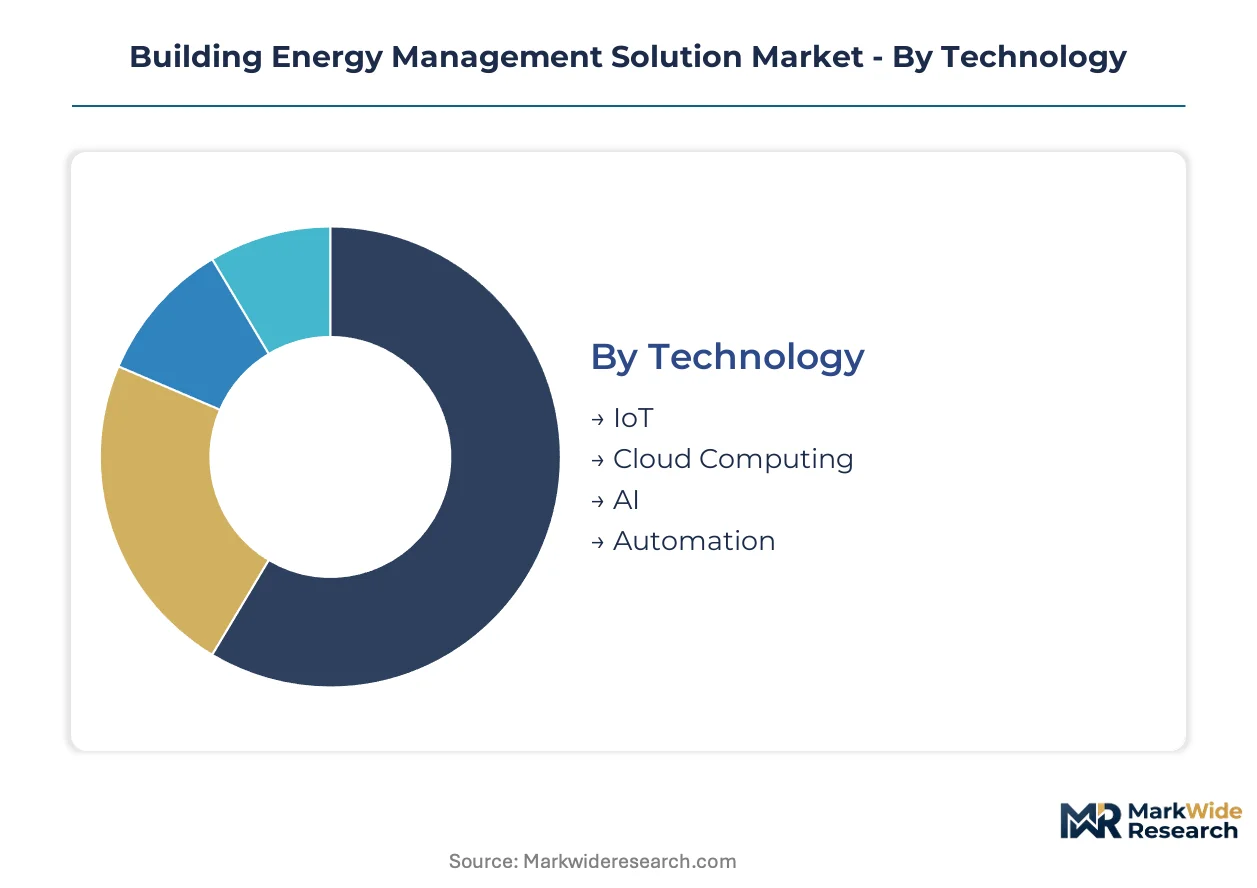
Energy management procurement splits sharply across technology maturity, facility type, and infrastructure architecture. Each segment carries distinct certification burdens and integration complexity that shape vendor selection criteria and contract structures.
Technology:
Certification requirements vary sharply by technology layer. IoT sensor networks must comply with FCC Part 15 in the United States and CE marking under the EU Radio Equipment Directive. Cloud platforms face GDPR data residency rules in Europe and Japan's APPI for cross-border energy data flows. AI modules encounter emerging algorithmic transparency mandates under the EU AI Act.
- IoT:Sensor networks and edge gateways form the physical data layer, requiring BACnet or Modbus protocol compliance for HVAC integration. Demand concentrates in German commercial retrofits where the EU Energy Performance of Buildings Directive mandates sub-15-minute metering granularity, forcing wholesale sensor upgrades in 1970s office stock.
- Cloud Computing:Centralized data lakes and multi-site dashboards eliminate on-premise server maintenance. Japanese METI building codes for structures exceeding 3,000 square meters are accelerating Tokyo and Osaka deployments as landlords seek automated compliance reporting.
- AI:Predictive analytics engines for fault detection and load forecasting.
- Automation:Rule-based control systems triggering HVAC and lighting responses.
Leading the category by volume: IoT. Growing fastest: Cloud Computing.
End User:
Facility type determines procurement authority, budget scale, and payback period tolerance. Industrial campuses prioritize uptime over efficiency. Educational institutions navigate public procurement rules. Residential deployments remain fragmented across individual homeowners and multi-family operators.
- Commercial Buildings:Office towers, retail centers, and hospitality assets with centralized facilities management. Demand clusters in U.S. commercial real estate investment trusts specifying ENERGY STAR-certified hardware in standard procurement templates, filtering non-compliant vendors from bid pools.
- Industrial Facilities:Manufacturing campuses with process-critical thermal loads. German automotive and chemical plants are deploying physics-based digital twins that simulate HVAC performance against production schedules, compressing commissioning cycles from months to weeks.
- Residential Homes:Single-family and multi-family dwellings with distributed ownership.
- Educational Institutions:K-12 schools and university campuses with public funding constraints.
Highest contract value: Commercial Buildings. Steepest expansion trajectory: Industrial Facilities.
Application:
Functional modules align with building energy profiles and utility tariff structures. HVAC dominates thermal load management. Lighting offers rapid retrofit payback. Renewable integration responds to behind-the-meter solar growth.
- HVAC Control:Automated heating, ventilation, and air conditioning optimization commanding the largest installed base. U.S. ASHRAE Standard 90.1 tightening product efficiency baselines under partial-load conditions is forcing equipment replacements in 1980s-era buildings with pneumatic legacy systems.
- Lighting Management:Daylight harvesting, occupancy sensing, and circadian tuning. Japanese commercial districts in Yokohama are standardizing sensor deployments as METI codes mandate automated monitoring, creating bundled LED-control procurement.
- Energy Analysis:Utility bill auditing, load profiling, and carbon accounting.
- Renewable Integration:Solar PV dispatch, battery storage arbitrage, and grid-interactive controls.
Widest deployment: HVAC Control. Gaining share fastest: Renewable Integration.
Deployment:
Infrastructure architecture determines capital expenditure timing, IT security exposure, and vendor lock-in risk. On-premise retains air-gapped security. Hybrid configurations balance latency sensitivity with centralized analytics.
- On-premise:Local servers and dedicated networks for security-sensitive facilities. Aging U.S. federal buildings and defense-adjacent industrial sites maintain legacy infrastructure due to cybersecurity liability exclusions in standard property insurance coverage.
- Cloud-based:Fully managed SaaS platforms with browser-based dashboards. German mid-sized commercial portfolios are accessing capabilities previously reserved for enterprise-grade installations as deployment timelines compress from months to weeks.
- Hybrid:Edge processing with cloud aggregation for bandwidth optimization.
- Others:Emerging serverless and containerized architectures.
Dominant legacy mode: On-premise. Climbing the fastest: Cloud-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial building operators in Germany, the United States, and Japan are accelerating procurement of integrated energy management platforms as retrofit cycles intensify and disclosure requirements tighten. These three markets concentrate demand due to aging building stock, stringent regulatory mandates, and established vendor ecosystems. Each geography presents distinct procurement patterns shaped by local compliance frameworks and utility tariff structures.
United States
Commercial real estate investment trusts specify ENERGY STAR-certified hardware in standard procurement templates, filtering non-compliant vendors from bid pools. The EPA's certification program and ASHRAE Standard 90.1 establish product efficiency baselines that equipment manufacturers must demonstrate under partial-load conditions. Class A office towers in Manhattan, Chicago, and Los Angeles are unbundling energy management from facilities management contracts, creating direct vendor relationships with software platforms.
Germany
The EU Green Deal and Energy Performance of Buildings Directive mandate automated monitoring systems and renovation roadmaps across member states, compelling retrofits in aging commercial stock. National building performance standards are tightening energy disclosure requirements for commercial leases, accelerating landlord investment in automated monitoring infrastructure. Automotive and chemical plants in Bavaria and Baden-Württemberg deploy physics-based digital twins that simulate HVAC performance against production schedules.
Japan
METI building codes enforce automated energy monitoring requirements for structures exceeding 3,000 square meters, standardizing sensor deployments in Tokyo, Osaka, and Yokohama commercial districts. Landlords seek automated compliance reporting as METI mandates sub-15-minute metering granularity. Commercial districts in Yokohama are standardizing bundled LED-control procurement as codes mandate automated monitoring.
China
Dual carbon goals and provincial building energy codes are accelerating smart building retrofits in tier-one cities. The Ministry of Ecology and Environment enforces carbon intensity reduction targets that cascade into municipal building performance standards. Yangtze River Delta manufacturing campuses are deploying integrated energy management to align thermal loads with production schedules and grid dispatch signals.
United Kingdom
The Minimum Energy Efficiency Standards and forthcoming Building Safety Act are tightening operational energy disclosure for commercial leases. London's commercial property market is specifying cloud-native platforms to satisfy investor ESG reporting requirements. Greater Manchester and Birmingham office portfolios are compressing deployment timelines from months to weeks as mid-sized assets access capabilities previously reserved for enterprise-grade installations.
Building Energy Management Solution Market Vendor Landscape
Platform consolidation dominates the current landscape as vendors absorb specialized analytics providers to deepen AI capabilities. The vendor base stratifies across three tiers: diversified industrial conglomerates with embedded building automation divisions, pure-play software platforms born cloud-native, and regional system integrators with deep mechanical contractor relationships. Strategic archetypes include full-stack platform providers, point-solution specialists in fault detection or digital twins, and hardware-anchored integrators transitioning to recurring software revenue. M&A activity and subscription-based commercial model shifts represent the dominant competitive moves reshaping vendor positioning.
Within the diversified industrial tier, Schneider Electric, Johnson Controls, and Siemens occupy positions that exemplify contrasting strategic emphases. Schneider Electric leverages its EcoStruxure platform to anchor integrated HVAC and lighting control across European commercial portfolios. Johnson Controls sustains research and development intensity in AI-driven fault detection, representing the hardware-anchored transition toward predictive analytics subscriptions. Siemens dominates digital twin deployments for industrial facility energy optimization, occupying a whitespace beyond traditional commercial real estate. These three entities illustrate how incumbent industrial players are repositioning legacy automation portfolios around cloud-native orchestration and recurring revenue models.
| Leading Market Players |
|---|
| Schneider Electric |
| Johnson Controls |
| Honeywell International |
| Siemens |
| ABB |
| Emerson Electric |
| General Electric |
| Trane Technologies |
| Rockwell Automation |
| Others |
Supply Flow & Price Mechanics
The EU Green Deal's Energy Performance of Buildings Directive gates qualified supply and premium-tier pricing access by mandating sub-15-minute metering granularity and automated monitoring compliance, forcing landlords to specify certified hardware bundles that filter non-compliant vendors from bid pools while compressing margins on legacy sensor-controller production.
Pricing Analysis
Volume concentrates in IoT sensor-controller bundles while margin pools deepen in AI-driven predictive analytics subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified integrated platforms from basic BACnet-compliant controllers and unbranded commodity sensors. Cost compression in hardware tiers is intensifying because semiconductor input volatility extends lead times and forces spot-market purchasing. Mid-sized commercial portfolios in Germany exhibit the sharpest price sensitivity, whereas industrial facility operators in Japan prioritize uptime guarantees over per-unit hardware costs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for edge gateways and HVAC controllers, while system integrators serve fragmented mid-market retrofits. Manufacturing concentrates in China for sensor assembly, Germany for precision controllers, and Taiwan for edge-computing chipsets. Production draws from silicon wafers, rare-earth magnets for motor drives, and copper for electrical components. Single-source vulnerability in semiconductor foundry capacity creates supply chain risk. Distribution runs through mechanical contractor networks and facilities management conglomerates transitioning to software platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The building energy management solution market functions as a vertical-integration race where control over edge-gateway manufacturing and cloud-native software stacks determines pricing power and customer retention. Players are pursuing backward integration into sensor-controller production to secure supply and deepen margins.
For Market Incumbents: Anchor cloud-native orchestration capabilities against pure-play software entrants by acquiring specialized AI analytics providers. Prioritize R&D intensity in fault-detection algorithms to sustain subscription renewal rates. Defensive consolidation around BACnet and Modbus protocol stacks mitigates proprietary fragmentation risk that raises integration costs for facility operators. For New Entrants and Emerging Players: The premium-to-economy price-point gap in mid-sized commercial portfolios offers white-space entry. Target Germany's national building performance standards enforcement as landlords accelerate automated monitoring procurement without enterprise-grade IT departments. Pursue subscription-based optimization-as-a-service to bypass capital-intensive hardware manufacturing and capture recurring revenue from disintermediated facilities management relationships. For Investors and Strategic Acquirers: METI building code enforcement in Japan is the leading indicator that regulatory mandates are standardizing sensor deployments across Asia-Pacific manufacturing hubs. Long-term viability hinges on software platform recurring revenue multiples rather than hardware shipment volumes. Acquisition candidates with physics-based digital twin capabilities for industrial campuses command strategic premium. Watch for cloud-native platform unbundling from diversified industrial conglomerates as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| AI Module Acquisition | Deepens predictive maintenance subscription margins for facility operators. |
| Edge Gateway Manufacturing Scale-Up | Secures semiconductor allocation and compresses deployment timelines for retrofits. |
| Digital Twin Platform Launch | Opens industrial facility whitespace beyond traditional commercial real estate. |
| Certification Pre-Compliance Investment | Filters non-compliant competitors from ENERGY STAR procurement templates. |
| System Integrator Channel Partnership | Captures mid-market retrofit demand through mechanical contractor relationships. |
Methodological Framework
Regulatory filings from the EPA, METI, and EU Energy Performance databases, alongside ASHRAE standards documentation and commercial real estate investment trust procurement records, formed the secondary backbone. Primary interviews with facilities management directors, HVAC system integrators, building automation engineers, and sustainability officers at commercial landlords validated deployment timelines and pricing structures. Bottom-up sensor shipment analysis and top-down building stock modeling were triangulated against utility rebate program participation data.
Historical trendline analysis of retrofit cycle intensity and cloud-platform subscription attach rates anchored the projection framework. Segmentation dimensions modeled include technology layer, facility type, application module, and deployment architecture, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from elasticity-adjusted adoption curves across the projection horizon. Forecast inputs incorporated semiconductor lead time volatility and EU Green Deal enforcement trajectory.
Inputs from METI compliance reporting databases and German building performance disclosure registries were available through the study window; gaps in mid-sized commercial portfolio sensor deployment rates introduce uncertainty bands around cloud-based adoption assumptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and utility tariff restructuring. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Data Center Power Management Market
Energy Management Systems
Asia-Pacific Energy Management System Market
Energy Management Systems
US Energy Management Systems Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market
Energy Management Systems
Home Energy Management System Market
Energy Management Systems
Bed Cooling System Market
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Energy Management Systems (EMS) Market
Energy Management Systems
Peltier Chillers Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Evaporative Air Cooler Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
Global Vibration Control System Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
Global Personal Cooling Device Market