
 Global Cloud Accounting Technology Market | 2026-2036
Global Cloud Accounting Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Accounting Technology Market Foresight
Certified cloud accountants and DevSecOps talent is reorganizing how vendors scale implementation and support services. Intuit Inc leverages its consumer-tax heritage to anchor small-business onboarding flows. Xero Limited competes through API-first architecture that sustains third-party ecosystem density. Sage Group plc specializes in compliance-heavy European deployments where local tax rules dominate configuration requirements.
Cloud accounting technology denotes software delivered via internet-hosted infrastructure that automates ledger management, reconciliation, and regulatory reporting through multi-tenant architectures with SOC 2 Type II or ISO 27001 certification. Its primary commercial purpose is to replace on-premise general ledger systems with real-time financial visibility and automated audit trails. Public cloud deployments lead volume due to lower total cost of ownership, while hybrid cloud configurations capture the fastest growth as regulated industries demand data residency controls. Payroll management and tax management solution offerings concentrate margin pools where jurisdictional complexity creates pricing power.
FDA oversight applies where accounting platforms interface with clinical trial billing, while GDPR and EU AI Act frameworks in Europe mandate algorithmic transparency in automated expense categorization. SEC disclosure rules in the United States shape how public-cloud financial reporting tools structure audit-ready data retention. Stakeholders must monitor whether emerging AI-generated ledger entries trigger new liability standards under existing financial services regulations.
Market Dynamics
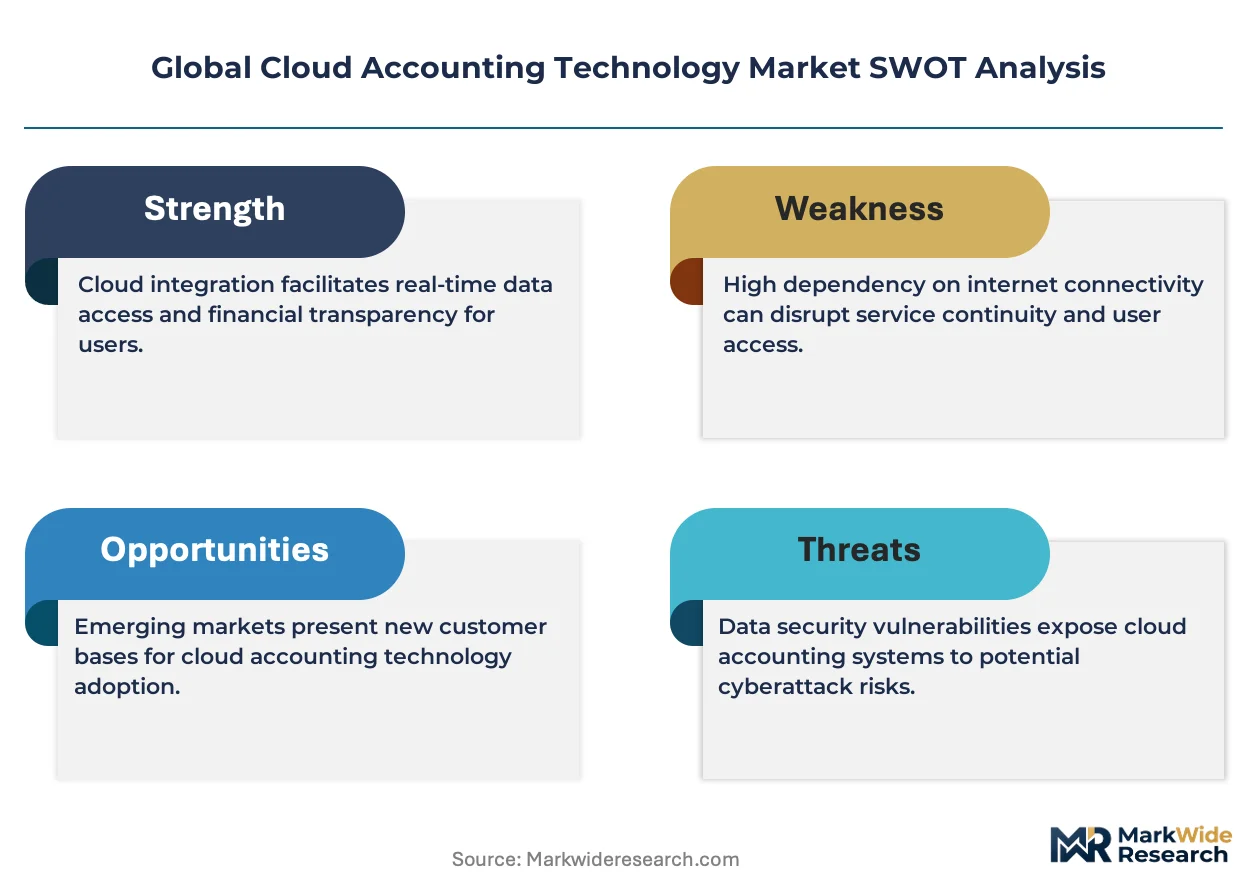
Mid-market enterprises are consolidating purchasing power around platforms that embed real-time compliance engines, forcing vendors to re-architect core ledgers for jurisdictional adaptability rather than feature velocity.
Growth Catalysts
- GDPR Article 17 right-to-erasure mandates:European deployments now require immutable audit trails with selective deletion capabilities, accelerating replacement of legacy on-premise systems that cannot satisfy both requirements simultaneously.
- India's PLI scheme for IT hardware:Domestic data center capacity expansion reduces latency for accounting SaaS, enabling tier-2 city penetration where connectivity previously blocked adoption.
- Embedded finance APIs:Banking-as-a-service integrations allow accounting platforms to capture payment flows natively, converting software vendors into primary financial data aggregators for small businesses.
Market Restraints
- Certified DevSecOps talent scarcity:SOC 2 Type II audit preparation requires specialized security engineering that concentrates in San Francisco, London, and Bangalore, inflating implementation costs elsewhere.
- Data residency fragmentation:Russia, China, and Indonesia mandate local server presence, fragmenting vendor infrastructure economics and preventing pure public-cloud cost structures in those markets.
- Legacy ERP sunk-cost entrenchment:SAP and Oracle on-premise installations in Fortune 500 companies carry decades of customized tax logic that resists cloud migration despite higher maintenance burdens.
Strategic Opportunities
- German Mittelstand compliance automation:Complex local tax determination rules create pricing power for vendors that pre-configure GoBD-compliant document management and audit trail generation.
- AI-generated ledger entry liability frameworks:Anticipated SEC guidance on algorithmic financial record-keeping will favor early movers that build explainable categorization engines with human-in-the-loop validation.
- Vertical-specific channel partnerships:Construction and healthcare sectors require job-costing and clinical trial billing modules that generalist platforms cannot replicate, creating white space for specialized distributors.
Industry Challenges
- ISO 27001 certification timeline compression:Enterprise procurement committees now demand current certificates with less than six months remaining validity, straining vendor audit scheduling capacity.
- Multi-jurisdictional tax engine maintenance:Real-time rate updates across Indian GST state variants, US sales tax locality databases, and EU VAT OSS schemes require continuous engineering investment that erodes SaaS margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Accounting Technology Market |
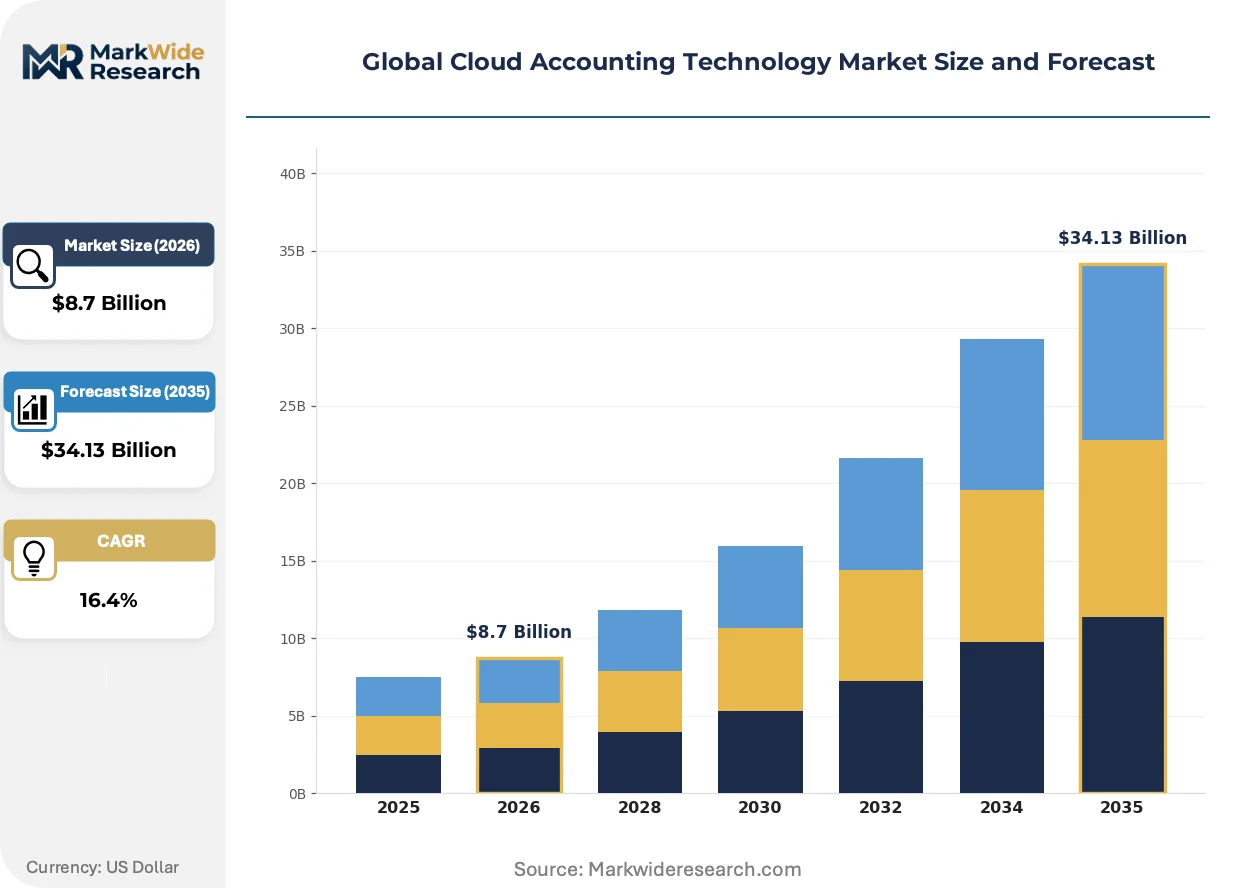
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Offering: Invoicing, Expense Management, Financial Reporting, Payroll Management, Tax Management Use Case: Small Business, Mid-Market Enterprises, Freelancers, Nonprofit Organizations End User Industry: Professional Services, Manufacturing Firms, Educational Institutions, Hospitality Companies |
| Companies Covered | Intuit Inc, Xero Limited, Sage Group plc, Microsoft Corporation, SAP SE, Oracle Corporation, Zoho Corporation, Workday Inc, FreshBooks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Accounting Technology Market Shifts & Advancements
Algorithmic automation is reconfiguring the boundary between accounting software and financial services, embedding lending and payment capabilities directly into bookkeeping workflows.
Large language model-powered transaction categorization is displacing rule-based expense classification in mid-market deployments. Finance teams at professional services firms now accept machine-generated draft entries with spot-check validation rather than line-by-line review. This compression of reconciliation labor is enabling vendors to capture adjacent workflow automation budgets previously allocated to separate procurement tools.
EU AI Act transparency requirements for automated decision-making are mandating algorithmic audit trails in expense management modules. Vendors must now document training data provenance and model versioning for high-risk financial categorization functions. German and French enterprise buyers are prioritizing platforms with pre-built explainability dashboards that satisfy national regulator expectations ahead of formal enforcement timelines.
Subscription unbundling is fragmenting how accounting capabilities are purchased. Small businesses in the United States increasingly assemble workflows across specialized point solutions rather than accepting monolithic suites. This pattern concentrates margin in API infrastructure and data synchronization layers while compressing standalone general ledger pricing toward commodity levels.
Global Cloud Accounting Technology Market Segmentation
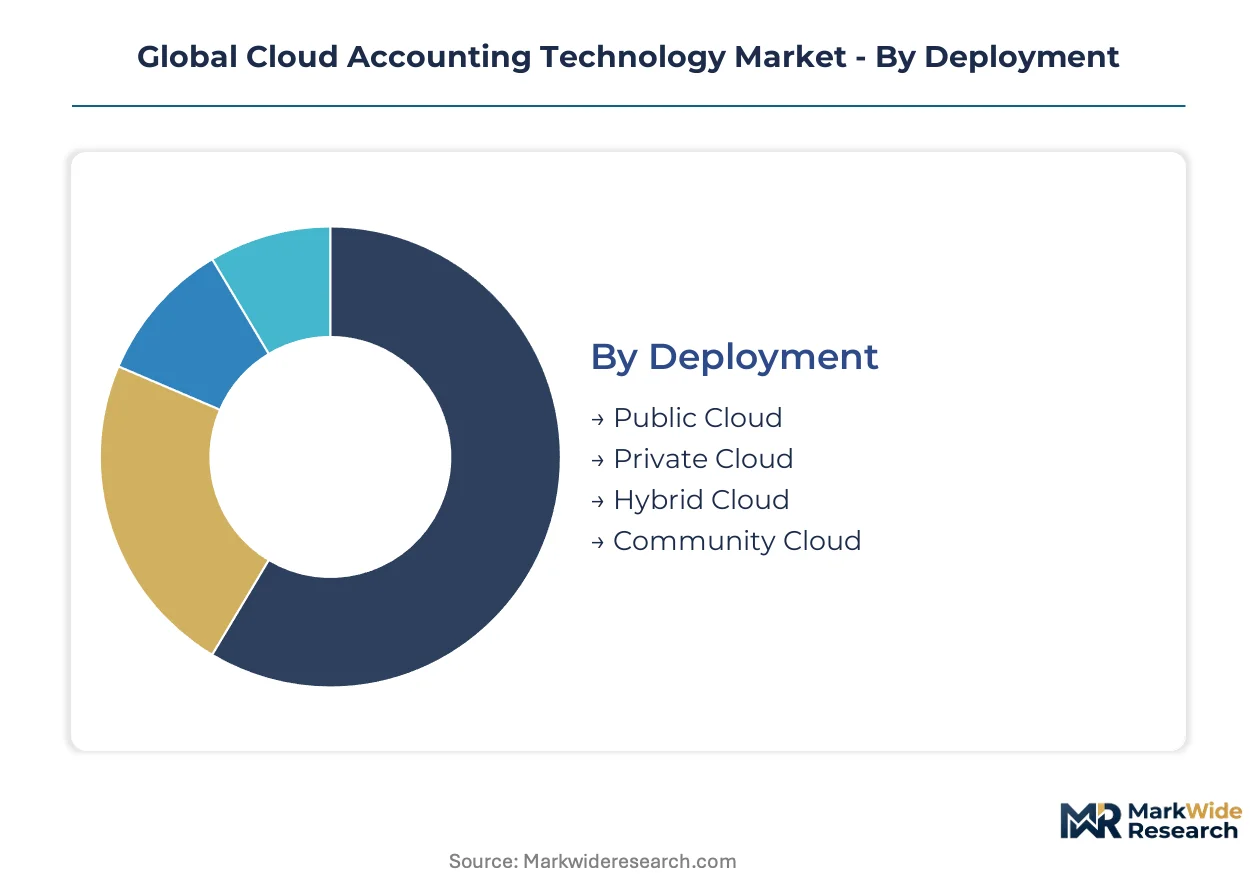
Cloud accounting technology segments fragment along deployment architecture, functional depth, and buyer sophistication. Substitution pressures vary sharply across these dimensions, with legacy on-premise ERP systems posing the gravest threat to basic cloud configurations while specialized compliance modules resist displacement.
Deployment:
Public cloud configurations face the most acute substitution pressure from hybrid alternatives as data residency mandates proliferate across jurisdictions.
- Public Cloud:Multi-tenant infrastructure delivers ledger management through shared hosting environments with SOC 2 Type II certification. Demand concentrates among United States small businesses where connectivity density supports real-time synchronization and capital constraints favor subscription models over infrastructure investment.
- Hybrid Cloud:Split architectures maintain sensitive payroll data on private nodes while pushing routine transactions to public infrastructure. German Mittelstand manufacturers and Indian pharmaceutical exporters are adopting this model to satisfy local audit trail requirements without sacrificing remote accessibility.
- Private Cloud:Dedicated single-tenant deployments serve Fortune 500 finance departments with customized tax logic retention.
- Community Cloud:Shared infrastructure among industry consortia addresses sector-specific compliance needs like nonprofit grant reporting.
Public cloud retains volume leadership; hybrid cloud holds the steepest expansion curve.
Solution Offering:
Margin concentration follows jurisdictional complexity, with tax engines commanding premium pricing against commoditized invoicing modules.
- Tax Management:Real-time rate engines synchronize across Indian GST state variants, US sales tax locality databases, and EU VAT OSS schemes. Professional services firms in Germany and France prioritize these modules to automate GoBD-compliant document generation and reduce manual reconciliation labor.
- Payroll Management:Embedded compensation processing integrates with banking-as-a-service APIs to capture payment flows natively. Mid-market enterprises in the United States and India deploy these solutions to consolidate vendor relationships and reduce separate HR system overhead.
- Expense Management:Algorithmic categorization with EU AI Act transparency documentation serves European enterprise procurement committees.
- Financial Reporting:SEC disclosure-ready audit trails attract United States public company finance teams.
- Invoicing:Basic accounts receivable automation faces the strongest price compression from freemium competitors.
Tax management captures the highest margin pool; invoicing confronts the steepest pricing erosion.
Use Case:
Buyer sophistication determines feature penetration, with mid-market procurement committees driving the most complex configuration requirements.
- Mid-Market Enterprises:Consolidated purchasing power around embedded compliance engines forces vendors to re-architect core ledgers for jurisdictional adaptability. These buyers in Germany, the United States, and India negotiate multi-year contracts with real-time support SLAs and dedicated implementation resources.
- Small Business:Fragmented demand across specialized point solutions rather than monolithic suites concentrates margin in API infrastructure layers. United States micro-enterprises increasingly assemble workflows across best-of-breed tools with native integration requirements.
- Freelancers:Simplified mobile-first interfaces with basic expense capture serve solo practitioners with minimal reconciliation needs.
- Nonprofit Organizations:Grant-compliant fund accounting with donor-restricted revenue tracking addresses specialized reporting requirements.
Mid-market enterprises command the deepest feature penetration; freelancers represent the largest addressable population.
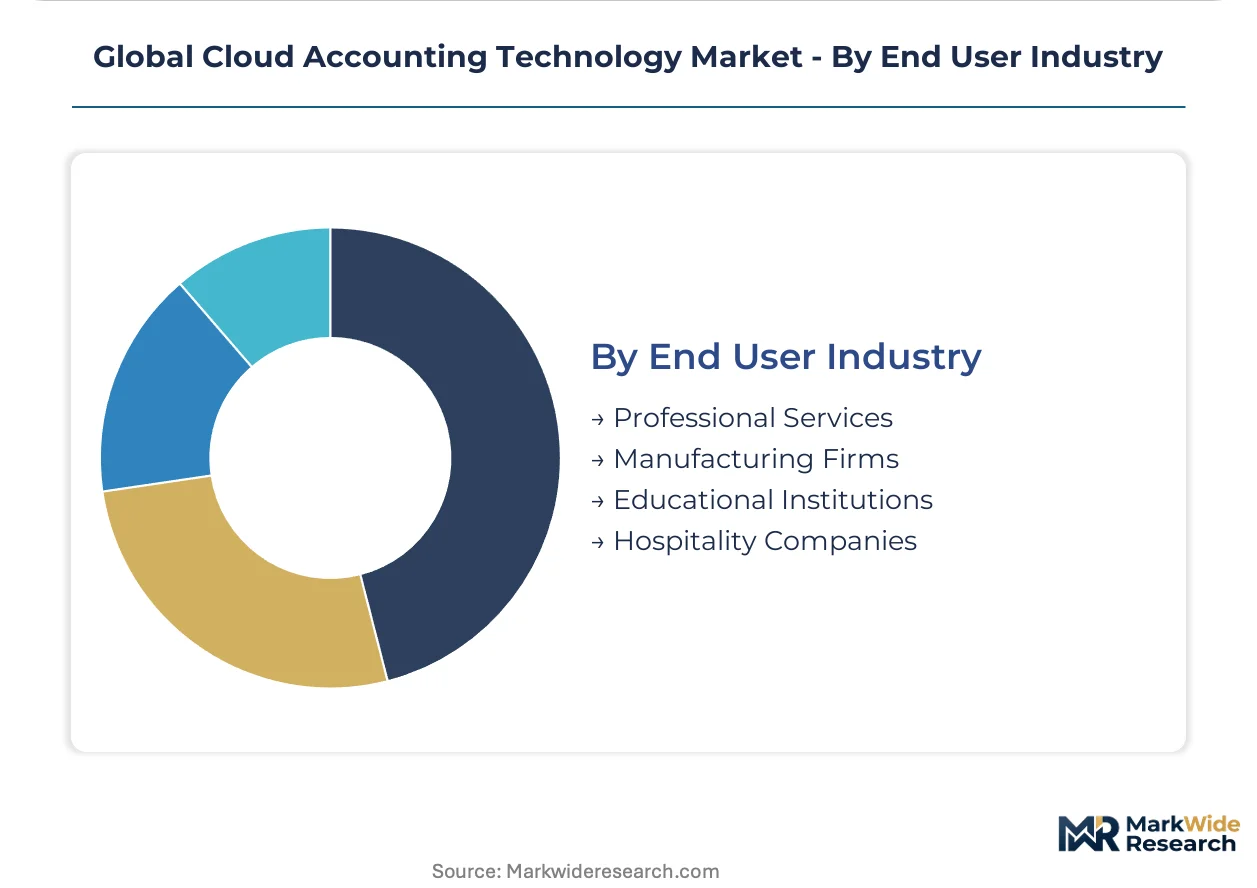
End User Industry:
Vertical-specific workflow integration creates defensible positioning against horizontal platform competition.
- Professional Services:Project-based billing with time-tracking integration and client profitability analytics serves law firms and consulting practices. These deployments in the United States and United Kingdom prioritize real-time utilization dashboards and automated invoice generation from recorded hours.
- Manufacturing Firms:Job-costing modules with inventory valuation and work-in-progress tracking address production accounting complexity. German and Indian manufacturers require these capabilities to maintain cost competitiveness under margin pressure.
- Educational Institutions:Tuition revenue recognition with semester-based deferral schedules satisfies fund accounting requirements.
- Hospitality Companies:Multi-property consolidation with daily revenue reporting and franchise fee calculations serves hotel operators.
Professional services generates the highest per-seat revenue; manufacturing shows the strongest platform stickiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premium multiples against commoditized deployments in India, where connectivity constraints compress vendor margins despite accelerating volume growth.
United States
Mid-market procurement committees in the United States consolidate purchasing around embedded compliance engines with real-time SEC disclosure capabilities. FDA oversight shapes clinical trial billing modules where accounting platforms interface with healthcare revenue cycles. San Francisco and New York clusters concentrate DevSecOps talent for SOC 2 Type II audit preparation, inflating implementation costs for vendors serving interior markets.
Germany
German Mittelstand manufacturers demand GoBD-compliant document management with selective deletion capabilities under GDPR Article 17. The EU AI Act mandates algorithmic transparency in automated expense categorization, forcing vendors to document training data provenance. Bavaria and Baden-Württemberg industrial clusters drive hybrid cloud adoption to satisfy local audit trail requirements without sacrificing remote accessibility for export operations.
India
India's PLI scheme for IT hardware expands domestic data center capacity, reducing latency for accounting SaaS penetration into tier-2 cities. GST state variant complexity concentrates margin in real-time tax rate engines. Bangalore and Hyderabad technology corridors anchor implementation support services, while Mumbai and Delhi finance teams negotiate multi-year contracts with dedicated vendor resources.
United Kingdom
Professional services firms in London prioritize real-time utilization dashboards with automated invoice generation from recorded hours. HMRC digital tax submission mandates accelerate replacement of legacy spreadsheet workflows. The Southeast England cluster concentrates API-first platform adoption where small businesses assemble workflows across specialized point solutions rather than accepting monolithic suites.
Japan
Japanese manufacturers require job-costing modules with inventory valuation and work-in-progress tracking to maintain cost competitiveness under margin pressure. METI guidelines on data sovereignty influence hybrid cloud configurations for sensitive payroll data. Tokyo and Osaka finance departments demand dedicated single-tenant deployments with customized tax logic retention, resisting multi-tenant public cloud economics.
Global Cloud Accounting Technology Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with API-first innovators competing against heritage ERP incumbents carrying decades of customized tax logic. The vendor base fragments across four distinct tiers: consumer-tax heritage platforms, pure-play cloud natives, legacy ERP extenders, and vertical specialists. Dominant competitive moves include strategic partnerships with banking-as-a-service providers and geographic expansion through compliance-heavy European deployments.
Within the heritage platform tier, Intuit Inc represents consumer-tax heritage positioning that anchors small-business onboarding flows through familiar interface patterns. Xero Limited exemplifies API-first architecture sustaining third-party ecosystem density against monolithic competitors. Sage Group plc occupies a specialized position in compliance-heavy European deployments where local tax rules dominate configuration requirements and pre-built GoBD compliance creates pricing power.
| Leading Market Players |
|---|
| Intuit Inc |
| Xero Limited |
| Sage Group plc |
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| Zoho Corporation |
| Workday Inc |
| FreshBooks |
| Others |
Supply & Pricing Matrix
Ninety-day implementation lead times for SOC 2 Type II certification anchor vendor cost structures and pricing power in San Francisco, London, and Bangalore clusters. This geographic concentration of DevSecOps talent creates tiered delivery economics where proximity to certified engineers commands premium configuration rates.
Pricing Analysis
The customization-premium spread between configured-to-order GoBD-compliant deployments and standard multi-tenant subscriptions captures the widest pricing differential. SaaS-tiered subscription models dominate, with price differentiation driven by ISO 27001 certification grade and vertical-specific tax engine complexity. Cost compression in basic invoicing modules intensifies as freemium competitors erode entry-level pricing. Small businesses exhibit highest price sensitivity, while German Mittelstand manufacturers accept premium rates for pre-built compliance automation.
Supply Chain Analysis
Inbound logistics costs for server hardware through Shanghai and Singapore trade lanes influence hybrid cloud infrastructure deployment economics. Supply concentrates in United States hyperscaler regions, Indian PLI-supported domestic data centers, and German sovereign cloud facilities. Raw material dependencies include silicon processors, storage arrays, and networking equipment. Single-source vulnerability in specialized compliance engineering talent strains vendor scaling capacity. Distribution runs through direct enterprise sales teams and API marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud accounting technology is crossing a platform-economics inflection where API interoperability determines vendor survival. Ecosystem density now matters more than feature breadth as small businesses assemble workflows across specialized point solutions.
For Market Incumbents: Secure API-first architecture investments to defend against horizontal platform substitution. Acquire specialized tax engine providers in Germany and India to lock in jurisdictional complexity moats. Channel control through embedded finance partnerships with banking-as-a-service providers creates switching cost barriers.
For New Entrants and Emerging Players: ISO 27001 fast-track certification programs open mid-market procurement committee access previously blocked by audit validity requirements. White space concentrates in construction job-costing modules and clinical trial billing for healthcare revenue cycles. Channel partnerships with vertical-specific distributors offer lower customer acquisition costs than direct enterprise sales.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy ERP incumbents carrying decades of customized tax logic that resists cloud migration. Long-term viability favors vendors with explainable AI engines that anticipate SEC guidance on algorithmic financial record-keeping. Monitor EU AI Act enforcement timelines as the signal for compliance-tech valuation inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Enables small businesses to assemble workflows across specialized point solutions rather than monolithic suites. |
| Banking-as-a-Service Partnership | Converts software vendors into primary financial data aggregators through embedded payment flow capture. |
| Compliance-Heavy Geographic Expansion | Pre-built GoBD configurations create pricing power in German Mittelstand manufacturing clusters. |
| Acquisition of Specialist Tax Engine | Jurisdictional complexity in Indian GST state variants and EU VAT OSS schemes commands premium module pricing. |
| Explainable AI Engine Development | Anticipated SEC transparency requirements favor early movers with human-in-the-loop validation workflows. |
Research Methodology
Desk research of SEC filings, hyperscaler capex disclosures, and EU regulatory frameworks preceded structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners. Primary fieldwork combined with secondary validation across customs data and SaaS subscription databases. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Variance decomposition across deployment architecture, organization size, vertical integration complexity, and regional adoption pattern shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation against macroeconomic indicators. Forecast inputs included PLI scheme capacity expansion timelines and GDPR enforcement pattern shifts.
Decision-makers should treat outputs as directional under assumptions of continued mid-market SaaS migration and stable data residency policy environments; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Virtual Fitting Software Market
Software & Services
Discount Management Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
MEP Software Market
Software & Services
Remote Sensing Software Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Software Construction Components Market
Software & Services
Global Florist Software Market
Software & Services
Video Editing Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Output Management Software Market
Software & Services
Global Auction Software Market
Software & Services
Global Inside Sales Software Market
Software & Services
Global Affiliate Software Market
Software & Services
Global Subscription Billing Software Market