
 Smart HVAC Controls Market | 2026-2036
Smart HVAC Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Smart HVAC Controls Market Analysis
Building automation engineering talent is rotating toward software-defined climate systems faster than vocational pipelines can replenish mechanical-specialist cohorts. Siemens leverages its digital twin infrastructure to anchor European commercial retrofit workflows. Johnson Controls sustains R&D intensity across sensor fusion and edge analytics for institutional clients. Daikin Industries competes through captive compressor manufacturing and integrated refrigerant circuit design.
Smart HVAC controls encompass networked hardware and software systems that modulate heating, ventilation, and air conditioning equipment through real-time sensor feedback, typically operating across 24-volt low-voltage wiring or wireless protocols with sub-100-millisecond response thresholds for zone-level damper actuation. Their primary commercial purpose is to minimize energy consumption while maintaining indoor environmental quality parameters within ASHRAE-specified ranges. Smart thermostats occupy the most visible consumer entry point yet generate thinner margin pools than zoning systems, which command premium positioning in commercial building automation tenders. Wi-Fi-enabled devices dominate residential penetration while Zigbee and Z-Wave architectures concentrate in multi-zone commercial deployments where mesh reliability and protocol interoperability determine specification wins.
EPA energy efficiency standards and ASHRAE guideline compliance windows shape product development cycles and qualification requirements for North American market access. The EU Green Deal and F-Gas Regulation accelerate refrigerant transition timelines that cascade into control system upgrade mandates across European commercial building stock. Stakeholders must monitor how building electrification codes in multiple jurisdictions redefine the boundary between HVAC controls and grid-interactive demand response assets.
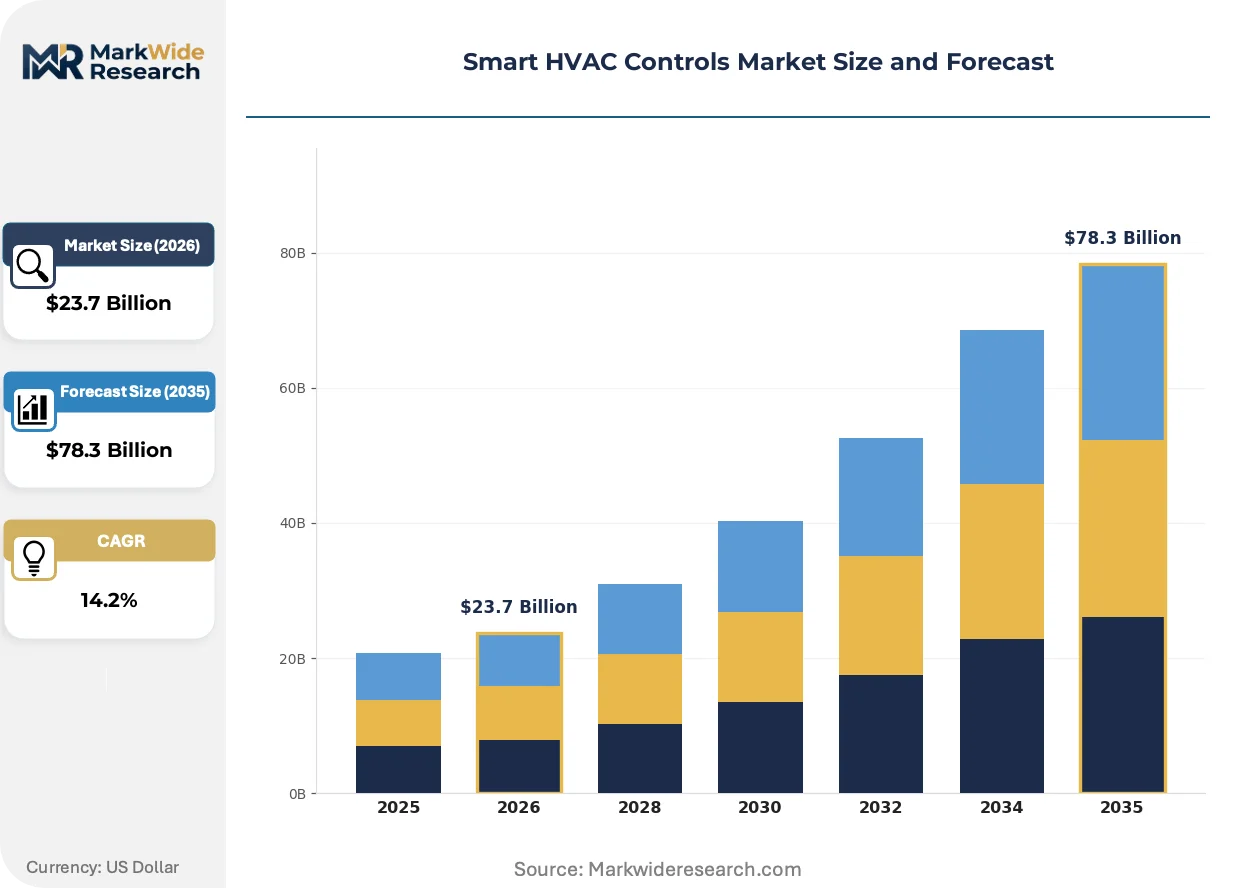
Market Dynamics
Building electrification codes are compressing upgrade cycles across aging commercial portfolios, forcing property managers to treat climate controls as grid-interactive assets rather than isolated mechanical systems. This regulatory pressure is reconfiguring procurement specifications and vendor qualification requirements.
Growth Catalysts
- Utility Rebate Programs:United States electricity providers offer tiered incentives for networked thermostat and zoning system installations, accelerating retrofit decisions in Class B office buildings.
- ASHRAE Guideline Compliance:Indoor air quality mandates require continuous monitoring and automated ventilation adjustments, embedding smart controls into base building specifications.
- Edge Analytics Convergence:Sensor fusion platforms process occupancy and environmental data locally, reducing cloud dependency while enabling sub-second damper response.
Market Restraints
- Semiconductor Supply Concentration:Zigbee and Z-Wave radio module fabrication clusters in East Asian foundries, exposing control system OEMs to allocation volatility.
- Copper Wiring Cost Exposure:24-volt low-voltage infrastructure remains copper-dependent, with commodity price swings compressing project margins on fixed-bid commercial tenders.
- Legacy Pneumatic System Entrenchment:Pre-digital HVAC infrastructure in 1970s-era buildings requires complete replacement rather than retrofit, extending payback periods.
Strategic Opportunities
- Grid-Interactive Demand Response:FERC Order 2222 implementation enables aggregated building loads to participate in wholesale markets, creating recurring revenue streams for control platforms.
- India Building Stock Electrification:Bureau of Energy Efficiency mandates for commercial cooling load management open specification windows for mesh-networked zoning systems.
- Refrigerant Transition Mandates:EPA phase-down schedules for hydrofluorocarbons force compressor replacements, bundling control upgrades into mechanical refresh cycles.
Industry Challenges
- Software-Defined Competency Gap:Mechanical engineering talent pipelines fail to produce sufficient firmware and edge computing specialists, forcing contractors to subcontract integration work.
- Multi-Protocol Interoperability Testing:BACnet, Modbus, and proprietary mesh stacks require expensive certification cycles before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart HVAC Controls Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Thermostats, Zoning Systems, HVAC Sensors, Remote Access Devices Technology: Wi-Fi, Zigbee, Z-Wave, Bluetooth End User: Residential, Commercial, Industrial, Institutional Installation Type: Retrofit, New Construction, DIY, Professional |
| Companies Covered | Siemens, Daikin Industries, Johnson Controls, Mitsubishi Electric, Lennox International, Trane Technologies, Schneider Electric, LG Electronics, Carrier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart HVAC Controls Market Emerging Trajectories
Digital twin infrastructure is migrating from design-phase simulation to operational optimization, with physics-based models now running in parallel to physical equipment. This shift is compressing commissioning timelines and enabling predictive maintenance contracts.
AI-driven fault detection algorithms process vibration, temperature, and pressure signatures to identify compressor degradation before failure. Large commercial property operators deploy these systems across portfolios to reduce emergency maintenance dispatch. Predictive analytics is displacing scheduled preventive maintenance contracts in institutional tenders.
The EU F-Gas Regulation accelerates refrigerant transition timelines that cascade into control system recalibration requirements. Equipment manufacturers must validate sensor accuracy across new thermodynamic profiles. European commercial retrofit workflows now specify control platforms with firmware update capabilities to accommodate evolving charge specifications.
Facility managers increasingly unbundle hardware procurement from ongoing optimization services, treating climate controls as subscription-managed infrastructure. Third-party energy service companies capture long-term performance contracts. This purchasing pattern shift concentrates most visibly in United States multi-site retail and healthcare portfolios where capital constraints favor operational expenditure structures.
Smart HVAC Controls Market Segmentation
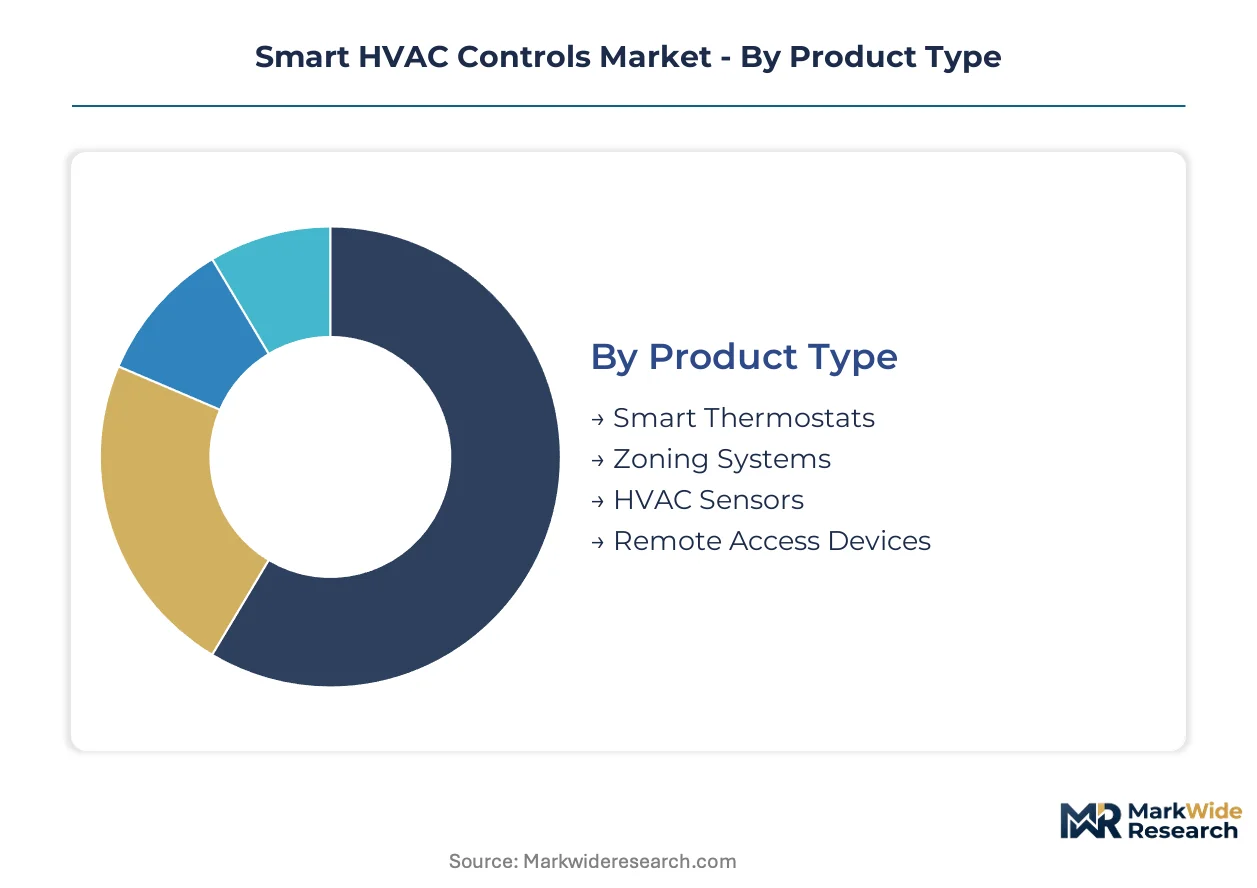
Smart HVAC controls fragment across hardware, connectivity, and deployment modes that shape procurement workflows differently. Each segment carries distinct margin structures and specification requirements that determine vendor positioning.
Product Type:
Domestic demand concentrates in retrofit-ready hardware with simplified installation, while export specifications favor modular systems for integration into building automation frameworks.
- Zoning Systems:Multi-zone damper controllers with BACnet interoperability dominate commercial building automation tenders. Class B office portfolios across the United States specify these for ASHRAE Guideline compliance and utility rebate capture.
- Smart Thermostats:Wall-mounted temperature controllers with occupancy sensing and Wi-Fi backhaul anchor residential penetration. Thin margins here push vendors toward recurring software revenue models.
- HVAC Sensors:Temperature, humidity, and CO2 probes with 4-20mA or Modbus outputs.
- Remote Access Devices:Cloud-connected gateways enabling smartphone and web portal control.
Zoning systems hold the largest share; momentum sits with smart thermostats as residential electrification codes expand.
Technology:
Protocol selection determines mesh reliability, power consumption, and integration complexity across deployment scales.
- Zigbee:Mesh networking stack operating at 2.4 GHz with self-healing topology and sub-100-millisecond latency for damper actuation. Commercial multi-zone installations across Germany and France specify Zigbee for its interoperability certification.
- Z-Wave:Sub-GHz mesh protocol with longer range per hop and lower interference susceptibility. North American residential and light commercial deployments favor this for its dedicated spectrum allocation.
- Wi-Fi:IP-native connectivity leveraging existing infrastructure, dominant in consumer thermostats.
- Bluetooth:Point-to-point protocol for commissioning and mobile device pairing, not primary operational backhaul.
Zigbee commands commercial specification wins; Z-Wave climbs fastest in residential retrofit channels.
End User:
Customer type dictates performance requirements, contract structures, and replacement cycle timing.
- Commercial:Office, retail, and hospitality properties with networked building automation systems and continuous commissioning mandates. EPA energy efficiency thresholds and FERC Order 2222 participation drive specification of grid-interactive controls.
- Residential:Single-family and multi-family dwellings with consumer-facing interfaces and utility rebate eligibility. Installation simplicity and smartphone app quality determine brand selection.
- Industrial:Manufacturing and warehouse facilities with process-critical environmental control and integration into SCADA systems.
- Institutional:Schools, hospitals, and government buildings with extended procurement cycles and preventive maintenance contracts.
Commercial generates the highest absolute revenue; residential offers the steepest expansion trajectory as electrification codes proliferate.
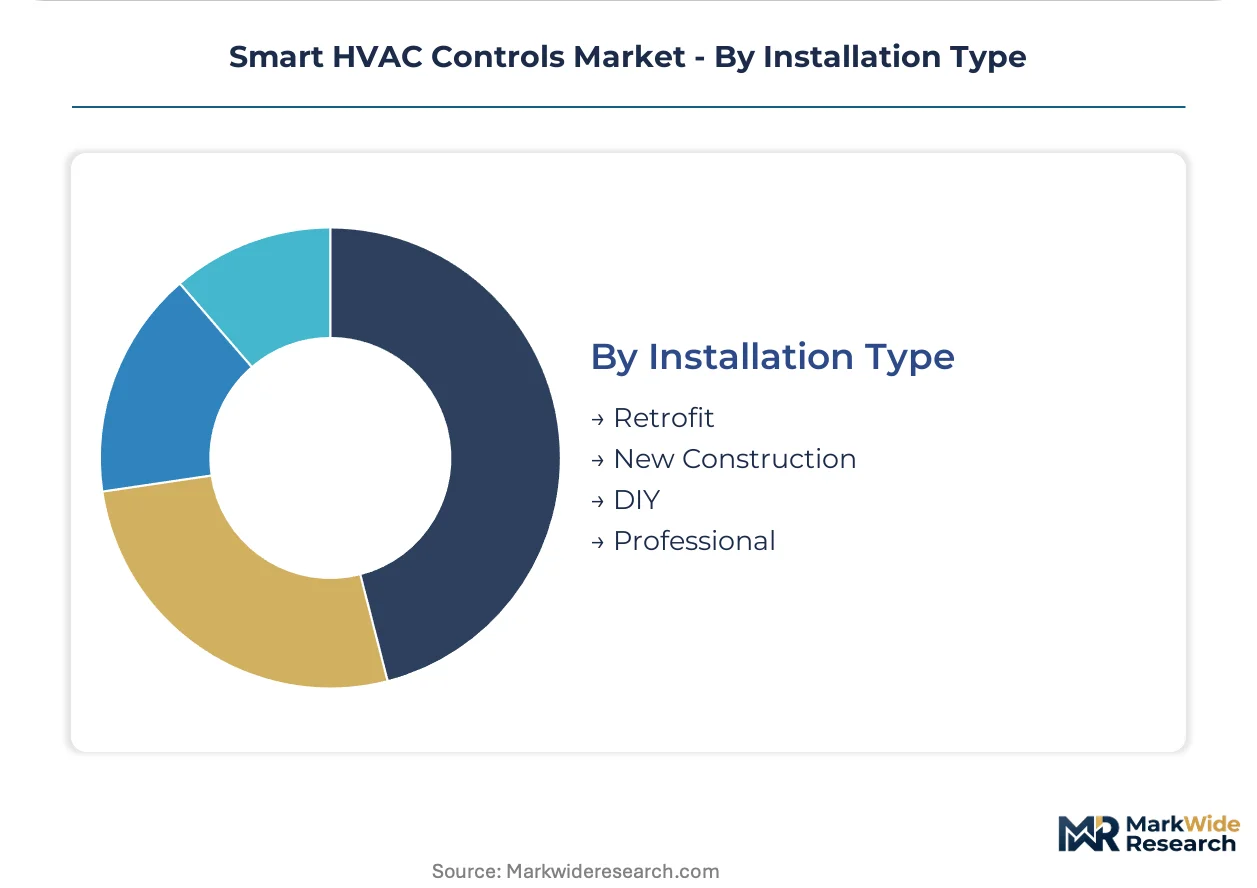
Installation Type:
Deployment method shapes channel economics and customer acquisition costs across market tiers.
- Retrofit:Replacement of legacy pneumatic or basic digital controls in existing buildings. The United States aging office stock and refrigerant transition mandates bundle control upgrades with compressor replacements.
- Professional:Certified contractor installation with commissioning and warranty coverage. Commercial and institutional procurement requires this for code compliance and insurance coverage.
- New Construction:Specification during building design with integration into digital twin workflows.
- DIY:Consumer self-installation of retail thermostats with app-guided setup.
Retrofit dominates current volume; professional installation captures expanding share as grid-interactive requirements complicate deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility rebate structures and building electrification codes drive divergent procurement patterns across major economies. The United States prioritizes grid-interactive demand response capabilities, while European specifications emphasize refrigerant transition compatibility and digital twin integration.
United States
Class B office portfolios in Texas and Illinois accelerate networked zoning system procurement to capture utility incentive tiers. FERC Order 2222 implementation enables aggregated building loads to participate in wholesale electricity markets. Dallas-Fort Worth and Chicago metropolitan clusters concentrate retrofit activity as aging commercial stock faces EPA energy efficiency compliance deadlines.
Germany
Commercial building automation tenders specify Zigbee-interoperable multi-zone controllers for ASHRAE-equivalent indoor air quality mandates. The EU F-Gas Regulation compresses refrigerant transition timelines that cascade into control system recalibration requirements. Munich and Frankfurt engineering clusters anchor digital twin infrastructure deployment across European retrofit workflows.
China
Rapid urban commercial construction in Yangtze River Delta cities drives specification of mesh-networked climate systems with edge analytics capabilities. National dual carbon goals tighten energy efficiency thresholds for large-scale properties. Shanghai and Hangzhou manufacturing bases supply radio modules and sensor assemblies for domestic and export markets.
India
Bureau of Energy Efficiency mandates for commercial cooling load management open specification windows for professional installation channels. Building electrification codes in Maharashtra and Gujarat accelerate procurement cycles across new commercial construction. Mumbai and Ahmedabad property developers bundle smart controls into base building specifications to meet compliance thresholds.
Japan
Institutional procurement in Tokyo and Osaka metropolitan areas emphasizes predictive maintenance contracts and sensor fusion platforms. METI efficiency standards for commercial buildings embed continuous commissioning requirements into climate control specifications. Nagoya industrial clusters manufacture precision damper actuators and refrigerant pressure sensors for regional supply chains.
Smart HVAC Controls Market Vendor Landscape
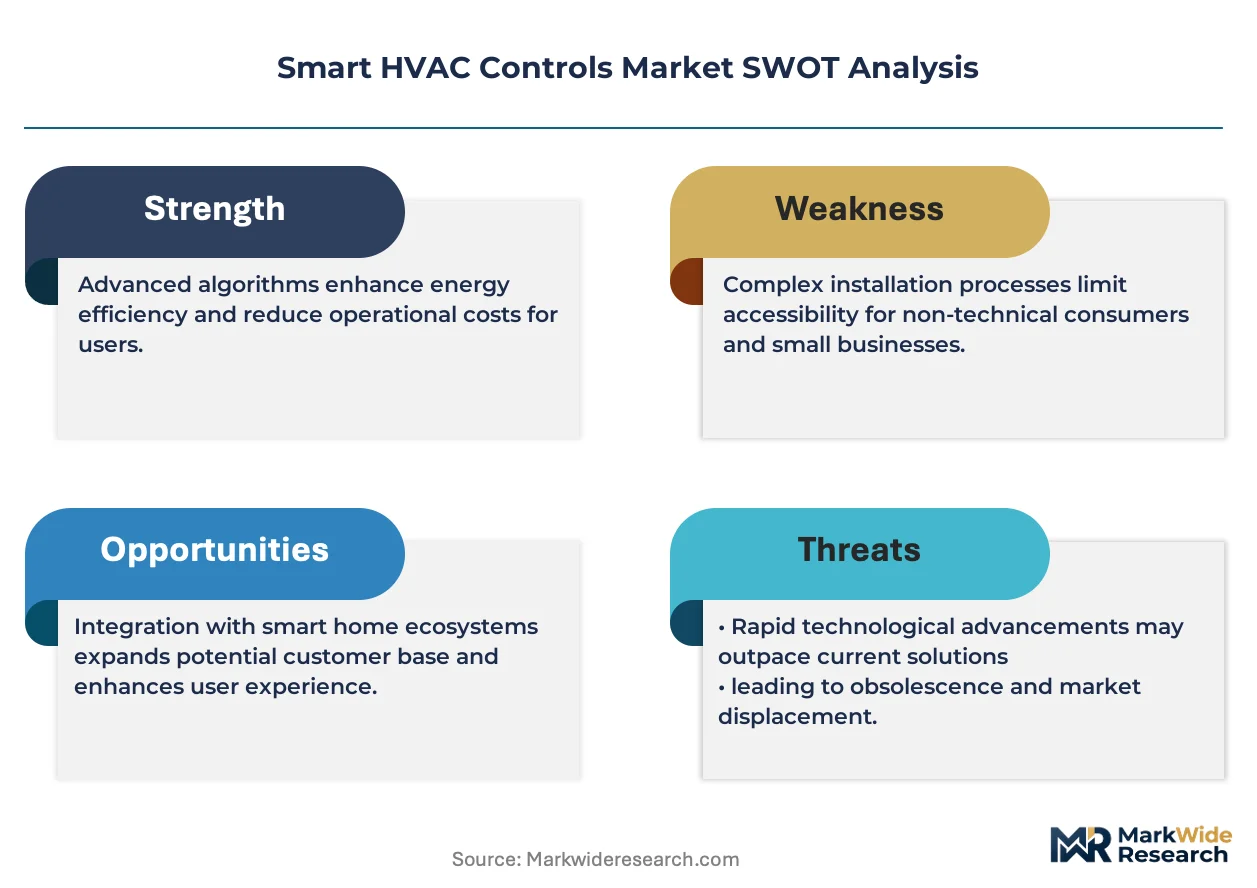
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated in captive component manufacturing and digital infrastructure ownership. The middle tier fragments across protocol-specific engineering houses and regional installation contractors. Three archetypes dominate: full-stack building automation platforms, captive compressor-to-control integrated suppliers, and software-defined climate optimization specialists. Competitive moves center on backward integration into sensor manufacturing and strategic technology licensing for mesh protocol interoperability.
Among Germany-based industrial conglomerates, Siemens and Daikin Industries exemplify divergent strategic positioning within the integrated tier. Siemens anchors European commercial retrofit workflows through digital twin infrastructure, while Daikin Industries occupies a position emphasizing captive compressor manufacturing and refrigerant circuit integration. Johnson Controls represents the building automation platform archetype, with R&D intensity concentrated across sensor fusion and edge analytics deployment for institutional client portfolios.
| Leading Market Players |
|---|
| Siemens |
| Daikin Industries |
| Johnson Controls |
| Mitsubishi Electric |
| Lennox International |
| Trane Technologies |
| Schneider Electric |
| LG Electronics |
| Carrier |
| Others |
Supply Flow & Price Mechanics
Copper-to-aluminum wiring substitution in 24-volt low-voltage infrastructure is simultaneously shifting procurement geography toward Southeast Asian cable manufacturers and compressing project margins on fixed-bid commercial tenders across United States Class B office retrofits.
Pricing Analysis
Long-term performance contracts dominate institutional procurement, embedding subscription-based optimization services alongside hardware deployment. Three-tier pricing structure across premium BACnet-interoperable zoning systems, standard Wi-Fi thermostats, and economy-grade sensor bundles reflects certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because semiconductor allocation volatility from East Asian foundries squeezes radio module availability. Residential DIY buyers exhibit highest price sensitivity, while commercial property managers prioritize ASHRAE compliance and utility rebate capture over unit economics.
Supply Chain Analysis
Port congestion on the Shanghai-Los Angeles trade lane elevates inbound logistics costs for Zigbee and Z-Wave radio modules fabricated in Taiwan, South Korea, and China. Control system OEMs draw from concentrated semiconductor foundry capacity, copper wiring mills in Chile and Peru, and precision damper actuator manufacturing in Japan. Single-source vulnerability in mesh protocol chip fabrication exposes vendors to allocation volatility during demand spikes. Distribution runs through certified contractor networks for commercial and institutional channels, with retail direct-to-consumer for residential thermostats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart HVAC controls represent an early-cycle expansion story as building electrification codes across multiple jurisdictions mandate networked climate systems in aging commercial stock.
For Market Incumbents: Compound defensive positioning through backward integration into sensor manufacturing and captive compressor supply chains. Deepen firmware development capabilities to counter software-defined climate optimization specialists entering from adjacent building automation verticals. Prioritize Zigbee and Z-Wave interoperability certification investment to lock specification wins in European and North American commercial tenders.
For New Entrants and Emerging Players: Differentiate on edge analytics convergence and predictive maintenance service bundling for institutional healthcare and education portfolios. White-space targets include India's Bureau of Energy Efficiency compliance-driven commercial construction in Maharashtra and Gujarat, plus United States multi-site retail chains seeking operational expenditure structures over capital-intensive hardware procurement. Pursue direct utility partnership channels for rebate-program eligibility.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed building automation engineering houses lacking digital twin infrastructure ownership. Long-term viability centers on software-defined competency capture and grid-interactive demand response platform integration. The signal to watch is FERC Order 2222 implementation velocity enabling aggregated building load participation in wholesale electricity markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Development | Edge analytics capabilities reduce cloud dependency for sub-second damper response in commercial zoning systems. |
| Digital Twin Infrastructure Deployment | Physics-based operational models compress commissioning timelines and enable predictive maintenance contract capture. |
| Mesh Protocol Interoperability Certification | Zigbee and Z-Wave stack validation determines specification wins in German and French commercial building automation tenders. |
| Grid-Interactive Control Integration | FERC Order 2222 compliance enables aggregated building load participation in wholesale electricity markets. |
| Refrigerant Transition-Compatible Firmware | EPA hydrofluorocarbon phase-down schedules bundle control upgrades into compressor replacement cycles. |
Methodological Framework
A spread of perspectives from building automation engineers, commercial property portfolio managers, HVAC contractor operations heads, and utility demand response program directors converged on the working assumptions. Primary interviews combined with secondary validation from EPA energy efficiency filings, FERC regulatory dockets, ASHRAE guideline documentation, and Bureau of Energy Efficiency mandate records. Bottom-up unit economics triangulated against top-down building stock electrification penetration models.
Product type, connectivity protocol, end-user vertical, and installation mode shaped the segmentation dimensions modeled across the analysis window. CAGRs derived from utility rebate program expansion trajectories, refrigerant transition mandate timelines, and building electrification code adoption curves. Forecast inputs incorporated semiconductor foundry capacity utilization and copper commodity price volatility assumptions.
Decision-makers should treat outputs as directional under steady regulatory enforcement and technology adoption assumptions; material deviation would warrant model refresh. Specific risk factors include F-Gas Regulation acceleration in Europe, semiconductor allocation shocks from East Asian supply concentration, and legacy pneumatic system replacement cost overruns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Smart Programmable Thermostat Market
Energy Management Systems
Global Next-Generation Building Energy Management Systems Market
Energy Management Systems
Global Smart Air Conditioning Market
Energy Management Systems
Grid Optimization Solution Market
Energy Management Systems
Saudi Arabia Portable Air Conditioner Market
Energy Management Systems
Intelligent Digital Meter Market
Energy Management Systems
GCC Desert Air Coolers Market
Energy Management Systems
Global Data Center Energy Management Solution Market
Energy Management Systems
Global Digital Utility Market
Energy Management Systems
North America Residential Lighting Control System Market
Energy Management Systems
Africa Digital Showers Market
Energy Management Systems
Outage Management System (OMS) Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
USA and Canada Portable Air Conditioner Market
Energy Management Systems
Chemical Control Systems Market
Energy Management Systems
Data Center Power Management Market