
 Cell Culture Media Bags Market | 2026-2036
Cell Culture Media Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Culture Media Bags Market Analysis
Contract manufacturing organizations is collapsing the historical procurement dominance of captive biopharma facilities in cell culture media bags. Thermo Fisher Scientific leverages its integrated life sciences platform to control distribution across North American biologics corridors. Sartorius AG anchors European supply through specialized single-use technologies for adherent and suspension cell lines. Merck KGaA differentiates via membrane filtration compatibility testing bundled with media bag portfolios.
Cell culture media bags are sterile, flexible containers engineered from multilayer polymer films—typically incorporating low-density polyethylene, ethylene vinyl acetate, and nylon barrier layers—designed for aseptic storage, transport, and dispensing of nutrient media in mammalian and microbial cell propagation. These bags integrate ports, tubing, and closure systems validated for gamma irradiation sterilization, with working volumes spanning 100 mL to 5 L configurations serving upstream bioprocessing workflows. Disposable bags command the largest revenue share due to elimination of cleaning validation burdens in multi-product facilities, while cell therapy applications represent the fastest-expanding segment driven by autologous manufacturing scale-out. Plastic bags retain cost advantages for commodity media storage, though glass bottles persist in serum and specialty additive niches requiring oxygen barrier performance.
FDA enforces Current Good Manufacturing Practice for biological products under 21 CFR Parts 600 through 680, requiring extractables and leachables qualification for all fluid contact surfaces in cell culture media bags. EMA's Guideline on Plastic Immediate Packaging Materials and ISO 10993 biocompatibility standards collectively shape material selection, supplier qualification timelines, and documentation burdens for market access across regulated jurisdictions. Stakeholders must monitor evolving cell therapy-specific guidance from FDA's Office of Therapeutic Products, as forthcoming sterility assurance level requirements for closed-system processing will redefine bag design specifications and validation protocols.
Market Dynamics
Single-use technologies are collapsing the traditional stainless-steel infrastructure model in bioprocessing, forcing media bag suppliers to reconfigure manufacturing footprints around gamma-irradiation capacity and polymer film supply chains.
Growth Catalysts
- EMA sterility assurance mandates:Tightened Guideline on Plastic Immediate Packaging Materials is compelling cell therapy manufacturers to upgrade to closed-system bags with validated barrier properties.
- Adherent cell line expansion:Allogeneic therapy developers are scaling out planar culture platforms that consume 3-5× more media bag surface area per dose than suspension systems.
- Massachusetts biomanufacturing clustering:Concentrated facility builds in Cambridge and Worcester are generating localized procurement volumes that justify regional bag molding investments.
Market Restraints
- Ethylene vinyl acetate supply concentration:Three Asian polymer producers control 70% of medical-grade EVA resin, exposing bag converters to input cost volatility and allocation risk.
- Glass bottle substitution in serum storage:Oxygen barrier requirements for heat-sensitive additives preserve legacy packaging in high-value niche applications.
- ISO 10993 biocompatibility timelines:Extended extractables testing protocols stretch supplier qualification cycles to 18-24 months, freezing new entrants from rapid market access.
Strategic Opportunities
- North Carolina Research Triangle expansion:RTP biomanufacturing campus developments are attracting contract manufacturers underserved by incumbent bag distributors.
- Closed-system welding integration:Convergence of aseptic tubing welders with pre-sterilized bag manifolds is enabling fully automated media transfer without cleanroom intervention.
- IRA biomanufacturing reshoring incentives:Domestic production tax credits are creating favorable economics for US-based bag film extrusion and gamma sterilization facilities.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with multilayer film coextrusion expertise are concentrated among legacy medical packaging firms, constraining supplier R&D velocity.
- Legacy MES integration friction:Electronic batch record systems at established biopharma sites require custom API development to accommodate single-use bag RFID tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Culture Media Bags Market |
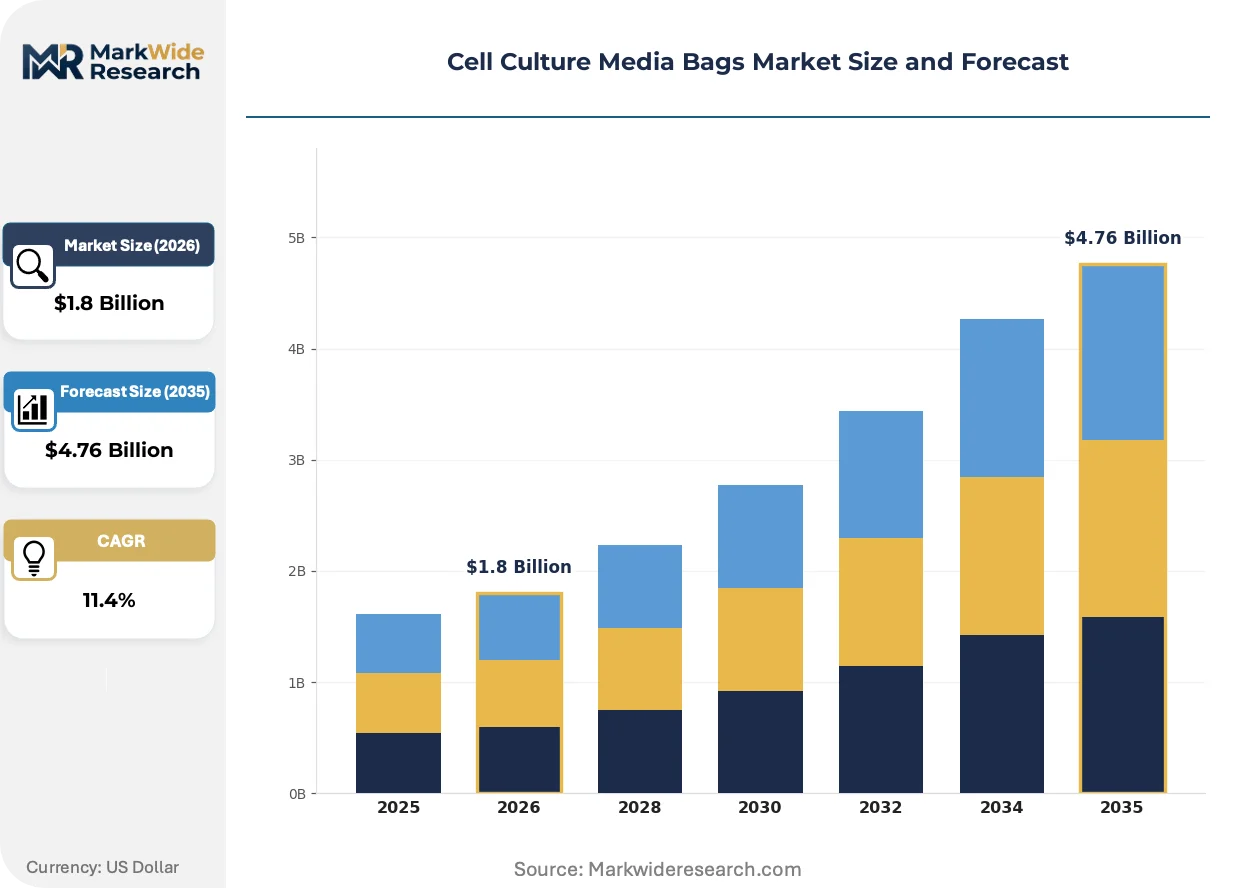
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Bags, Glass Bottles, Disposable Bags, Reusable Containers Ending User: Biopharmaceutical Companies, Research Institutes, Contract Manufacturing Organizations, Academic Institutions Size: 100 mL, 500 mL, 1 L, 5 L Application: Tissue Engineering, Drug Discovery, Vaccine Production, Cell Therapy |
| Companies Covered | Thermo Fisher Scientific, Sartorius AG, Merck KGaA, Danaher Corporation, Corning Incorporated, Lonza Group, Saint-Gobain Performance Plastics, GE Healthcare, Avantor Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Culture Media Bags Market Emerging Trajectories
Film engineering advances and sterility assurance technologies are redefining performance benchmarks, while procurement centralization is compressing vendor margins and consolidating specification authority.
Multilayer coextruded films with ethylene vinyl alcohol barrier layers are displacing conventional nylon-reinforced constructions in high-value media applications. Cell therapy manufacturers in Massachusetts and North Carolina are specifying these upgraded materials for 2-year shelf-life requirements. The shift is displacing incumbent bag converters lacking in-house film extrusion capabilities and forcing partnerships with specialized polymer suppliers.
FDA's evolving guidance on closed-system processing for cell therapy manufacturing is mandating redundant sterile barriers and integrated sampling ports. The regulation is accelerating validation documentation burdens and reshaping R&D priorities toward integrated manifold designs. Autologous therapy developers are responding by consolidating procurement around suppliers with pre-validated closed-system platforms.
Direct sourcing from bag converters is bypassing traditional distribution intermediaries in large-volume contract manufacturing relationships. CDMOs with standardized platform processes are negotiating multi-year supply agreements that bundle film, port, and tubing specifications. The pattern is most visible in North Carolina's Research Triangle, where facility clustering enables consolidated procurement volumes that warrant dedicated manufacturing lines.
Cell Culture Media Bags Market Segmentation
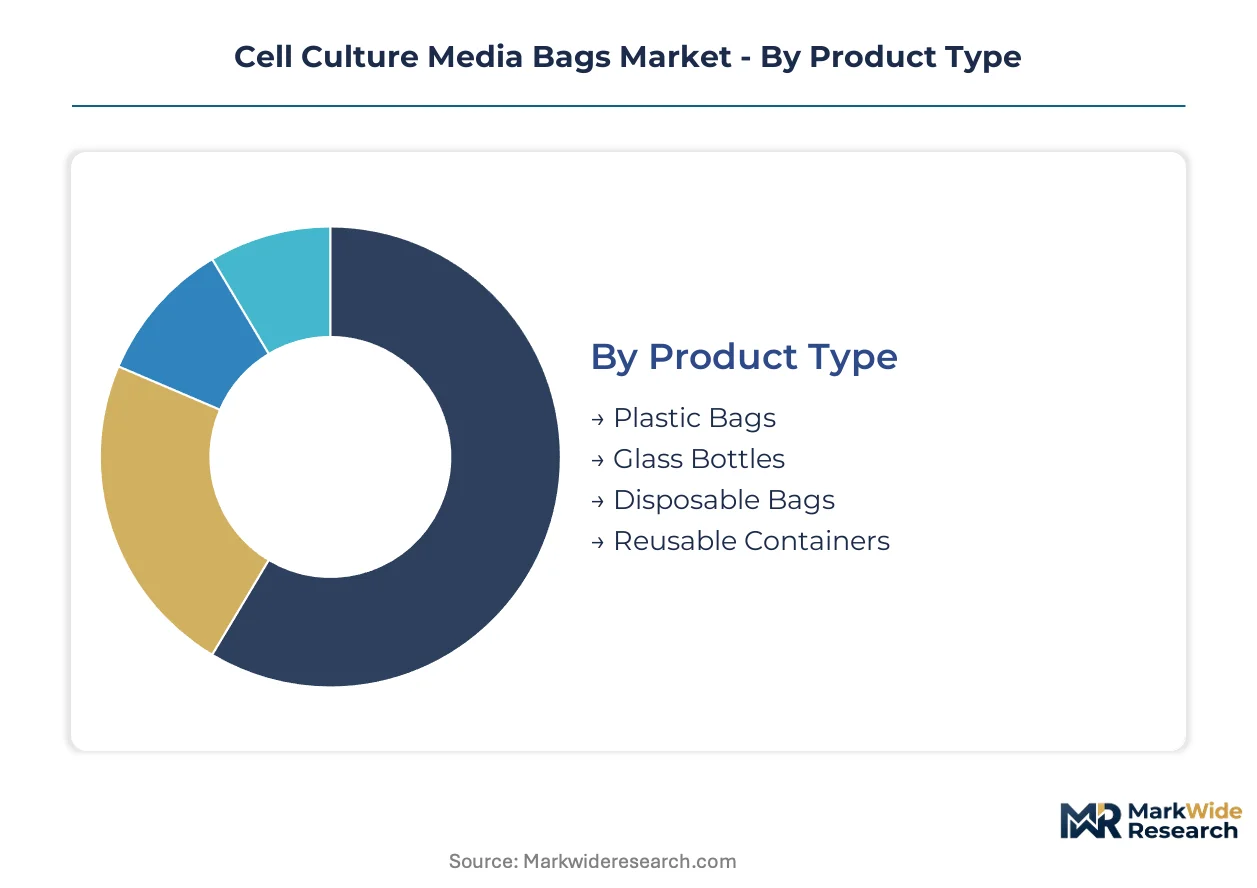
Segmentation in cell culture media bags reflects divergent sterility requirements across bioprocessing workflows and the tension between single-use convenience and legacy packaging durability. Each dimension carries distinct substitution pressures that reshape procurement patterns and supplier positioning.
Product Type:
Glass bottles face the most acute substitution threat as biopharma facilities eliminate cleaning validation burdens, though oxygen barrier needs preserve niche demand for heat-sensitive additives.
- Plastic Bags:Multilayer polyethylene-EVA-nylon constructions dominate commodity media storage with gamma-irradiation compatibility and cost advantages. Demand concentrates in high-volume vaccine production facilities seeking to minimize capital equipment footprint.
- Disposable Bags:Pre-sterilized, closed-system configurations with integrated tubing and sampling ports eliminate cross-contamination risks in multi-product CDMO operations. Massachusetts biomanufacturing clusters are specifying these for autologous cell therapy platforms requiring rapid changeover between patient batches.
- Glass Bottles:Borosilicate constructions with septum closures persist in serum and specialty additive storage where oxygen ingress compromises media stability.
- Reusable Containers:Stainless-steel vessels with steam-in-place capability retain footholds in legacy vaccine manufacturing infrastructure resistant to single-use conversion capital costs.
Disposable bags anchor the volume base while plastic bags gain share at the steepest rate as mid-scale biopharma facilities standardize on flexible film platforms.
Ending User:
Procurement authority is migrating toward contract manufacturing organizations as platform standardization enables consolidated volume negotiations.
- Biopharmaceutical Companies:Captive manufacturing operations specify custom bag configurations with proprietary port geometries and RFID tracking integration for electronic batch record compliance.
- Contract Manufacturing Organizations:Multi-tenant facilities in North Carolina's Research Triangle are driving demand for closed-system manifolds with validated sterile welding compatibility, prioritizing rapid product changeover over customization.
- Research Institutes:Smaller-volume procurement of 100-500 mL configurations for early-stage process development, with limited bargaining power versus bag converters.
- Academic Institutions:Price-sensitive purchasing of standard polyethylene bags without specialized barrier layers, often through distributor intermediaries rather than direct converter relationships.
Contract manufacturing organizations now capture procurement volume leadership while biopharmaceutical companies retreat to specialized, high-margin applications.
Size:
Volume economics favor larger configurations as upstream bioprocessing scales toward single-use bioreactor integration.
- 5 L:Integrated with stirred-tank bioreactor feed systems in commercial-scale antibody production, requiring validated aseptic connection protocols and pressure-rated film constructions.
- 1 L:Standard for seed train expansion in mammalian cell culture, balancing handling ergonomics with sufficient media volume for multiple passage expansions.
- 500 mL:Common in process development and small-scale viral vector production where media formulation screening demands frequent changeover.
- 100 mL:Restricted to early-stage cell line development and cryopreservation media aliquoting in academic and research settings.
The 5 L configuration anchors manufacturing-scale procurement while 1 L formats expand most quickly as mid-tier CDMOs build out platform processes.
Application:
Cell therapy's stringent sterility requirements are forcing material upgrades that cascade into adjacent application segments.
- Cell Therapy:Autologous manufacturing demands closed-system bags with redundant sterile barriers, extractables/leachables documentation, and 2-year shelf-life validation. FDA's Office of Therapeutic Products guidance is mandating integrated sampling ports for in-process testing without breach.
- Vaccine Production:Viral and bacterial vaccine platforms require gamma-stable films compatible with pH-adjusted media and adjuvant formulations, with demand clustering in emerging biomanufacturing hubs seeking pandemic preparedness infrastructure.
- Tissue Engineering:Scaffold seeding applications favor larger surface-area bags for adherent cell expansion, with planar culture configurations consuming elevated media volumes per therapeutic unit.
- Drug Discovery:High-throughput screening operations prioritize cost minimization over specialized barrier properties, accepting standard EVA constructions with shorter validated shelf lives.
Vaccine production maintains the installed volume base while cell therapy commands the steepest expansion trajectory as allogeneic platforms scale toward commercial manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European distribution efficiency for temperature-sensitive bioprocessing materials. Regional procurement clusters around gamma-irradiation facilities and polymer film extrusion plants that serve cell therapy manufacturing hubs.
United States
FDA's 21 CFR Parts 600-680 biologics regulations and IRA domestic production incentives are accelerating bag converter investments. Massachusetts biomanufacturing corridors in Cambridge and Worcester concentrate autologous therapy demand. North Carolina's Research Triangle Park attracts CDMOs seeking consolidated procurement volumes for closed-system platforms.
Germany
EMA's Guideline on Plastic Immediate Packaging Materials and ISO 10993 biocompatibility standards shape supplier qualification protocols. Baden-Württemberg hosts specialized polymer film coextrusion operations serving European biologics manufacturers. Bavaria's Munich biotech cluster drives demand for validated sterile barrier configurations.
Switzerland
Swissmedic's stringent extractables documentation requirements elevate material validation burdens for market access. Basel's pharmaceutical manufacturing concentration generates procurement volumes for high-barrier multilayer films. The country's precision polymer processing heritage supports specialized port and tubing integration capabilities.
China
NMPA's evolving biological product packaging standards and dual carbon goals are reshaping domestic manufacturing footprints. Yangtze River Delta biopharma parks in Shanghai and Suzhou scale mammalian cell culture operations. Local polymer producers are expanding medical-grade EVA resin capacity to reduce import dependency.
India
CDSCO's tightening sterility assurance requirements for biological products are elevating documentation standards for bag converters. Karnataka's Bangalore biotech corridor attracts contract research organizations scaling upstream processing. PLI scheme incentives for domestic medical device manufacturing are stimulating local film extrusion investments.
Cell Culture Media Bags Market Vendor Landscape
Listed leaders compete with private specialists across integrated life sciences platforms and single-use technology portfolios. The market structure concentrates among diversified conglomerates with captive polymer processing capabilities and specialized converters with proprietary film formulations. Two strategic archetypes dominate: integrated platform providers bundling bags with analytical services, and pure-play single-use specialists with dedicated gamma-sterilization infrastructure. Competitive moves center on backward integration into film extrusion and multi-year supply agreements with high-volume CDMOs.
Within the integrated platform tier, Thermo Fisher Scientific and Danaher Corporation exemplify conglomerate-scale positioning across North American biologics corridors. Sartorius AG occupies a specialized position among European single-use technology providers. These three anchors represent divergent strategic postures: the American diversified life sciences model versus the German precision-engineering approach to adherent and suspension cell line applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius AG |
| Merck KGaA |
| Danaher Corporation |
| Corning Incorporated |
| Lonza Group |
| Saint-Gobain Performance Plastics |
| GE Healthcare |
| Avantor Inc. |
| Others |
Supply Flow & Price Mechanics
Multilayer coextruded film adoption is displacing conventional nylon-reinforced constructions while simultaneously shifting supply geography toward polymer extrusion hubs in Germany and the United States and compressing pricing premiums for legacy bag converters lacking in-house film capabilities.
Pricing Analysis
Volume-discount tiering separates closed-system cell therapy configurations from commodity plastic bag formats, with three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade margins for FDA-validated extractables documentation and gamma-irradiation sterility assurance, while economy tiers serve academic procurement through distributor intermediaries. Pricing pressure stems from CDMO consolidated procurement volumes that leverage multi-year supply agreements to extract concessionary terms. Research institutes exhibit highest price sensitivity due to fragmented purchasing authority, whereas autologous therapy developers prioritize barrier performance over unit cost.
Supply Chain Analysis
China, South Korea, and Germany anchor medical-grade ethylene vinyl acetate resin production, with three Asian polymer producers controlling the majority share of input supply. Bag converters draw from concentrated EVA, ethylene vinyl alcohol, and low-density polyethylene feedstocks, with formulation chemists for multilayer coextrusion concentrated among legacy medical packaging firms. Single-source vulnerability in gamma-irradiation sterilization capacity creates chokepoint risk for pre-sterilized bag supply. Distribution runs through direct converter relationships for high-volume CDMOs and distributor intermediaries for fragmented academic and research procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating among contract manufacturing organizations as platform standardization enables consolidated volume negotiations, shifting buyer-power dynamics toward multi-tenant facilities in clustered biomanufacturing corridors.
For Market Incumbents: Compound backward integration into polymer film extrusion to defend margin position against specialized converters with proprietary multilayer formulations. Prioritize captive gamma-irradiation capacity additions in North Carolina and Massachusetts to secure regional supply commitments from CDMOs scaling autologous manufacturing. Invest in extractables testing laboratories to accelerate supplier qualification cycles that currently freeze new entrants from rapid FDA compliance. For New Entrants and Emerging Players: Rapid-changeover service-layer gaps in CDMO sterile welding integration present white-space targets where incumbents under-serve with rigid platform configurations. Target North Carolina Research Triangle expansion zones underserved by established bag distributors with closed-system manifold pre-validation bundled with local technical support. Pursue go-to-market positioning around 18-24 month ISO 10993 qualification acceleration through specialized polymer science talent recruitment from legacy medical packaging firms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed single-use technology specialists lacking integrated life sciences platform scale. Five-to-ten year viability hinges on film formulation IP durability and gamma-sterilization facility network density. Acquisition target archetype: regional bag converters with validated closed-system platforms and underutilized extrusion capacity. Signal to watch: FDA Office of Therapeutic Products sterility assurance level guidance publication triggering redesign capex cycles across installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive polymer supply secures margin control against EVA resin allocation volatility from Asian producers. |
| Gamma Sterilization Facility Expansion | Regional irradiation capacity in Massachusetts and North Carolina shortens lead times for autologous therapy supply. |
| Closed-System Manifold Pre-Validation | FDA-aligned extractables documentation accelerates CDMO procurement decisions for cell therapy platforms. |
| Extractables Testing Laboratory Investment | In-house ISO 10993 qualification reduces supplier onboarding cycles from 24 months toward competitive benchmarks. |
| Multi-Year CDMO Supply Agreements | Consolidated volume commitments from Research Triangle facilities warrant dedicated manufacturing line economics. |
Methodological Framework
Operator-level perspectives from bioprocess engineers, CDMO procurement directors, regulatory affairs specialists, and polymer formulation chemists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA 21 CFR guidance documents, EMA plastic packaging guidelines, ISO 10993 biocompatibility standards, and SEC filings from listed life sciences conglomerates. Bottom-up demand modeling triangulated against top-down supply-side capacity assessments across gamma-irradiation and film extrusion infrastructure.
Sensitivity analysis framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, end-user archetype, working volume configuration, and application workflow. Treatment of cell therapy versus vaccine production versus drug discovery use cases captured divergent sterility requirement intensities. CAGRs derived from installed base evolution, replacement cycle dynamics, and pipeline conversion rates for autologous and allogeneic platforms. Industry-specific inputs incorporated EMA sterility assurance mandate implementation timelines and IRA domestic production incentive uptake.
Underlying assumptions cover regulatory guidance stability, polymer feedstock availability, and CDMO facility buildout continuity, with deviation risk concentrated in FDA closed-system processing guidance revisions and EVA resin supply allocation disruptions. Recalibration cycles align with material shifts in biologics pipeline composition and sterility validation protocol evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Sperm Processing Media Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Woven Medical Tape Market
Medical Supplies
Global Automated Blood Tube Labeler and Specimen Transport Box Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Custom Procedure Packs (CPT) Market
Medical Supplies
Disposable Medical Gloves Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Evacuated Drainage Bottles Market