
 Dental Emergency Kit Market | 2026-2036
Dental Emergency Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Emergency Kit Market Analysis
Dental supply store networks is reconfiguring how emergency kits reach end users, with regional distributors consolidating shelf space for higher-margin trauma management assortments. Oscar Boscarol leverages its European manufacturing footprint to sustain consistent supply to pharmacy chains across Italy and Spain. Paramed International anchors its position through specialized trauma management modules designed for hospital emergency departments. COOK Medical competes by extending its clinical device expertise into sterile emergency dental tools for post-operative care settings.
A dental emergency kit comprises sterile instruments, temporary filling materials, analgesic compounds, and hemostatic agents packaged for immediate intervention in acute oral trauma, avulsion, or post-extraction complications. Most kits incorporate dental dams, temporary cement syringes, and irrigation solutions formulated for pH-balanced wound cleansing in non-clinical environments. Toothache relief kits occupy the largest volume share due to recurring consumer demand for over-the-counter pain management solutions. Emergency dental tools represent the fastest-expanding category as mobile dentists and sports medicine programs prioritize portable, sterilized instrument sets for field deployment. First aid kits generate stable margins through institutional procurement contracts with hospitals and dental clinics.
FDA device classification rules and CE marking under the EU MDR govern sterile instrument standards, while ISO 13485 quality management systems shape manufacturer compliance burdens for kit assemblers. The EPA regulates disinfectant components in certain kit formulations, particularly those containing chlorhexidine or hydrogen peroxide solutions. Stakeholders must monitor evolving harmonization between FDA and EU MDR requirements to avoid duplicative testing costs that could compress margins on multi-market product lines.
Market Dynamics
Home care adoption is compressing traditional clinic-first pathways, with consumers now demanding immediate pain relief capabilities before professional intervention. This shift forces manufacturers to redesign kit configurations for non-clinical environments while maintaining sterile integrity.
Growth Catalysts
- Aging Demographics:Japan, Germany, and the United States exhibit expanding elderly populations requiring accessible emergency dental intervention. Kit manufacturers prioritize simplified instrument designs for arthritic users.
- FDA Device Classification Rules:Tightened sterile instrument standards elevate barriers for low-quality competitors. Compliant assemblers capture shelf space previously occupied by unregulated imports.
- Sports Medicine Integration:Athletic programs and mobile dentistry units deploy portable sterilized instrument sets for field trauma management. Emergency dental tools gain traction in sideline medical protocols.
Market Restraints
- Chlorhexidine Supply Volatility:EPA-regulated disinfectant components face input cost fluctuations and sourcing constraints. Formulators absorb margin pressure or reformulate with hydrogen peroxide alternatives.
- EU MDR Compliance Burden:CE marking under tightened medical device regulations imposes duplicative testing costs. Small kit assemblers exit multi-market product lines rather than absorb certification expenses.
- Professional Substitution:Tele-dentistry platforms redirect acute cases toward virtual consultation rather than self-treatment. Emergency kit purchases compress where digital triage penetrates.
Strategic Opportunities
- Rural Underpenetration:Remote United States counties and Australian outback regions lack proximity to emergency dental services. Distributors develop compact, temperature-stable kit variants for extended shelf life in harsh climates.
- ISO 13485 Certification Tailwind:Quality management system credentials unlock institutional procurement contracts with hospital networks. Certified assemblers displace uncertified competitors in emergency department supply chains.
- Pharmacy Channel Expansion:Retail pharmacy chains consolidate emergency health product assortments. Kit manufacturers secure end-cap placement adjacent to analgesic and wound care categories.
Industry Challenges
- Sterile Packaging Engineering Talent:Barrier material science expertise for maintaining instrument sterility across variable storage conditions remains scarce. Manufacturers compete for polymer engineers with medical device backgrounds.
- ISO Harmonization Timelines:Divergent testing protocols between FDA and EU MDR create certification bottlenecks. Product launches stall awaiting dual jurisdiction approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Emergency Kit Market |
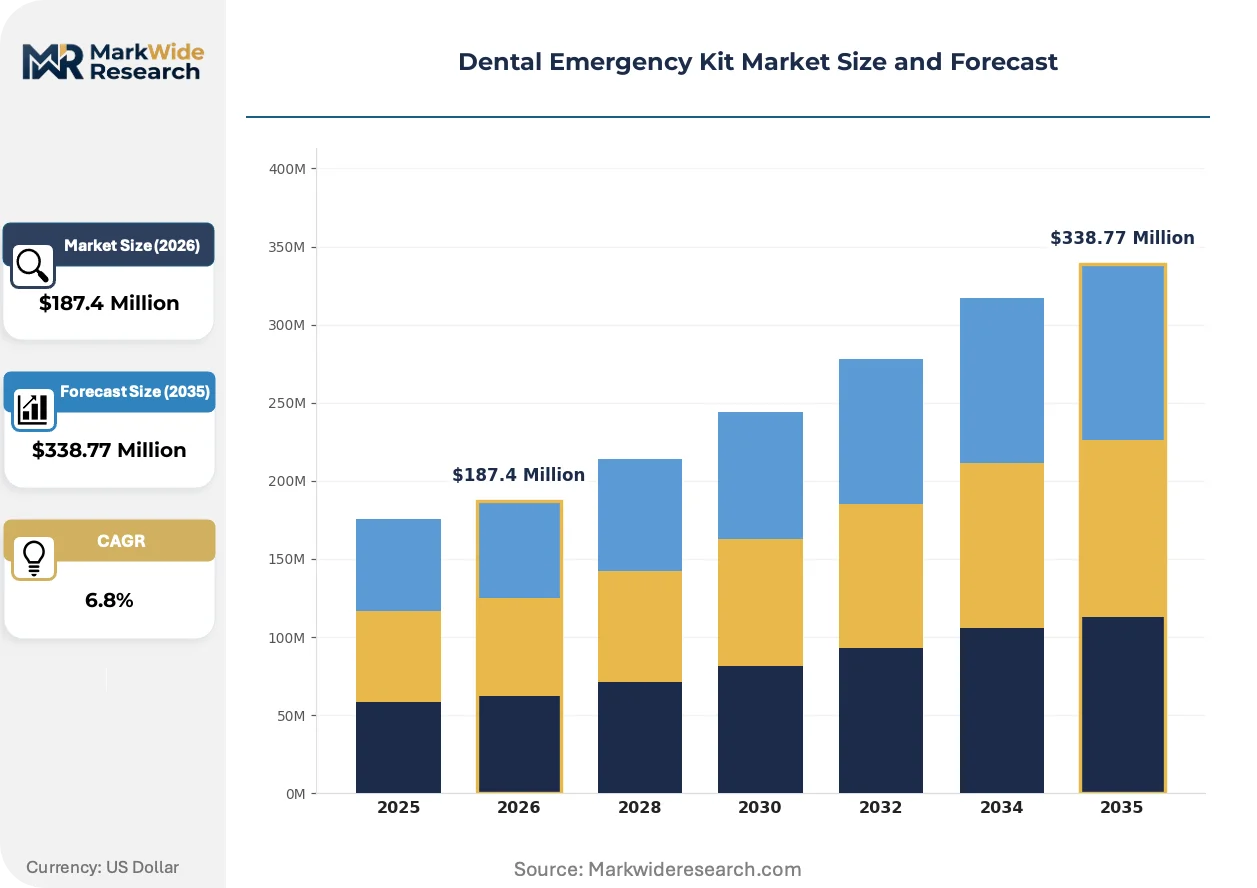
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: First Aid Kits, Toothache Relief Kits, Tooth Repair Kits, Emergency Dental Tools End User: Hospitals, Dental Clinics, Home Care, Mobile Dentists Application: Trauma Management, Post-Operative Care, Pain Relief, Oral Hygiene Distribution Channel: Online Retail, Pharmacies, Dental Supply Stores, Direct Sales |
| Companies Covered | Oscar Boscarol, Paramed International, Simulaids, Taumediplast, PVS, COOK Medical, Cardiva Integral Solutions, AKLA, Blume, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Emergency Kit Market Emerging Trajectories
Kit configuration is migrating toward modular, indication-specific designs that replace generic all-purpose assortments. Manufacturers now optimize component selection for distinct trauma scenarios rather than maximum instrument variety.
Single-use sterile instrument packs is migrating from hospital emergency departments toward home care and sports medicine applications. Athletic trainers and mobile dentists adopt pre-sterilized, disposable tool sets to eliminate field autoclave dependencies. This migration from reusable to disposable architectures compresses capital requirements for remote deployment while expanding addressable user bases.
EU MDR implementation is reshaping technical documentation requirements for kit assemblers marketing across European Economic Area member states. Manufacturers must maintain updated clinical evaluation reports and post-market surveillance systems. Smaller Italian and Spanish distributors consolidate supplier relationships to reduce compliance fragmentation.
Institutional buyers now unbundle after-sales training from product procurement, contracting specialized dental educators separately from kit vendors. Hospital systems in Germany and Japan negotiate pure product pricing while sourcing competency certification through independent channels. This separation of goods and services compresses vendor margins while elevating purchaser flexibility.
Dental Emergency Kit Market Segmentation
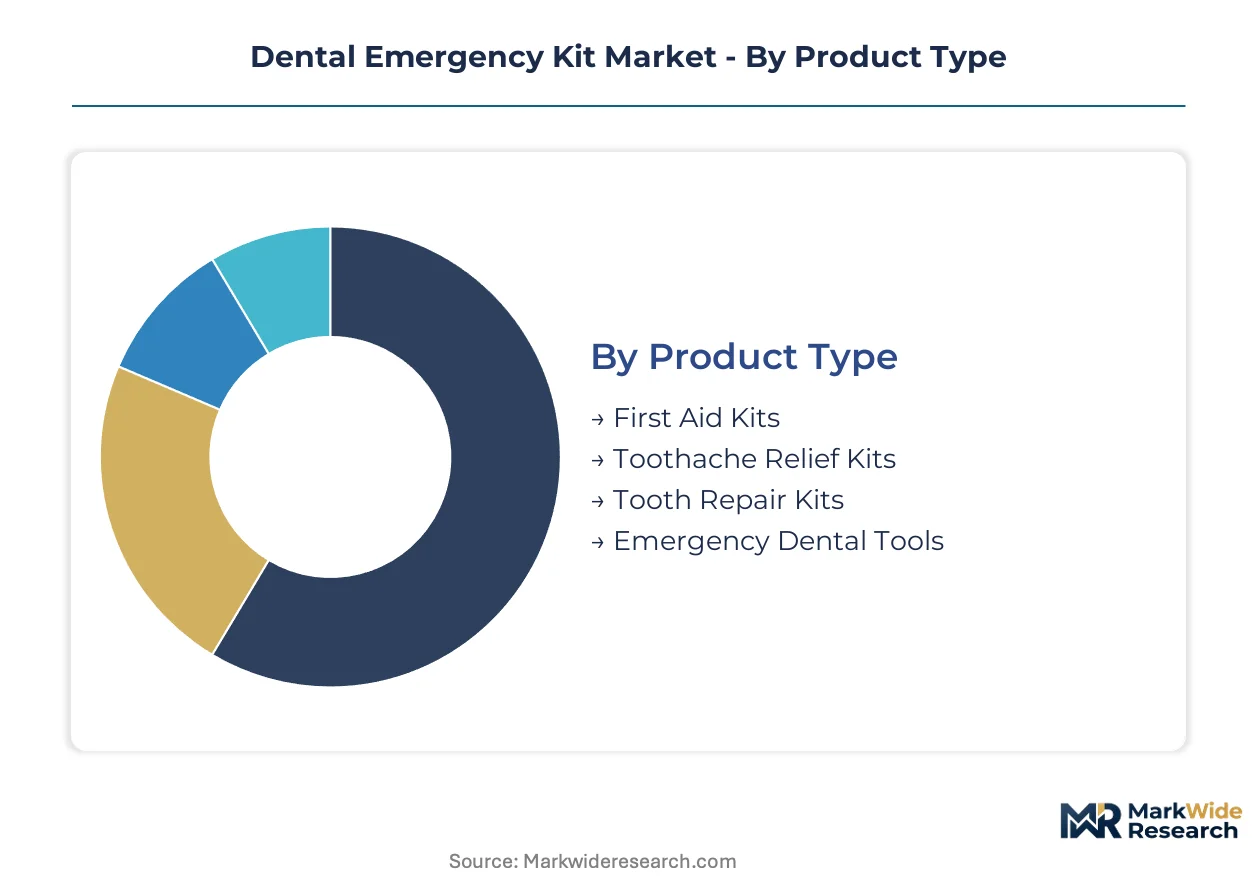
Segmentation in dental emergency kits reveals distinct velocity profiles across product categories, with consumable components cycling faster than capital equipment. Understanding these turnover patterns enables manufacturers to calibrate inventory strategies and distribution investments against actual replacement demand rather than initial purchase cycles.
Product Type:
Replacement cycles vary dramatically across this category, with single-use consumables turning over in weeks while instrument sets persist for years.
- Toothache Relief Kits:These over-the-counter assortments contain analgesic compounds, temporary filling materials, and pH-balanced irrigation solutions formulated for consumer self-administration. Demand concentrates in United States pharmacy chains and German drugstore networks where aging populations seek immediate pain intervention before professional appointments. Recurring purchase patterns drive volume leadership in this segment.
- Emergency Dental Tools:Portable sterilized instrument sets—including dental dams, temporary cement syringes, and hemostatic applicators—serve mobile dentists and sports medicine programs requiring field-deployable trauma capability. Athletic trainers in Japan and sideline medical staff across United States collegiate programs prioritize pre-sterilized disposable architectures that eliminate autoclave dependencies.
- Tooth Repair Kits:Temporary crown adhesives and composite patching materials target consumers managing fractured restorations between dental visits. These kits emphasize shelf-stable chemistry and simplified application instructions for non-clinical users.
- First Aid Kits:Comprehensive trauma assortments combine instruments, medications, and wound management supplies for institutional procurement by hospital emergency departments and dental clinics. ISO 13485 certification unlocks supply chain access for these higher-value configurations.
Toothache Relief Kits dominate installed base through sheer transaction volume. Emergency Dental Tools represent where expansion concentrates as mobile care models proliferate.
End User:
Customer type determines regulatory burden and pricing architecture, with institutional buyers demanding certification documentation that consumer channels ignore.
- Home Care:Individual consumers purchasing through retail pharmacy and online channels prioritize compact packaging, clear instructions, and immediate accessibility over clinical precision. FDA device classification compliance remains minimal at this tier, lowering barriers to entry for private-label assemblers.
- Hospitals:Emergency departments require sterile instrument documentation, lot traceability, and post-market surveillance systems under EU MDR and FDA Quality System Regulation. These procurement contracts reward ISO 13485-certified manufacturers with multi-year supply agreements.
- Dental Clinics:Practice-based stockpiling focuses on post-operative complication management and same-day trauma intervention. Clinicians favor modular kit configurations that unbundle components by indication rather than all-purpose assortments.
- Mobile Dentists:Field practitioners deploy portable sterilized sets for nursing home visits, rural outreach, and athletic event coverage. Weight reduction and temperature stability across variable storage conditions drive product selection.
Hospitals anchor premium pricing through compliance-heavy procurement. Home Care is where volume expansion accelerates as self-treatment adoption climbs.
Application:
Use-case specificity is reshaping kit design, with manufacturers abandoning generic configurations for indication-optimized component selection.
- Trauma Management:Avulsion protocols, alveolar fracture stabilization, and acute hemorrhage control demand hemostatic agents, irrigation solutions, and temporary splinting materials. Sports medicine programs and mobile dentistry units drive fastest uptake as field trauma capabilities expand.
- Pain Relief:Analgesic compounds and topical anesthetics target the largest addressable user base—consumers experiencing dental pain without immediate access to professional care. Pharmacy channel placement adjacent to ibuprofen and acetaminophen categories maximizes impulse purchase conversion.
- Post-Operative Care:Extraction site management, dry socket prevention, and suture care materials serve dental clinics and hospital discharge protocols. Chlorhexidine-based formulations face EPA regulatory scrutiny that pressures reformulation toward hydrogen peroxide alternatives.
- Oral Hygiene:Prophylactic maintenance supplies including antimicrobial rinses and interdental cleaning tools occupy preventive rather than emergency positioning. This application commands lower per-unit pricing but generates recurring revenue through replacement consumption.
Pain Relief captures the broadest user footprint. Trauma Management is climbing the fastest as athletic and field deployment protocols formalize.
Distribution Channel:
Channel selection determines margin structure and customer education burden, with direct sales capturing value that retail intermediaries dissipate.
- Pharmacies:Retail drugstore chains consolidate emergency health assortments into dedicated end-cap displays. Italian and Spanish pharmacy networks favor European-manufactured kits with CE marking documentation prominently displayed.
- Online Retail:E-commerce platforms enable direct-to-consumer distribution of toothache relief and basic repair kits, bypassing wholesale markups. Search visibility and review aggregation determine competitive positioning in this channel.
- Dental Supply Stores:Professional-focused distributors serve clinics and hospitals with technical support, training materials, and volume pricing structures. Regional consolidation is compressing supplier counts as larger distributors demand exclusive relationships.
- Direct Sales:Manufacturer-to-institution contracts for hospital networks and dental service organizations eliminate intermediary margins. These arrangements require dedicated account management and clinical education capabilities.
Pharmacies maintain the deepest consumer penetration. Online Retail is where growth investment concentrates as digital purchasing habits solidify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device classification rules anchor the United States market, where sterile instrument standards shape competitive entry barriers and procurement patterns across hospital networks and retail pharmacy chains.
United States
Aging demographics and high dental awareness drive kit purchases through CVS and Walgreens pharmacy networks. FDA Quality System Regulation governs sterile instrument documentation for hospital emergency departments. The Boston medical device cluster concentrates manufacturers serving institutional buyers with ISO 13485-certified configurations.
Germany
EU MDR compliance requirements elevate technical documentation burdens for kit assemblers targeting hospital procurement. CE marking under tightened medical device regulations imposes post-market surveillance obligations. The Baden-Württemberg industrial belt hosts distributors consolidating supplier relationships to reduce certification fragmentation.
Japan
Mobile dentistry expansion and sports medicine protocol formalization accelerate demand for portable sterilized instrument sets. METI standards influence quality management expectations for domestic manufacturers. The Osaka-Kobe manufacturing corridor supplies pharmacy chains with compact kits designed for arthritic elderly users.
Italy
Pharmacy channel consolidation favors European-manufactured kits with prominent CE marking documentation. Oscar Boscarol leverages domestic production capacity to sustain consistent supply across Italian and Spanish retail networks. The Emilia-Romagna medical supply cluster specializes in modular trauma management configurations.
Australia
Rural underpenetration creates demand for temperature-stable kit variants with extended shelf life in harsh outback climates. The Therapeutic Goods Administration regulates sterile instrument standards for hospital procurement. Sydney-based distributors develop compact emergency dental tools for remote nursing home outreach programs.
Dental Emergency Kit Market Vendor Landscape
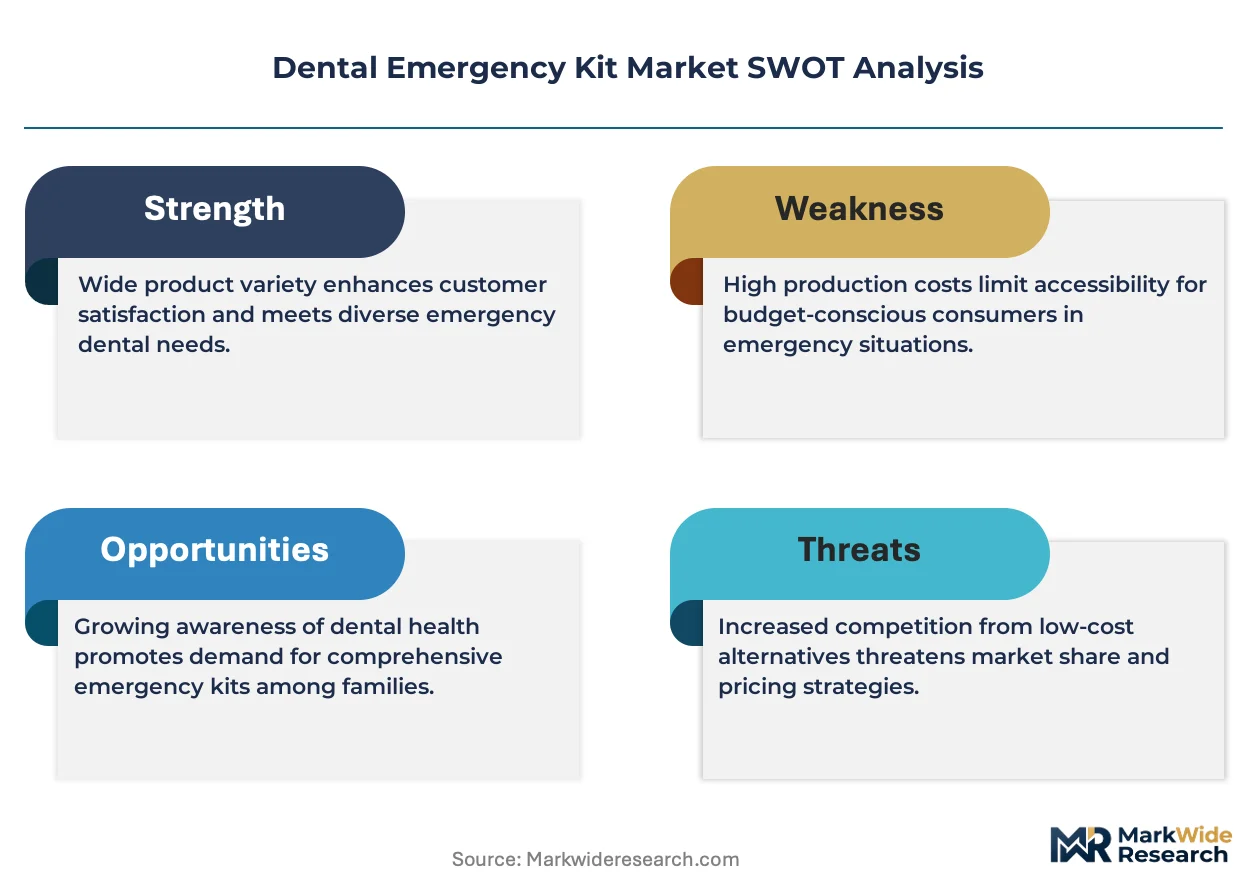
European manufacturers and North American clinical device specialists split the market between pharmacy retail penetration and institutional certification depth. The vendor base concentrates around mid-scale assemblers with regional manufacturing footprints rather than global conglomerates. Three archetypes dominate: CE-marked European distributors serving pharmacy chains, ISO 13485-certified suppliers capturing hospital contracts, and trauma management specialists targeting sports medicine deployment. Competitive moves center on EU MDR compliance investment and modular kit configuration diversification to replace generic all-purpose assortments.
Among European-based fabricators, Oscar Boscarol and Paramed International occupy distinct positioning archetypes. Oscar Boscarol exemplifies the pharmacy-channel specialist leveraging manufacturing proximity to Italian and Spanish retail networks. Paramed International represents the trauma management module developer designing for hospital emergency department specifications. COOK Medical anchors the clinical device extension strategy, translating sterile instrument expertise into post-operative care settings. These three illustrate how geographic origin and customer-type focus shape competitive differentiation more than scale or vertical integration depth.
| Leading Market Players |
|---|
| Oscar Boscarol |
| Paramed International |
| Simulaids |
| Taumediplast |
| PVS |
| COOK Medical |
| Cardiva Integral Solutions |
| AKLA |
| Blume |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Italian sterile instrument fabrication compresses supplier margins while simultaneously elevating pricing power for ISO 13485-certified assemblers who can document EU MDR compliance. This utilization asymmetry rewards certified manufacturers with hospital procurement access while forcing uncertified competitors toward pharmacy-channel discounting or exit.
Pricing Analysis
Price spreads between United States hospital contracts and European pharmacy retail exceed threefold for equivalent kit configurations. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified hospital supply from CE-marked pharmacy retail and unbranded online private-label. Price differentiation rests on certification grade and after-sales training bundling. Cost compression in economy tiers intensifies because chlorhexidine supply volatility forces reformulation investments. Home care consumers exhibit highest price sensitivity while hospital purchasing committees prioritize compliance documentation over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among Baden-Württemberg precision instrument fabricators and Emilia-Romagna polymer packaging specialists serving kit assemblers. Geographic supply concentration centers on Germany, Italy, and Japan for sterile instruments, barrier films, and hemostatic agents respectively. Raw material dependencies draw from chlorhexidine compounders, medical-grade polymer resin suppliers, and pH-balanced irrigation solution formulators. Single-source vulnerability in chlorhexidine active pharmaceutical ingredient creates procurement risk for antiseptic-dependent kit configurations. Distribution runs through regional dental supply distributors consolidating toward exclusive supplier relationships with hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier material science expertise for sterile packaging engineering remains scarce relative to kit assembler demand, constraining product development velocity and elevating compensation costs for qualified polymer engineers.
For Market Incumbents: Build regulatory certification moats through dual FDA-EU MDR compliance investment to displace fragmented small assemblers unable to absorb duplicative testing costs. Deepen backward integration into medical-grade polymer resin sourcing to secure barrier film supply against chlorhexidine reformulation cycles. Anchor capacity expansion in Osaka-Kobe corridor to capture Japanese mobile dentistry procurement growth. For New Entrants and Emerging Players: Australian outback rural underpenetration offers accessible white-space with minimal incumbent presence and forgiving regulatory entry barriers through TGA self-certification pathways. Compact temperature-stable kit variants for extended shelf life in harsh climates represent the most penetrable product configuration. Pursue direct-to-nursing-home distribution partnerships bypassing consolidated pharmacy channel gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale ISO 13485-certified assemblers with existing hospital network contracts and underutilized European manufacturing footprints. Long-term viability favors operators who can amortize compliance costs across multi-market product lines rather than single-jurisdiction specialists. Watch for chlorhexidine supply contract renegotiations as inflection signal for margin compression or reformulation-driven competitive displacement.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | CE marking documentation unlocks hospital procurement across German and Italian networks. |
| Backward Integration into Barrier Films | In-house polymer packaging production secures sterile integrity against supplier concentration. |
| Pharmacy Channel End-Cap Placement | CVS and Walgreens positioning adjacent to analgesics drives impulse purchase conversion. |
| Modular Kit Configuration Development | Indication-specific designs replace generic assortments for trauma management specialization. |
| ISO 13485 Certification Pathway | Quality management credentials displace uncertified competitors in emergency department supply chains. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with dental supply procurement managers, hospital biomedical engineers, sterile packaging polymer engineers, and pharmacy chain category buyers; and secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital GPO contract repositories, and customs trade records for medical device imports. Bottom-up kit shipment estimates triangulated against top-down demographic demand modeling for aging population dental emergency incidence.
Forecast inputs considered product type segmentation across toothache relief kits, emergency dental tools, and first aid configurations; end-user channels spanning home care, hospitals, dental clinics, and mobile dentists; and application-specific demand trajectories for trauma management and pain relief. CAGRs were derived from installed base turnover rates and replacement cycle compression observed across the projection horizon. Industry-specific inputs incorporated tele-dentistry platform penetration rates and sports medicine protocol formalization timelines.
Practitioners should monitor EU MDR implementation enforcement consistency and chlorhexidine supply contract renegotiation patterns for early signals of competitive repositioning. Forecasts reflect documented assumptions regarding sterile instrument standard harmonization timelines and mobile dentistry reimbursement policy evolution. Quarterly review of hospital procurement database award notifications and pharmacy chain SKU rationalization announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Japan Organ Preservation Market
Medical Supplies
Disposable Masks Market
Medical Supplies
India Disposable Latex Gloves Market
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
GCC Syringes and Needles Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Tracheostomy Securement Tapes Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Single-Use Sterilization Wraps Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Asia-Pacific Insulin Syringe Market
Medical Supplies
Italy Ostomy Care and Accessories Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Smart Face Masks Market