
 Hysterectomy Devices Market | 2026-2036
Hysterectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Hysterectomy Devices Market Analysis
Robot-assisted surgical integration is reconfiguring how hysterectomy platforms combine imaging, instrumentation, and digital feedback loops into unified operating room ecosystems. Medtronic leverages its spine-to-surgery robotics heritage to extend hardware architectures into gynecological applications. Johnson & Johnson anchors its competitive position through its Ethicon energy device portfolio and stapling systems that pair with third-party robotic arms. KARL STORZ SE specializes in rigid endoscopy and integrated visualization, sustaining dominance in laparoscopic hysterectomy towers across European and Asian hospital networks.
Hysterectomy devices comprise specialized mechanical, electrosurgical, and robotic instrumentation designed for uterine removal via abdominal, vaginal, or laparoscopic access routes, typically incorporating bipolar energy delivery, tissue morcellation containment, and articulating stapler mechanisms to achieve hemostasis and specimen extraction. The primary commercial purpose centers on enabling safe, reproducible uterine removal while minimizing perioperative complications and recovery intervals across benign and oncological indications. Robotic device types command premium positioning due to capital intensity and recurring instrument revenue, while laparoscopic platforms represent the highest procedure volume and most mature replacement cycle. Stainless steel and titanium materials dominate reusable instrument construction, though polymer single-use components are gaining share in containment and retrieval applications where cross-contamination protocols have tightened.
FDA 510(k) clearance pathways and subsequent FDA guidance on power morcellation containment shape product development timelines and labeling requirements for US market entry, while the EU MDR transition forces European manufacturers to renew technical documentation and clinical evidence for legacy hysterectomy device portfolios. ISO 13485 quality management certification and IEC 60601 electrical safety standards form baseline predicates for regulatory access across OECD markets. Stakeholders must monitor how CMS reimbursement adjustments for outpatient hysterectomy site-of-service differentials reshape capital purchase decisions by hospital procurement committees.
Market Dynamics
Minimally invasive surgical platforms are compressing traditional open hysterectomy volumes while forcing capital equipment refresh cycles across hospital systems. Ambulatory surgical centers now drive procedure migration away from inpatient settings, rewiring procurement priorities toward compact, multi-specialty robotic systems.
Growth Catalysts
- Outpatient site-of-service expansion:CMS reimbursement differentials for ambulatory hysterectomy procedures are accelerating capital deployment into freestanding surgical centers across the United States.
- Power morcellation containment standards:FDA guidance on sealed tissue extraction systems has created compliance-driven replacement demand for legacy laparoscopic instrumentation.
- Bipolar vessel sealing advancement:Electrosurgical platforms incorporating real-time tissue impedance feedback are reducing conversion rates to open procedures in obese patient populations.
Market Restraints
- Titanium alloy supply concentration:Surgical instrument forging capacity clusters in Germany and Switzerland, exposing manufacturers to energy cost volatility and export license delays.
- Capital intensity barriers:Robotic surgical systems require $1.5-2.5 million upfront investment plus annual service contracts, limiting penetration to health systems with procedure volumes exceeding 200 hysterectomies annually.
- Substitution from uterine-sparing interventions:MRI-guided focused ultrasound and endometrial ablation systems are capturing fibroid treatment cases previously routed to hysterectomy.
Strategic Opportunities
- India outpatient infrastructure buildout:Corporate hospital chains in Mumbai and Delhi are installing laparoscopic towers in day-surgery units to capture gynecology cases from public sector waiting lists.
- EU MDR clinical evidence gap:Legacy hysterectomy device portfolios lacking prospective data create opening for new entrants with robust PMCF studies to displace incumbent positions.
- 5G telesurgery integration:Low-latency connectivity is enabling hub-and-spoke robotic hysterectomy networks connecting tertiary centers to community hospitals lacking on-site surgical expertise.
Industry Challenges
- Robotic console operator certification bottlenecks:Gynecologic surgeons require 20-50 supervised cases for privileges, constraining system utilization rates and amortization schedules.
- Single-use instrument cost compression:Containment bags and vessel sealers priced per procedure are triggering value-analysis committee scrutiny amid inpatient margin pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hysterectomy Devices Market |
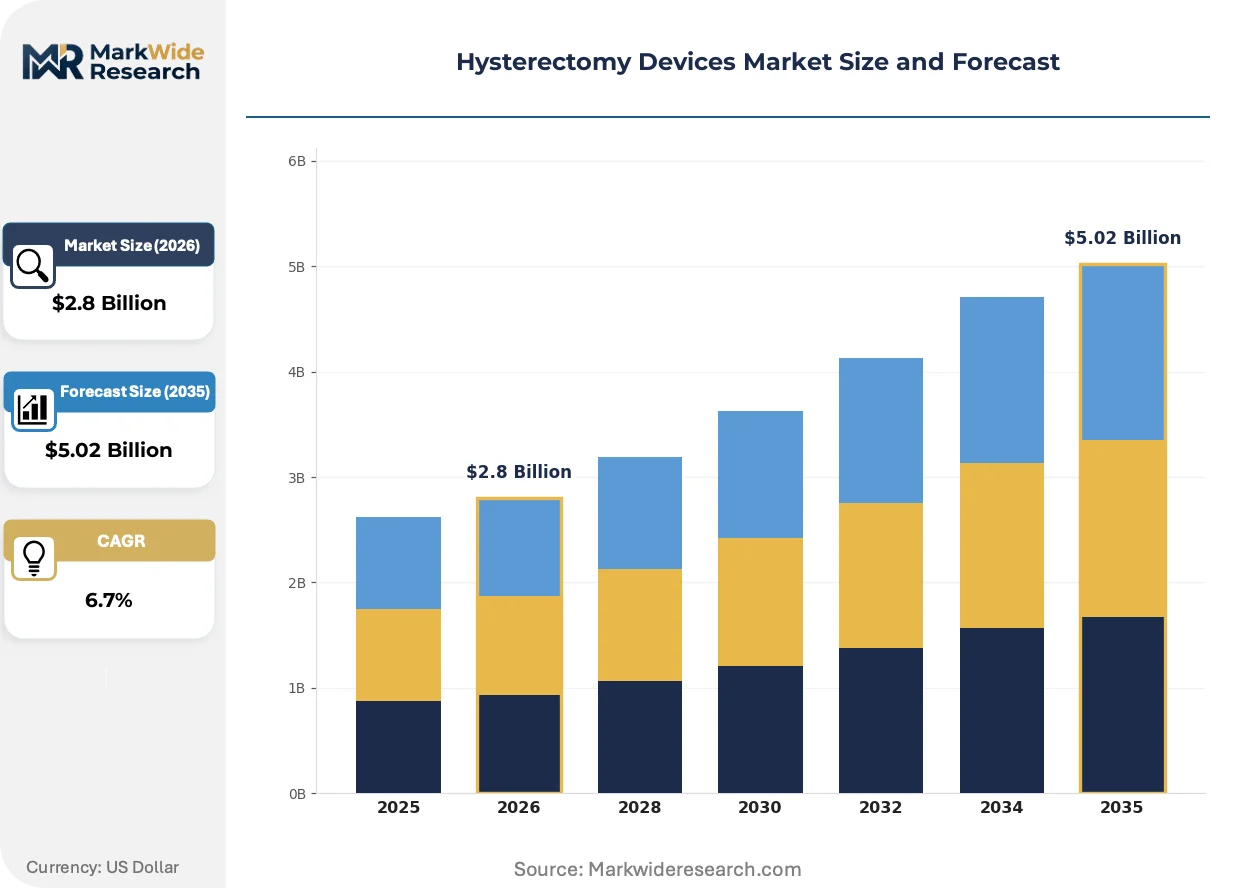
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laparoscopic, Robotic, Abdominal, Vaginal End User: Hospitals, Clinics, Ambulatory Surgical Centers, Medical Research Institutes Procedure Type: Open Hysterectomy, Total Laparoscopic Hysterectomy, Radical Hysterectomy, Subtotal Hysterectomy Material: Stainless Steel, Polymer, Carbon Fiber, Titanium |
| Companies Covered | Medtronic, Johnson & Johnson, KARL STORZ SE, Cook Medical, Hologic, Cooper Surgical, Boston Scientific Corporation, FUJIFILM Corporation, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hysterectomy Devices Market Emerging Trajectories
Surgical visualization and energy delivery systems are converging into unified platforms that compress operative time and reduce training variance. Device architectures now prioritize modularity over monolithic design, enabling incremental upgrades without full system replacement.
Articulating stapler mechanisms with integrated near-infrared fluorescence imaging are collapsing the distinction between mechanical and energy-based hemostasis in laparoscopic hysterectomy. Academic medical centers in Boston and Stanford are piloting these hybrid platforms for complex oncologic cases. The convergence is compressing instrument counts per procedure while forcing manufacturers to master dual competency in stapling and energy modalities.
The EU MDR transition is forcing hysterectomy device manufacturers to regenerate technical documentation for legacy portfolios, with notified body capacity constraints extending clearance timelines. European hospitals are delaying procurement decisions pending renewed CE marking validity. German and French health technology assessment bodies are now requiring procedure-specific clinical evidence rather than predicate equivalence for novel energy devices.
Hospital procurement committees are consolidating vendor relationships through integrated operating room contracts that bundle hysterectomy devices with anesthesia and imaging systems. United States integrated delivery networks in Texas and Florida are piloting total cost-of-procedure agreements that shift risk to device suppliers. This model is displacing traditional capital purchase cycles with per-procedure leasing structures that align supplier revenue to clinical throughput.
Hysterectomy Devices Market Segmentation
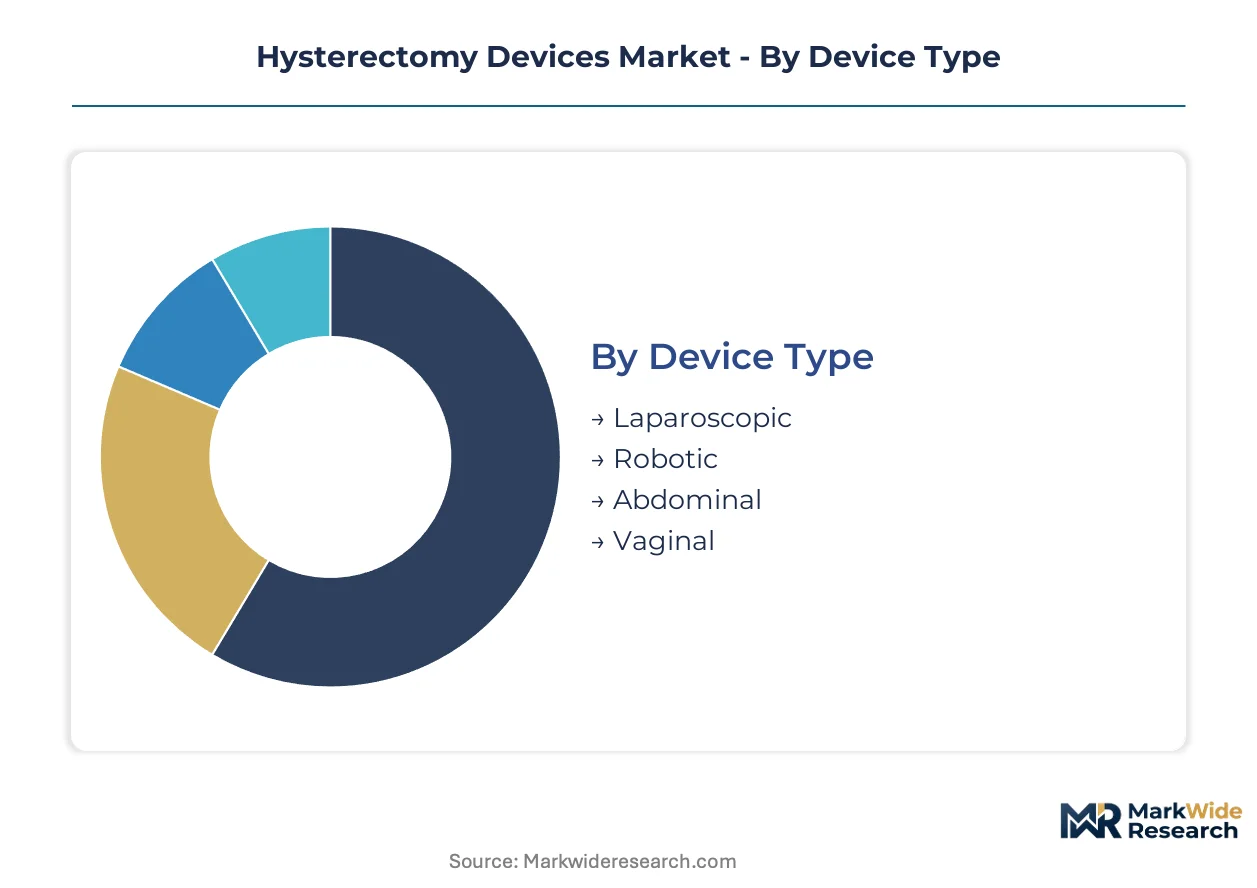
Hysterectomy device segmentation reveals divergent capital intensity and clinical workflows across access routes and care settings. Procurement committees weight replacement cycles against procedure volume economics when allocating budgets across these categories.
Device Type:
Mature laparoscopic platforms coexist with emerging robotic architectures as health systems balance capital deployment against utilization targets.
- Laparoscopic:Rigid endoscopic towers with bipolar energy delivery and manual articulation dominate procedure volume across integrated delivery networks. United States hospital systems in Texas and Florida prioritize these systems for their established service contracts and surgeon familiarity.
- Robotic:Integrated surgical platforms combining haptic feedback, 3D visualization, and wristed instrumentation command premium positioning. Ambulatory surgical centers in California and New York are piloting compact multi-specialty configurations to capture outpatient migration.
- Abdominal:Open retractor systems and handheld instrumentation retain utility in oncologic cases requiring extensive lymphadenectomy.
- Vaginal:Specialized speculums, retractors, and morcellation containment bags serve same-day discharge protocols in European day-surgery units.
Laparoscopic systems handle the majority of throughput; robotic platforms are gaining share fastest as outpatient site-of-service expansion accelerates.
End User:
Customer type determines capital intensity tolerance and procurement committee composition across the care continuum.
- Hospitals:Academic medical centers and community hospitals with gynecologic surgery departments anchor capital equipment demand. These institutions negotiate integrated operating room contracts bundling hysterectomy devices with anesthesia and imaging systems.
- Ambulatory Surgical Centers:Freestanding facilities drive the steepest expansion trajectory as CMS reimbursement differentials reward outpatient procedure migration. Corporate chains in Texas and Florida are consolidating vendor relationships through total cost-of-procedure agreements.
- Clinics:Office-based hysteroscopy and diagnostic platforms serve preoperative workup and postoperative surveillance.
- Medical Research Institutes:Academic consortia in Boston and Stanford pilot next-generation visualization and energy delivery systems before commercial scale-up.
Hospitals retain the dominant installed base; ambulatory surgical centers are climbing the fastest on procedure volume share.
Procedure Type:
Clinical indication severity shapes instrument selection and containment requirements across the surgical spectrum.
- Total Laparoscopic Hysterectomy:Complete uterine removal via laparoscopic access with sealed tissue extraction systems. United States health systems are replacing legacy power morcellation devices with FDA-compliant containment platforms to meet updated guidance.
- Radical Hysterectomy:Extended oncologic resection incorporating parametrial tissue and lymph node dissection. Tertiary centers in Germany and France require integrated near-infrared fluorescence imaging for sentinel node mapping.
- Open Hysterectomy:Abdominal access for massive fibroid burden or suspected malignancy with adhesions.
- Subtotal Hysterectomy:Cervix-sparing approaches preserving pelvic floor support in younger patient populations.
Total laparoscopic hysterectomy commands the highest procedure count; radical hysterectomy shows the steepest technology premium per case.
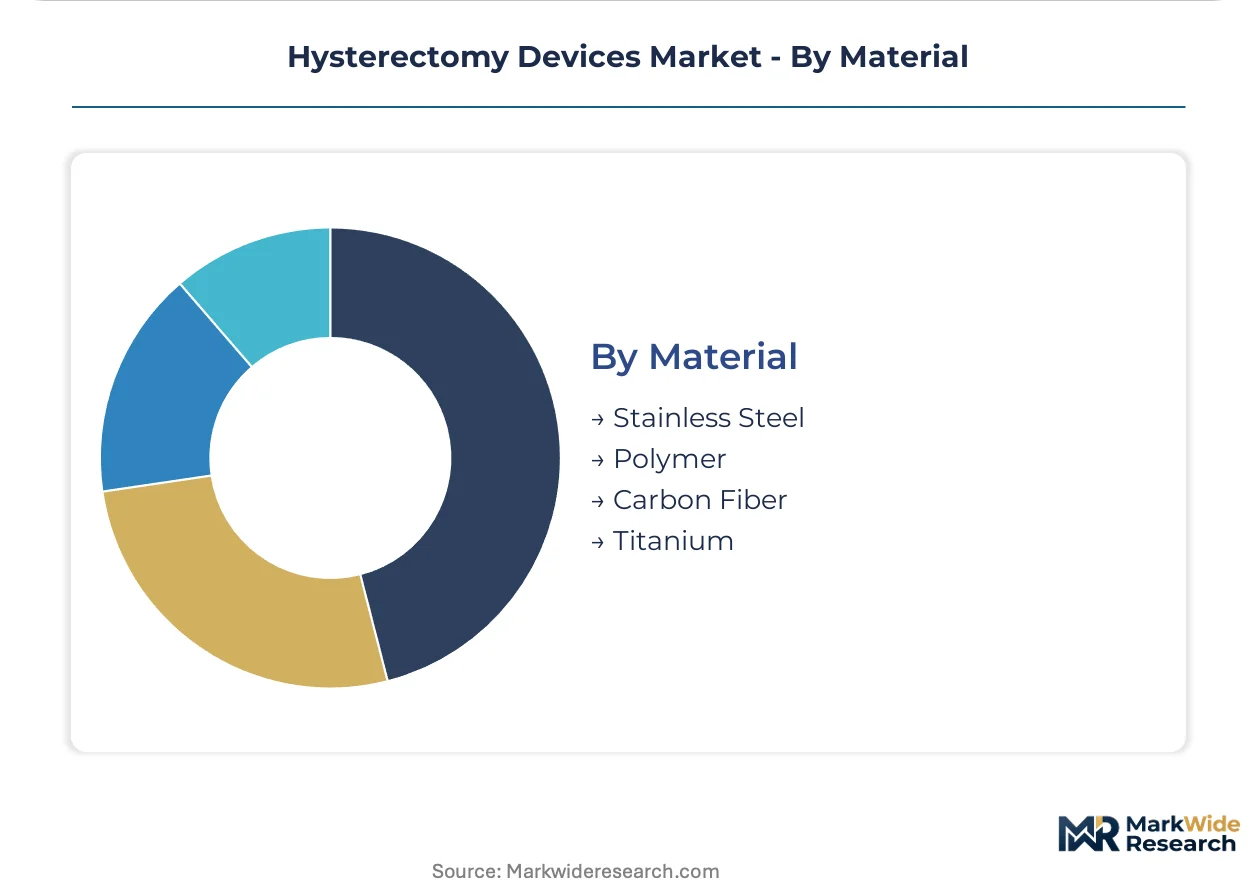
Material:
Supply concentration in European forging centers shapes cost structures and availability timelines for metallic instrumentation.
- Stainless Steel:Austenitic grades dominate reusable forceps, scissors, and retractor construction. German and Swiss forging capacity clusters expose manufacturers to energy cost volatility and export license delays.
- Titanium:Biocompatible alloys enable lightweight articulating instruments with superior fatigue resistance. Premium robotic instrument arms incorporate these materials for repetitive motion durability.
- Polymer:Single-use containment bags and specimen retrieval pouches address cross-contamination protocols. These components are gaining share where sterilization validation costs exceed disposables pricing.
- Carbon Fiber:Reinforced composites serve specialized laparoscopic shafts requiring electrical insulation and radiolucency.
Stainless steel retains the dominant share of instrument mass; polymer components are expanding most quickly in containment applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German surgical instrument manufacturers export titanium-forged hysterectomy instrumentation to United States health systems, establishing the primary transatlantic trade corridor for premium reusable devices.
United States
Integrated delivery networks in Texas and Florida consolidate gynecological service lines through bundled operating room contracts. FDA power morcellation containment guidance drives replacement demand for sealed tissue extraction systems. Ambulatory surgical centers in California deploy compact robotic platforms to capture CMS-reimbursed outpatient procedures.
Germany
Titanium alloy forging clusters in Solingen and Tuttlingen supply precision instruments to European and Asian hospital networks. EU MDR technical documentation requirements extend clearance timelines for legacy laparoscopic portfolios. Academic medical centers in Berlin pilot near-infrared fluorescence imaging for oncologic hysterectomy cases.
India
Corporate hospital chains in Mumbai and Delhi install laparoscopic towers in day-surgery units to absorb public sector waiting list volumes. CDSCO device registration pathways prioritize quality management system certification for imported energy platforms. Tamil Nadu's medical device manufacturing zone attracts contract forging partnerships for stainless steel instrumentation.
Japan
Metropolitan Tokyo hospitals integrate robotic hysterectomy platforms into hub-and-spoke referral networks. PMDA streamlined review pathways for predicate-equivalent laparoscopic devices accelerate market entry for European manufacturers. Osaka-based surgical societies establish training protocols for minimally invasive gynecologic certification.
United Kingdom
NHS integrated care systems negotiate total cost-of-procedure agreements shifting utilization risk to device suppliers. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR clinical evidence standards. London teaching hospitals concentrate radical hysterectomy volumes requiring advanced lymphadenectomy instrumentation.
Hysterectomy Devices Market Vendor Landscape
On the supply side, the industry is consolidating around integrated surgical platform ecosystems rather than standalone instrument vendors. Capital intensity barriers favor manufacturers with recurring revenue streams from disposable components. Two strategic archetypes dominate: diversified medtech conglomerates leveraging cross-specialty robotics heritage, and specialized endoscopy firms defending laparoscopic installed bases through visualization innovation. Competitive moves center on hub-and-spoke telesurgery network partnerships and per-procedure leasing structures that displace traditional capital purchase cycles.
Within the diversified systems tier, Medtronic and Johnson & Johnson occupy positions anchored by spine-to-surgery robotics extension and energy device portfolio breadth respectively. KARL STORZ SE exemplifies the specialized visualization archetype, sustaining European and Asian hospital network relationships through rigid endoscopy tower dominance. These three manufacturers represent the primary competitive anchors shaping procurement committee vendor consolidation patterns.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| KARL STORZ SE |
| Cook Medical |
| Hologic |
| Cooper Surgical |
| Boston Scientific Corporation |
| FUJIFILM Corporation |
| Stryker Corporation |
| Others |
Supply Flow & Price Mechanics
Titanium alloy supply concentration in German and Swiss forging centers exposes manufacturers to energy cost volatility and export license delays, compressing margins across premium robotic instrument tiers while forcing procurement committees toward polymer single-use alternatives in containment applications. This input dependency simultaneously widens price spreads between reusable metallic instrumentation and disposable polymer components while reshaping inventory strategies toward dual-source qualification.
Pricing Analysis
Current-generation robotic platforms command three to four times the per-procedure instrument cost of prior-generation laparoscopic towers, while next-generation telesurgery-enabled systems carry additional connectivity surcharges. Three-tier pricing structure across premium, standard, and economy levels separates integrated surgical platforms with haptic feedback from manual laparoscopic towers and basic vaginal instrumentation kits. Cost compression in single-use containment bags is intensifying because hospital value-analysis committees scrutinize per-procedure spend amid inpatient margin pressure. Ambulatory surgical centers exhibit the highest price sensitivity due to capital intensity barriers, whereas academic medical centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
EU dual-use export controls on advanced surgical robotics components limit cross-border flows of precision servo motors and force-feedback sensors to non-OECD markets. Manufacturing gravity centers on Germany for titanium forging, Switzerland for precision instrument finishing, and the United States for robotic system assembly. Supply chains draw from austenitic stainless steel feedstock, medical-grade titanium billet, and polymer resin for containment applications. Single-source vulnerability concentrates in Solingen forging capacity for articulating instrument shafts. Distribution runs through integrated delivery network procurement committees and ambulatory surgical center group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring instrument revenue streams from single-use vessel sealers and containment bags are expanding faster than capital equipment sales, converting hardware vendors into service-attach businesses with predictable annuity profiles.
For Market Incumbents: Pre-empt displacement by EU MDR-compliant entrants through accelerated clinical evidence generation for legacy laparoscopic portfolios. Lock in ambulatory surgical center chains with total cost-of-procedure agreements that shift utilization risk to your balance sheet. Backward integration into titanium forging capacity mitigates Solingen supply concentration exposure. For New Entrants and Emerging Players: Establish a beachhead in India's corporate hospital day-surgery infrastructure where CDSCO registration pathways favor quality-certified imported energy platforms. Capture replacement demand for FDA-compliant power morcellation containment systems in United States health systems migrating from legacy devices. Lead with per-procedure leasing structures that bypass capital committee approval cycles. For Investors and Strategic Acquirers: EU MDR clinical evidence requirements reshape the acquisition landscape toward targets with robust PMCF study portfolios rather than predicate-equivalent legacy devices. Five-to-ten year viability hinges on recurring revenue attachment rates exceeding hardware depreciation schedules. Monitor notified body clearance timeline extensions as the inflection signal for distressed incumbent asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation renewal unlocks legacy portfolio continuity across German and French hospital networks. |
| Hospital System Partnership | Integrated delivery network contracts in Texas and Florida bundle hysterectomy devices with anesthesia and imaging systems. |
| Software Companion Development | Real-time tissue impedance feedback algorithms differentiate bipolar vessel sealing platforms in obese patient populations. |
| Reimbursement Strategy | CMS outpatient site-of-service differentials accelerate capital deployment into ambulatory surgical centers. |
| FDA Submission | 510(k) clearance for sealed tissue extraction systems addresses updated power morcellation containment guidance. |
Methodological Framework
Operator-level perspectives from gynecologic surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body clearance registries. Bottom-up procedure volume estimates triangulated with top-down capital equipment shipment analysis.
Scenario-bracketing framed demand projections across the analysis window, modeling hysterectomy device segmentation by access route, care setting, procedure type, and material composition. CAGRs derived from weighted average of historical replacement cycles, regulatory-driven upgrade timelines, and site-of-service migration patterns. Forecast inputs incorporated CMS reimbursement differential trajectories and EU MDR clearance capacity constraints.
Sensitivities concentrate around FDA guidance revisions on robotic validation requirements and titanium alloy supply disruptions from German forging centers. Forecasts reflect documented assumptions on procedure volume migration and capital equipment refresh timing. Material shifts in EU MDR notified body capacity or CMS outpatient reimbursement rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Korea Massage Equipment Market
Medical Devices
China General Surgical Devices Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Knee Braces Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
United Kingdom Respiratory Devices Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Cytology Brush Market
Medical Devices
Photomedicine Technology Market
Medical Devices
Endodontic Devices Market