
 US Ostomy Care and Accessories Market | 2026-2036
US Ostomy Care and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
US Ostomy Care and Accessories Market Insights
Enterostomal therapy nursing shortages are bifurcating the market into self-managed patient segments and institution-dependent care models. Coloplast Corp leverages its direct-to-patient subscription platforms to sustain recurring revenue outside traditional hospital purchasing. Hollister Incorporated anchors its position through R&D intensity in hydrocolloid adhesive formulations. ConvaTec Group Plc competes on manufacturing scale, operating high-volume production lines serving national durable medical equipment distributors.
Ostomy care and accessories comprise medical devices including drainable and closed pouching systems, skin barriers, and adjunct supplies designed to collect waste from surgically created stomas; hydrocolloid-based wafer compositions typically measure 1.5 to 4 inches in flange diameter and adhere to peristomal skin for 3 to 7 day wear cycles. The primary commercial purpose centers on maintaining skin integrity, controlling odor, and enabling ambulatory patient autonomy across acute, rehabilitation, and home settings. Colostomy bags occupy the largest volume share within product type segmentation, reflecting the prevalence of colorectal cancer and diverticular disease interventions. Accessories represents the fastest-expanding category as patients seek belt systems, pouch covers, and deodorizing products that extend wear time and improve quality of life. Home healthcare dominates delivery mode distribution, though online retail channels are capturing incremental share through insurance-integrated fulfillment and discrete shipping protocols.
FDA medical device regulations govern 510(k) clearance pathways for ostomy appliances, while CMS national coverage determinations shape reimbursement rates that directly influence patient access and manufacturer pricing authority. State-level Medicaid expansion decisions in Texas, Florida, and Georgia create variable access landscapes where DME supplier network density determines product availability. Stakeholders must monitor how Medicare Advantage plan carve-outs for ostomy supplies alter competitive dynamics between national distributors and regional specialty pharmacies.
Market Dynamics
Post-acute care migration from institutional settings to home environments is restructuring procurement channels, with durable medical equipment suppliers and specialty pharmacies capturing volume previously routed through hospital central supply departments.
Growth Catalysts
- Medicaid Expansion in Southeast States:Texas, Florida, and Georgia are extending coverage eligibility, enlarging the addressable patient population for ostomy supplies and driving network expansion among regional DME distributors.
- Hydrocolloid Adhesive Innovation:Extended wear-time formulations are reducing pouch change frequency from daily to multi-day cycles, improving patient compliance and lowering total cost of care for payers.
- Medicare Advantage Carve-Outs:Plan-specific ostomy benefit designs are creating dedicated procurement pathways outside traditional fee-for-service reimbursement, enabling direct-to-patient fulfillment models.
Market Restraints
- Enterostomal Therapy Nursing Shortage:Specialized wound and stoma care training programs are producing insufficient graduates, constraining patient education capacity and slowing adoption of advanced pouching systems.
- Adhesive Raw Material Concentration:Medical-grade hydrocolloid resin supply concentrates among three specialty chemical manufacturers, exposing converters to input cost volatility and qualification delays.
- FDA 510(k) Pathway Friction:Updated device classification rules for skin barriers are extending premarket notification review timelines, compressing product launch windows and deferring revenue recognition.
Strategic Opportunities
- Online Retail Channel Integration:Insurance-integrated e-commerce platforms with discrete shipping protocols are capturing patient segments prioritizing privacy and convenience over traditional brick-and-mortar DME suppliers.
- Accessories Category Expansion:Belt systems, pouch covers, and deodorizing products represent underdeveloped margin pools, with patients demonstrating willingness to pay out-of-pocket for quality-of-life improvements.
- Remote Patient Monitoring Convergence:Sensor-enabled pouches transmitting wear-time and output data are enabling proactive intervention models, aligning with CMS value-based care incentives for home health agencies.
Industry Challenges
- Complex Reimbursement Documentation:DME suppliers face escalating audit scrutiny from Medicare Administrative Contractors regarding medical necessity documentation, increasing administrative overhead and claim denial rates.
- Legacy System Integration:Electronic health record interoperability gaps between hospital discharge planners and home health intake coordinators are delaying supply authorization and extending patient risk windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ostomy Care and Accessories Market |
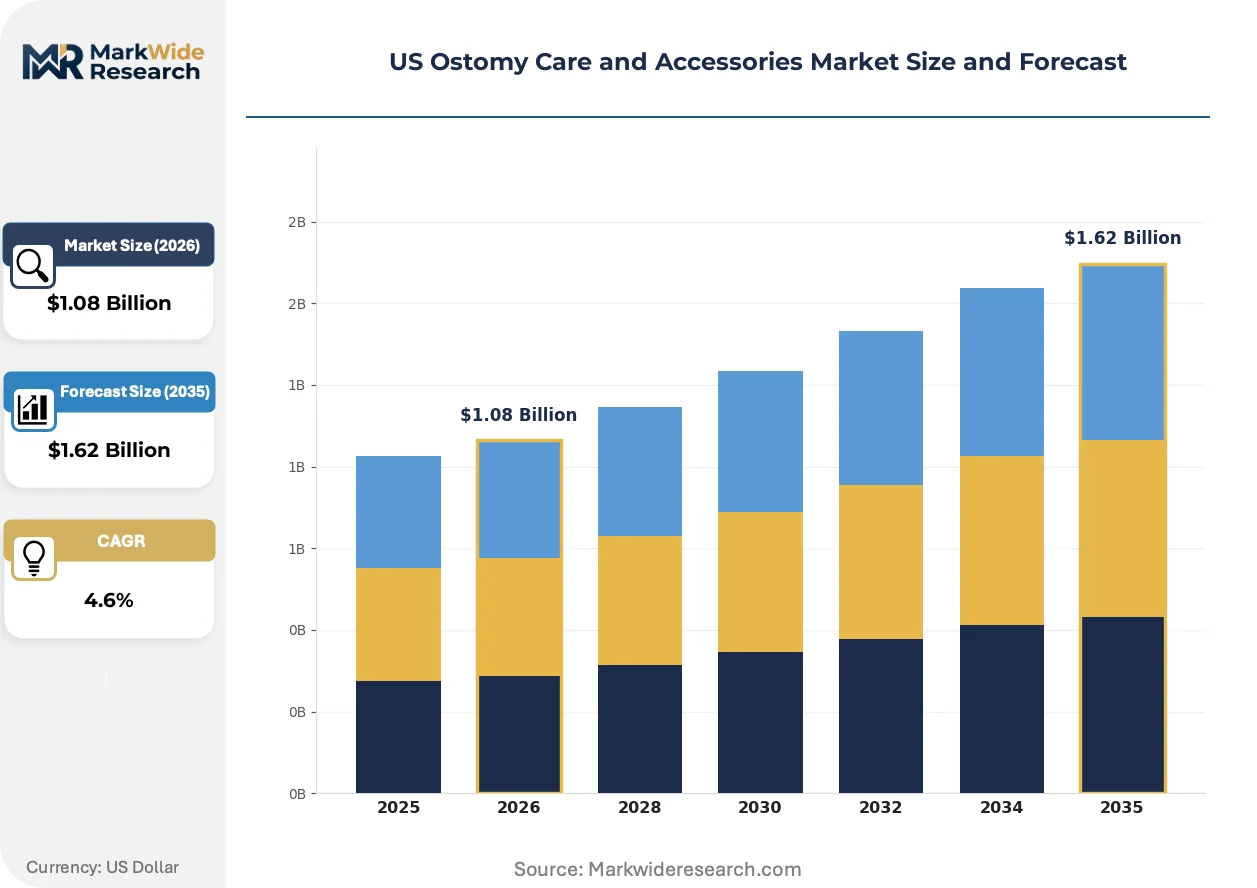
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.62 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colostomy Bags, Ileostomy Bags, Urostomy Bags, Accessories Material: Plastic, Silicone, Hydrocolloid, Non-Woven Delivery Mode: Home Healthcare, Hospitals, Clinics, Online Retail Application: Post-Surgical Care, Chronic Disease Management, Injury Recovery, Preventive Care |
| Companies Covered | B. Braun Melsungen AG, Nu-Hope Laboratories, Inc., Coloplast Corp, Alcare Co., Ltd, Perma-Type Company, Inc., Hollister Incorporated, Marlen Manufacturing & Development Company, Schena Ostomy Technologies, Inc., ConvaTec Group Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ostomy Care and Accessories Market Trends and Innovations
Digital connectivity and materials science are converging to transform ostomy care from a reactive supply model into a predictive health management discipline, with implications for every node from manufacturing to patient support.
Silicone-based adhesive formulations are decomposing the historical dominance of hydrocolloid wafers in sensitive-skin patient segments. Pediatric and geriatric populations with peristomal skin compromise are adopting these alternatives at accelerating rates. The technology is decomposing traditional three-to-seven-day wear cycles into variable-duration protocols calibrated to individual skin tolerance.
FDA's updated medical device classification framework for adhesive skin barriers is compressing 510(k) clearance pathways while elevating clinical data requirements. Manufacturers are restructuring regulatory affairs functions to accommodate parallel submissions for barrier and pouch combinations. The Southeast region, with its concentration of specialty clinic networks, is experiencing the most pronounced adjustment in product qualification timelines.
Patient-initiated brand switching is intensifying as online forums and peer support communities disseminate product performance comparisons. Direct-to-patient subscription platforms are displacing traditional DME supplier relationships in urban and suburban markets. This behavioral shift is most visible in California and the Northeast, where insurance-integrated fulfillment options have achieved highest penetration among working-age ostomates.
US Ostomy Care and Accessories Market Segmentation
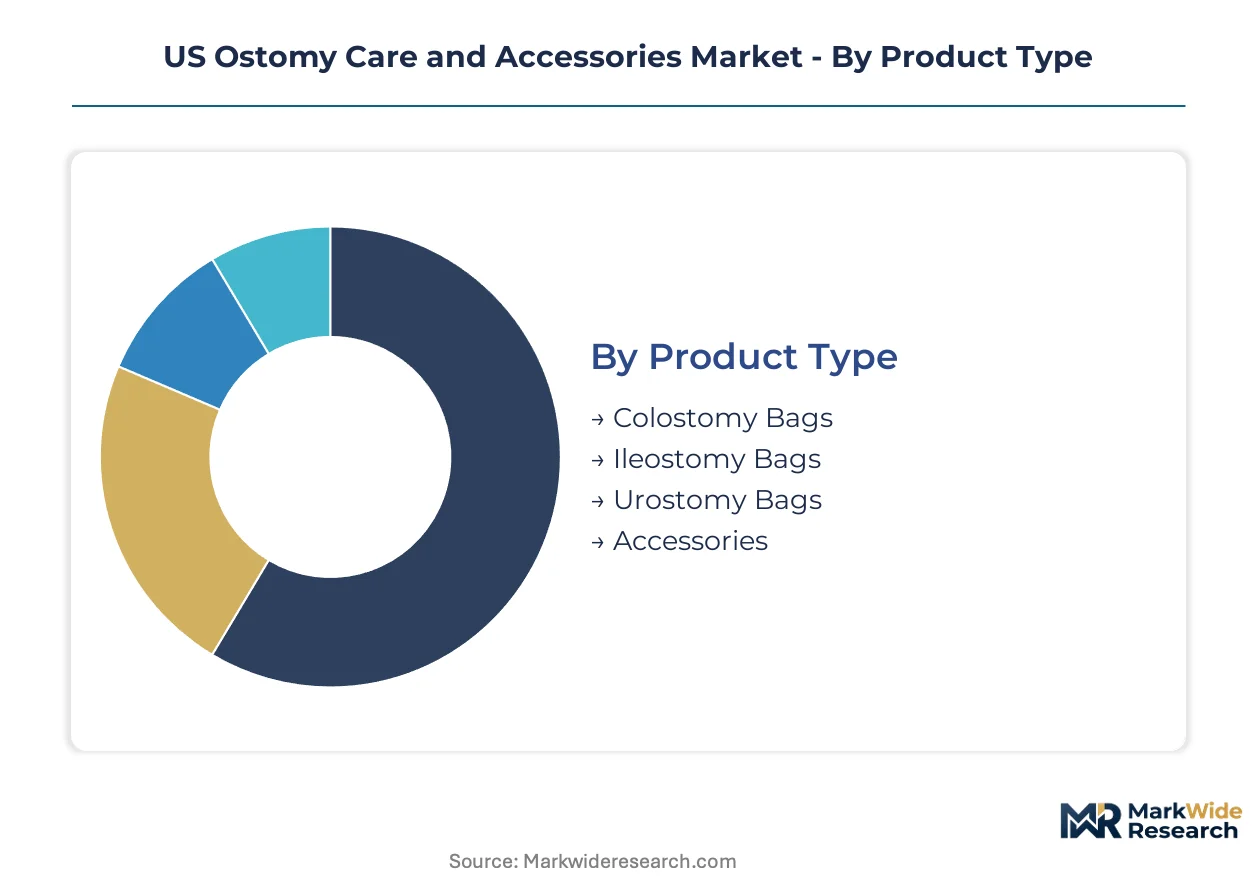
Segmentation in US ostomy care reveals how FDA device classifications and CMS reimbursement tiers fragment procurement pathways across patient acuity levels. Each dimension exposes distinct margin structures and competitive positioning opportunities for manufacturers and distributors.
Product Type:
FDA 510(k) clearance requirements vary substantially across pouching system categories, with drainable versus closed systems facing different clinical data thresholds.
- Colostomy Bags:These one-piece and two-piece drainable or closed pouching systems collect waste from surgically created colonic stomas. Demand concentrates in the Southeast, where Texas and Florida Medicaid expansion is enlarging the addressable patient population for post-colorectal cancer surgery care. The category faces pricing pressure from Medicare Advantage carve-outs that shift volume toward direct-to-patient fulfillment models.
- Ileostomy Bags:High-output pouching systems with integrated gas filters and liquid waste management features serve small intestine stoma patients. Demand clusters in academic medical centers with specialized enterostomal therapy nursing programs, particularly in Northeast corridor cities where patient education capacity supports advanced system adoption. Output consistency requirements drive preference for integrated barrier-pouch combinations.
- Urostomy Bags:Night drainage bags and day-wear systems with anti-reflux valves manage urinary diversion procedures.
- Accessories:Belt systems, pouch covers, deodorizing products, and skin barrier pastes extend wear time and improve quality of life.
Colostomy bags handle the majority of throughput; accessories are expanding most quickly as patients demonstrate willingness to pay out-of-pocket for quality-of-life improvements.
Material:
Raw material qualification timelines under FDA updated device classification rules are reshaping converter relationships with specialty chemical suppliers.
- Hydrocolloid:Medical-grade pectin and carboxymethylcellulose-based adhesive wafers form the dominant skin barrier composition, enabling three-to-seven-day wear cycles through moisture absorption and gentle adhesion. Southeast specialty clinic networks are experiencing the most pronounced supply qualification delays as manufacturers restructure regulatory affairs functions for parallel barrier-pouch submissions.
- Silicone:Soft, conformable adhesive formulations serve sensitive-skin patient segments in pediatric and geriatric populations, decomposing traditional fixed-duration wear protocols into variable cycles calibrated to individual skin tolerance. California and Northeast markets show accelerating adoption where patient-initiated brand switching through online forums drives preference.
- Plastic:Polyethylene and polypropylene films constitute pouch body materials across all system types.
- Non-Woven:Fabric-based pouch covers and backing materials improve comfort and discretion.
Hydrocolloid maintains volume leadership; silicone is gaining share fastest among material transitions.
Delivery Mode:
Post-acute care migration is restructuring channel economics, with reimbursement documentation requirements varying sharply between institutional and home-based procurement.
- Home Healthcare:Durable medical equipment suppliers and specialty pharmacies deliver recurring supply orders to patient residences, capturing volume previously routed through hospital central supply. Medicare Administrative Contractor audit scrutiny on medical necessity documentation is increasing administrative overhead for this channel.
- Online Retail:Insurance-integrated e-commerce platforms with discrete shipping protocols are capturing urban and suburban patient segments prioritizing privacy and convenience. California and Northeast markets show highest penetration among working-age ostomates.
- Hospitals:Acute care settings provide initial post-surgical systems and patient education.
- Clinics:Outpatient wound care centers and specialty stoma clinics manage ongoing system optimization.
Home healthcare dominates current volume; online retail shows the steepest expansion trajectory.
Application:
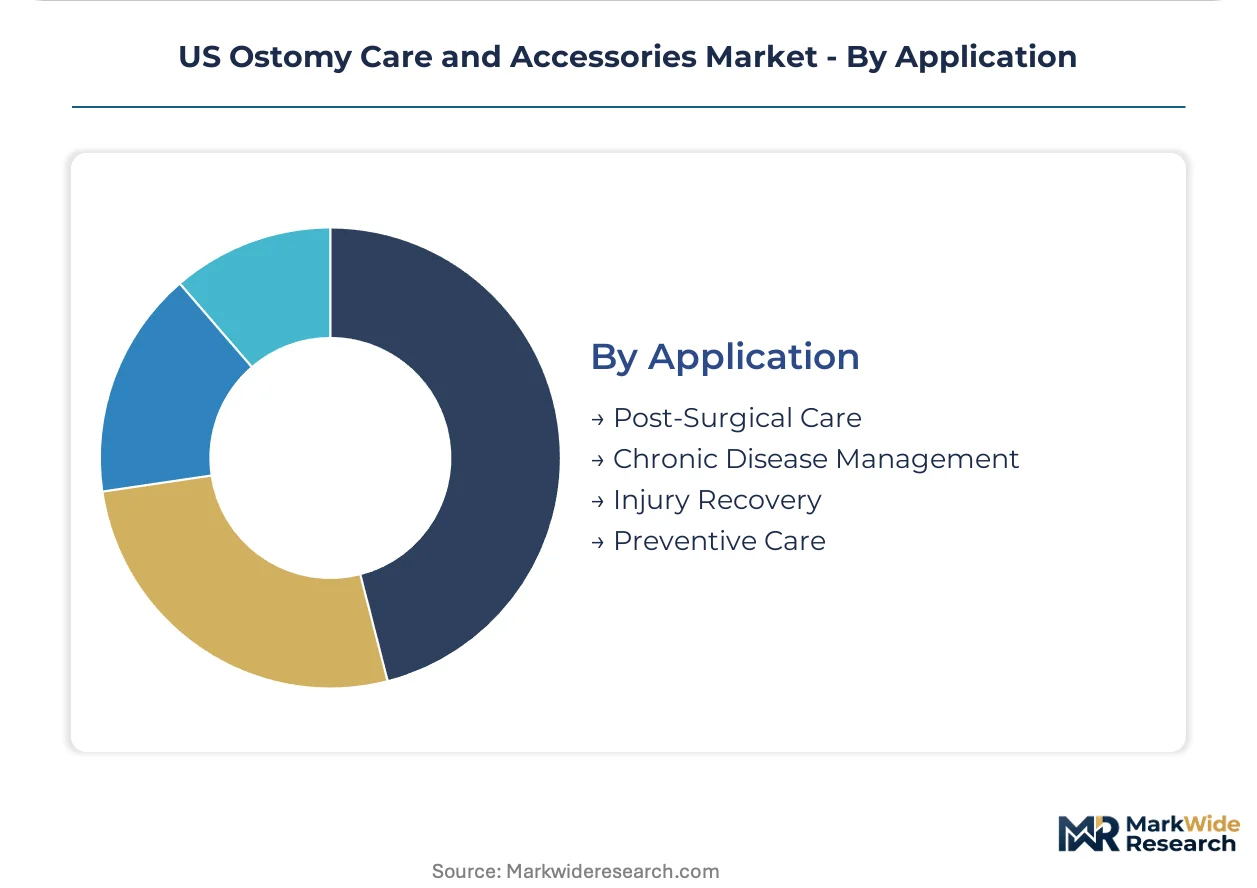
Clinical indication determines reimbursement coding specificity and prior authorization requirements across Medicare, Medicaid, and commercial payers.
- Post-Surgical Care:Initial ostomy creation following colorectal cancer resection, diverticular disease intervention, or trauma surgery requires intensive patient education and system fitting. Southeast specialty clinic network density determines patient volume capture in this segment.
- Chronic Disease Management:Long-term care for inflammatory bowel disease, familial adenomatous polyposis, and other conditions necessitating permanent or temporary ostomy drives recurring supply demand. Texas, Florida, and Georgia Medicaid expansion decisions create variable access landscapes.
- Injury Recovery:Trauma-related ostomies require temporary systems with anticipated reversal procedures.
- Preventive Care:Prophylactic ostomy in complex abdominal surgery cases represents a smaller volume category.
Post-surgical care generates the highest patient throughput; chronic disease management delivers the most predictable recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA medical device regulations and CMS reimbursement policies anchor demand concentration across US sub-regions, with state-level Medicaid decisions creating sharp access disparities that reshape distributor network economics.
Southeast (Florida/Georgia)
Texas and Florida Medicaid expansion decisions are enlarging the addressable patient population for post-surgical ostomy care. State Medicaid programs in Georgia are extending coverage eligibility for durable medical equipment, driving network expansion among regional DME distributors. Atlanta and Miami specialty clinic networks are experiencing the most pronounced patient volume growth as aging demographics concentrate surgical interventions.
Texas
Post-acute care migration from hospital central supply to home health agencies is restructuring procurement channels across Houston and Dallas-Fort Worth metro areas. State Medicaid expansion is creating variable access landscapes where DME supplier network density determines product availability. San Antonio specialty wound care centers are capturing volume previously managed through institutional discharge planning.
Northeast Corridor
Academic medical centers with specialized enterostomal therapy nursing programs in Boston and New York City support advanced pouching system adoption. Medicare Advantage plan carve-outs for ostomy supplies are altering competitive dynamics between national distributors and regional specialty pharmacies. Philadelphia and Baltimore outpatient clinics manage ongoing system optimization for inflammatory bowel disease patient cohorts.
California
Insurance-integrated e-commerce platforms with discrete shipping protocols are capturing urban and suburban patient segments prioritizing privacy and convenience. Patient-initiated brand switching through online forums is driving preference for silicone-based adhesive alternatives. Los Angeles and San Francisco Bay Area markets show highest penetration of direct-to-patient subscription fulfillment among working-age ostomates.
Midwest (Illinois/Ohio/Michigan)
Legacy hospital supply relationships in Chicago and Cleveland are gradually displacing volume toward home healthcare channels as post-acute care shifts outside institutional settings. Medicare Administrative Contractor audit scrutiny on medical necessity documentation is increasing administrative overhead for regional DME suppliers. Detroit specialty clinic networks are experiencing qualification delays as manufacturers restructure regulatory affairs functions for parallel barrier-pouch submissions.
US Ostomy Care and Accessories Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the ostomy care value chain. The market exhibits moderate consolidation at the manufacturing tier with fragmented distribution channels. Three archetypes dominate: multinational medical device conglomerates with direct-to-patient platforms, specialized wound care manufacturers with R&D intensity in adhesive formulations, and high-volume converters serving national DME distributors. Competitive moves center on regulatory affairs restructuring for parallel device submissions and insurance-integrated e-commerce channel development.
Among the multinational tier, Coloplast Corp and ConvaTec Group Plc occupy positions defined by scale and channel reach. Hollister Incorporated exemplifies the R&D-intensive specialist archetype with concentrated expertise in hydrocolloid adhesive chemistry. Nu-Hope Laboratories, Inc. and Marlen Manufacturing & Development Company represent mid-scale fabricators serving regional specialty clinic networks with customized system configurations.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Nu-Hope Laboratories, Inc. |
| Coloplast Corp |
| Alcare Co., Ltd |
| Perma-Type Company, Inc. |
| Hollister Incorporated |
| Marlen Manufacturing & Development Company |
| Schena Ostomy Technologies, Inc. |
| ConvaTec Group Plc |
| Others |
Pricing and Supply Chain Analysis
Take-or-pay agreements between hydrocolloid resin converters and specialty chemical manufacturers lock in multi-year supply access while capping input cost volatility for FDA-qualified skin barrier production. These contract structures anchor price visibility for US ostomy care manufacturers navigating CMS reimbursement compression.
Pricing Analysis
Price spreads between California and Southeast markets reflect Medicare Advantage plan density and DME supplier network concentration. A three-tier pricing structure across premium, standard, and economy levels stratifies by adhesive formulation complexity and wear-time certification. Cost compression in economy tiers stems from Medicaid administrative burden and audit scrutiny. Home healthcare procurement committees exhibit highest price sensitivity; academic medical centers with enterostomal therapy programs demonstrate lowest.
Supply Chain Analysis
US and European specialty chemical manufacturers anchor medical-grade hydrocolloid resin production for skin barrier converters. Supply chains draw from pectin feedstock concentrated in citrus-processing regions and carboxymethylcellulose from wood pulp derivatives. Single-source vulnerability concentrates among three qualified resin suppliers, exposing converters to FDA requalification delays. Distribution runs through national durable medical equipment distributors and insurance-integrated specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping US ostomy care as direct-to-patient subscription models disintermediate traditional DME supplier relationships, with insurance-integrated fulfillment creating winner-take-most dynamics in urban markets.
For Market Incumbents: Shield recurring revenue streams by deepening backward integration into hydrocolloid resin qualification pipelines and securing exclusive Medicare Advantage plan carve-out contracts. FDA 510(k) pathway friction threatens product launch velocity; incumbents should restructure regulatory affairs for parallel barrier-pouch submissions.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers accelerated market entry for silicone-based adhesive innovations targeting pediatric and geriatric sensitive-skin segments. White-space concentrates in online retail channel integration and accessories category expansion where patients pay out-of-pocket. A reimbursement-integrated e-commerce go-to-market angle captures privacy-seeking working-age ostomates in California and Northeast corridors.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale manufacturers with captive silicone formulation capabilities and established specialty clinic relationships. Long-term viability hinges on convergence with remote patient monitoring and value-based care incentives. Watch for CMS national coverage determinations expanding sensor-enabled pouch reimbursement as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Parallel Submission | Accelerates skin barrier and pouch combination approvals amid updated classification rules. |
| Medicare Advantage Carve-Out Negotiation | Secures dedicated procurement pathways outside fee-for-service reimbursement constraints. |
| Silicone Formulation R&D Investment | Captures sensitive-skin patient segments decomposing traditional hydrocolloid wear cycles. |
| Insurance-Integrated E-Commerce Launch | Displaces traditional DME relationships through discrete shipping and prior authorization automation. |
| Sensor-Enabled Pouch Development | Aligns with CMS value-based care incentives for proactive home health intervention models. |
Research Methodology
A spread of perspectives from enterostomal therapy nurses, hospital purchasing committee members, DME supplier procurement leads, and FDA regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against CMS national coverage determinations, FDA 510(k) clearance databases, state Medicaid expansion filings, and GPO contract repositories. Bottom-up patient volume modeling and top-down reimbursement flow analysis provided triangulation across the forecast framework.
Segmentation dimensions modeled include product type, material composition, delivery mode, and application across the projection horizon. CAGRs were derived from patient incidence projections, procedure volume trajectories, and reimbursement rate assumptions. Industry-specific forecast inputs incorporate enterostomal therapy nursing graduation rates and Medicare Advantage plan benefit design evolution.
Decision-makers should treat outputs as directional under stable FDA device classification rules and CMS reimbursement policy continuity; material deviation would warrant model refresh. Specific risk factors include state-level Medicaid eligibility reversals, hydrocolloid resin supply disruptions, and 510(k) review timeline extensions. Recalibration cycles align with material shifts in regulatory guidance and payer benefit structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Colostomy Bags Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Micro Vials Market
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
Sterile Container Market
Medical Supplies
Global Hypodermic Needles Market