
 Global Pregnancy Detection Kits Market | 2026-2036
Global Pregnancy Detection Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pregnancy Detection Kits Market Foresight
EU MDR is pivoting the compliance burden for lateral-flow device manufacturers toward clinical evidence requirements and post-market surveillance obligations. Swiss Precision Diagnostics GmbH leverages its captive manufacturing footprint to absorb these documentation costs without margin erosion. Piramal Enterprises anchors its competitive stance through dense pharmacy distribution across South Asia, while Abbott Laboratories differentiates via dual-track regulatory filings that secure simultaneous FDA and CE marking.
Pregnancy detection kits are disposable immunochromatographic devices that detect human chorionic gonadotropin in urine or serum samples, typically achieving sensitivity thresholds of 25 mIU/mL within three minutes of sample application. Their commercial purpose centers on enabling early, private pregnancy confirmation outside clinical settings. Urine test kits dominate volume due to shelf stability and minimal user training, while digital detectors command premium positioning through Bluetooth-linked cycle tracking and result logging. Immunoassay technology underpins the majority of unit economics, though chemiluminescence is gaining share in fertility centers where quantitative hCG monitoring supports early pregnancy management.
FDA 510(k) pathways, EU MDR notified body oversight, and WHO prequalification standards collectively determine which manufacturers can access reimbursed channels and humanitarian procurement pools. The FDA's evolving template for over-the-counter diagnostic clearances is narrowing the gap between professional-lab and home-use performance claims. Stakeholders must monitor how decentralized clinical trial designs reshape evidentiary requirements for algorithm-enhanced digital readouts.
Market Dynamics
The FDA's compression of over-the-counter diagnostic clearance timelines is restructuring competitive entry barriers, allowing algorithm-enhanced digital readouts to reach pharmacy shelves faster than legacy lateral-flow formats while forcing incumbents to defend through post-market surveillance investments.
Growth Catalysts
- Privacy-seeking first-time mothers:Home testing demand accelerates as digital-native consumers prioritize confidentiality and immediate results over clinical visits, particularly in markets with limited OB-GYN access.
- WHO prequalification standards:Humanitarian procurement pools now require documented shelf stability and temperature tolerance, expanding manufacturer access to developing-world health ministries and NGO supply chains.
- Bluetooth-linked cycle tracking:Connected devices capture longitudinal fertility data, creating subscription revenue streams and sticky user ecosystems beyond one-time test purchases.
Market Restraints
- EU MDR clinical evidence requirements:Lateral-flow device manufacturers face expanded post-market surveillance obligations and notified body backlogs that extend time-to-certification by 12-18 months.
- Nitrocellulose membrane supply concentration:Three Asian suppliers control 70% of high-purity membrane substrate, exposing manufacturers to input volatility and geopolitical shipping disruptions.
- Serum-based laboratory immunoassays:Hospital and fertility center quantitative hCG monitoring retains diagnostic authority for high-risk pregnancies, capping home-test premium pricing power.
Strategic Opportunities
- Tier-two and tier-three Indian cities:Pharmacy network expansion and direct-to-consumer e-commerce penetration create first-mover advantage in underpenetrated markets with rising female literacy and smartphone adoption.
- Dual-track regulatory filings:Simultaneous FDA 510(k) and CE marking submissions compress total approval timelines and unlock transatlantic revenue recognition within a single fiscal cycle.
- Chemiluminescence-quantitative convergence:Fertility centers seek portable quantitative hCG devices that bridge home convenience with clinical-grade sensitivity, opening premium positioning above standard lateral-flow units.
Industry Challenges
- Algorithm validation for digital readouts:Machine-learning result interpretation requires decentralized clinical trial designs that lack established evidentiary templates, creating regulatory uncertainty and development cost overruns.
- Captive manufacturing documentation:EU MDR technical file requirements demand extensive supply chain traceability that outsourced producers struggle to provide without margin-destroying audit investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pregnancy Detection Kits Market |
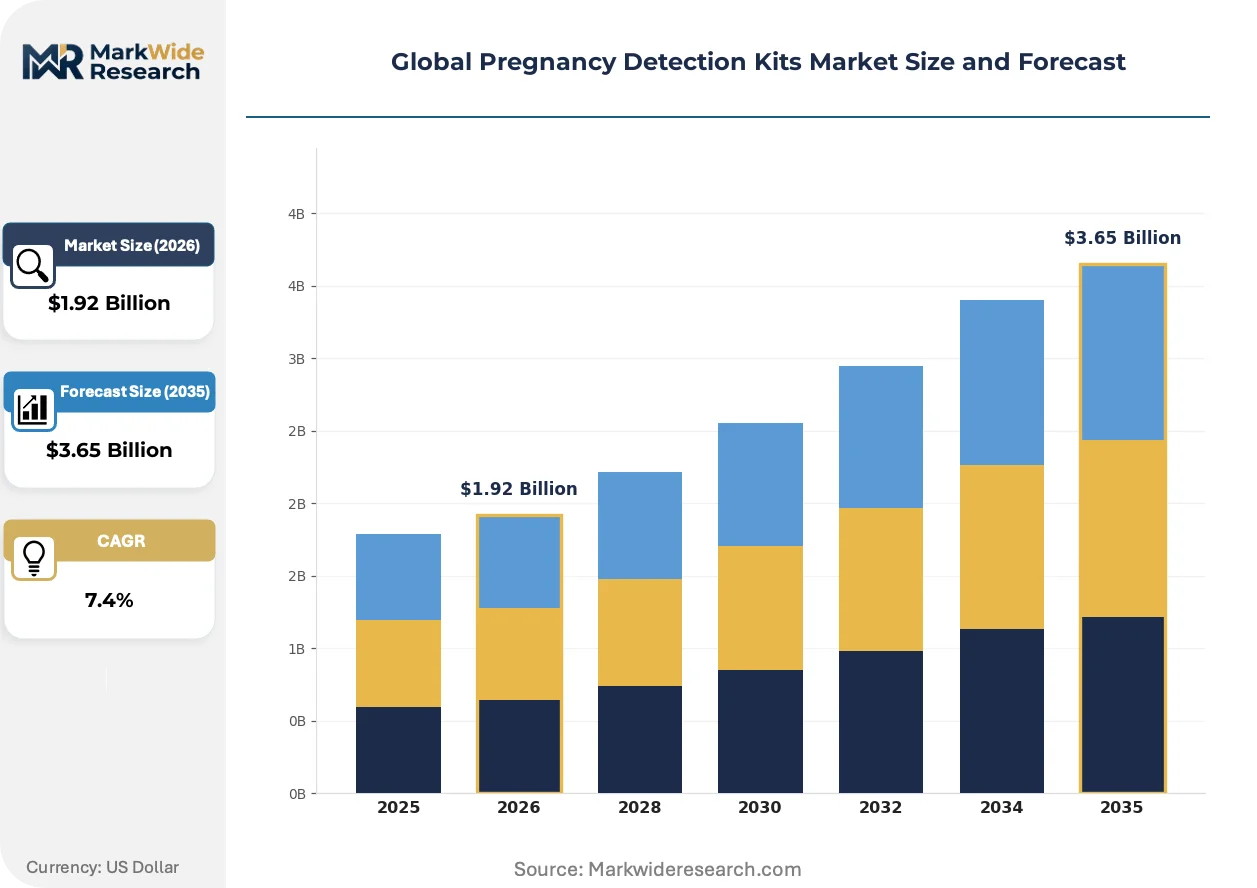
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.65 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Test Kits, Blood Test Kits, Combination Kits, Digital Detectors Technology: Immunoassay, Colorimetric, Enzyme-Linked Immunosorbent Assay, Chemiluminescence, Optical Sensors Application: Home Testing, Clinical Diagnostics, Fertility Centers, Obstetrics & Gynecology Clinics End User: Pharmacies, Diagnostic Laboratories, Maternity Hospitals, Wellness Centers |
| Companies Covered | Swiss Precision Diagnostics GmbH, bioMérieux SA, QuidelOrtho Corporation, Piramal Enterprises, Cardinal Health Inc., Abbott Laboratories, Procter & Gamble Co., Germaine Laboratories Inc., Church & Dwight Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pregnancy Detection Kits Market Shifts & Advancements
Digital connectivity and algorithmic result interpretation are compressing the functional gap between professional laboratory diagnostics and home-use devices, while regulatory frameworks race to accommodate evidence generation for software-enhanced medical devices.
Lateral-flow immunoassay technology is consolidating its position as the dominant cost-engineered platform for mass-market pregnancy confirmation. Retail pharmacy chains and direct-to-consumer subscription services are adopting these devices as loss-leading customer acquisition tools. The technology is consolidating manufacturing scale around automated membrane dispensing and cassette assembly, driving unit economics below $0.50 per test at volume.
EU MDR notified body oversight is intensifying documentation requirements for in vitro diagnostic self-tests. Manufacturers must now submit clinical performance studies and post-market surveillance plans that mirror pharmaceutical-grade rigor. Home-use pregnancy detection kits face extended certification timelines as notified bodies prioritize higher-risk device categories, creating temporary competitive shelter for pre-certified incumbents.
Subscription-based fertility tracking is displacing episodic over-the-counter purchases among digitally engaged consumers. Direct-to-consumer platforms bundle Bluetooth-enabled test hardware with mobile application cycle logging, capturing recurring revenue through data-driven ovulation prediction. This behavioral shift concentrates most visibly in North American and Western European urban markets where smartphone penetration and health-data comfort intersect.
Global Pregnancy Detection Kits Market Segmentation
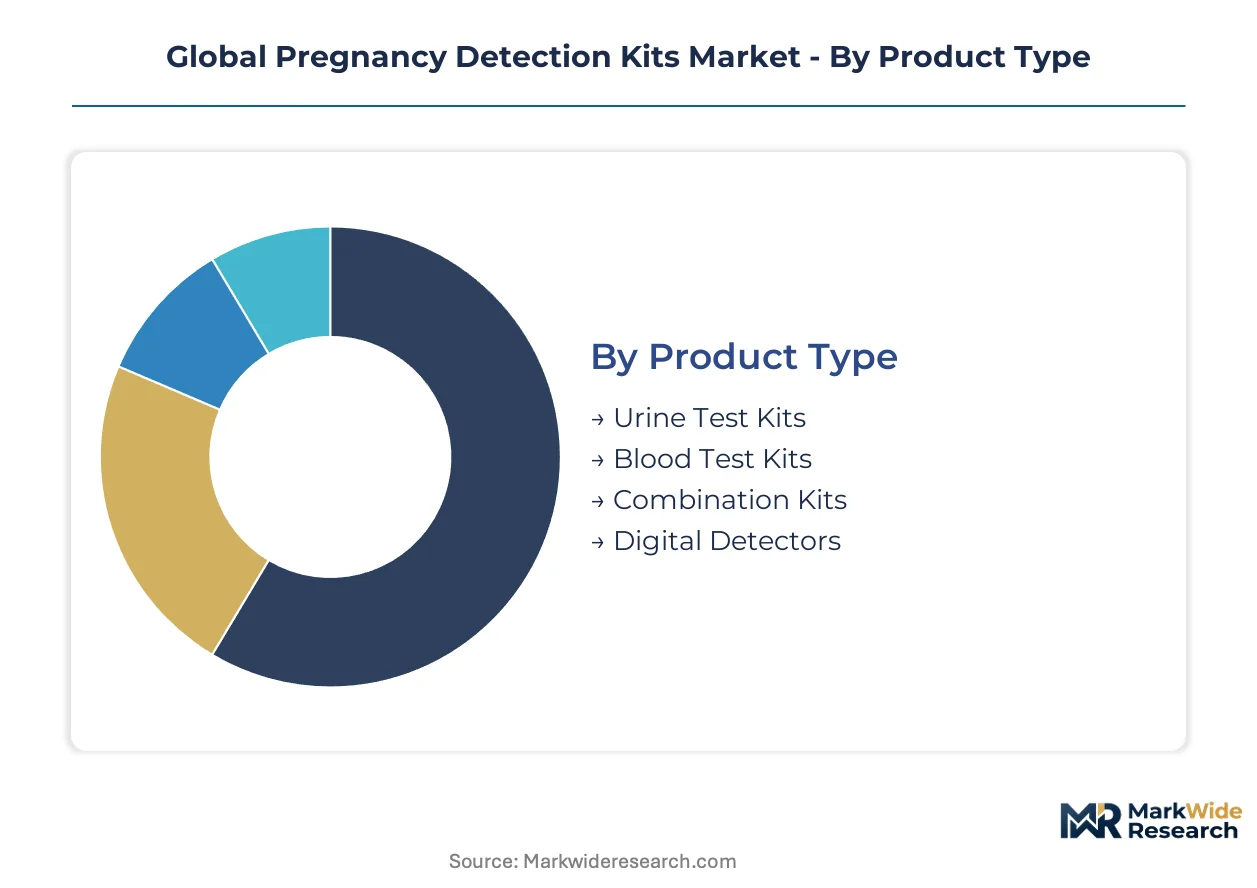
Segmentation in pregnancy detection kits reveals how technology sophistication, distribution channel economics, and user setting requirements create distinct competitive arenas. Manufacturers must align R&D investment and regulatory strategy with the specific performance and access demands of each segment cluster.
Product Type:
Replacement cycles vary sharply across product formats, with digital detectors driving hardware refresh demand while strip-based formats compete on per-test economics and shelf-life stability.
- Urine Test Kits:Lateral-flow strips and midstream devices detect hCG at 25 mIU/mL sensitivity without electronic components. Demand concentrates in India and Southeast Asia where pharmacy counter sales and e-commerce subscription models expand access beyond clinic-dependent populations.
- Digital Detectors:Bluetooth-enabled hardware pairs with mobile applications for cycle tracking and result logging. North American and Western European consumers drive adoption through direct-to-consumer channels seeking longitudinal fertility data and subscription revenue capture.
- Blood Test Kits:Capillary blood collection devices offer quantitative hCG measurement for early detection. Fertility centers and diagnostic laboratories in Germany and Japan utilize these for precise monitoring.
- Combination Kits:Multi-format packages bundle urine strips with ovulation predictors. Retail pharmacy chains in Brazil and Mexico deploy these as customer acquisition tools.
Urine test kits sit at the top of the volume ranking, with digital detectors climbing the fastest.
Technology:
Cost-to-performance ratios determine technology selection, with mature immunoassay platforms defending mass-market position against chemiluminescence encroachment in clinical settings.
- Immunoassay:Antibody-antigen binding on nitrocellulose membranes delivers results within three minutes at manufacturing costs below $0.50 per unit. Automated dispensing and cassette assembly in Chinese and Malaysian contract facilities sustain global supply.
- Chemiluminescence:Light-emitting detection systems achieve quantitative hCG measurement for fertility center applications. South Korean and Swiss manufacturers target premium positioning through portable device miniaturization.
- Colorimetric:Visual dye reaction without electronic interpretation serves lowest-cost market tiers. Sub-Saharan African health ministries procure these for community health worker deployment.
- Enzyme-Linked Immunosorbent Assay:Laboratory-grade specificity supports reference standard applications. WHO prequalification programs validate these for procurement pools.
- Optical Sensors:Smartphone camera-based result interpretation eliminates dedicated hardware. Israeli and Californian startups pilot these for telemedicine integration.
Immunoassay dominates absolute unit shipments, while chemiluminescence gains share fastest in clinical substitution.
Application:
User setting dictates sensitivity requirements, result format, and regulatory pathway complexity, creating divergent margin structures across consumer and professional channels.
- Home Testing:Privacy-seeking first-time mothers in tier-two Indian cities and Indonesian urban centers drive volume through pharmacy networks and direct-to-consumer platforms. FDA 510(k) and EU MDR self-test certifications determine market access.
- Fertility Centers:Quantitative hCG monitoring supports early pregnancy management and IVF cycle tracking. German and Japanese clinics demand portable devices bridging home convenience with laboratory precision.
- Clinical Diagnostics:Hospital laboratories utilize serum-based immunoassays for high-risk pregnancy confirmation. CDSCO-regulated Indian diagnostic chains and Health Canada-certified Canadian labs maintain this segment.
- Obstetrics & Gynecology Clinics:Point-of-care rapid testing supplements ultrasound confirmation. Brazilian and Mexican private clinic networks expand rapid test adoption.
Home testing commands the largest addressable population, with fertility centers expanding most quickly.
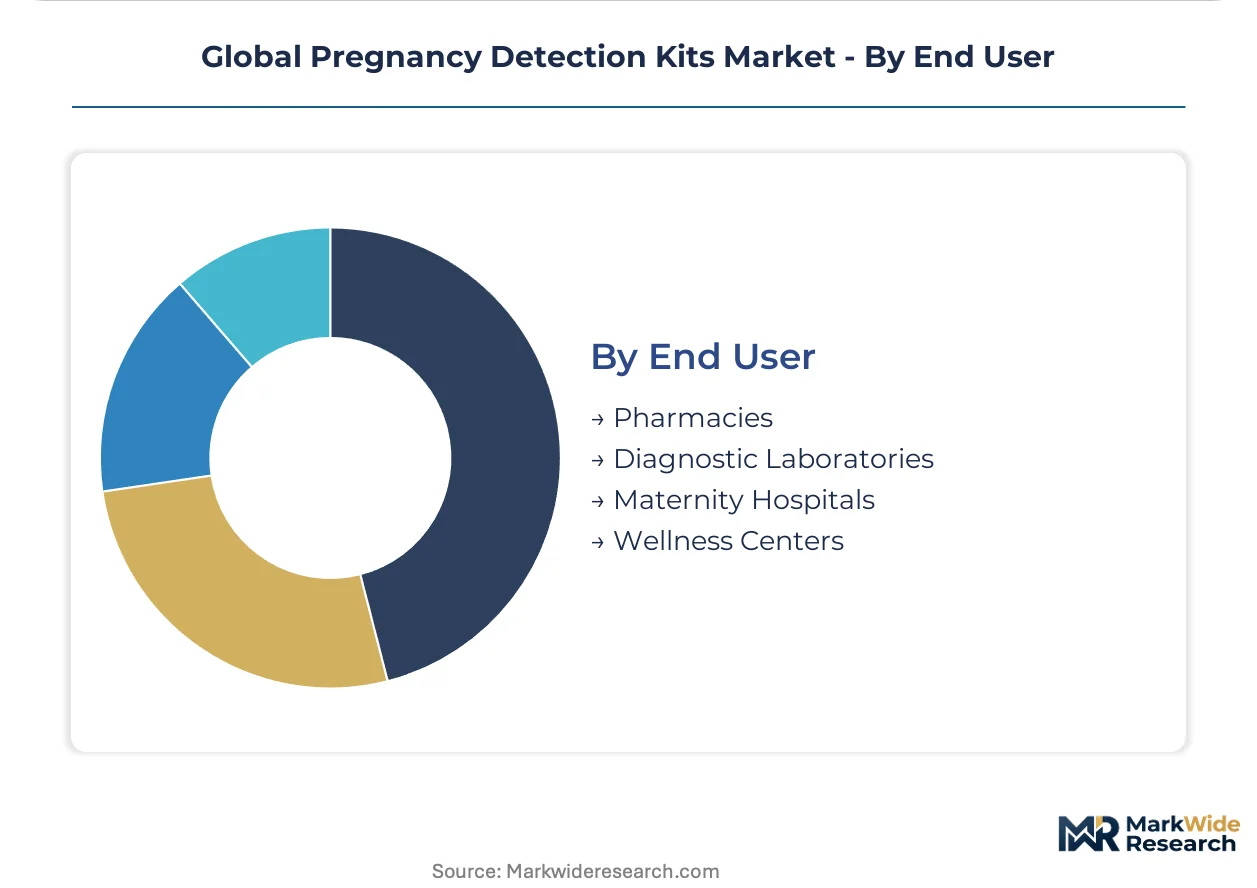
End User:
Procurement authority and reimbursement status reshape pricing power, with pharmacy retail and diagnostic laboratories operating on fundamentally different margin and volume logics.
- Pharmacies:Chain retail and independent drugstores in India, Brazil, and Nigeria serve as primary access points. Direct-to-consumer e-commerce platforms disintermediate traditional wholesale in urban markets.
- Diagnostic Laboratories:Centralized testing facilities in the United States and European Union require batch processing efficiency and LIS integration. WHO prequalification opens developing-world health ministry contracts.
- Maternity Hospitals:Emergency department and antenatal ward rapid testing supports triage decisions. Saudi Arabian and Emirati hospital construction programs expand installed base.
- Wellness Centers:Corporate and concierge health services bundle fertility tracking with preventive care. South Korean and Singaporean urban markets show earliest adoption.
Pharmacies anchor volume throughput, with diagnostic laboratories delivering the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled diagnostic device engineers cluster in Basel, Boston, and Bangalore, anchoring three distinct innovation ecosystems for pregnancy detection technology.
United States
Privacy-conscious first-time mothers and direct-to-consumer subscription services drive demand for Bluetooth-enabled digital detectors. FDA 510(k) pathway revisions compress clearance timelines for over-the-counter diagnostics. Greater Boston hosts algorithm validation startups pioneering smartphone-based result interpretation.
Germany
Fertility centers seek portable quantitative hCG devices bridging home convenience with laboratory precision. EU MDR notified body oversight extends certification timelines through expanded clinical evidence requirements. Baden-Württemberg manufacturing clusters absorb documentation costs through captive vertical integration.
India
Pharmacy network expansion in tier-two and tier-three cities creates access for rising female literacy populations. CDSCO regulates domestic diagnostic manufacturing while WHO prequalification standards open health ministry procurement contracts. Maharashtra anchors production scale for nitrocellulose membrane assembly.
Japan
Aging demographics and delayed childbearing increase fertility center demand for precise early pregnancy monitoring. PMDA maintains stringent performance thresholds for home-use device approvals. Kansai industrial corridors concentrate chemiluminescence miniaturization expertise.
Switzerland
Swissmedic oversees self-test certification for premium-positioned digital detectors distributed across European pharmacy chains. Basel-region precision diagnostics specialists leverage dual-track FDA and CE marking submissions. Zurich-area contract manufacturers supply membrane substrates to global kit assemblers.
Global Pregnancy Detection Kits Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between multinational healthcare conglomerates with broad diagnostic portfolios and regional manufacturers concentrating on lateral-flow economics. Three archetypes dominate: integrated device-and-digital platform builders, pharmacy-distribution specialists, and contract manufacturing scale operators. Competitive moves center on dual-track regulatory filings compressing transatlantic approval timelines and backward integration into nitrocellulose membrane production securing input stability.
Among European precision diagnostics specialists, Swiss Precision Diagnostics GmbH and bioMérieux SA occupy positions exemplifying divergent strategic postures—one anchored in consumer-facing platform integration, the other in clinical laboratory authority. Piramal Enterprises represents the pharmacy-network specialist archetype, its Mumbai-based corporate structure reflecting South Asian distribution density. These three entities illustrate how geographic origin and organizational form shape competitive positioning without prescribing specific tactical commitments.
| Leading Market Players |
|---|
| Swiss Precision Diagnostics GmbH |
| bioMérieux SA |
| QuidelOrtho Corporation |
| Piramal Enterprises |
| Cardinal Health Inc. |
| Abbott Laboratories |
| Procter & Gamble Co. |
| Germaine Laboratories Inc. |
| Church & Dwight Co., Inc. |
| Others |
Supply & Pricing Matrix
Diagnostic membrane engineers concentrated in Basel and Boston create labor-cost differentials that widen pricing-tier spreads between premium digital detectors and economy strip formats. FDA 510(k) pathway compression and EU MDR documentation burdens amplify these spreads as manufacturers pass compliance investments downstream.
Pricing Analysis
Bundled subscription services for Bluetooth-enabled cycle tracking separate from unbundled per-unit strip sales. Three-tier pricing structure across premium digital, standard midstream, and economy strip levels reflects certification grade and after-sales data services. Pricing pressure stems from nitrocellulose membrane supply concentration as three Asian suppliers control substrate availability. Pharmacy retail chains in India and Nigeria exhibit highest price sensitivity; fertility centers in Germany and Japan show lowest sensitivity due to reimbursement coverage.
Supply Chain Analysis
Workforce availability for precision membrane coating concentrates in China, Malaysia, and Maharashtra where automated dispensing technicians anchor production scale. Nitrocellulose membranes, plastic cassette housings, and antibody reagents constitute critical input dependencies. Single-source vulnerability in high-purity membrane substrate exposes assemblers to geopolitical shipping disruptions. Distribution runs through pharmacy wholesale networks in South Asia and direct-to-consumer platforms in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pregnancy Detection Kits Market functions as a stable compounder where recurring fertility-tracking subscriptions and replacement-driven strip demand generate predictable revenue streams. Privacy-seeking first-time mothers and expanding pharmacy access in emerging markets sustain volume growth.
For Market Incumbents: Acquire membrane substrate production capabilities to secure input stability against nitrocellulose supply concentration. Invest in dual-track FDA and CE marking submissions to compress transatlantic approval timelines before EU MDR notified body backlogs extend further. Algorithm-enhanced digital readouts from algorithm-validation startups threaten premium positioning; defend through post-market surveillance investments that satisfy expanded clinical evidence requirements. For New Entrants and Emerging Players: Enter via tier-two and tier-three Indian cities where pharmacy network expansion and direct-to-consumer e-commerce penetration create first-mover advantage in underpenetrated markets. Target fertility centers seeking portable quantitative hCG devices that bridge home convenience with laboratory precision. Pursue WHO prequalification standards to access humanitarian procurement pools and developing-world health ministry contracts. For Investors and Strategic Acquirers: Consumer health conglomerates with diagnostic portfolios are the most active acquirer in this space, seeking digital platform capabilities and pharmacy distribution density. The five-to-ten year viability window favors targets with captive manufacturing documentation and EU MDR technical file readiness. Watch for FDA template finalization for over-the-counter diagnostic clearances as the inflection indicator for algorithm-enhanced device valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Track Regulatory Filing | Simultaneous FDA 510(k) and CE marking submissions compress transatlantic approval timelines. |
| Backward Integration into Membrane Production | In-house nitrocellulose substrate manufacturing secures supply stability against Asian supplier concentration. |
| Bluetooth-Enabled Hardware Refresh | Digital detector replacement cycles create recurring revenue beyond one-time strip purchases. |
| Pharmacy Network Expansion | Dense distribution in tier-two Indian cities captures rising female literacy populations. |
| WHO Prequalification Pursuit | Documented shelf stability and temperature tolerance open health ministry procurement contracts. |
Research Methodology
Direct dialogue with diagnostic device engineers, regulatory affairs specialists at notified bodies, pharmacy procurement managers, and fertility center clinicians grounded the qualitative framework. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, WHO prequalification standards, and CDSCO manufacturing registrations. Bottom-up and top-down triangulation cross-checked unit economics assumptions against macro-level demand projections.
Bottom-up modeling of strip and digital detector shipments by product format, technology platform, and end-user channel fed into top-down market sizing. Segmentation dimensions included product type, technology, application, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of home testing adoption rates and fertility center expansion patterns, calibrated against historical lateral-flow device penetration curves and smartphone-enabled cycle tracking diffusion.
The model holds under stable FDA clearance timelines and EU MDR notified body capacity; deviation in membrane supply disruptions or algorithm validation regulatory uncertainty would shift volume and value projections. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Global Medical Kiosk Market
Medical Devices
Peripheral Guidewires Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Operating Room Integration Market
Medical Devices
Brazil Clear Aligners Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Global Wearable Skin Patch Market
Medical Devices
Absorbable Antibacterial Envelope Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
Global Prosthetics Market
Medical Devices
Global Casting Devices Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Radial Head Resection Implant Market