
 A2 Protein Milk Market | 2026-2036
A2 Protein Milk Market Size, Share, and Industry Trends Forecast 2026-2036
A2 Protein Milk Market Insights
A2 beta-casein protein certification is reorganizing competitive entry in premium dairy, as only herds verified through DNA testing and third-party audit qualify for A2-labeled products. The a2 Milk Company leverages its proprietary intellectual property around A1 protein-free cattle selection to dominate English-speaking markets. Fonterra Co-operative Group anchors its position through backward integration into New Zealand pasture-based supply chains, while China Mengniu Dairy Company competes via licensed partnerships that extend A2 sourcing into Inner Mongolian dairy clusters.
A2 protein milk contains exclusively the A2 variant of beta-casein, omitting the A1 protein associated with BCM-7 peptide release during digestion; this composition requires genomic screening of dairy herds and segregated processing lines to maintain protein purity. Liquid milk occupies the largest revenue pool among product types due to daily consumption frequency and premium shelf positioning, while yogurt commands margin concentration as functional probiotic-A2 combinations attract wellness-oriented shoppers. Fitness centers represent the fastest-growing end-user channel as post-workout recovery protocols incorporate A2 protein for perceived digestibility advantages over conventional whey blends.
Food Standards Australia New Zealand enforces strict identity preservation requirements for A2 claims, while China's SAMR mandates registration of imported dairy products with novel protein positioning. The U.S. FDA maintains oversight through dairy labeling standards that do not yet recognize A2 as a distinct nutritional category, creating compliance friction for cross-border entrants. Stakeholders must monitor whether genomic verification costs decline sufficiently to democratize A2 supply beyond current premium price tiers.
Market Dynamics
Genomic verification costs and segregated supply chain requirements are concentrating A2 protein production among vertically integrated dairy operators with captive herd screening capabilities. This structural barrier favors incumbents with multi-year breeding programs and dedicated processing infrastructure over new market entrants.
Growth Catalysts
- SAMR Registration Pathway:China's streamlined import registration for novel protein-positioned dairy accelerates cross-border product entry into premium retail channels.
- Fitness Center Channel:Post-workout recovery applications in boutique gym chains pull A2 protein into functional nutrition protocols previously dominated by conventional whey isolates.
- Digestive Wellness Positioning:Consumer willingness to pay premium prices for BCM-7 avoidance claims expands addressable market beyond diagnosed lactose intolerance into general wellness segments.
Market Restraints
- Genomic Screening Costs:DNA testing and third-party audit expenses for A2 beta-casein certification inflate production costs relative to conventional dairy.
- Herd Conversion Timelines:Multi-generational cattle breeding programs required for A1 protein elimination lock supply expansion to 5-7 year gestation periods.
- FDA Labeling Ambiguity:Absence of distinct A2 nutritional category recognition in US dairy standards creates compliance friction and claim restriction risks.
Strategic Opportunities
- Probiotic-A2 Convergence:Functional yogurt combining A2 protein with clinically validated strains opens margin-rich positioning in digestive health aisles.
- Pediatric Formula Segment:Infant nutrition applications with A2 beta-casein positioning address parental anxiety around early childhood digestive comfort.
- Inner Mongolian Sourcing Clusters:Licensed partnerships extending A2 verification into northern China's dairy heartland reduce import dependency and tariff exposure.
Industry Challenges
- Identity Preservation Complexity:Segregated processing lines and dedicated tanker logistics required to prevent A1 protein contamination strain operational infrastructure.
- Veterinary Genomics Talent Scarcity:Shortage of specialists combining livestock genetics with dairy supply chain management slows herd conversion program execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | A2 Protein Milk Market |
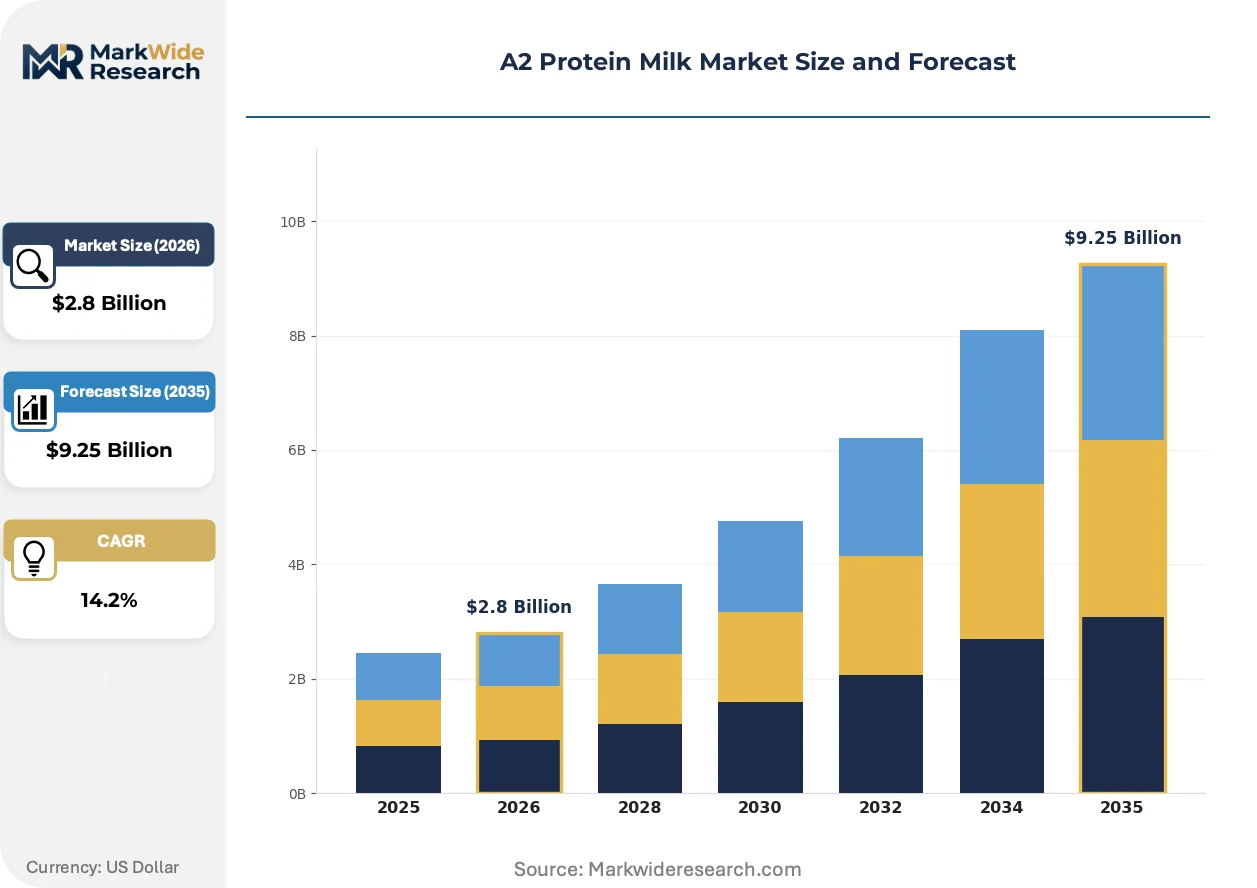
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Milk, Powdered Milk, Cream, Yogurt End User: Households, Restaurants, Cafes, Fitness Centers Form: Bottled, Carton, Tetra Pak, Sachet Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Shops |
| Companies Covered | The a2 Milk Company, Fonterra Co-operative Group, Nestlé, Gujarat Cooperative Milk Marketing Federation, Danone, Arla Foods, Dairy Farmers of America, China Mengniu Dairy Company, Inner Mongolia Yili Industrial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
A2 Protein Milk Market Trends and Innovations
Near-infrared spectroscopy and blockchain traceability are compressing verification timelines and rebuilding trust architectures in premium dairy. These technologies collectively enable real-time protein authentication and farm-to-shelf transparency previously unattainable at commercial scale.
Portable beta-casein testing devices using antibody-based assays are displacing laboratory-dependent verification methods. Mid-sized dairy cooperatives in New Zealand and Australia adopt these units for on-farm screening, reducing third-party testing bottlenecks and accelerating herd qualification decisions. This diffusion is compressing the cost structure for A2 certification and enabling smaller producers to enter premium supply pools.
Food Standards Australia New Zealand's tightened identity preservation requirements for A2 claims mandate segregated storage, dedicated transport, and batch-level documentation. These rules force processors to reconfigure liquid handling infrastructure or exit the category. Australian exporters face heightened audit frequency, while domestic retailers demand supplier indemnification against mislabeling penalties.
Direct-to-consumer subscription models for fresh A2 milk are bypassing traditional retail slotting fee structures. Urban households in Shanghai and Sydney subscribe to weekly deliveries from verified single-source farms, trading price premiums for provenance transparency. This channel shift concentrates buyer relationships with origin-branded producers rather than diversified dairy conglomerates.
A2 Protein Milk Market Segmentation
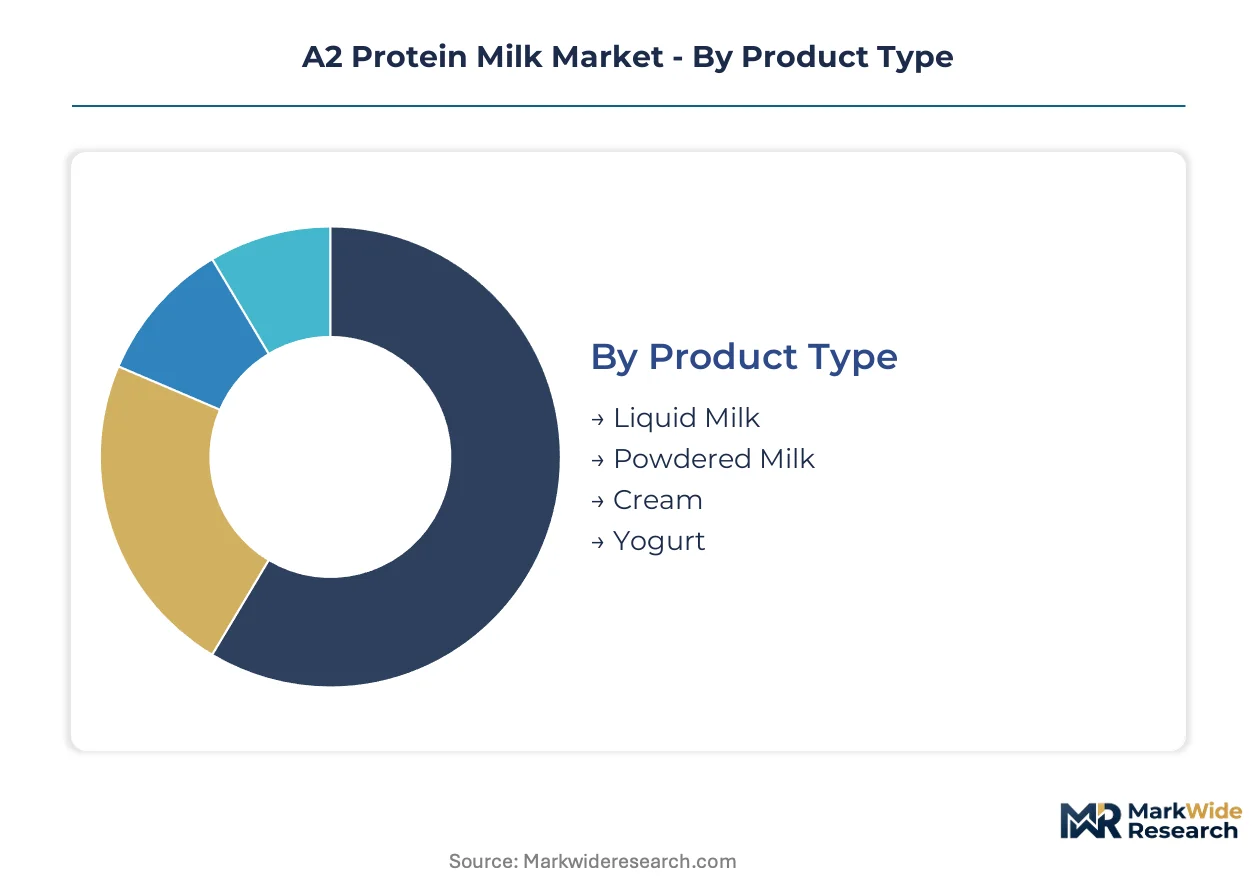
A2 protein milk segmentation tracks how genomic verification costs and segregated supply chains concentrate value across product formats and channel tiers. Margin pools diverge sharply between daily-consumption staples and functional-positioned premium lines.
Product Type:
Margin concentration follows consumption frequency and certification burden, with liquid formats commanding volume leadership and cultured products extracting premium pricing.
- Liquid Milk:Unprocessed A2 beta-casein milk requires continuous cold-chain integrity and dedicated tanker logistics to prevent A1 contamination. Daily consumption frequency in Chinese and Australian households anchors revenue concentration, though per-unit margins compress under identity-preservation audit costs.
- Yogurt:Fermented A2 protein combined with clinically validated probiotic strains creates functional digestive health positioning. Wellness-oriented shoppers in Shanghai and Sydney pay steep premiums for dual-claim products, making this the margin leader despite smaller volume throughput.
- Powdered Milk:Extended shelf life reduces cold-chain dependency for A2 protein preservation, enabling export economics into tariff-sensitive markets.
- Cream:Higher fat concentration amplifies A2 beta-casein purity claims for artisanal foodservice applications in premium restaurant segments.
Liquid milk holds installed capacity. Yogurt is rotating up the share rankings.
End User:
Channel economics split between recurring household subscription models and institutional procurement with diverging price elasticity profiles.
- Households:Direct-to-consumer weekly subscriptions from single-source verified farms bypass retail slotting fees. Urban middle-class families in China trade price premiums for blockchain-traceable provenance, locking in recurring revenue streams for origin-branded producers.
- Fitness Centers:Boutique gym chains incorporate A2 protein into post-workout recovery protocols, displacing conventional whey isolates. This channel is expanding most quickly as functional nutrition protocols professionalize around digestibility claims.
- Restaurants:Premium dining establishments source A2 cream and milk for menu differentiation, though volume remains constrained by foodservice margin pressures.
- Cafes:Specialty coffee chains in Australia and New Zealand leverage A2 positioning for flat white and latte premiumization.
Households hold installed capacity. Fitness centers are climbing the fastest.
Form:
Packaging selection determines shelf-life extension capabilities and cold-chain investment requirements across export versus domestic market strategies.
- Tetra Pak:Aseptic carton technology enables ambient distribution of UHT-processed A2 milk, unlocking Chinese inland markets beyond refrigerated logistics reach. SAMR registration requirements for imported novel-protein dairy favor this format's extended stability during customs clearance.
- Bottled:Premium PET and glass formats signal freshness for direct-to-consumer subscription channels in Sydney and Melbourne, supporting price premiums through tactile quality cues.
- Carton:Gable-top refrigerated cartons dominate Australian and New Zealand supermarket dairy aisles for fresh A2 milk positioning.
- Sachet:Single-serve powder sachets target trial conversion and travel retail segments with lower per-unit commitment.
Tetra Pak holds installed capacity. Bottled is gaining share fastest.
Distribution Channel:
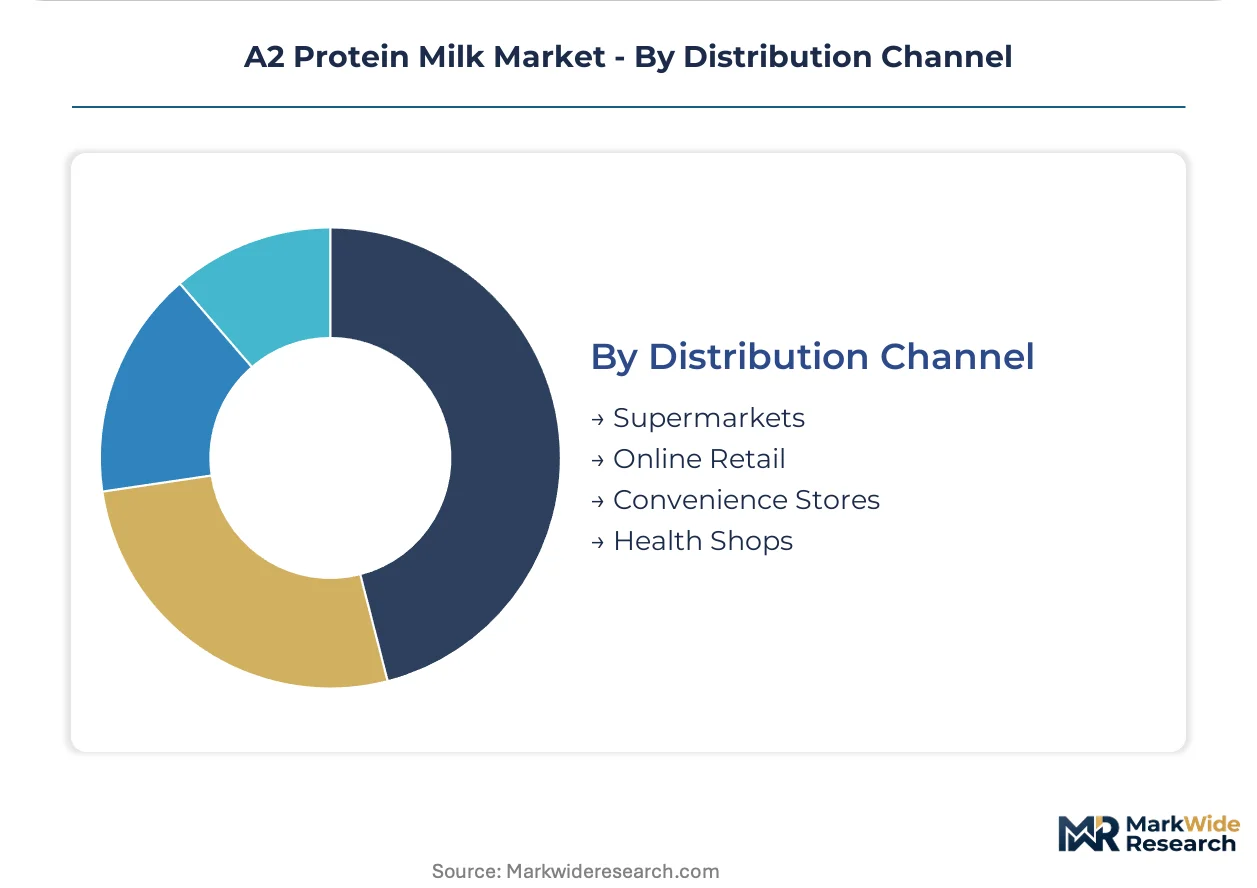
Channel selection determines compliance burden intensity and consumer education investment requirements for novel protein positioning.
- Supermarkets:Major chains in Australia enforce supplier indemnification against Food Standards Australia New Zealand mislabeling penalties. Slotting fees and promotional spend concentrate shelf access among vertically integrated producers with captive herd screening.
- Online Retail:Cross-border e-commerce platforms connect New Zealand origin-branded producers directly to Chinese consumers, bypassing import distributor margins. SAMR registration visibility and livestream commerce integration accelerate premium conversion.
- Convenience Stores:Grab-and-go chilled A2 milk targets urban commuter occasions with premium single-serve pricing.
- Health Shops:Specialist retailers provide educated staff to communicate BCM-7 avoidance science, justifying steeper markups for informed wellness consumers.
Supermarkets hold installed capacity. Online retail is climbing the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR registration pathways for novel protein-positioned dairy accelerate cross-border entry into Chinese premium retail channels. New Zealand's Ministry for Primary Industries and Australia's Food Standards Code tighten labeling requirements, reshaping competitive entry barriers. Demand concentrates in China as middle-class households trade up to premium dairy positioned for lactose sensitivity.
China
Urban middle-class households in Shanghai and Beijing drive demand for blockchain-traceable A2 milk through direct-to-consumer subscription models. SAMR mandates registration of imported dairy products with novel protein positioning, creating compliance checkpoints for New Zealand and Australian exporters. Inner Mongolian dairy clusters around Hohhot host licensed partnerships extending A2 verification into northern China's production heartland.
New Zealand
Pasture-based supply chains anchored by Fonterra Co-operative Group dominate English-speaking market exports through captive herd screening capabilities. The Ministry for Primary Industries enforces strict identity preservation requirements for A2 claims, mandating segregated storage and dedicated transport logistics. Canterbury and Waikato dairy regions concentrate genomic verification infrastructure and third-party audit capacity.
Australia
Food Standards Australia New Zealand's tightened identity preservation rules force processors to reconfigure liquid handling infrastructure or exit the category. Sydney and Melbourne urban households subscribe to weekly deliveries from verified single-source farms, trading price premiums for provenance transparency. Victorian and New South Wales dairy cooperatives adopt portable beta-casein testing devices for on-farm screening, reducing third-party testing bottlenecks.
United States
FDA dairy labeling standards do not recognize A2 as a distinct nutritional category, creating compliance friction for cross-border entrants and restricting claim language. Fitness centers in Los Angeles and New York incorporate A2 protein into post-workout recovery protocols, displacing conventional whey isolates. California and Wisconsin dairy processors face indemnification demands from retailers against mislabeling penalties.
India
Gujarat Cooperative Milk Marketing Federation extends A2 sourcing into Anand and surrounding districts through Amul's established cooperative infrastructure. FSSAI oversight of dairy protein claims remains less prescriptive than Australian or Chinese equivalents, allowing broader positioning flexibility. Maharashtra and Karnataka urban centers witness trial adoption of A2-positioned products through modern trade channels.
A2 Protein Milk Market Competitive Landscape
Listed leaders compete with private specialists across genomic verification capabilities and captive herd access. The market structures around three tiers: proprietary IP holders with multi-decade breeding programs, cooperative giants with backward integration into pasture-based supply chains, and licensed regional players leveraging partnership models for market entry. Two dominant competitive moves define current positioning: M&A activity targeting genomic screening capabilities and strategic partnerships extending A2 verification into new sourcing clusters.
Within the proprietary IP tier, The a2 Milk Company exemplifies the DNA-testing and third-party audit model that dominates English-speaking markets. Fonterra Co-operative Group anchors the cooperative archetype through New Zealand pasture-based supply chain control. China Mengniu Dairy Company occupies the licensed partnership position, extending A2 sourcing into Inner Mongolian dairy clusters through verified herd programs.
| Leading Market Players |
|---|
| The a2 Milk Company |
| Fonterra Co-operative Group |
| Nestlé |
| Gujarat Cooperative Milk Marketing Federation |
| Danone |
| Arla Foods |
| Dairy Farmers of America |
| China Mengniu Dairy Company |
| Inner Mongolia Yili Industrial Group |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at New Zealand's Canterbury and Waikato dairy processing facilities shapes both supply concentration and price floors for A2 protein milk, as genomic verification infrastructure requires dedicated tanker fleets and segregated storage to prevent A1 contamination. This scale dependency locks smaller operators out of premium certification tiers while concentrating margin extraction among vertically integrated cooperatives with captive herd screening capabilities.
Pricing Analysis
Certification level (Food Standards Australia New Zealand-grade) creates the primary spread between origin-branded subscription tiers and mass-market retail positioning. Three-tier pricing structure across premium single-source, standard verified-herd, and economy conventional dairy levels segments buyer willingness to pay for blockchain traceability. Pricing pressure stems from genomic screening cost compression as portable beta-casein testing devices displace laboratory-dependent verification methods. Direct-to-consumer households in Shanghai demonstrate lowest price sensitivity, while Australian supermarket shoppers exhibit highest elasticity to promotional discounting.
Supply Chain Analysis
Container availability constraints on the Trans-Tasman trade lane inflate inbound logistics costs for Australian processors sourcing genomic verification equipment from New Zealand suppliers. Geographic supply concentrates in New Zealand, Australia, and China as Food Standards Australia New Zealand and SAMR registration requirements enforce regional compliance specialization. Raw material dependencies center on A1-free cattle genetics, third-party audit services, and segregated processing infrastructure. Single-source vulnerability runs through Fonterra's captive pasture-based supply chains. Distribution runs through direct-to-consumer subscription channels bypassing traditional retail slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against plant-based protein substitutes encroaching on digestive wellness positioning, as oat and almond milk alternatives capture price-sensitive consumers in fitness center and household channels.
For Market Incumbents: Compound genomic verification capabilities through backward integration into Inner Mongolian dairy clusters, reducing tariff exposure and import dependency. Lock in exclusive supplier indemnification agreements with Australian supermarket chains against Food Standards Australia New Zealand mislabeling penalties. Channel control through direct-to-consumer subscription platforms defends margin position against retail promotional pressure. For New Entrants and Emerging Players: Boutique fitness center recovery protocol integration represents the most penetrable service-layer gap, where incumbents under-serve functional nutrition education needs. Target post-workout A2 protein positioning in Los Angeles and New York gym chains where FDA labeling ambiguity has slowed established player entry. Go-to-market angle should emphasize digestibility science communication through certified nutritionist partnerships rather than retail shelf competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors veterinary genomics specialists combining livestock breeding expertise with dairy supply chain management capabilities. Long-term viability hinges on whether near-infrared spectroscopy and blockchain traceability costs decline sufficiently to democratize A2 certification beyond current premium tiers. Acquisition target archetype: regional dairy cooperatives with established herd conversion programs and underutilized segregated processing capacity. Signal to watch: SAMR registration pathway simplification for novel protein-positioned imports.| Strategic Initiative | Industry Significance |
|---|---|
| Herd Conversion Program Expansion | Multi-generational A1 protein elimination breeding secures captive supply for premium certification tiers. |
| Probiotic-A2 Convergence Product Launch | Functional yogurt combining clinically validated strains opens margin-rich digestive health aisle positioning. |
| Blockchain Traceability Integration | Farm-to-shelf transparency rebuilds consumer trust architectures for urban Chinese subscription households. |
| Licensed Partnership in Inner Mongolia | Local A2 verification reduces import dependency and SAMR registration clearance timelines for Chinese market entry. |
| Portable Beta-Casein Testing Adoption | On-farm screening accelerates herd qualification decisions and compresses third-party audit cost structures. |
Research Methodology
The analysis maps liquid milk, yogurt, powdered milk, and cream segments, each validated through dairy cooperative procurement directors, genomic verification laboratory managers, and supermarket category buyers. Primary interviews with Food Standards Australia New Zealand compliance officers, SAMR registration consultants, and fitness center nutrition program coordinators combined with secondary validation from customs records, dairy herd registration databases, and aseptic packaging trade disclosures. Bottom-up volume builds triangulated against top-down value estimates from premium dairy retail audit data.
Consistency checks validated volume and value outputs against regional processing capacity filings and pasture-based supply chain throughput benchmarks. Segmentation dimensions modeled include product format, end-user channel, packaging technology, and regional regulatory cluster across the projection horizon. CAGRs derived from fitted growth curves incorporating genomic verification cost elasticity, herd conversion program timelines, and SAMR registration pathway efficiency assumptions.
Forecasts assume regulatory continuity in Food Standards Australia New Zealand identity preservation requirements and SAMR novel protein import registration frameworks; material policy shifts would require re-modeling. Specific risk factors include FDA labeling standard revisions recognizing A2 as distinct nutritional category, veterinary genomics talent scarcity slowing herd conversion execution, and trade lane disruption affecting genomic equipment sourcing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Milk Fat Fractions Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Evaporated Milk Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Saudi Arabia Camel Dairy Market
Dairy Products
Textured Butter Market
Dairy Products
United Kingdom Casein and Caseinates Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Canada Milk Protein Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Goat Milk Products Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
South America Dairy Market
Dairy Products
Goat Milk Market