
 Low-Calorie Cream Market | 2026-2036
Low-Calorie Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Calorie Cream Market Analytics
Subscription-based replenishment models for low-calorie cream is expanding how manufacturers monetize recurring household demand. Kraft Heinz Company leverages its retail shelf presence to sustain volume leadership in mass-market channels. Danone competes through specialized plant-based low-calorie formulations that differentiate its portfolio from conventional dairy alternatives.
Low-calorie cream denotes dairy or non-dairy emulsions formulated with reduced fat content, typically under 10 grams per serving, achieved through ultrafiltration, microbial fermentation, or fat-mimetic hydrocolloid stabilization. These products serve commercial and household applications requiring creamy texture with controlled caloric contribution. Coffee creamer leads product type demand due to specialty beverage proliferation, while food services anchors end-user consumption through bulk procurement of culinary cream for recipe-standardized menus. Pouch packaging captures the fastest-growing format segment as single-serve portions align with food service portion control and household trial behavior.
FDA nutritional labeling requirements and USDA dairy standards govern low-calorie cream composition claims, caloric disclosure precision, and organic certification pathways in the United States. EFSA health claim regulations in Europe restrict how reduced-fat positioning can be communicated to consumers, forcing reformulation-for-compliance strategies across export-oriented manufacturers. Stakeholders must monitor evolving clean-label enforcement thresholds and alternative protein regulatory classifications that will determine which formulation technologies secure shelf access.
Market Dynamics
FDA nutritional labeling reforms are compressing formulation cycles as manufacturers recalibrate fat-mimetic hydrocolloid ratios to maintain sub-10-gram serving claims while preserving mouthfeel standards demanded by specialty coffee chains.
Growth Catalysts
- Specialty Coffee Chain Expansion:Premium beverage outlets in the United States are standardizing low-calorie cream as a default offering, creating pull-through demand for pouch-packaged single-serve formats.
- REACH Compliance Export Pathway:European EFSA health claim regulations are forcing reformulation investments that simultaneously unlock shelf access across multiple member states for compliant manufacturers.
- Ultrafiltration Cost Curves:Membrane separation technology improvements are reducing per-unit production costs for reduced-fat dairy emulsions at commercial scale.
Market Restraints
- Hydrocolloid Input Volatility:Guar gum and locust bean bean supply fluctuations from India and Pakistan destabilize cost structures for fat-mimetic stabilization systems.
- Organic Certification Bottlenecks:USDA National Organic Program compliance timelines extend 18-24 months, freezing product pipeline velocity for clean-label entrants.
- Oat Milk Substitution Pressure:Barista-grade oat milk alternatives are capturing coffeehouse dispensing equipment slots previously reserved for dairy-based low-calorie creams.
Strategic Opportunities
- Food Service Bulk Procurement:Recipe-standardized culinary cream contracts for restaurant chains represent underpenetrated volume pools outside retail-dominated channels.
- Subscription Replenishment Models:Direct-to-household auto-delivery platforms are expanding recurring revenue capture beyond traditional grocery replenishment cycles.
- Plant-Based Convergence:Microbial fermentation-derived proteins combined with precision lipid structuring are enabling next-generation non-dairy low-calorie formulations with dairy-comparable functionality.
Industry Challenges
- Clean-Label Enforcement Thresholds:Evolving FDA interpretation of "natural" claims requires continuous label revision and reformulation guardrails.
- Cross-Functional Formulation Talent:Scarcity of technologists versed simultaneously in emulsion science, sensory profiling, and regulatory navigation constrains R&D throughput.
- Legacy Equipment Retrofit Costs:Aseptic filling lines designed for conventional cream require capital-intensive modification to handle hydrocolloid-stabilized low-viscosity emulsions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Calorie Cream Market |
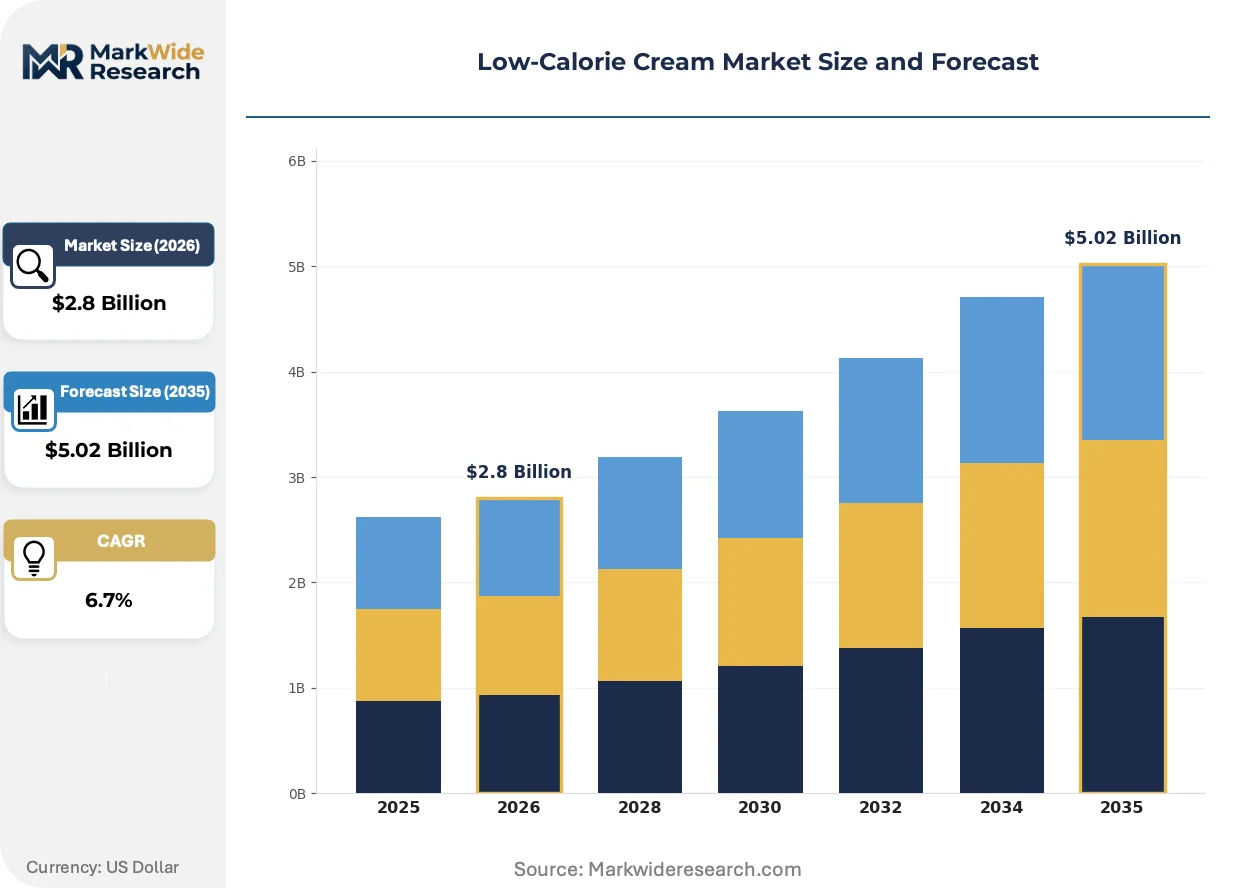
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
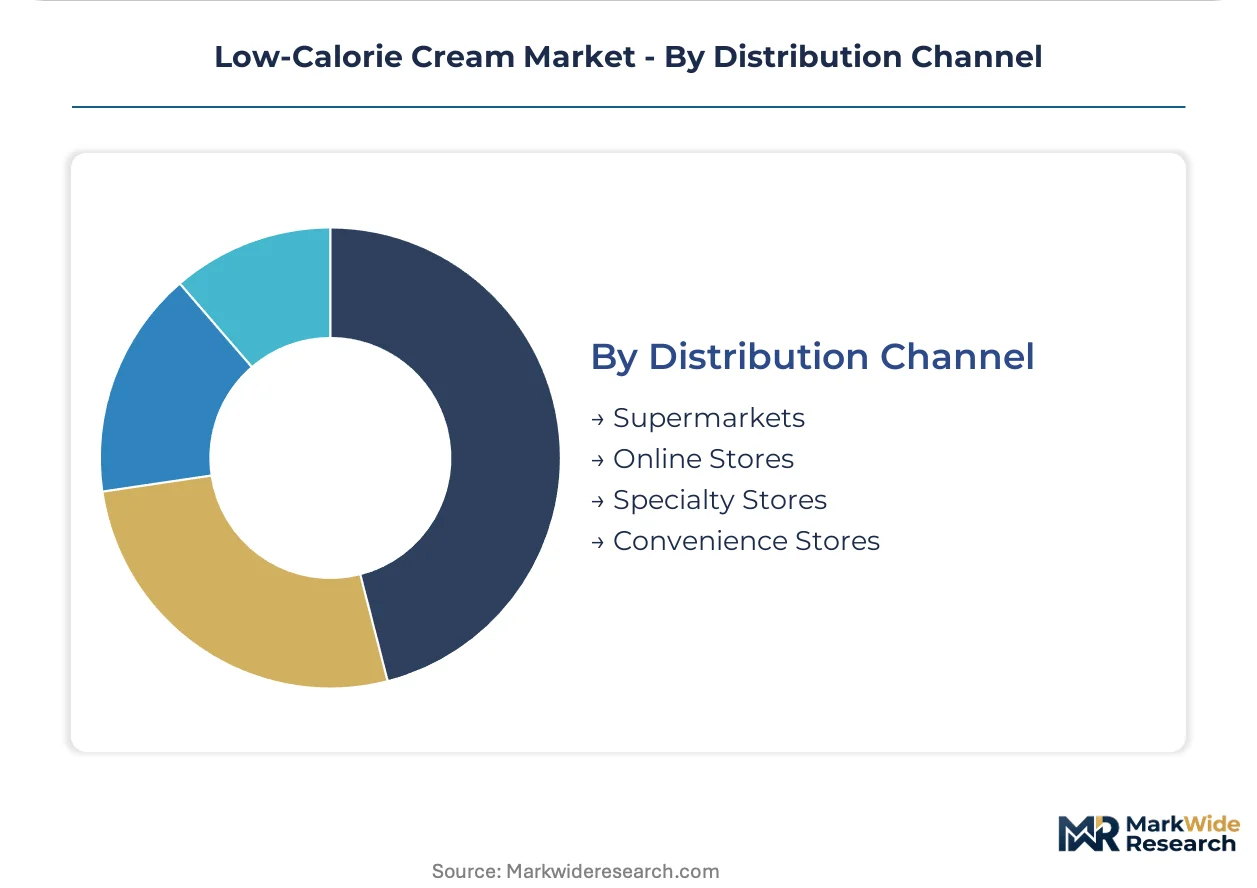
| Segmentation | Product Type: Sour Cream, Whipped Cream, Coffee Creamer, Culinary Cream End User: Households, Food Services, Retailers, Food Manufacturers Packaging Type: Tubs, Cartons, Pouches, Sachets Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Convenience Stores |
| Companies Covered | Kraft Heinz Company, Arla Foods amba, Lactalis Group, Philadelphia Cream Cheese, Kite Hill, Miyoko’s Creamery, Danone, Nestlé, Dairy Farmers of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Calorie Cream Market Evolving Landscape
Formulation science and portion-format engineering are converging to redefine how low-calorie cream delivers texture fidelity at reduced caloric density. Three developments are restructuring competitive positioning.
Precision fermentation-derived dairy proteins are expanding into commercial-scale low-calorie cream production. Specialty ingredient suppliers are scaling microbial biomass facilities to supply food manufacturers with functional milk proteins minus lactose and saturated fat load. This biotechnology is expanding into traditional dairy heartland markets previously resistant to alternative protein incorporation.
EFSA health claim regulations are tightening permissible reduced-fat positioning language across European Union member states. Manufacturers must now substantiate specific metabolic benefit claims through clinical evidence packages, raising compliance investment thresholds. Export-oriented producers are responding by bifurcating formulation portfolios into EU-compliant and rest-of-world specifications.
Single-serve pouch formats are displacing multi-serve bottles in food service procurement specifications. Portion control requirements from institutional buyers are compressing order quantities toward trial-sized units that reduce waste and enable menu flexibility. This format rotation is most visible in United States quick-service restaurant chain supply agreements where dispensing consistency trumps per-ounce cost optimization.
Low-Calorie Cream Market Segmentation
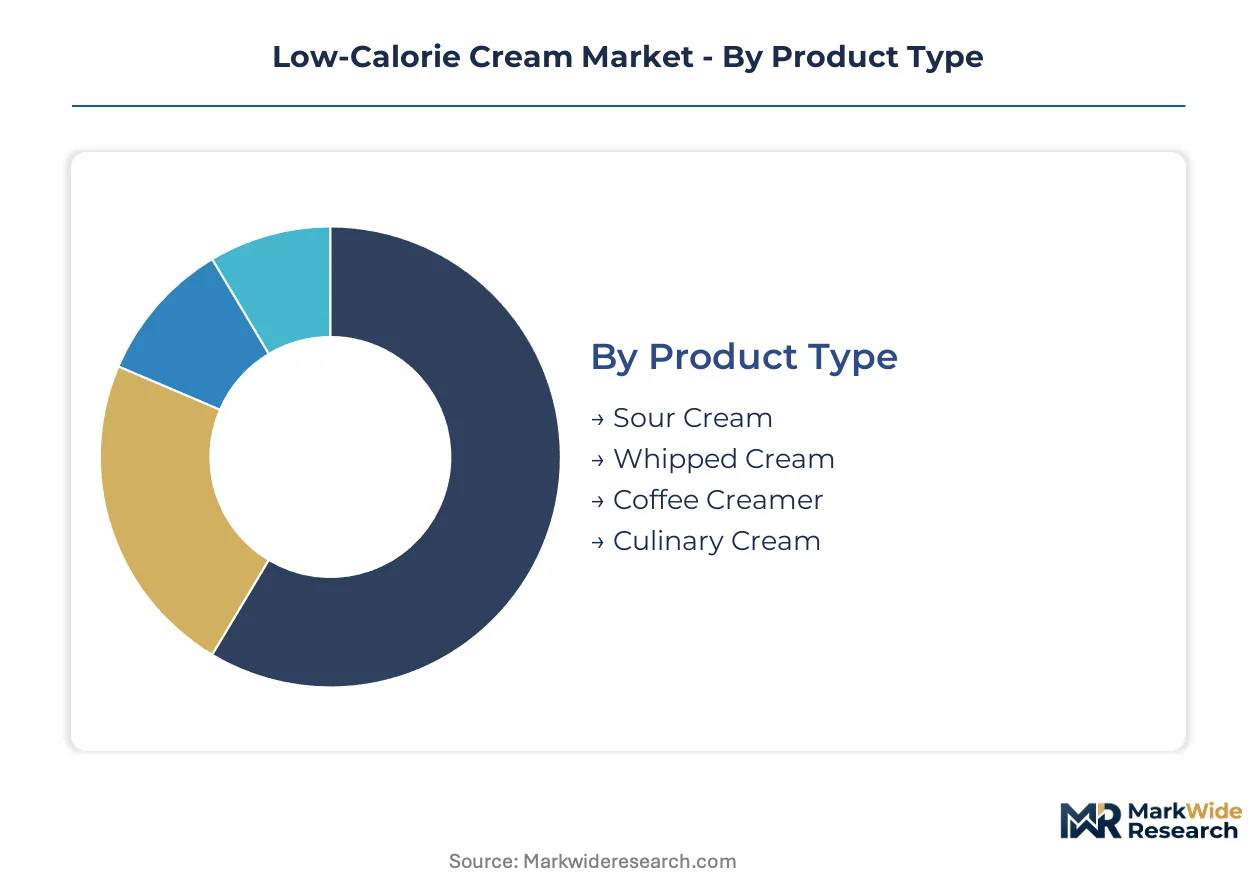
Low-calorie cream manufacturers configure production lines around distinct consumption occasions and procurement patterns. Segment boundaries determine formulation priorities, shelf-life engineering, and margin structures across the value chain.
Product Type:
Reformulation cycles accelerate as brands replace legacy full-fat portfolios with reduced-calorie alternatives that preserve functional performance in target applications.
- Coffee Creamer:Emulsions stabilized with fat-mimetic hydrocolloids deliver creamy mouthfeel at under 10 grams fat per serving. Specialty coffee chains in the United States standardize these formulations for beverage consistency across outlets.
- Culinary Cream:Reduced-fat dairy bases for recipe-standardized menus require heat-stable emulsion structures. Food service chains negotiate bulk procurement contracts specifying viscosity tolerances and scorch resistance.
- Sour Cream:Cultured low-fat dairy with controlled fermentation profiles maintains tang and texture for topping applications. Reformulation focuses on microbial strain selection to compensate for reduced fat solids.
- Whipped Cream:Aerosol and frozen formats rely on precision lipid structuring and nitrous oxide propellant systems. Aeration stability challenges dominate R&D investment for this segment.
Volume placements concentrate in Coffee Creamer; the faster expansion belongs to Culinary Cream.
End User:
Procurement authority and technical specifications diverge sharply between fragmented household demand and concentrated institutional buyers.
- Food Services:Restaurant chains and institutional kitchens drive bulk volume through recipe-standardized contracts. Procurement teams specify fat content, viscosity, and portion-control compatibility.
- Food Manufacturers:Ingredient buyers integrate low-calorie cream into processed food formulations requiring controlled caloric contribution and freeze-thaw stability.
- Households:Individual consumers purchase through retail channels, with trial behavior favoring smaller formats and clean-label positioning.
- Retailers:Private-label programs and shelf-space negotiations shape manufacturer portfolio breadth and promotional calendar intensity.
Food Services commands the largest contract values; Food Manufacturers show the steepest expansion trajectory as ingredient substitution accelerates.
Packaging Type:
Format engineering responds to diverging priorities: food service demands dispensing efficiency while households favor convenience and waste reduction.
- Pouches:Single-serve flexible packaging aligns with quick-service restaurant portion control and household trial behavior. Material science investments target barrier properties for extended shelf life.
- Tubs:Multi-serve rigid containers dominate retail dairy cases and back-of-house food service storage. Format loyalty persists among established brands with refrigerated distribution infrastructure.
- Cartons:Aseptic brick packs enable ambient distribution for extended supply chains. Capabilities concentrate among manufacturers with Tetra Pak or equivalent filling line partnerships.
- Sachets:Individual powder or liquid portions serve travel, hospitality, and institutional feeding channels. Unit economics challenge profitability at small scale.
Tubs retain the highest absolute volume; Pouches are climbing the fastest as single-serve adoption spreads.
Distribution Channel:
Channel selection determines margin capture, brand control, and consumer data access across diverging retail formats.
- Supermarkets:Mass-market retailers anchor volume through promotional calendars and private-label competition. Slotting fees and trade spend requirements compress net margins for branded entrants.
- Online Stores:Direct-to-consumer and marketplace platforms enable subscription replenishment models. Cold-chain logistics investments separate viable entrants from commodity competitors.
- Specialty Stores:Natural and gourmet retailers command premium positioning for organic and clean-label formulations. Assortment depth favors niche brands over mass-market portfolios.
- Convenience Stores:Grab-and-go occasions drive single-serve and extended-shelf-life formats. Distribution economics favor ambient-stable products over refrigerated alternatives.
Supermarkets maintain dominant volume share; Online Stores are gaining share fastest as subscription models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in North American and European dairy heartlands while consumption spreads across urbanized markets with specialty coffee penetration. The United States generates the largest absolute demand through quick-service restaurant chains and household retail channels. Export-oriented manufacturers navigate divergent regulatory frameworks that reshape formulation specifications by destination.
United States
Specialty coffee chains and quick-service restaurants drive bulk procurement of pouch-packaged single-serve formats. FDA nutritional labeling reforms mandate precise caloric disclosure and restrict "natural" claim thresholds, forcing continuous reformulation cycles. Chicago and Minneapolis-St. Paul anchor dairy processing clusters where membrane filtration capacity expansion serves both domestic and export demand.
Germany
Food service distributors and industrial ingredient buyers sustain demand for heat-stable culinary cream variants. EFSA health claim regulations under EU framework restrict reduced-fat positioning language, compelling clinical evidence packages for compliant formulations. Bavaria's dairy processing corridor concentrates ultrafiltration infrastructure serving Central European markets.
France
Traditional dairy culture intersects with clean-label demand from urban consumers seeking reduced-calorie alternatives without synthetic additives. ANSM and DGCCRF enforcement of EU food law shapes permissible formulation claims and organic certification pathways. The Brittany dairy basin hosts specialized facilities producing export-compliant low-fat emulsions for Middle Eastern and Asian markets.
United Kingdom
Coffee shop proliferation and meal-kit subscription services expand addressable channels beyond conventional retail. Post-Brexit divergence from EU labeling standards creates dual compliance burdens for manufacturers serving both markets. The West Midlands and Yorkshire processing zones concentrate aseptic filling capacity for ambient-distribution cream alternatives.
Japan
Convenience store chains and automated vending networks create unique single-serve demand patterns distinct from Western markets. METI standards on food labeling and functional claims govern permissible health-related positioning for reduced-fat products. The Kanto region around Tokyo hosts formulation R&D facilities adapting European membrane technologies to local taste preferences.
Low-Calorie Cream Market Competitive Landscape
Capital-heavy dairy processors compete with asset-light brand licensors and private-label specialists for shelf positioning and food service contracts. Market structure shows moderate consolidation at the production tier alongside fragmentation among niche plant-based entrants and regional co-operatives. Three archetypes dominate: diversified multinational food conglomerates with refrigerated distribution infrastructure, specialized dairy cooperatives with captive milk supply, and venture-backed alternative protein startups leveraging precision fermentation. Competitive intensity manifests through M&A activity targeting regional brands and strategic partnerships locking coffee chain dispensing equipment slots.
Within the multinational conglomerate tier, Kraft Heinz Company and Danone occupy positions exemplifying divergent strategic postures—one leveraging mass-market retail shelf dominance, the other advancing plant-based formulation specialization. Nestlé represents the integrated nutrition portfolio approach spanning dairy and non-dairy alternatives. These three anchors illustrate how scale, supply chain control, and R&D allocation determine competitive viability across diverging consumer preference vectors.
| Leading Market Players |
|---|
| Kraft Heinz Company |
| Arla Foods amba |
| Lactalis Group |
| Philadelphia Cream Cheese |
| Kite Hill |
| Miyoko's Creamery |
| Danone |
| Nestlé |
| Dairy Farmers of America |
| Others |
Value Network & Pricing Analysis
Ultrafiltration membrane technology maturation is compressing unit production costs for reduced-fat dairy emulsions while simultaneously concentrating processing capacity among manufacturers with capital-intensive membrane infrastructure. This dual effect reshapes pricing power dynamics between commodity dairy processors and specialized low-calorie formulation specialists.
Pricing Analysis
Margin tightening in standard-grade culinary cream traces to guar gum and locust bean supply volatility from India and Pakistan destabilizing fat-mimetic stabilization costs. Three-tier pricing structure across premium organic, standard clean-label, and economy conventional levels separates USDA-certified products from mass-market alternatives. Cost-down pressure on pouch-packaged single-serve formats accelerates because quick-service restaurant chains prioritize dispensing consistency over per-ounce optimization. Food service procurement teams show lowest price sensitivity due to recipe-standardized contract specifications, while household retail buyers demonstrate highest elasticity driven by private-label substitution.
Supply Chain Analysis
Single-source vulnerability sits with Indian and Pakistani guar gum suppliers who anchor global hydrocolloid feedstock for fat-mimetic systems. Raw material dependencies extend to microbial fermentation-derived proteins from precision fermentation facilities and dairy solids from North American and European cooperative networks. Tariff exposure on processed dairy imports into Asian markets threatens margin structures for export-oriented manufacturers. Distribution runs through temperature-controlled logistics networks linking Midwest dairy processing clusters to quick-service restaurant distribution centers and retail refrigerated cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive supply of membrane filtration capacity and precision fermentation protein output determines margin defense against oat milk substitution pressure.
For Market Incumbents: Anticipate barista-grade oat milk capture of coffeehouse dispensing slots by locking multi-year equipment partnerships with specialty coffee chains. Secure backward integration into microbial fermentation protein supply through strategic ingredient supplier alliances. Invest in USDA National Organic Program certification pipelines to defend premium positioning against clean-label entrants.
For New Entrants and Emerging Players: The gap between premium organic and economy conventional pricing tiers creates white-space opportunity for mid-market plant-based formulations with dairy-comparable functionality. Target food service bulk procurement contracts for recipe-standardized culinary cream as the most penetrable volume pool outside retail saturation. Pursue direct-to-consumer subscription replenishment platforms as the primary go-to-market angle bypassing slotting fee barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified multinational food conglomerates seeking refrigerated distribution infrastructure and coffee chain dispensing relationships. Long-term viability hinges on formulation portfolios spanning both dairy and precision fermentation-derived alternatives. Watch EFSA health claim enforcement stringency as the signal indicating which European-export-capable manufacturers will secure shelf access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Protein Integration | Microbial biomass facilities supply functional milk proteins minus lactose load for next-generation formulations. |
| Single-Serve Pouch Format Expansion | Quick-service restaurant portion control specifications drive fastest-growing packaging segment adoption. |
| USDA Organic Certification Pipeline Investment | Eighteen-to-twenty-four-month compliance timelines reward early entrants with clean-label shelf positioning. |
| Food Service Bulk Procurement Contracting | Recipe-standardized culinary cream agreements unlock underpenetrated volume outside retail channels. |
| Membrane Filtration Capacity Expansion | Ultrafiltration infrastructure in Chicago and Minneapolis-St. Paul clusters serves domestic and export demand. |
Research Methodology
Document review covered FDA nutritional labeling guidance, USDA National Organic Program standards, EFSA health claim regulations, and specialty coffee chain procurement specifications, complemented by interviews with dairy processing plant managers, food service category buyers, membrane filtration technology suppliers, and precision fermentation ingredient executives. Secondary validation drew from customs trade data on hydrocolloid imports, refrigerated distribution capacity reports, and quick-service restaurant supply chain disclosures. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, packaging format, and distribution channel dimensions.
Cross-referencing historical capacity expansion patterns against expert panel input on formulation technology adoption shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, packaging format, and distribution channel, with additional granularity on organic certification status and regional regulatory compliance tier. CAGRs were derived from trend extrapolation adjusted for technology cost curve trajectories and substitution elasticity estimates. Forecast inputs incorporated membrane filtration yield improvements and precision fermentation protein scale-up timelines.
Underlying measurement precision varies by segment; coffee creamer and food service procurement carry tighter precision than emerging precision fermentation-derived alternatives. Forecasts reflect documented assumptions on regulatory enforcement continuity and specialty coffee chain expansion trajectories, with oat milk substitution velocity and hydrocolloid supply disruption representing primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Cultured Dairy Blends Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Germany Dairy Alternatives Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Cashew Milk Market
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
Plant Milk Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market