
 Infant Formula Milk Powder with A2 Beta-Casein Market | 2026-2036
Infant Formula Milk Powder with A2 Beta-Casein Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Formula Milk Powder with A2 Beta-Casein Market Insights
Health-conscious millennial parents is redrawing the buyer landscape for A2 beta-casein infant formula, displacing traditional price-sensitive procurement. The a2 Milk Company leverages its proprietary A2 protein sourcing and herd certification to dominate premium shelf positioning. Nestlé S.A. sustains global manufacturing scale across multiple regulatory jurisdictions. Danone S.A. specializes in medical and specialty nutrition extensions that anchor its pediatric portfolio.
Infant formula milk powder with A2 beta-casein designates a dairy-based nutritional product manufactured exclusively from cow milk containing the A2 variant of beta-casein protein, excluding the A1 variant through selective herd screening and chromatographic separation processes. The formulation delivers infant nutrition with purported digestive tolerance advantages over conventional A1/A2 mixed protein sources. Powdered Formula commands the largest volume share due to extended shelf stability and lower logistics costs, while Organic Formula captures disproportionate margin pools from premium-positioned urban consumers. Target Age Group segmentation shows Toddlers emerging as the fastest-expanding category as extended breastfeeding durations shift weaning timelines later.
FDA infant formula enforcement standards, China's NMPA registration requirements under GB 10765, and EFSA novel food evaluations collectively govern market access and compositional claims across major consumption zones. These frameworks elevate compliance costs for new entrants while rewarding incumbents with established dossier portfolios. Stakeholders must monitor evolving protein labeling thresholds and cross-border e-commerce duty structures to preserve competitive positioning.
Market Dynamics
Selective herd screening and chromatographic separation technologies are concentrating A2 protein sourcing capabilities among operators with capital-intensive dairy infrastructure, compressing competitive access to certified milk supplies.
Growth Catalysts
- China's NMPA registration pathway:GB 10765 compliance requirements create defensible moats for dossier-ready suppliers while filtering subscale competitors from premium shelf access.
- Extended breastfeeding durations:Toddlers segment expansion stretches formula consumption windows past traditional twelve-month boundaries, enlarging addressable volume pools.
- Cross-border e-commerce duty structures:Favorable tariff treatment on direct-to-consumer infant nutrition shipments accelerates brand penetration without conventional retail slotting investments.
Market Restraints
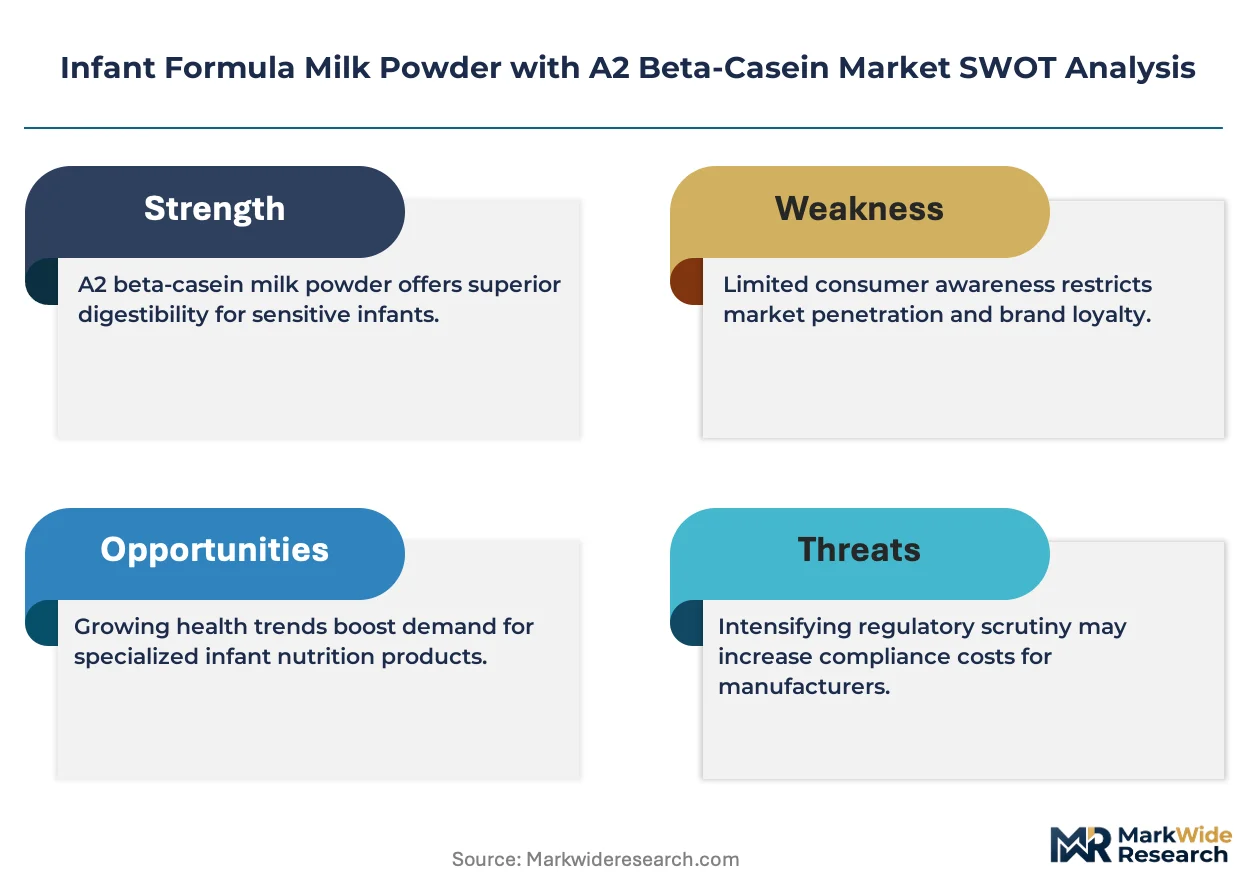
- A2-certified dairy herd scarcity:Genetic testing and selective breeding programs constrain raw milk availability, amplifying input cost volatility for non-integrated processors.
- EFSA novel food evaluation timelines:European protein variant authorization protocols extend market entry lead times, advantaging incumbents with established safety dossiers.
- Plant-based protein substitutes:Oat and pea-derived infant nutrition alternatives capture allergen-sensitive households, fragmenting premium dairy protein demand.
Strategic Opportunities
- India's FSSAI pediatric nutrition standards:Emerging middle-class formula adoption in tier-two cities opens white-space expansion beyond saturated coastal metros.
- Medical and specialty nutrition convergence:Metabolic disorder and cow-milk protein allergy formulations command reimbursement-adjacent pricing premiums.
- Subscription direct-to-consumer channels:Automated replenishment platforms bypass traditional pharmacy and grocery intermediaries, capturing lifetime value through data-driven personalization.
Industry Challenges
- A2 protein assay certification complexity:Chromatographic verification protocols and third-party laboratory accreditation extend batch-release timelines, constraining inventory velocity.
- Legacy ERP integration with traceability systems:Herd-to-shelf blockchain and genomic tracking platforms require substantial middleware development, complicating digital transformation roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Formula Milk Powder with A2 Beta-Casein Market |
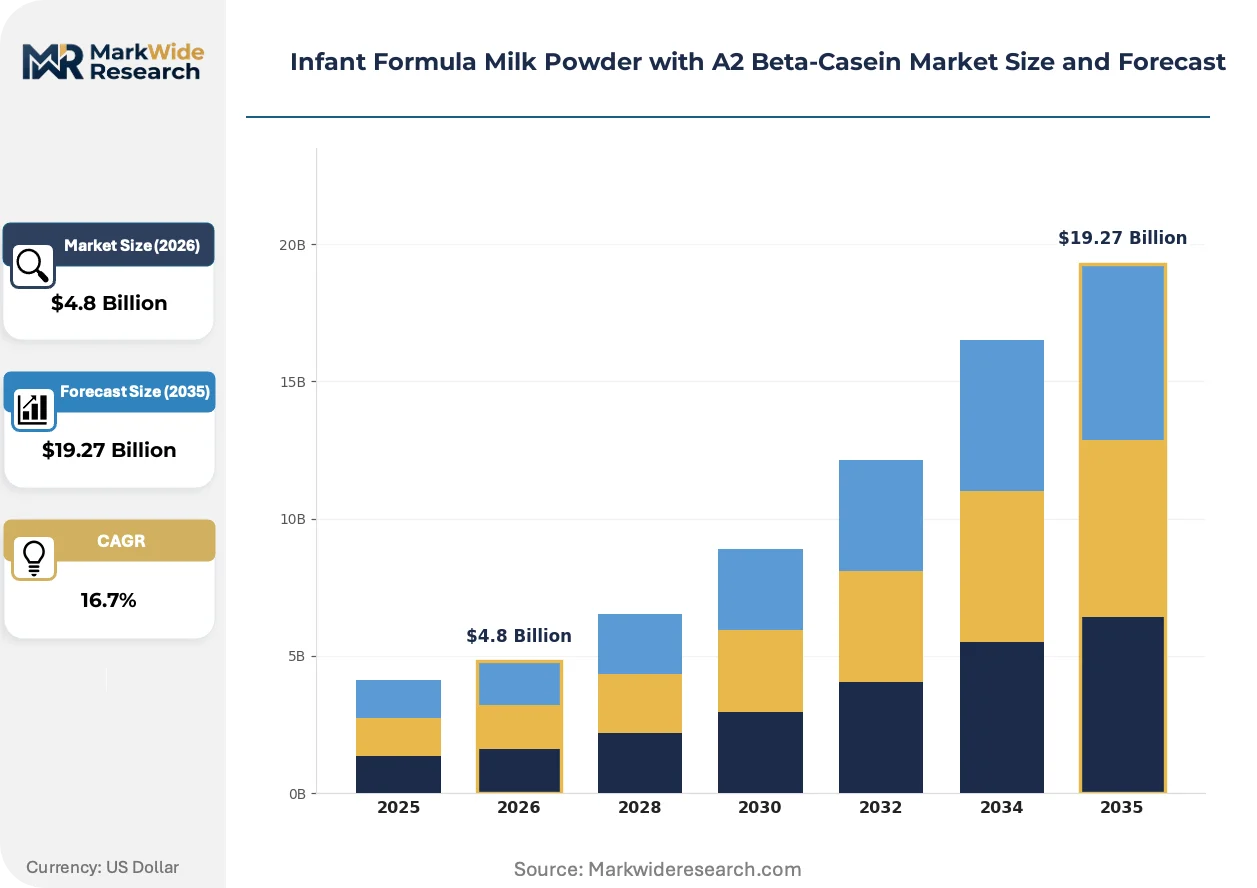
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Formula, Liquid Concentrate, Ready-to-Feed, Organic Formula Ingredient Type: A2 Milk, Lactose-Free, Plant-Based, Fortified Target Age Group: Newborns, Infants, Toddlers, Preterm Packaging Type: Tin Packaging, Pouches, Bottles, Single-Serve Packs |
| Companies Covered | The a2 Milk Company, Nestlé S.A., Danone S.A., Abbott Laboratories, Reckitt Benckiser Group, Synlait Milk, Arla Foods amba, Bubs Australia Limited, Bellamy’s Organic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Formula Milk Powder with A2 Beta-Casein Market Trends and Innovations
Protein identification and separation technologies are compressing production economics while regulatory labeling precision and parental purchasing behaviors reshape competitive differentiation mechanisms.
Chromatographic beta-casein separation equipment is miniaturizing from industrial-scale installations to modular processing units suitable for mid-tier dairy cooperatives. Regional processors in Australia and New Zealand are adopting these compact systems to capture A2 protein premiums without consolidated plant investments. This diffusion pattern is fragmenting previously concentrated A2 milk supply control.
China's SAMR is tightening protein variant labeling thresholds under revised GB standards, mandating quantitative A1/A2 disclosure rather than binary presence claims. Formulators must revalidate analytical methods and packaging declarations, elevating compliance expenditures. Premium-positioned suppliers with in-house testing infrastructure are absorbing these costs more efficiently than contract manufacturers.
Parental information-seeking behavior is shifting from pediatrician-directed recommendations toward peer-validated digital channels, compressing traditional professional influence cycles. Health-conscious millennial cohorts in Shanghai and Sydney are prioritizing third-party certification seals and transparent sourcing documentation over legacy brand equity. This credential-driven preference rotation is elevating niche entrants with robust traceability narratives.
Infant Formula Milk Powder with A2 Beta-Casein Market Segmentation
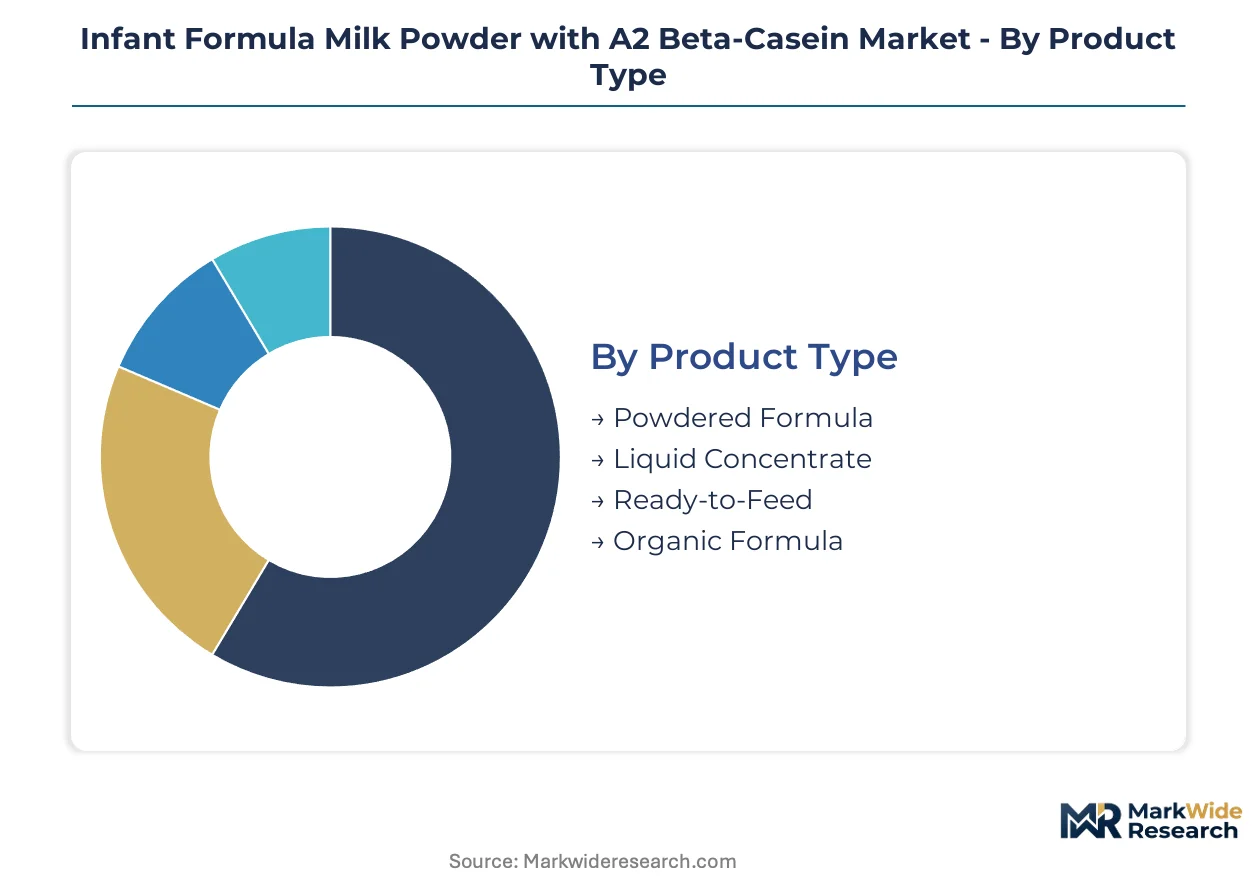
A2 beta-casein infant formula segments by physical form, protein sourcing, developmental stage, and delivery format. Each dimension carries distinct regulatory pathways and margin structures that reshape competitive positioning across export corridors and domestic markets.
Product Type:
Powdered formulations dominate cross-border e-commerce channels, while liquid variants concentrate in pharmacy retail networks.
- Powdered Formula:Dehydrated milk protein matrix with extended shelf stability enables bulk procurement and ocean freight economics. Demand clusters in China's tier-one cities through cross-border platforms, constrained by NMPA registration timelines for new entrants.
- Liquid Concentrate:Reconstitutable emulsion requiring refrigeration post-opening limits distribution radius to cold-chain capable retail networks. Australian pharmacy chains and Japanese convenience stores represent primary volume concentration.
- Ready-to-Feed:Sterile single-use packaging commands hospital discharge gift-set channels and travel-oriented convenience purchasing.
- Organic Formula:Certified A2 protein from organic pasture systems captures premium urban households in Shanghai and Sydney prioritizing sourcing transparency.
Powdered Formula holds the largest share; momentum sits with Organic Formula.
Ingredient Type:
Cost tiers separate chromatographically verified A2 protein from modified carbohydrate and alternative protein formulations.
- A2 Milk:Beta-casein variant isolated through genomic herd screening and chromatographic separation delivers the core value proposition. Supply scarcity concentrates in New Zealand's Waikato region and Australia's Gippsland corridor.
- Lactose-Free:Enzymatically hydrolyzed carbohydrate matrix serves diagnosed lactose intolerance cases through pediatric specialty channels.
- Plant-Based:Oat and pea protein isolates fragment allergen-sensitive demand away from dairy protein systems.
- Fortified:DHA, ARA, and prebiotic supplementation targets neurodevelopment positioning in competitive shelf sets.
A2 Milk holds the largest share; steepest expansion trajectory belongs to Plant-Based.
Target Age Group:
Volume concentration shifts as extended breastfeeding patterns delay weaning milestones across developed Asian markets.
- Toddlers:12-36 month nutritional requirements now represent the steepest volume expansion as maternal breastfeeding duration extends past traditional twelve-month boundaries in China's coastal provinces.
- Newborns:First-week colostrum transition products concentrate in hospital discharge protocols and maternity gift registries.
- Infants:Core 0-12 month formulation faces compressed volume pools from breastfeeding advocacy campaigns.
- Preterm:Fortified caloric density formulations command NICU-adjacent pricing through medical nutrition reimbursement channels.
Infants holds the largest share; Toddlers is gaining share fastest.
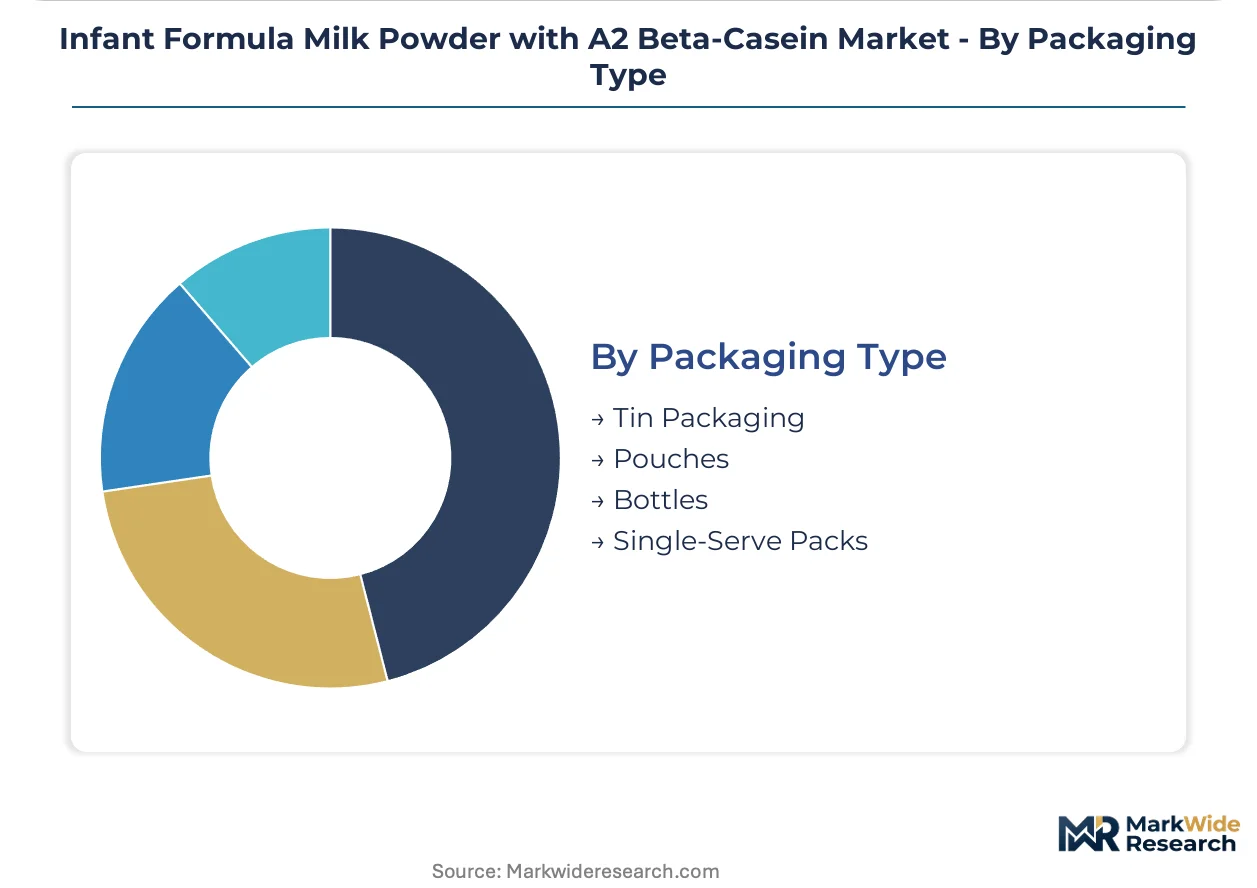
Packaging Type:
Format selection tracks channel economics from bulk tin retail to single-unit convenience purchasing.
- Tin Packaging:Metal canister with nitrogen flush and resealable lid dominates warehouse club and pharmacy bulk purchasing in Australia and China.
- Pouches:Flexible film portion packs enable trial-size sampling and travel convenience in Japanese drugstore channels.
- Bottles:Pre-sterilized ready-to-feed containers capture hospital discharge and on-the-go consumption occasions.
- Single-Serve Packs:Sachet formats reduce contamination risk and enable precise portion control for caregiver convenience.
Tin Packaging holds the largest share; Single-Serve Packs shows strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian dairy processors dominate export corridors into Chinese cross-border e-commerce channels, while New Zealand's Waikato region supplies chromatographically verified A2 protein to multinational formulators.
China
Shanghai and Beijing tier-one households drive premium pediatric nutrition procurement through cross-border platforms. NMPA registration under GB 10765 standards filters subscale competitors from pharmacy shelf access. Yangtze River Delta distribution hubs concentrate import clearing and cold-chain logistics for Australian and New Zealand origin products.
Australia
Gippsland dairy cooperatives supply A2-certified raw milk to domestic formulators and Chinese export contracts. TGA pharmaceutical manufacturing standards govern medical-grade formula production for NICU-adjacent channels. Melbourne and Sydney serve as headquarters for herd certification laboratories and chromatographic testing infrastructure.
New Zealand
Waikato region pasture systems host the world's densest concentration of A2-genotyped dairy herds. MPI dairy export certification requirements align with China's SAMR labeling mandates for protein variant disclosure. Auckland processing facilities integrate chromatographic separation equipment for regional cooperative networks.
United States
FDA infant formula enforcement discretion frameworks govern compositional claims and facility registration for A2 protein variants. California and New York metro health-conscious parent cohorts prioritize third-party certification seals over legacy brand equity. Domestic manufacturing scales across multiple regulatory jurisdictions serve pharmacy and grocery retail networks.
India
Mumbai and Delhi-NCR emerging middle-class households expand formula adoption beyond traditional breastfeeding patterns. FSSAI pediatric nutrition standards under development create white-space opportunities for dossier-ready international suppliers. Tier-two city pharmacy chains represent underpenetrated distribution infrastructure for premium protein variants.
Infant Formula Milk Powder with A2 Beta-Casein Market Competitive Landscape
Player mix skews toward integrated dairy processors with captive A2 herd certification and chromatographic separation capabilities. Market structure concentrates around operators with established NMPA dossiers and cross-border e-commerce logistics infrastructure. Three archetypes dominate: proprietary protein sourcing specialists, global nutrition conglomerates with multi-jurisdictional manufacturing, and regional organic formulators with traceability narratives. Competitive moves center on herd acquisition strategies and direct-to-consumer subscription platform deployment.
Within the proprietary sourcing tier, The a2 Milk Company exemplifies single-variant protein specialization through genomic herd screening and brand equity built on digestive tolerance positioning. Nestlé S.A. and Danone S.A. anchor the global conglomerate archetype, occupying positions defined by manufacturing scale across FDA, EFSA, and NMPA jurisdictions rather than protein variant exclusivity. Synlait Milk represents the integrated processor model, sitting within supply chains that bridge New Zealand raw milk concentration with Asian brand-owner formulation requirements.
| Leading Market Players |
|---|
| The a2 Milk Company |
| Nestlé S.A. |
| Danone S.A. |
| Abbott Laboratories |
| Reckitt Benckiser Group |
| Synlait Milk |
| Arla Foods amba |
| Bubs Australia Limited |
| Bellamy's Organic |
| Others |
Pricing and Supply Chain Analysis
China's NMPA registration framework under GB 10765 standards gates both supply qualification and price differentiation simultaneously, filtering subscale competitors from premium shelf access while enabling dossier-ready suppliers to command certification-linked price premiums. Health-conscious millennial parents in Shanghai and Sydney translate third-party herd certification into willingness-to-pay differentials that compress margins for non-compliant operators.
Pricing Analysis
Chromatographic separation technology pricing gaps separate industrial-scale installations from emerging modular processing units suitable for mid-tier dairy cooperatives. Three-tier pricing structure across premium certified-organic, standard A2-verified, and economy A1/A2 blended levels tracks certification depth and sourcing transparency. Price differentiation hinges on genomic herd traceability documentation and third-party laboratory accreditation, with cost compression in the economy tier intensifying due to plant-based protein substitution. Pharmacy procurement managers in China's tier-one cities demonstrate lowest price sensitivity, while emerging middle-class households in India's tier-two cities drive volume at compressed margins.
Supply Chain Analysis
A2-certified dairy herd scarcity in New Zealand's Waikato region and Australia's Gippsland corridor concentrates raw material control among integrated processors with captive genomic screening programs. Chromatographic separation equipment, nitrogen-flush packaging materials, and cold-chain logistics infrastructure draw from specialized supplier networks with limited alternative sourcing. Single-source vulnerability runs through the New Zealand-Australia milk supply axis, where genetic testing backlogs extend batch-release timelines. Distribution runs through cross-border e-commerce platforms for Chinese market penetration and pharmacy retail networks for Australian domestic consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-border e-commerce platform economics are reshaping competitive entry patterns, as direct-to-consumer subscription infrastructure collapses traditional retail slotting barriers and enables data-driven personalization at scale.
For Market Incumbents: Fortify NMPA dossier portfolios through accelerated GB 10765 revalidation timelines as China's SAMR tightens protein variant labeling thresholds. Deepen upstream control over A2-genotyped herd supply through selective breeding program investments in New Zealand's Waikato region, insulating input cost volatility from non-integrated processors. Expand direct-to-consumer subscription platforms to capture lifetime value and bypass pharmacy intermediary margin extraction. For New Entrants and Emerging Players: India's FSSAI pediatric nutrition standards fast-track creates white-space expansion into Mumbai and Delhi-NCR tier-two pharmacy chains where premium protein variants remain underpenetrated. Target medical and specialty nutrition convergence segments—metabolic disorder and cow-milk protein allergy formulations—where reimbursement-adjacent pricing premiums reward clinical validation investments. Deploy automated replenishment platforms with traceability-native branding to differentiate from legacy equity-dependent competitors. For Investors and Strategic Acquirers: China's SAMR labeling mandate reshapes the acquisition landscape toward operators with in-house chromatographic testing infrastructure and established NMPA registration pathways. Mid-term viability over the coming decade centers on integrated processors bridging New Zealand raw milk concentration with Asian brand-owner formulation requirements. Monitor A2 protein assay certification complexity as an inflection indicator, where batch-release timeline extensions signal inventory velocity constraints that compress working capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Platform Deployment | Captures lifetime value through data-driven personalization while bypassing pharmacy intermediaries in Chinese tier-one cities. |
| Chromatographic Separation Capacity Expansion | Modular processing unit adoption fragments previously concentrated A2 milk supply control among mid-tier dairy cooperatives. |
| Genomic Herd Certification Program Investment | Selective breeding programs in New Zealand's Waikato region anchor raw material security for integrated processors. |
| Medical Nutrition Formulation Development | Metabolic disorder and cow-milk protein allergy variants command reimbursement-adjacent pricing premiums through pediatric specialty channels. |
| Cross-Border E-Commerce Logistics Infrastructure | Favorable tariff treatment on direct-to-consumer infant nutrition shipments accelerates brand penetration without conventional retail slotting investments. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain participant interviews anchors the qualitative findings in verifiable operational constraints. Primary fieldwork encompassed dairy cooperative managers, chromatographic equipment specialists, NMPA registration consultants, pharmacy category buyers, and cross-border platform operators. Secondary validation drew from China's SAMR labeling directives, New Zealand MPI export certifications, FDA infant formula enforcement discretion frameworks, Australian TGA pharmaceutical manufacturing standards, and trade flow documentation through Yangtze River Delta distribution hubs. Bottom-up volume modeling triangulated against top-down market sizing across ingredient type and target age group dimensions.
Sensitivity analysis around breastfeeding duration assumptions and cross-border e-commerce duty structure stability frames the projection uncertainty. The analytical framework segments by product type, ingredient sourcing, developmental stage, and packaging format across the modeling period, with CAGRs derived from historical volume trajectory analysis and regulatory pathway timing assessments. Herd certification penetration rates and chromatographic processing capacity expansion schedules constitute critical forecast inputs specific to A2 protein supply economics.
Underlying assumptions cover sustained NMPA registration pathway integrity and A2-certified dairy herd genetic testing throughput, with deviation risk concentrated in EFSA novel food evaluation timeline extensions and plant-based protein substitution acceleration. Practitioners should keep alternative scenarios live as China's SAMR labeling mandate implementation and India's FSSAI standard finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market
Baby Food and Infant Formula
GCC Baby Food and Infant Formula Market
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
South America Organic Baby Food Market
Baby Food and Infant Formula
Asia-Pacific Baby Food Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Pet Milk Replacement Products Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Infant Nutritional Premix Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Japan Baby Food and Infant Formula Market
Baby Food and Infant Formula
Global Oligosaccharides in Infant Nutrition Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Baby Formula Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
Canada Baby Food Market