
 5G in Defense Market | 2026-2036
5G in Defense Market Size, Share, and Industry Trends Forecast 2026-2036
5G in Defense Market Intelligence
Specialized radio-frequency engineering talent is bifurcating the vendor landscape as defense primes race to staff mmWave and software-defined radio teams. Ericsson sustains early traction through European NATO testbed partnerships, while Lockheed Martin anchors its position via classified programs integrating 5G with existing C4ISR infrastructure. Samsung Electronics competes aggressively in the Asia-Pacific defense corridor with hardened base station designs purpose-built for electromagnetic-contested environments.
5G in defense denotes the deployment of fifth-generation cellular infrastructure—operating across sub-6 GHz and mmWave bands with sub-millisecond latency—to enable secure, high-bandwidth military communications, autonomous system coordination, and real-time sensor fusion in contested operational theaters. Network slicing architectures allow commanders to partition bandwidth across classified and unclassified traffic streams on shared hardware. Beamforming and massive MIMO deployments dominate current procurement as forces prioritize directional resilience over omnidirectional broadcast patterns, while edge computing nodes at the tactical edge represent the fastest-growing technology segment as latency requirements tighten for drone swarm coordination and augmented-reality maintenance applications.
The U.S. Federal Communications Commission governs spectrum allocation for defense 5G trials, while NATO's Standardization Office shapes interoperability protocols that constrain non-aligned vendor participation in allied networks. The U.S. Department of Defense's Open RAN mandates and EU defense fund guidelines on strategic autonomy are forcing procurement officers to balance supply chain security against performance benchmarks. Stakeholders must monitor how emerging electromagnetic spectrum denial tactics reshape hardware hardening requirements and whether allied spectrum harmonization agreements expand addressable contract pools beyond national silos.
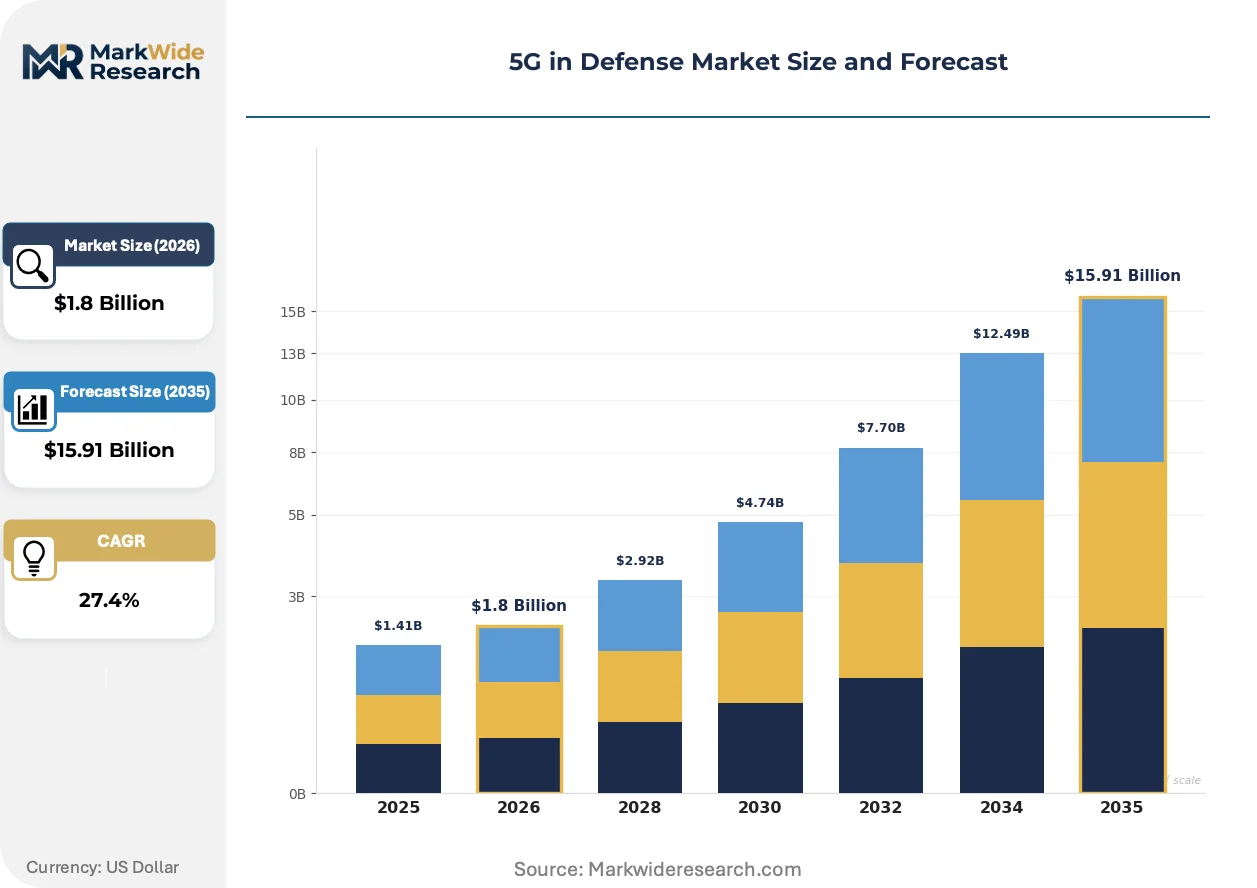
Market Dynamics
Open RAN mandates from the U.S. Department of Defense are forcing defense primes to re-architect supply chains around interoperable radio access networks, compressing vendor consolidation timelines while fragmenting hardware procurement across qualified suppliers.
Growth Catalysts
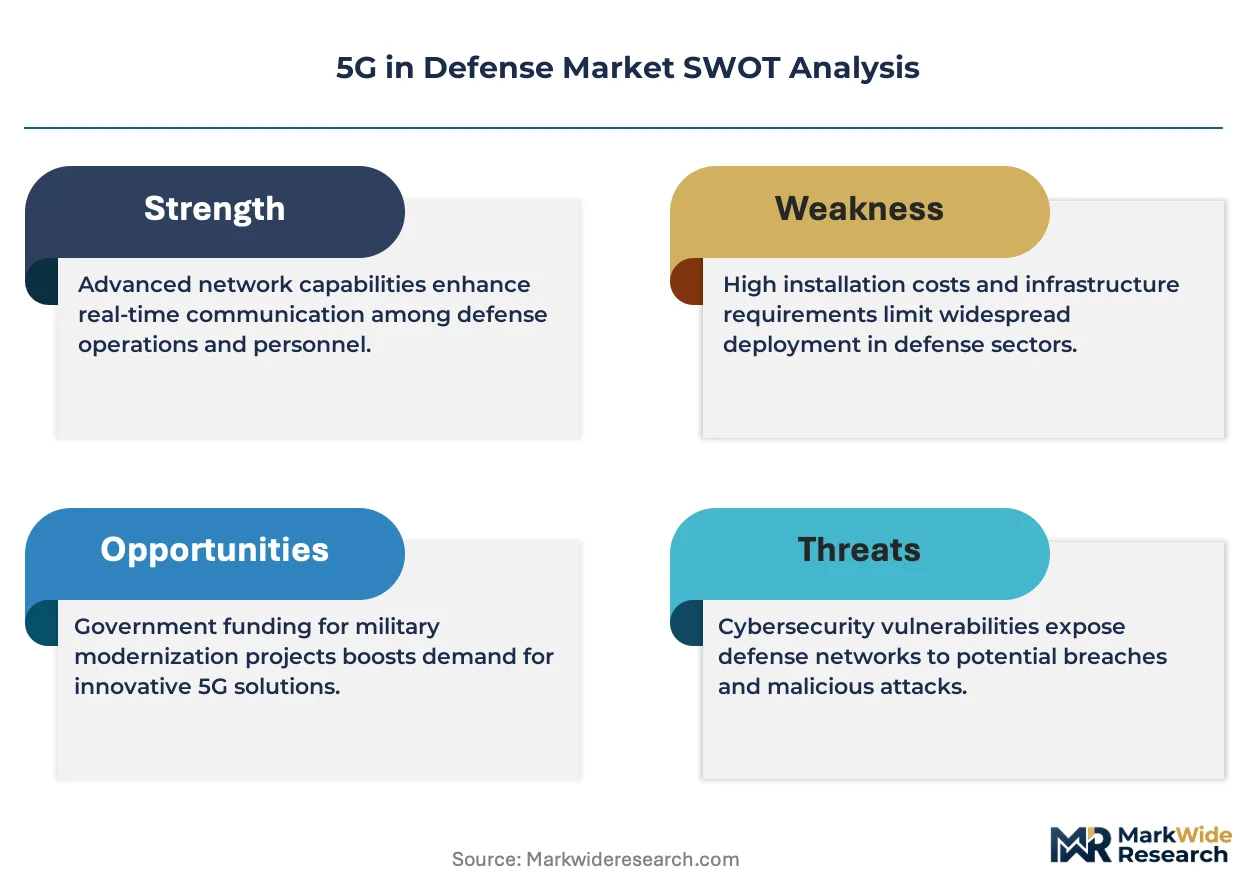
- Network slicing architectures:NATO's digital transformation directives require partitioned bandwidth for classified and unclassified traffic streams on shared tactical hardware, accelerating validation of multi-tenant base station designs.
- Electromagnetic-contested environment hardening:Military end users in allied nations demand beamforming and massive MIMO deployments with directional resilience over omnidirectional broadcast patterns for battlefield survivability.
- mmWave spectrum allocation:The U.S. Federal Communications Commission's defense trial authorizations in sub-6 GHz and millimeter-wave bands enable sub-millisecond latency for drone swarm coordination and augmented-reality maintenance.
Market Restraints
- Specialized RF engineering scarcity:Defense primes face acute shortages of software-defined radio and mmWave talent, inflating recruitment costs and stretching program timelines.
- Spectrum harmonization friction:Divergent national allocation frameworks between NATO member states fragment addressable contract pools beyond national procurement silos.
- Electromagnetic spectrum denial threats:Adversarial jamming capabilities force redundant hardware hardening that adds weight, power consumption, and thermal management complexity to field-deployable units.
Strategic Opportunities
- Edge computing node deployment:Latency requirements for autonomous system coordination at the tactical edge represent uncontracted white space for hardened micro-datacenter integration.
- EU defense fund strategic autonomy guidelines:Procurement officers must balance supply chain security against performance benchmarks, creating entry points for non-U.S. subsystem vendors.
- Mesh network architecture validation:Pentagon testbeds at Marine Corps bases and Army proving grounds are stress-testing self-healing topologies for expeditionary force scalability.
Industry Challenges
- C4ISR integration complexity:Existing command, control, communications, computers, intelligence, surveillance, and reconnaissance infrastructure requires costly middleware development for 5G protocol translation.
- Vendor qualification timeline compression:NATO's Standardization Office interoperability protocols constrain non-aligned supplier participation while allied forces demand accelerated fielding schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G in Defense Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $15.91 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Surveillance, Communication, Navigation, Remote Control Technology: MIMO, Beamforming, Network Slicing, Edge Computing End User: Military, Defense Contractors, Government Agencies, Security Firms Deployment: On-Premises, Cloud-Based, Hybrid, Tactical Networks |
| Companies Covered | Ericsson, Huawei, Nokia, Samsung Electronics, NEC, Thales Group, L3Harris Technologies, Raytheon Technologies, Lockheed Martin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G in Defense Market Strategic Shifts & Innovations
Defense communications infrastructure is undergoing fundamental restructuring as electromagnetic contested environments and latency-critical applications force hardware architects toward modular, software-defined architectures with hardened physical layers.
Software-defined radio platforms with reprogrammable waveform processing are bifurcating the traditional defense electronics supply chain. Tier-one integrators now maintain captive mmWave design teams while outsourcing baseband processing to specialized semiconductor foundries. This technology shift is compressing procurement cycles for tactical radios while fragmenting subsystem vendor relationships across allied defense industrial bases.
The U.S. Federal Communications Commission's spectrum allocation frameworks for defense trials are tightening hardware certification requirements. Equipment vendors must now demonstrate coexistence with commercial 5G networks in shared bands, adding electromagnetic compatibility testing burdens. Marine Corps expeditionary units and Army maneuver elements face extended fielding schedules as dual-use spectrum coordination protocols undergo revision.
Defense procurement officers are unbundling network infrastructure from long-term service contracts, compressing vendor revenue recognition toward hardware delivery milestones. Systems integrators respond with modular base station designs supporting rapid component swap-out rather than comprehensive platform replacement. This behavioral shift concentrates in United States Pentagon testbeds where program managers prioritize operational technology refresh cycles over multi-decade platform commitments.
5G in Defense Market Segmentation
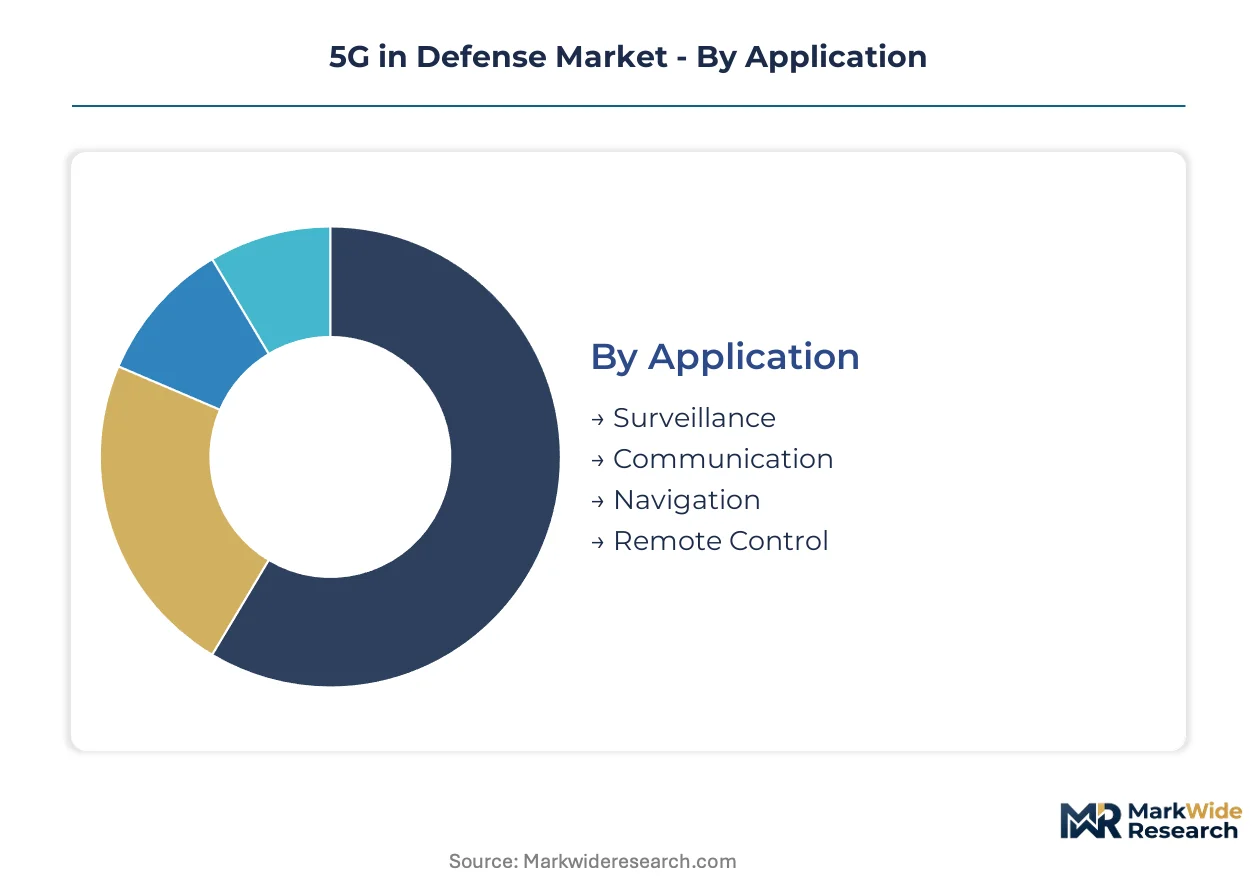
Defense procurement officers slice 5G infrastructure investments across mission-critical applications, hardened technology layers, and operational deployment modes. Each segmentation axis reveals distinct vendor qualification hurdles, spectrum allocation requirements, and integration complexity with legacy C4ISR systems.
Application:
Surveillance platforms face acute substitution pressure from legacy satellite and airborne relay networks, forcing 5G proponents to demonstrate latency advantages in contested electromagnetic environments.
- Surveillance:Real-time video streaming from distributed sensor arrays demands sub-10 millisecond latency for actionable intelligence dissemination. Pentagon testbeds at Army proving grounds validate mesh architectures for border monitoring and forward operating base perimeter security, with procurement concentrating in United States expeditionary force modernization programs.
- Communication:Secure voice and data transmission across classified and unclassified traffic streams leverages network slicing for multi-tenant base station designs. NATO digital transformation directives accelerate validation of partitioned bandwidth architectures, with demand clustering in allied member state tactical network upgrades.
- Navigation:Precision positioning services augment GPS-denied environments through 5G-based terrestrial triangulation.
- Remote Control:Teleoperation of unmanned ground and aerial vehicles requires hardened low-latency links for beyond-line-of-sight maneuvering.
Communication retains volume leadership; Surveillance holds the steepest expansion curve.
Technology:
Cost tier stratification separates proven sub-6 GHz implementations from emerging millimeter-wave investments demanding specialized RF engineering talent.
- MIMO:Massive multiple-input multiple-output arrays with 64+ antenna elements enable spatial multiplexing for high-throughput tactical backhaul. Marine Corps expeditionary units prioritize directional resilience over omnidirectional broadcast patterns, driving procurement toward hardened massive MIMO base stations for electromagnetic-contested theaters.
- Beamforming:Dynamic beam steering concentrates radiated energy toward intended receivers while suppressing interference. Army maneuver elements validate adaptive antenna systems for drone swarm coordination, with testbed activity concentrating at Marine Corps bases.
- Network Slicing:Virtualized network partitions isolate classified traffic on shared hardware infrastructure.
- Edge Computing:Hardened micro-datacenters at the tactical edge reduce backhaul dependency for autonomous system coordination.
MIMO dominates current procurement volumes; Edge Computing is climbing the fastest.
End User:
Customer type determines security clearance thresholds, with military end users imposing the most stringent supply chain vetting.
- Military:Armed forces across NATO member states scale procurement of tactical 5G networks for battlefield connectivity, with Open RAN mandates from the U.S. Department of Defense compressing vendor qualification timelines.
- Defense Contractors:Systems integrators require interoperable radio access network components for platform integration programs.
- Government Agencies:Civilian defense and homeland security organizations demand hardened infrastructure for critical infrastructure protection.
- Security Firms:Private sector contractors supporting military operations require commercial-grade 5G with military hardening specifications.
Military end users anchor procurement volumes; Defense Contractors are gaining share fastest through subsystem specialization.
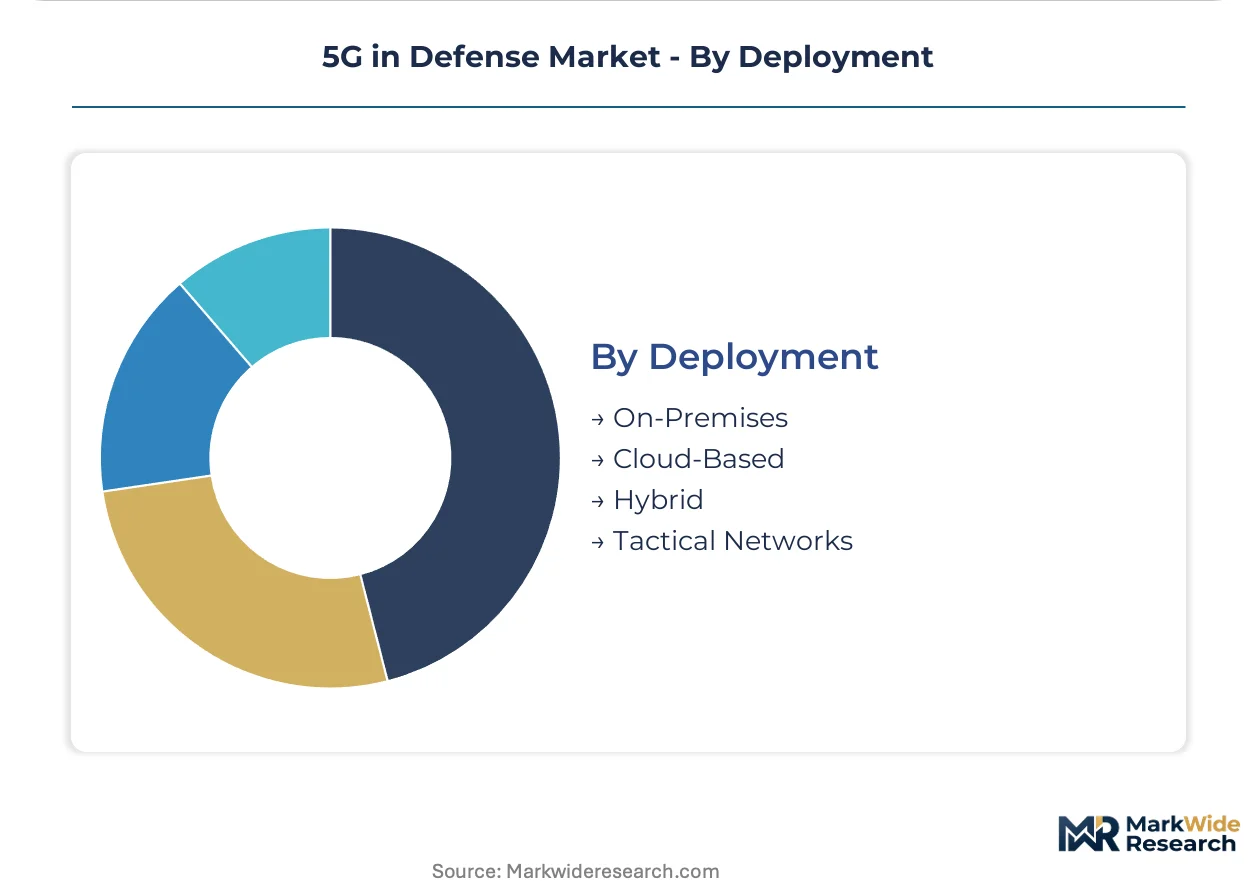
Deployment:
Supply concentration in tactical hardware vendors shapes deployment architecture choices, with expeditionary forces prioritizing rapid fielding over fixed infrastructure.
- Tactical Networks:Self-healing mesh topologies enable expeditionary force scalability without fixed infrastructure dependency. Pentagon testbeds stress-test autonomous reconfiguration for contested logistics environments, with validation activity concentrating at Army proving grounds and Marine Corps bases.
- On-Premises:Dedicated base station deployments serve permanent installations with controlled spectrum environments.
- Cloud-Based:Virtualized core network functions reduce hardware footprint for rear-echelon command centers.
- Hybrid:Combined cloud-edge architectures balance latency requirements with computational offload flexibility.
Tactical Networks command the steepest investment trajectory; On-Premises retains installed base dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Federal Communications Commission anchors defense 5G spectrum allocation through trial authorizations in sub-6 GHz and millimeter-wave bands, with Pentagon testbeds validating mesh architectures for expeditionary force modernization across allied nations.
United States
Pentagon procurement concentrates tactical 5G validation at Marine Corps bases and Army proving grounds for battlefield connectivity. The Department of Defense's Open RAN mandates compress vendor qualification timelines while fragmenting hardware procurement across qualified suppliers. Marine Corps expeditionary units in California prioritize hardened massive MIMO base stations for electromagnetic-contested theaters.
Germany
NATO's Standardization Office in Brussels shapes interoperability protocols that constrain non-aligned vendor participation in allied networks. The EU defense fund guidelines on strategic autonomy force procurement officers to balance supply chain security against performance benchmarks. Industrial activity clusters in Bavaria and Baden-Württemberg where defense primes maintain captive mmWave design teams.
United Kingdom
UK armed forces scale procurement of tactical networks for forward operating base perimeter security and border monitoring applications. The Ministry of Defence aligns with NATO digital transformation directives requiring partitioned bandwidth for classified traffic streams. Testbed activity concentrates in Wiltshire and surrounding defense corridors for C4ISR integration programs.
Japan
The Ministry of Economy, Trade and Industry governs spectrum coordination for dual-use defense-commercial 5G deployments. METI frameworks tighten hardware certification requirements for electromagnetic compatibility with commercial networks in shared bands. Industrial concentration in the Kanto region around Tokyo supports specialized radio-frequency engineering talent pools for software-defined radio development.
South Korea
Samsung Electronics competes aggressively in the Asia-Pacific defense corridor with hardened base station designs purpose-built for electromagnetic-contested environments. The national spectrum regulator allocates trial bands for military latency-critical applications including drone swarm coordination. Defense procurement activity concentrates in the Seoul Capital Area for autonomous system integration programs.
5G in Defense Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the defense 5G vendor landscape. The market structure fragments between telecommunications equipment specialists and aerospace-defense primes with C4ISR integration capabilities. Three strategic archetypes dominate: European infrastructure vendors with NATO testbed partnerships, Asian electronics conglomerates with hardened hardware specialization, and U.S. defense primes with classified program access. Competitive moves concentrate on Open RAN interoperability certification and mmWave engineering talent acquisition.
Within the telecommunications infrastructure tier, Ericsson and Nokia represent European vendors with established NATO relationships, while Samsung Electronics anchors the Asia-Pacific specialization vector. These three exemplify divergent geographic anchoring strategies—Ericsson and Nokia sit within European defense industrial base networks, whereas Samsung occupies a position bridging commercial scale with military hardening requirements. Lockheed Martin represents the U.S. defense prime archetype integrating 5G with existing command infrastructure through classified development channels.
| Leading Market Players |
|---|
| Ericsson |
| Huawei |
| Nokia |
| Samsung Electronics |
| NEC |
| Thales Group |
| L3Harris Technologies |
| Raytheon Technologies |
| Lockheed Martin |
| Others |
Cost & Logistics Intelligence
Capacity utilization at specialized semiconductor foundries in Taiwan and South Korea shapes both supply concentration and price floors for defense-grade 5G hardware, as dedicated military production lines command premium allocations against commercial demand cycles.
Pricing Analysis
United States Pentagon procurement runs 15-25% above allied NATO member pricing for equivalent tactical base station specifications, reflecting FCC certification burdens and Open RAN interoperability testing requirements. Three-tier pricing structure across hardened expeditionary, standard tactical, and commercial-off-the-shelf military specifications separates procurement tiers, with certification grade and electromagnetic-contested environment hardening as primary differentiation drivers. Cost compression in commercial-off-the-shelf tiers is intensifying because defense primes face recruitment inflation for mmWave engineering talent. Government agencies exhibit highest price sensitivity due to budget cycle constraints, while military end users prioritize performance benchmarks over unit economics.
Supply Chain Analysis
The United States and Germany anchor final assembly and systems integration for tactical 5G networks, while Taiwan and South Korea supply advanced baseband processors and RF front-end components. Gallium nitride substrates, high-purity silicon germanium, and specialized ceramic packaging materials constitute critical input dependencies. Single-source vulnerability concentrates in millimeter-wave power amplifier foundries, where qualified defense suppliers number fewer than six globally. Distribution runs through prime contractor channel structures with long-term service contract bundling, though procurement officers are unbundling hardware from service commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through NATO Standardization Office interoperability protocols creates substantial switching costs for allied defense procurement officers.
For Market Incumbents: Fortify captive mmWave design teams through targeted acquisition of specialized radio-frequency engineering boutiques in Germany and Japan, countering talent scarcity that stretches program timelines. Deepen backward integration into gallium nitride substrate supply through joint ventures with established semiconductor foundries, insulating against single-source vulnerability in power amplifier components. For New Entrants and Emerging Players: Lead with subsystem specialization in edge computing node hardware for tactical networks, where uncontracted white space exists and vendor qualification timelines remain compressed. Target EU defense fund strategic autonomy guidelines as entry pathway, positioning non-U.S. subsystem designs for procurement officers balancing supply chain security against performance benchmarks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among systems integrators with classified program access and long-term C4ISR infrastructure relationships. Acquisition focus should center on mid-cap specialists with NATO testbed validation and captive mmWave engineering teams, as these assets compound defensive positioning across multi-year procurement cycles. Monitor electromagnetic spectrum denial threat evolution as inflection indicator for hardware hardening demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | Accelerates vendor qualification timelines under U.S. Department of Defense mandates while fragmenting procurement. |
| mmWave Engineering Talent Acquisition | Addresses acute scarcity of software-defined radio specialists that inflates recruitment costs across defense primes. |
| Edge Computing Node Integration | Captures fastest-growing technology segment for drone swarm coordination and augmented-reality maintenance applications. |
| EU Defense Fund Strategic Autonomy Positioning | Creates entry points for non-U.S. subsystem vendors balancing supply chain security against NATO performance benchmarks. |
| Mesh Network Architecture Validation | Validates self-healing topologies at Marine Corps bases and Army proving grounds for expeditionary force scalability. |
Research Approach
Cross-validation between primary interviews with defense procurement officers, systems integration program managers, and RF engineering directors and secondary validation through FCC defense trial authorizations, NATO Standardization Office protocol documents, and Pentagon budget justification materials anchors the qualitative findings. Bottom-up triangulation across vendor qualification timelines and top-down reconciliation against allied defense expenditure disclosures ensures coverage coherence.
Sensitivity analysis around electromagnetic spectrum denial threat evolution and mmWave spectrum allocation policy shifts informs the analytical framework across the analysis window. Segmentation dimensions modeled include application type, technology layer, end user security clearance tier, and deployment architecture, with CAGRs derived from procurement pipeline visibility and testbed validation schedules. Open RAN mandate compliance timelines and NATO digital transformation directive implementation pace constitute defense-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained allied defense expenditure growth and spectrum harmonization progress would require recalibration. Forecasts reflect documented assumptions regarding vendor qualification timeline compression and electromagnetic-contested environment hardening requirements. Recalibration cycles align with material shifts in FCC defense trial authorizations and NATO interoperability protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Esim Market
Telecommunications
5G MVNO Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
Australia Telecom Tower Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
France Telecom Market
Telecommunications
Philippines Telecom Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
LTE Base Station System Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
Cloud PBX Market
Telecommunications
Indonesia Telecom Market
Telecommunications
Cambodia ICT Market