
 Global Esim Market | 2026-2036
Global Esim Market Size, Share, and Industry Trends Forecast 2026-2036
Global Esim Market Foresight
Semiconductor packaging engineer shortages across Europe and East Asia is reorganizing how eSIM module vendors allocate fabrication capacity. Infineon Technologies AG leverages its Munich-based R&D footprint to sustain captive wafer supply for secure element production. Thales Group anchors its position through defense-grade certification expertise that extends into civilian IoT modules.
An eSIM (embedded Subscriber Identity Module) is a reprogrammable chip soldered directly onto a device motherboard, typically conforming to ETSI M2M specifications with storage capacities from 128 KB to several MB for carrier profiles and encryption keys; its industrial purpose is to enable remote, over-the-air provisioning of mobile network credentials without physical SIM card replacement. Consumer electronics deployment generates the largest current revenue pool, while industrial IoT application represents the fastest-expanding segment as asset-tracking and predictive maintenance programs scale. Remote SIM provisioning technology leads in installed base, though integrated SIM architectures are capturing margin in wearables and ultra-compact sensors where board space commands premium pricing.
The European Telecommunications Standards Institute sets the eUICC technical baseline that FDA-registered medical device makers must also satisfy when embedding cellular connectivity in remote patient monitors. FCC equipment authorization rules in the United States govern RF emissions from eSIM-enabled devices, creating a dual-compliance pathway that shapes product development timelines for vendors targeting transatlantic sales. Stakeholders must monitor how GSMA certification requirements evolve alongside national cybersecurity frameworks to avoid stranded inventory in fragmented regulatory environments.
Market Dynamics
Remote SIM provisioning architectures are compressing carrier authentication into software layers, eroding hardware-based security margins while expanding addressable device categories beyond traditional mobile handsets.
Growth Catalysts
- Automotive OEM connected-car mandates:Vehicle manufacturers in Germany and South Korea are embedding eSIM modules for over-the-air firmware updates and telematics, creating captive demand for automotive-grade secure elements.
- EU AI Act data-localization requirements:The framework mandates edge-processing of biometric and location data, forcing device makers to provision multiple regional carrier profiles through embedded modules rather than roaming agreements.
- Semiconductor packaging cluster concentration:Advanced substrate and wafer-level packaging capabilities in Taiwan and Malaysia are lowering unit costs for integrated SIM form factors in wearables.
Market Restraints
- Secure element foundry concentration:Mature-node capacity for tamper-resistant silicon is concentrated among three East Asian foundry groups, exposing module vendors to allocation rationing during demand spikes.
- GDPR profile-migration complexity:Cross-border transfer restrictions on subscriber identity data create legal friction for global enterprises deploying unified eSIM management platforms.
- Physical SIM residual infrastructure:Retail carrier stores and legacy point-of-sale systems in emerging markets continue to subsidize removable SIM distribution, delaying eSIM-only device launches.
Strategic Opportunities
- Industrial IoT asset-tracking expansion:Cold-chain logistics operators in the United States are adopting integrated SIM sensors for real-time temperature and location verification, opening volume contracts beyond consumer electronics.
- India PLI scheme for telecom equipment:Production-linked incentives for domestic manufacturing of network gear are attracting module assembly investments to serve South Asian carrier digitization programs.
- Healthcare remote patient monitoring:FDA-registered device makers are embedding cellular connectivity in cardiac monitors and infusion pumps, requiring FDA and ETSI dual compliance that favors established secure-element suppliers.
Industry Challenges
- Multi-standard certification bottlenecks:GSMA security accreditation timelines for new eUICC operating systems routinely exceed 18 months, delaying product launches for fabless module designers.
- Legacy M2M integration friction:Enterprise fleet management systems built on proprietary remote SIM provisioning protocols resist migration to standardized SGP.32 architectures without middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Esim Market |
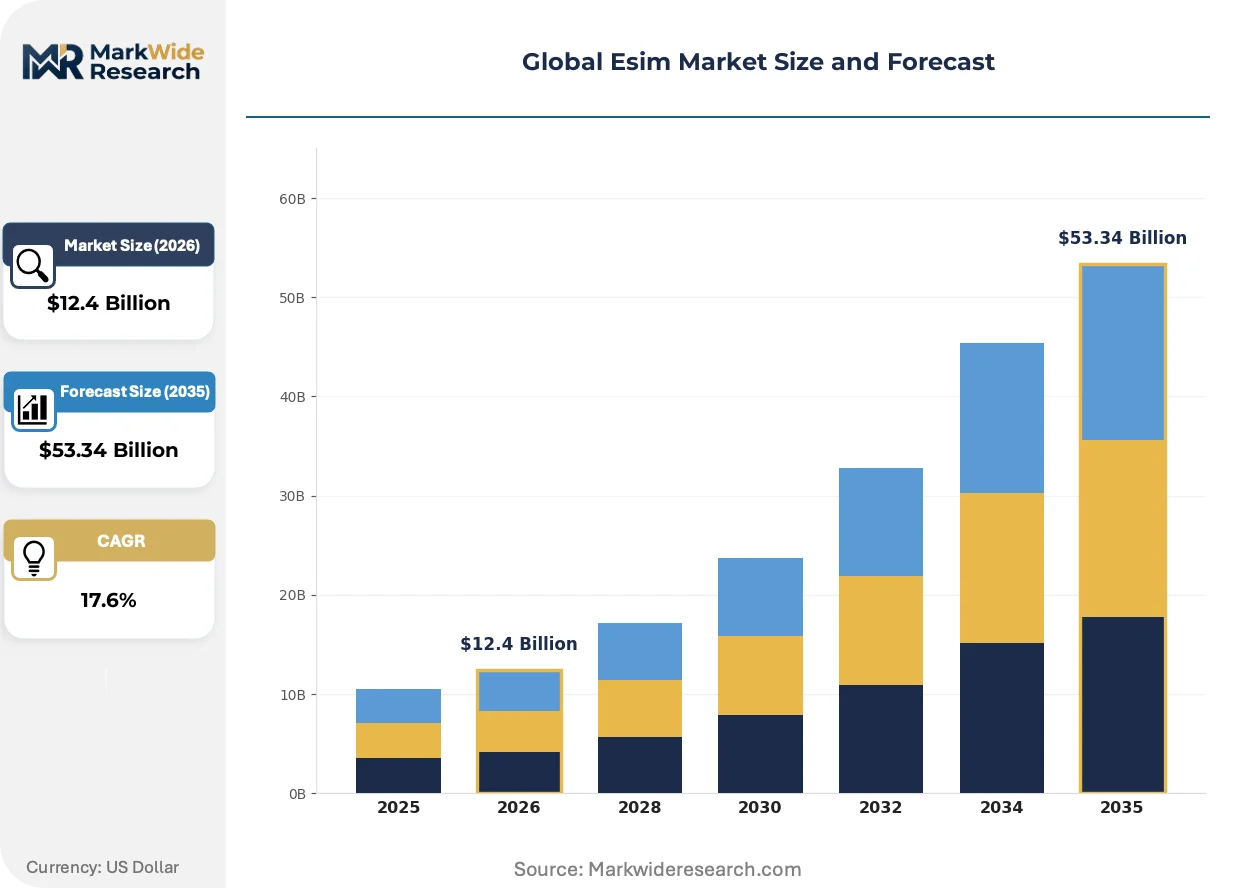
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $53.34 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smartphones, Tablets, Wearables, Connected Cars, Smart Home Devices, Industrial IoT Technology: Embedded Universal Integrated Circuit Card (eUICC), Remote SIM Provisioning, Integrated SIM, Virtual SIM End User: Telecom Operators, Mobile Virtual Network Operators, Device Manufacturers, IoT Service Providers, Automotive OEMs Deployment: Consumer Electronics, Enterprise Solutions, Public Safety, Transportation Systems, Healthcare Networks |
| Companies Covered | Giesecke+Devrient GmbH, Infineon Technologies AG, STMicroelectronics, Thales Group, IDEMIA, NXP Semiconductors, Sierra Wireless, Deutsche Telekom AG, KORE Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Esim Market Shifts & Advancements
Integrated SIM architectures are dissolving the boundary between baseband processor and identity security, enabling new device form factors while complicating supply chain accountability for cryptographic credential integrity.
iSIM technology—where the secure element function migrates into the cellular SoC die—is fragmenting the traditional eUICC vendor landscape. Automotive Tier-1 suppliers in Stuttgart and Seoul are piloting iSIM for connected vehicle platforms, eliminating discrete secure-element BOM while concentrating liability for breach response onto semiconductor foundries.
GDPR Article 44 transfer mechanism rulings are forcing device manufacturers to regionalize their subscription management data routing. The European Data Protection Board's Schrems II enforcement has triggered construction of EU-localized SM-DP+ servers, adding operational cost but creating compliance differentiation for vendors with Frankfurt or Dublin hosting infrastructure.
Enterprise procurement of eSIM-enabled devices is consolidating through mobile virtual network enablers rather than direct carrier relationships. Large-scale logistics operators in the United States are negotiating aggregated connectivity contracts with neutral host platforms, compressing carrier retail margins while demanding API-level integration with existing fleet management dashboards.
Global Esim Market Segmentation
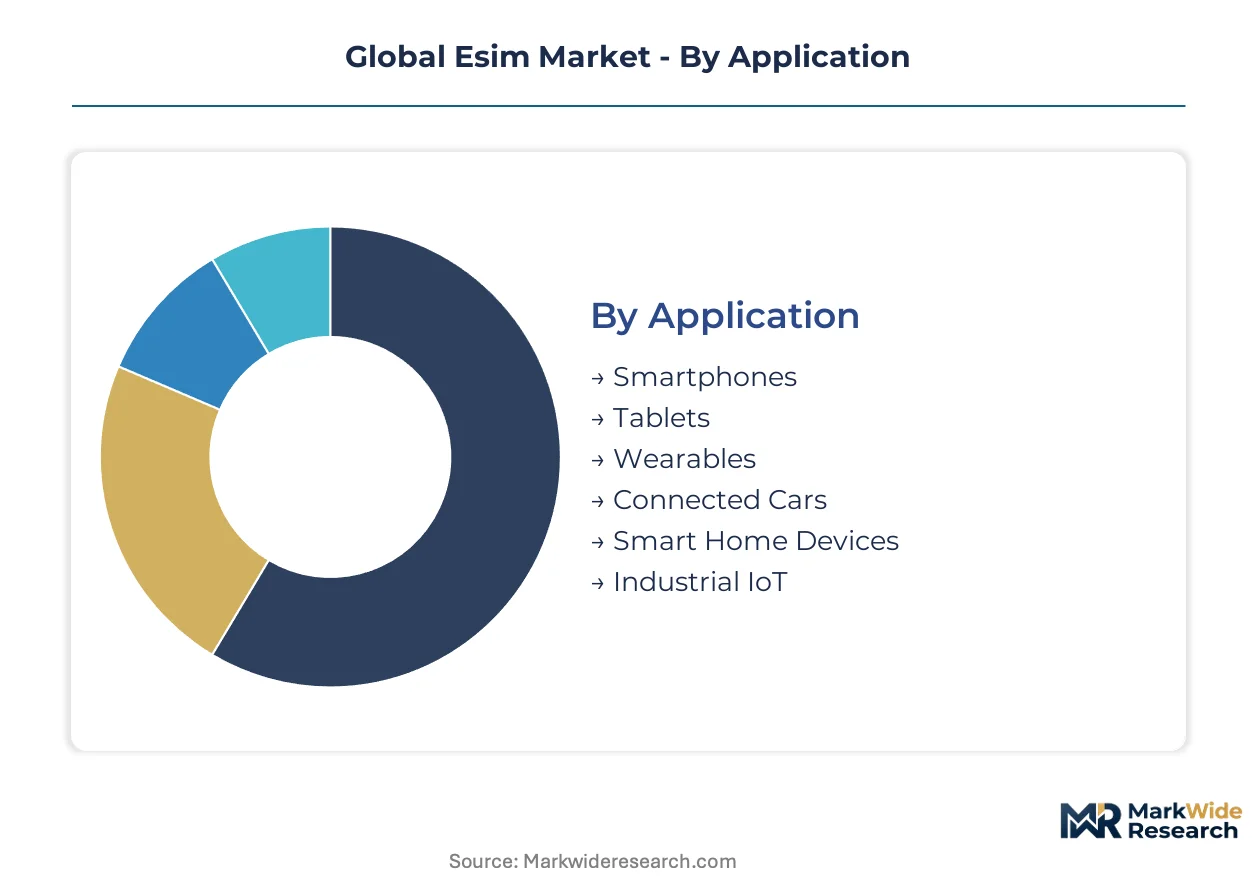
eSIM segmentation reveals divergent margin structures across consumer and industrial deployments. Technology architecture choices determine whether vendors capture value in hardware, software, or subscription layers.
Application:
Premium margin pools concentrate in automotive and industrial deployments where certification barriers limit supplier entry.
- Smartphones:eSIM modules in flagship handsets conform to ETSI M2M specifications with 128 KB to several MB storage for carrier profiles. Apple and Samsung procurement in the United States and South Korea drives volume, though per-unit margins compress under carrier subsidy pressure.
- Connected Cars:Automotive-grade secure elements soldered to telematics control units enable over-the-air firmware updates and emergency call functionality. German and South Korean OEM mandates for connected vehicle platforms create captive demand with extended qualification timelines that protect pricing.
- Wearables:Ultra-compact integrated SIM form factors address board space constraints in fitness bands and smartwatches.
- Tablets:Enterprise fleet deployments favor eSIM for flexible carrier switching across regional operations.
- Smart Home Devices:Security cameras and voice assistants embed cellular backup connectivity through remote-provisioned modules.
- Industrial IoT:Asset-tracking sensors in cold-chain logistics require temperature-resistant packaging and decade-long operational lifecycles.
Smartphones hold installed capacity. Industrial IoT is rotating up the share rankings.
Technology:
Architecture selection determines whether value accrues to semiconductor foundries, software platforms, or system integrators.
- Remote SIM Provisioning:GSMA-standardized over-the-air credential management dominates installed base across consumer electronics. Carrier authentication compression into software layers erodes hardware security margins while expanding addressable device categories.
- Integrated SIM:Secure element function migration into cellular SoC die eliminates discrete component BOM in wearables and ultra-compact sensors. Taiwan and Malaysia packaging clusters enable cost structures that capture premium pricing where board space commands scarcity rents.
- Embedded Universal Integrated Circuit Card (eUICC):ETSI-compliant removable-secure-element architecture persists in industrial gateways requiring field serviceability.
- Virtual SIM:Pure-software identity abstraction layers target cloud-native IoT platforms with containerized workloads.
Remote SIM Provisioning anchors current revenue. Integrated SIM is climbing the fastest as iSIM pilots expand.
End User:
Procurement consolidation patterns separate volume buyers from price-sensitive segments.
- Telecom Operators:Direct eSIM platform investments by Deutsche Telekom and Verizon focus on subscriber retention through seamless carrier switching barriers.
- Automotive OEMs:Tier-1 supplier contracts with Infineon and Thales specify defense-grade certification lineage for telematics modules.
- Device Manufacturers:Consumer electronics OEMs negotiate aggregated component sourcing through EMS partners in Taiwan and Malaysia.
- Mobile Virtual Network Operators:Neutral host platforms aggregate connectivity contracts for enterprise fleet operators, compressing retail carrier margins.
- IoT Service Providers:Vertical specialists in cold-chain logistics and predictive maintenance bundle connectivity with analytics dashboards.
Telecom Operators retain legacy dominance. Automotive OEMs are gaining share fastest as connected-car mandates multiply.
Deployment:
Regulatory compliance intensity varies sharply across deployment contexts, shaping vendor qualification requirements.
- Consumer Electronics:FCC equipment authorization in the United States and CE marking in Europe govern RF emissions from eSIM-enabled handsets and wearables.
- Healthcare Networks:FDA-registered remote patient monitors require dual compliance with ETSI technical baselines and FDA quality system regulations, favoring established secure-element suppliers.
- Enterprise Solutions:GDPR Article 44 transfer mechanism rulings force regionalized subscription management data routing for multinational deployments.
- Transportation Systems:Connected vehicle platforms face KBA type approval in Germany and NHTSA guidelines in the United States.
- Public Safety:First responder communications equipment demands FIPS 140-2 cryptographic certification in the United States.
Consumer Electronics maintains volume leadership. Healthcare Networks is expanding most quickly as cardiac monitor and infusion pump connectivity mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization rules govern RF emissions from eSIM-enabled devices in the United States, creating compliance pathways that shape transatlantic product development timelines for vendors serving multiple jurisdictions.
United States
Enterprise fleet operators and cold-chain logistics providers drive integrated SIM adoption for real-time asset tracking. FDA-registered medical device makers must satisfy dual compliance with FCC emissions standards and ETSI technical baselines when embedding cellular connectivity in cardiac monitors. Silicon Valley and Austin semiconductor clusters host R&D operations for secure element architecture development.
Germany
Automotive OEM connected-car mandates generate captive demand for automotive-grade secure elements in telematics control units. KBA type approval regulations govern connected vehicle platforms, extending qualification timelines that protect supplier pricing. Stuttgart and Munich anchor the automotive electronics ecosystem where Tier-1 suppliers pilot iSIM architectures for next-generation vehicle platforms.
South Korea
Consumer electronics OEMs in Seoul and Suwon drive volume procurement of remote SIM provisioning modules for flagship handsets. MFDS cybersecurity frameworks for medical devices create parallel compliance requirements for healthcare connectivity applications. Busan-Ulsan packaging clusters enable advanced substrate capabilities for integrated SIM form factors in wearables.
Taiwan
Wafer-level packaging capabilities in Hsinchu Science Park lower unit costs for integrated SIM form factors where board space commands scarcity rents. Semiconductor foundries concentrate mature-node capacity for tamper-resistant silicon production. Taipei-based EMS partners negotiate aggregated component sourcing contracts for global device manufacturers.
India
TRAI digitization mandates accelerate carrier infrastructure modernization, opening volume contracts for module assembly investments. Production-linked incentive schemes for domestic telecom equipment manufacturing attract supply chain relocation from East Asian clusters. Bengaluru and Hyderabad host emerging R&D operations for subscription management platform development.
Global Esim Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the eSIM value chain, creating a tiered competitive structure where secure element design, semiconductor fabrication, and subscription management platforms represent distinct battlegrounds. Consolidation pressures concentrate around GSMA certification bottlenecks and automotive qualification timelines that favor incumbent suppliers with established regulatory relationships. Three archetypes dominate: integrated device manufacturers with captive secure element production, fabless module designers reliant on foundry partnerships, and neutral host platforms aggregating enterprise connectivity contracts. Strategic moves center on backward integration into wafer supply and geographic expansion into India PLI scheme jurisdictions.
Among European secure element specialists, Infineon Technologies AG and Thales Group exemplify the defense-grade certification lineage that extends into civilian IoT and automotive telematics modules. STMicroelectronics occupies a position bridging consumer electronics volume and industrial qualification requirements. These three anchors represent how Munich-based R&D footprints and Paris-region certification expertise translate into compliance differentiation for FDA-registered and ETSI-compliant device deployments.
| Leading Market Players |
|---|
| Giesecke+Devrient GmbH |
| Infineon Technologies AG |
| STMicroelectronics |
| Thales Group |
| IDEMIA |
| NXP Semiconductors |
| Sierra Wireless |
| Deutsche Telekom AG |
| KORE Wireless |
| Others |
Supply & Pricing Matrix
Eighteen-month GSMA certification timelines for new eUICC operating systems compress supplier margins while amplifying pricing power for incumbent secure-element vendors with established regulatory relationships. Automotive OEM qualification cycles in Germany and South Korea extend to 24-36 months, creating captive pricing tiers that resist commoditization pressures from consumer electronics volume buyers.
Pricing Analysis
Automotive-grade secure elements command 40-60% premiums over consumer handset modules in Taiwan and Malaysia assembly clusters. Three-tier pricing structure across automotive-certified, industrial-grade, and consumer-economy levels separates defense-lineage suppliers from fabless module designers. Cost compression in smartphone eSIMs stems from carrier subsidy pressure and EMS partner consolidation in Taipei. Enterprise fleet operators exhibit lowest price sensitivity due to compliance bundling requirements, while wearable OEMs face acute margin pressure from board-space scarcity rents.
Supply Chain Analysis
Mature-node wafer capacity for tamper-resistant silicon concentrates among East Asian foundry groups, exposing module vendors to allocation rationing during demand spikes. Secure element production draws from silicon wafer supply chains in Taiwan, South Korea, and Japan, with advanced substrate packaging capabilities clustering in Hsinchu Science Park and Busan-Ulsan corridors. Single-source vulnerability in defense-grade certification expertise creates qualification bottlenecks for FDA-registered medical device deployments. Distribution runs through EMS partners aggregating component sourcing for global device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
eSIM penetration sits at early-cycle expansion as connected-car mandates and industrial IoT asset-tracking programs multiply addressable device categories beyond traditional mobile handsets.
For Market Incumbents: Consolidate backward integration into captive wafer supply for secure element production, mirroring Infineon's Munich-based R&D footprint strategy. Deepen automotive qualification relationships with Stuttgart and Seoul Tier-1 suppliers to defend margin position against iSIM architecture displacement from cellular SoC vendors.
For New Entrants and Emerging Players: Anchor in India PLI scheme jurisdictions for domestic telecom equipment assembly, leveraging TRAI digitization mandates to bypass entrenched East Asian supply chain relationships. Target cold-chain logistics operators in the United States with integrated SIM sensors bundling connectivity and analytics dashboards.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-arbitrage play because regulatory fragmentation across GDPR, EU AI Act, and FDA dual-certification requirements favors established secure-element suppliers with defense-grade lineage. Watch GSMA certification timeline compression as inflection signal for fabless module designer viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer Supply | Captive mature-node capacity insulates against East Asian foundry allocation rationing during demand spikes. |
| iSIM Architecture Pilot Programs | Automotive Tier-1 suppliers in Stuttgart and Seoul test SoC-integrated secure elements for next-generation telematics platforms. |
| EU-Localized SM-DP+ Infrastructure | Frankfurt and Dublin hosting investments create compliance differentiation under Schrems II enforcement patterns. |
| India PLI Scheme Manufacturing Relocation | Domestic module assembly attracts supply chain relocation from Taiwan and Malaysia packaging clusters. |
| Healthcare Dual-Compliance Certification | FDA-registered device makers require ETSI baseline alignment for cardiac monitor and infusion pump connectivity. |
Research Methodology
The analysis maps remote SIM provisioning architectures, integrated SIM form factors, and iSIM technology trajectories, each validated through semiconductor packaging engineers, automotive Tier-1 procurement leads, carrier platform executives, and FDA regulatory affairs specialists. Primary fieldwork combined with secondary validation from ETSI technical specifications, GSMA certification databases, FCC equipment authorization filings, and EU AI Act implementation guidance. Bottom-up module shipment estimates triangulated against top-down connectivity subscription forecasts across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across application segments, technology architectures, end-user procurement patterns, and deployment contexts. Segmentation modeling incorporated device category, certification grade tier, regional regulatory cluster, and supply chain sourcing geography. CAGRs derived from installed base progression curves and replacement cycle dynamics, with specific inputs from automotive connected-car mandate schedules and industrial IoT sensor deployment pipelines.
Decision-makers should treat outputs as directional under sustained semiconductor packaging cluster concentration and GSMA certification timeline stability; material deviation in foundry capacity allocation or regulatory enforcement intensity would warrant model refresh. Practitioners should keep alternative scenarios live as EU AI Act data-localization requirements and Schrems II transfer mechanism rulings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
South Africa MNO - MVNO Market
Telecommunications
Mftpaas Market
Telecommunications
Ireland Telecom Market
Telecommunications
Mobile Voice Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
GPON Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
Global 5G Services Market
Telecommunications
Prepaid Communication Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Iceland Telecom Market
Telecommunications
Costa Rica Telecom Market
Telecommunications
Global LTE Market
Telecommunications
North America Telecom Expense Management Market