
 Middle East and Africa Telecom Expense Management Market | 2026-2036
Middle East and Africa Telecom Expense Management Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Telecom Expense Management Market Foresight
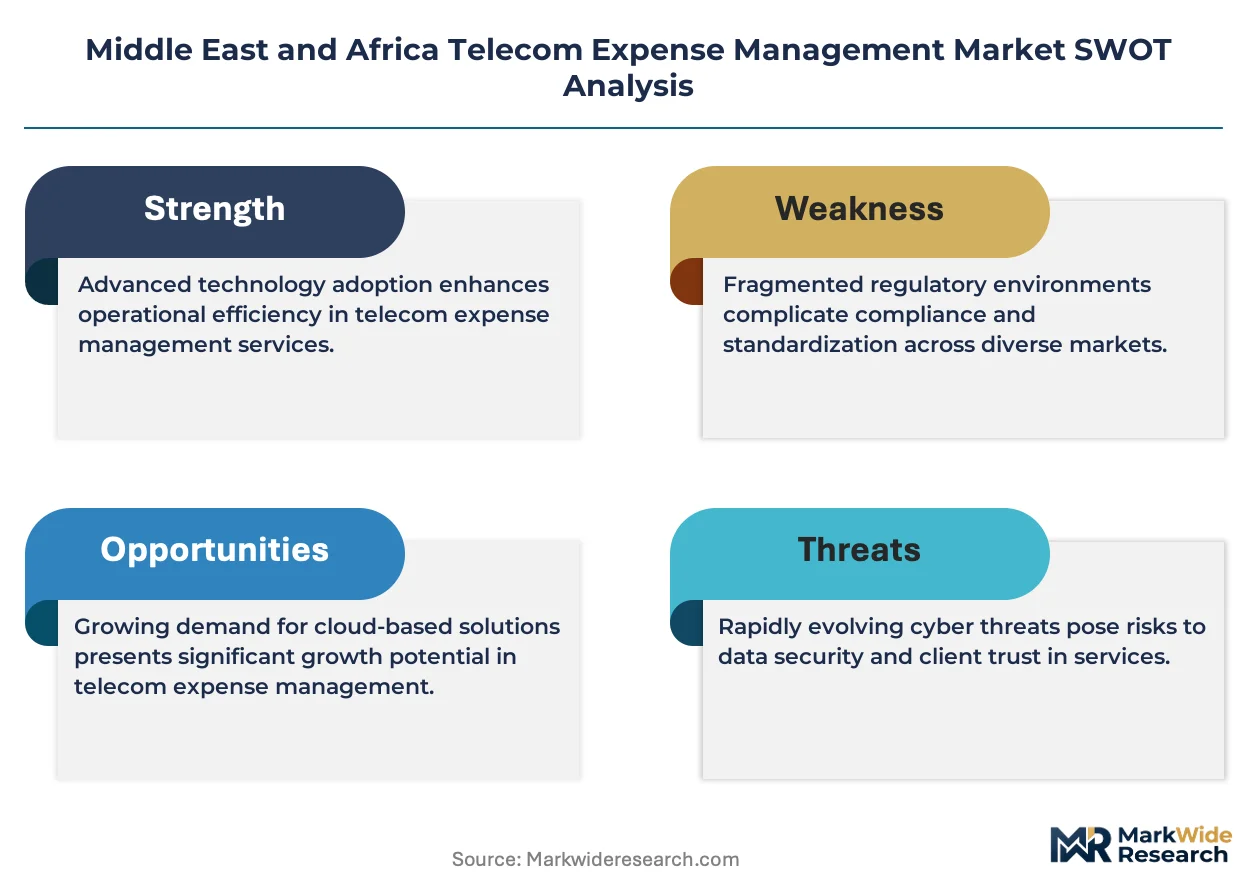
Asset-light managed service contracts and outcome-based leasing arrangements is reconfiguring competitive entry barriers for regional TEM providers. Vodafone Group leverages its carrier-owned status to embed expense management directly into enterprise connectivity bundles. Tangoe anchors its position through specialized SaaS platforms that consolidate multi-voice invoices across fragmented African networks. Calero-MDSL differentiates via deep integration with European parent systems serving multinationals with MEA operations.
Telecom expense management encompasses the systematic audit, allocation, and optimization of enterprise telecommunications expenditures across mobile, fixed-line, and data services, typically deployed through software platforms that automate invoice validation against contracted rates and usage patterns. The practice serves chiefly to eliminate billing discrepancies, enforce corporate mobility policies, and recover vendor overcharges across distributed workforces. Cloud-based deployment models now lead adoption trajectories among mid-market enterprises seeking rapid implementation without capital infrastructure commitment. Managed services represents the fastest-expanding segment as African enterprises outsource TEM complexity to third-party specialists. Government entities constitute a concentrated margin pool given procurement compliance mandates and multi-year framework agreements.
South Africa's Independent Communications Authority enforces cost-based interconnection regulations that directly shape enterprise billing transparency requirements and TEM platform demand. Nigeria's NCC consumer protection codes mandate itemized billing disclosures, creating compliance-driven software procurement across Lagos and Abuja commercial corridors. The UAE's TDRA spectrum and tariff frameworks impose structured reporting obligations on licensed operators. Stakeholders must weigh cloud migration timelines against hybrid deployment persistence in markets with intermittent connectivity reliability.
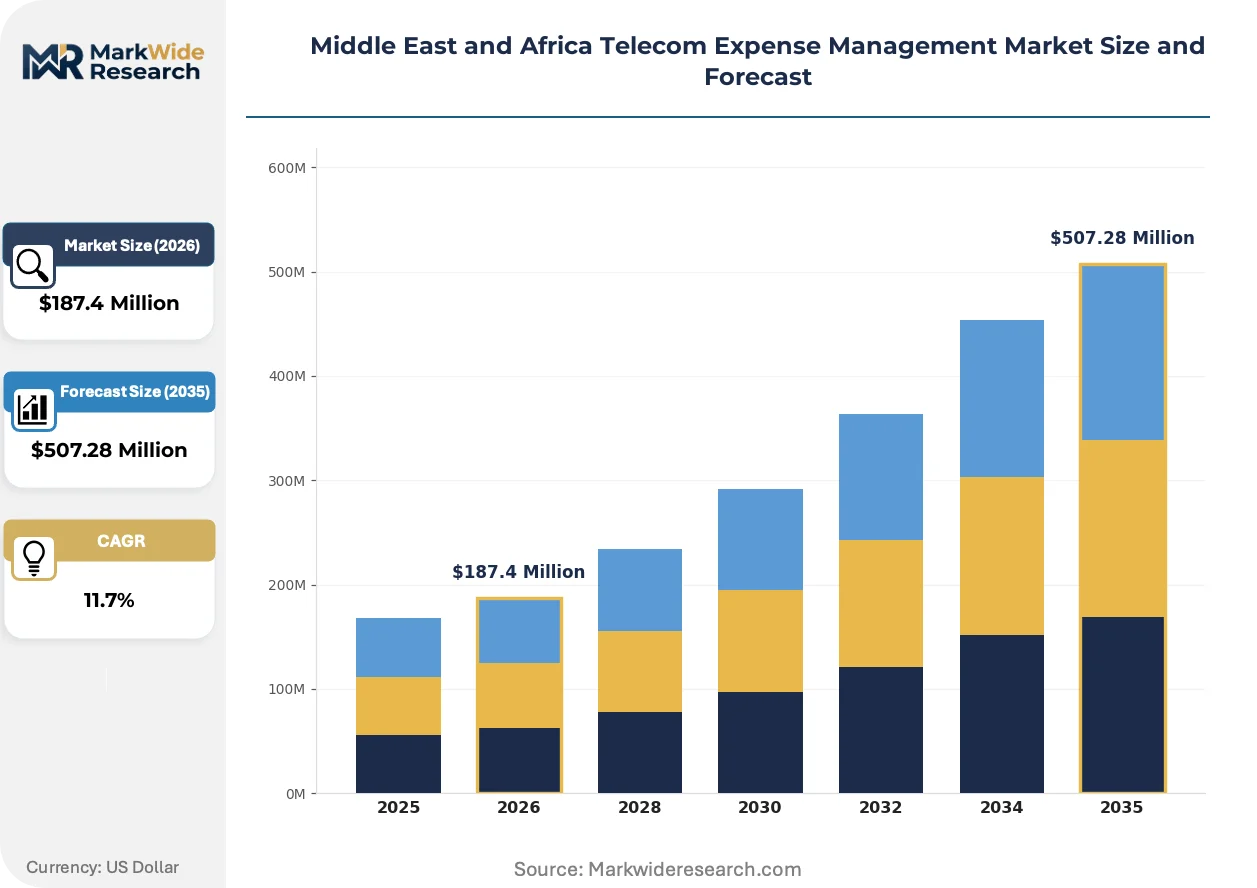
Market Dynamics
Carrier consolidation across Gulf Cooperation Council markets is compressing vendor choice for enterprise buyers while simultaneously expanding bundled TEM functionality into connectivity contracts. This structural concentration is reconfiguring how procurement teams evaluate standalone versus embedded expense management platforms.
Growth Catalysts
- ICASA Cost-Based Interconnection Rules:South Africa's regulatory framework mandates transparent wholesale rate disclosure, forcing operators to provide machine-readable billing feeds that TEM platforms ingest automatically.
- Enterprise Mobility Expansion:Mining and logistics conglomerates across the Democratic Republic of Congo and Zambia are deploying managed mobility programs spanning thousands of field workers, creating audit complexity that software platforms resolve.
- Cloud Infrastructure Maturation:Johannesburg and Lagos data center buildouts are eliminating latency barriers that previously justified on-premise TEM deployments, accelerating SaaS adoption among mid-market enterprises.
Market Restraints
- Foreign Exchange Volatility:Naira and Rand depreciation against dollar-denominated software licensing creates unpredictable total cost of ownership for Nigerian and South African procurement teams.
- Carrier Billing Fragmentation:Pan-African enterprises contract with fifteen-plus mobile network operators across operating markets, each deploying proprietary invoice formats that resist standardization.
- Connectivity Infrastructure Gaps:Intermittent terrestrial and submarine cable reliability in East African corridor markets disrupts cloud-dependent TEM platform uptime guarantees.
Strategic Opportunities
- Ethiopian Market Liberalization:The Ethio Telecom monopoly breakup creates first-mover advantage for TEM providers establishing relationships with newly licensed Safaricom Ethiopia and potential third entrants.
- Sovereign Wealth Deployment:UAE and Saudi Arabia government digitization mandates under Vision 2030 frameworks are channeling procurement spend toward compliance-automating expense management platforms.
- AI-Enabled Anomaly Detection:Machine learning layer integration with existing SaaS architectures is virtualizing manual invoice audit functions, opening premium pricing tiers for automated recovery services.
Industry Challenges
- Localization Engineering Burden:Arabic right-to-left interface adaptation and French regulatory reporting modules for Francophone West Africa require dedicated development resources that strain regional software teams.
- Integration Debt Accumulation:Legacy SAP and Oracle ERP instances prevalent in established South African enterprises demand custom API development that extends implementation timelines beyond SaaS benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Telecom Expense Management Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed Line Services, Data Services, VoIP Solutions Customer Type: Enterprises, SMBs, Government Entities, Non-Profits Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services Technology: Software Solutions, Analytics Tools, Automation Platforms, Integration Systems |
| Companies Covered | Vodafone Group, Tangoe, Calero-MDSL, Cass Information Systems, CGI Inc., Accenture, TeleManagement Technologies Inc., Asignet, WidePoint Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Telecom Expense Management Market Shifts & Advancements
Artificial intelligence layer insertion is compressing audit cycle times from weeks to hours while simultaneously expanding the category of detectable billing anomalies. Platform architecture decisions now pivot on inference latency rather than storage optimization.
Containerized microservices architecture is virtualizing monolithic TEM platform delivery, enabling South African financial services firms to deploy invoice processing modules independently from mobility management components. Mid-market banks in Cape Town and Durban are piloting this decomposition to match software spend with actual feature utilization. The structural consequence is collapsing minimum viable contract thresholds that previously excluded sub-thousand-employee enterprises.
Nigeria's NCC Consumer Protection Codes mandating itemized billing disclosure are compelling Lagos-based carriers to restructure invoice data architectures. Enterprise procurement teams in Abuja commercial corridors now receive granular call-record detail that TEM platforms ingest for policy enforcement. Software vendors are responding with pre-configured compliance dashboards that accelerate Nigerian sales cycles.
Subscription fatigue among procurement executives is fragmenting long-term managed service commitments into modular, renewable components. Kenyan and Ghanaian enterprises now separately contract for invoice audit, mobility policy enforcement, and vendor negotiation support rather than consolidated engagements. This unbundling is most visible in Nairobi's technology and professional services verticals where procurement teams rotate point solution providers annually.
Middle East and Africa Telecom Expense Management Market Segmentation
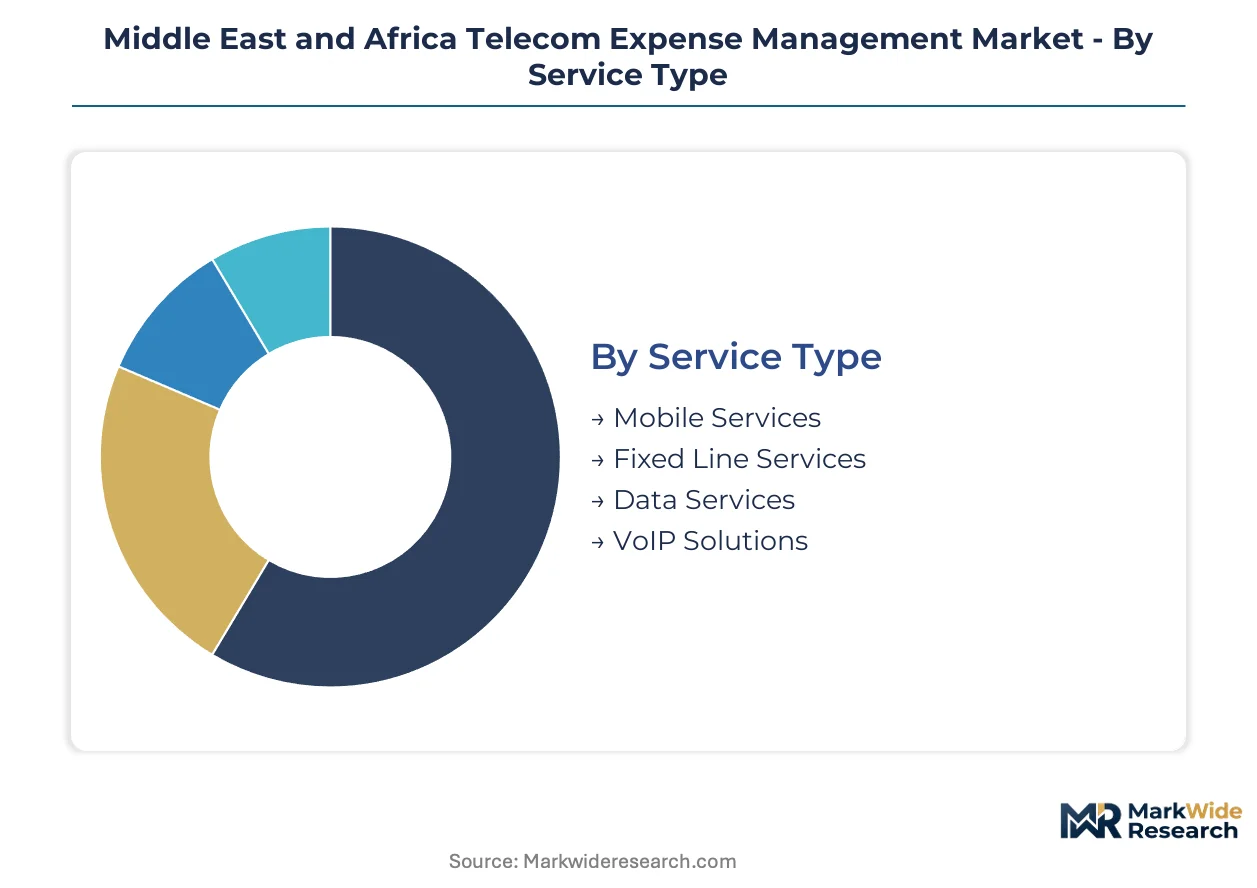
Telecom expense management platforms must align with distinct operational architectures across Middle East and Africa enterprises. Segmentation reveals how deployment constraints, regulatory mandates, and workforce mobility patterns shape procurement priorities.
Service Type:
Mature mobile audit functions coexist with emerging VoIP optimization capabilities as enterprise communication stacks diversify.
- Mobile Services:Encompasses cellular voice, messaging, and data plan management across distributed workforces. Mining conglomerates in the Democratic Republic of Congo and Zambia deploy these modules for thousands of field personnel where roaming charges accumulate unpredictably.
- Fixed Line Services:Covers PSTN and enterprise PBX expenditure tracking, including international calling verification. South African financial services firms in Johannesburg and Cape Town retain substantial fixed infrastructure requiring invoice reconciliation against negotiated rate decks.
- Data Services:Dedicated circuits, MPLS, and dedicated internet access optimization. UAE government entities under TDRA procurement frameworks utilize these modules for multi-year connectivity framework compliance.
- VoIP Solutions:Unified communications and SIP trunking expense monitoring. Nairobi technology firms pilot these capabilities as internet telephony displaces traditional voice across Kenyan commercial corridors.
Mobile Services handles the majority of throughput; VoIP Solutions is expanding most quickly as cloud telephony penetrates mid-market enterprises.
Customer Type:
Procurement sophistication varies sharply across organizational scale, with compliance mandates driving public sector adoption.
- Enterprises:Large organizations with multi-country operations requiring centralized visibility. Pan-African logistics operators spanning fifteen-plus mobile network operators depend on these deployments to standardize invoice formats across fragmented carrier billing systems.
- SMBs:Small and medium businesses prioritizing rapid implementation without capital infrastructure commitment. Lagos and Abuja commercial corridor firms favor cloud-based entry tiers that eliminate on-premise hardware requirements.
- Government Entities:Public sector organizations with procurement compliance mandates. Saudi Vision 2030 digitization frameworks channel spend toward automated expense management platforms with multi-year framework agreement structures.
- Non-Profits:Mission-driven organizations with constrained IT budgets. East African NGO networks leverage donor-funded managed service arrangements to outsource TEM complexity.
Enterprises dominate current revenue concentration; Government Entities show the steepest expansion trajectory as sovereign wealth deployment accelerates.
Deployment Model:
Cloud migration timelines diverge based on terrestrial connectivity reliability and data residency requirements.
- On-Premises:Self-hosted installations within enterprise data centers. Established South African enterprises with legacy SAP and Oracle ERP instances persist with these models despite extended implementation timelines.
- Cloud-Based:SaaS platforms eliminating capital infrastructure commitment. Mid-market banks in Cape Town and Durban pilot containerized microservices to match software spend with actual feature utilization.
- Hybrid:Mixed architectures preserving sensitive data on-premise while leveraging cloud processing. Nigerian enterprises navigating NCC consumer protection codes utilize hybrid structures for granular call-record detail retention.
- Managed Services:Third-party specialists handling complete TEM operations. African enterprises across Kenya and Ghana outsource invoice audit, mobility policy enforcement, and vendor negotiation support through modular renewable contracts.
Cloud-Based deployments are gaining share fastest as Johannesburg and Lagos data center buildouts eliminate latency barriers; Managed Services shows premium pricing resilience among procurement teams seeking outcome-based arrangements.
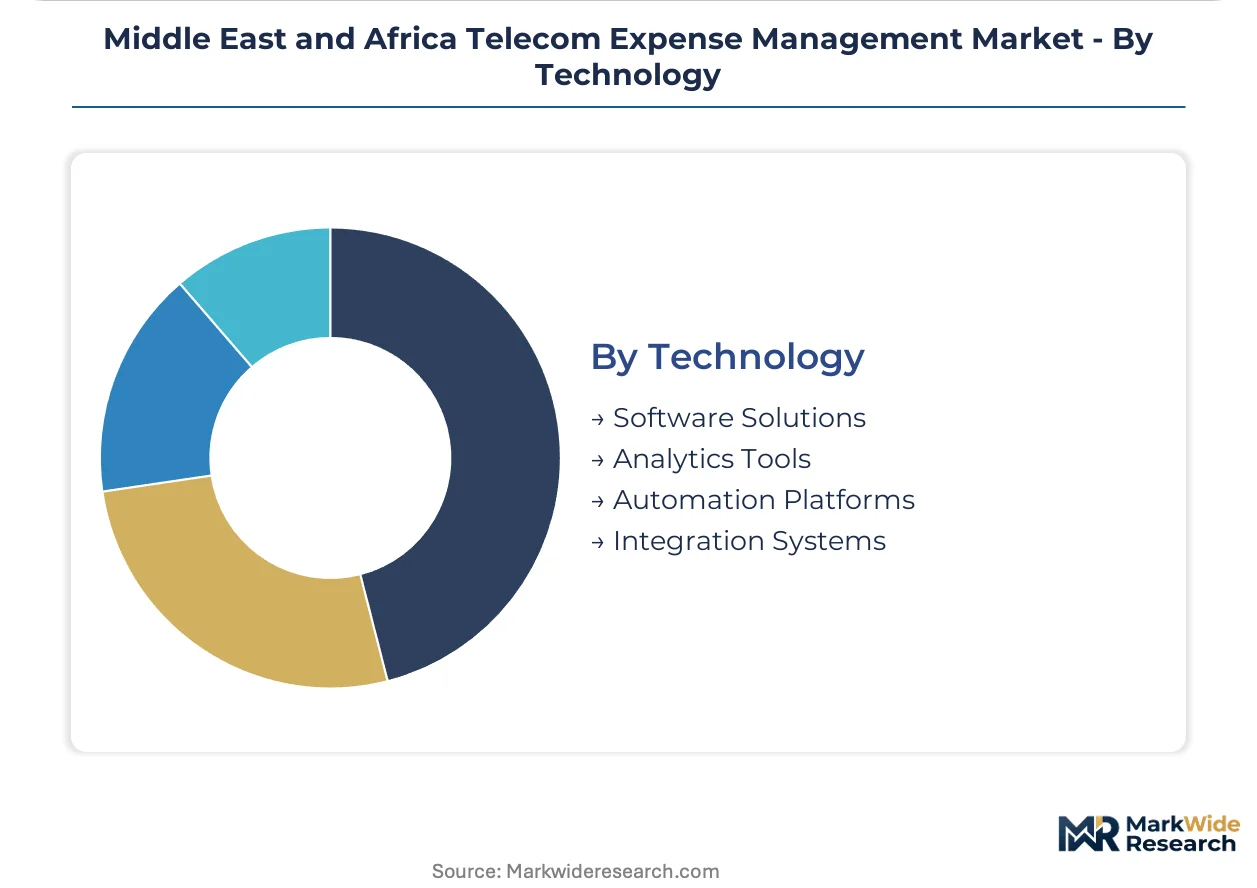
Technology:
Platform architecture decisions increasingly pivot on inference latency rather than storage optimization as artificial intelligence layers proliferate.
- Software Solutions:Core TEM platforms automating invoice validation against contracted rates. Tangoe anchors regional position through specialized SaaS platforms consolidating multi-voice invoices across fragmented African networks.
- Analytics Tools:Business intelligence modules for expenditure pattern visualization. Ethiopian market entrants utilize these capabilities to establish baseline metrics ahead of Safaricom Ethiopia and potential third operator launches.
- Automation Platforms:Machine learning-enabled anomaly detection and recovery services. Premium pricing tiers emerge as AI compresses audit cycle times from weeks to hours.
- Integration Systems:API architectures connecting TEM platforms to ERP and procurement systems. Calero-MDSL differentiates through deep European parent system integration serving multinationals with MEA operations.
Software Solutions retains the dominant installed base; Automation Platforms is climbing the fastest as procurement executives prioritize recovery yield over manual audit capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa Telecom Expense Management Market exhibits pronounced trade asymmetries in software and services flows. Gulf Cooperation Council states import specialized SaaS platforms from European and North American vendors while South Africa and Nigeria cultivate indigenous managed service capabilities for re-export to neighboring markets.
United Arab Emirates
UAE government entities under TDRA procurement frameworks drive substantial demand for compliance-automating expense management platforms. The Telecommunications and Digital Government Regulatory Authority imposes structured reporting obligations on licensed operators that cascade into enterprise billing transparency requirements. Dubai and Abu Dhabi commercial corridors host concentrated deployments among sovereign wealth-backed enterprises digitizing under Vision 2030 mandates.
Saudi Arabia
Saudi Vision 2030 government digitization initiatives channel procurement spend toward automated expense management with multi-year framework agreement structures. The Communications, Space and Technology Commission enforces tariff transparency rules that shape carrier billing practices. Riyadh and the Eastern Province petroleum sector enterprises represent the densest concentration of managed mobility program expansion.
South Africa
South African mining and financial services conglomerates deploy managed mobility programs spanning thousands of field workers, creating audit complexity that software platforms resolve. ICASA cost-based interconnection regulations mandate transparent wholesale rate disclosure and machine-readable billing feeds. Johannesburg and Cape Town financial services firms retain substantial fixed infrastructure requiring invoice reconciliation against negotiated rate decks.
Nigeria
Nigerian enterprise digitization across Lagos and Abuja commercial corridors accelerates demand for itemized billing compliance solutions. NCC consumer protection codes mandate granular call-record disclosure, compelling carrier data architecture restructuring. Lagos-based technology and professional services firms separately contract for invoice audit, mobility policy enforcement, and vendor negotiation support through modular arrangements.
Kenya
Kenyan enterprises in Nairobi's technology and professional services verticals rotate point solution providers annually, fragmenting long-term managed service commitments. The Communications Authority of Kenya enforces quality of service standards that indirectly shape enterprise telecom procurement practices. Nairobi technology firms pilot VoIP optimization capabilities as internet telephony displaces traditional voice across Kenyan commercial corridors.
Middle East and Africa Telecom Expense Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying modular audit engines and policy enforcement layers. The vendor base concentrates around carrier-owned entities, independent SaaS providers, and consulting-anchored managed service operations. Three archetypes dominate: telecommunications operators embedding TEM into connectivity bundles, pure-play software vendors consolidating multi-voice invoices across fragmented networks, and systems integrators serving multinationals with complex MEA operations. Competitive moves center on geographic expansion into newly liberalized markets and AI layer integration for automated anomaly detection.
Within the carrier-anchored tier, Vodafone Group exemplifies vertical integration strategies that embed expense management directly into enterprise connectivity offerings. Tangoe and Calero-MDSL occupy positions among independent platform specialists; Tangoe anchors through SaaS consolidation capabilities while Calero-MDSL represents European parent system integration serving multinationals with regional operations. These three entities collectively illustrate the competitive spectrum from bundled telecommunications services through specialized software to consulting-anchored implementations.
| Leading Market Players |
|---|
| Vodafone Group |
| Tangoe |
| Calero-MDSL |
| Cass Information Systems |
| CGI Inc. |
| Accenture |
| TeleManagement Technologies Inc. |
| Asignet |
| WidePoint Corporation |
| Others |
Supply & Pricing Matrix
European and North American software vendors anchor upstream supply for TEM platforms, concentrating margin capture in carrier-owned service bundles and government framework agreements across Gulf Cooperation Council states. Dollar-denominated licensing costs flow through to Nigerian and South African procurement teams facing foreign exchange volatility, compressing total cost of ownership predictability.
Pricing Analysis
Enterprise procurement teams anchor pricing negotiations around SaaS-tiered subscription models with modular component selection. Price differentiation rests on integration complexity with legacy ERP systems and AI-enabled anomaly detection capabilities. Cost compression in mid-market entry tiers intensifies as containerized microservices reduce minimum viable contract thresholds. Government entities under multi-year framework agreements show least price sensitivity; Lagos and Abuja commercial corridor SMBs exhibit highest sensitivity to upfront licensing exposure.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Johannesburg and Lagos data center operators ease working capital pressure for regional managed service providers. Platform development concentrates in the United States, Ireland, and South Africa, with implementation services drawing from UAE and Kenyan consulting ecosystems. Cloud infrastructure dependencies rest on submarine cable reliability through the East African corridor. Single-source vulnerability concentrates in European parent system integrations for multinational deployments. Distribution runs through carrier-direct channels, independent software vendors, and systems integrators serving complex MEA operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier-embedded expense management functionality threatens standalone TEM software incumbents with direct substitution into connectivity contracts. Procurement teams increasingly favor bundled solutions that eliminate separate vendor relationships.
For Market Incumbents: Insulate platform differentiation through AI layer integration for automated anomaly detection and recovery services. Deepen API development capabilities for legacy SAP and Oracle ERP integration in established South African enterprises. Vertical integration into carrier partnerships defends against embedded substitution, while certification investment for TRAI-style compliance modules preserves government framework access. For New Entrants and Emerging Players: Ethiopian market liberalization represents the most penetrable entry point ahead of Safaricom Ethiopia and potential third operator launches. Modular managed service components for Kenyan and Ghanaian enterprises separately contracting invoice audit, mobility policy enforcement, and vendor negotiation support offer white-space expansion. Go-to-market execution should anchor in Nairobi technology and professional services verticals with annual provider rotation patterns. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed managed service providers holding government framework agreements across UAE and Saudi Arabia Vision 2030 digitization mandates. Long-term viability centers on AI-enabled automation platform transitions and cloud infrastructure maturation in Johannesburg and Lagos data center buildouts. Watch Ethiopian regulatory liberalization timeline as inflection indicator for regional expansion opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| AI Layer Integration | Machine learning-enabled anomaly detection compresses audit cycles from weeks to hours for premium pricing tiers. |
| Carrier Partnership Deepening | Embedded expense management in connectivity bundles defends against standalone platform substitution. |
| Ethiopian Market Entry | First-mover positioning ahead of Safaricom Ethiopia and potential third operator captures liberalization upside. |
| Legacy ERP Integration Investment | Custom API development for South African SAP and Oracle instances extends implementation timelines but locks enterprise clients. |
| Modular Service Unbundling | Separately contracted invoice audit, mobility policy enforcement, and vendor negotiation support matches Nairobi procurement rotation patterns. |
Research Methodology
Initial hypotheses were tested against primary input from enterprise procurement officers, carrier enterprise sales directors, TEM platform engineers, and government IT procurement managers and refined through secondary validation. Primary fieldwork combined structured interviews with secondary source triangulation across SEC filings of listed software vendors, TRAI and NCC regulatory disclosure databases, ICASA tariff rulings, and hyperscaler capex disclosures for Johannesburg and Lagos data center buildouts. Bottom-up enterprise deployment sizing and top-down market aggregation were reconciled to produce segment-level estimates.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled encompass deployment model, organization scale, vertical industry, integration complexity with legacy systems, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year sizing, with trajectory validation against cloud infrastructure maturation indicators and sovereign wealth deployment timelines under Vision 2030 frameworks.
Macroeconomic conditions sit as an overlay; deviation in Naira and Rand exchange rates against dollar-denominated software licensing would shift the trajectory. Forecasts reflect documented assumptions about carrier consolidation pace, regulatory liberalization sequencing, and AI adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Utility Communications Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
China ICT Market
Telecommunications
5G Monetization Market
Telecommunications
Denmark ICT Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
Austria ICT Market
Telecommunications
5G Transport Networks Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Angola Telecom Market
Telecommunications
Argentina ICT Market