
 Cambodia ICT Market | 2026-2036
Cambodia ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Cambodia ICT Market Outlook
Cambodia's financial services sector is pivoting toward cloud-based transaction platforms and mobile banking infrastructure. Smart Axiata leverages its nationwide 4G coverage to anchor digital payment ecosystems for unbanked populations. Metfone competes through aggressive fiber-to-the-home expansion in provincial urban centers. EZECOM specializes in enterprise-grade leased-line services for Phnom Penh's commercial district.
Information and communications technology in Cambodia encompasses telecommunications infrastructure, data transmission systems, software platforms, and digital service delivery mechanisms operating across fixed-line, mobile cellular, and internet protocol networks with spectrum allocations primarily in 700 MHz to 2.6 GHz bands for mobile broadband. The sector serves commercial transaction processing, government service digitization, and educational content delivery as its primary functions. Software Solutions within the Product Type dimension leads current revenue generation as enterprises replace legacy accounting and customer management platforms. Cloud Computing under the Technology dimension represents the fastest-expanding segment as SMEs migrate from on-premise servers to subscription-based infrastructure. Government Agencies among End Users command disproportionate contract value through national digital identity and tax automation programs.
Cambodia's Ministry of Posts and Telecommunications issues operator licenses and spectrum authorizations that directly determine market entry for telecom providers. The Telecom Regulator of Cambodia enforces interconnection rules and quality-of-service benchmarks that shape retail pricing and network investment cycles. BIS-equivalent technical standards for networking equipment imports create compliance thresholds for hardware suppliers. Stakeholders must monitor pending data protection legislation and its interaction with cross-border cloud service arrangements.
Market Dynamics
Cambodia's ICT sector is undergoing a structural transformation driven by the Ministry of Posts and Telecommunications' spectrum reallocation mandates, which force operators to consolidate infrastructure investments while expanding rural coverage obligations.
Growth Catalysts
- Mobile Financial Services Regulation:The National Bank of Cambodia's licensing framework for payment service providers accelerates digital wallet penetration among unbanked agricultural households.
- Submarine Cable Landings:New fiber-optic cable systems landing in Sihanoukville reduce international bandwidth costs for domestic internet service providers.
- Smart City Phnom Penh:Municipal digitization contracts create concentrated demand for integrated surveillance, traffic management, and e-government platforms.
Market Restraints
- Imported Equipment Dependence:BIS-equivalent certification requirements for networking hardware extend procurement cycles by 4-6 months for base station components.
- Power Infrastructure Gaps:Unreliable grid connectivity in Kampong Thom and Preah Vihear provinces elevates diesel generator costs for rural tower operators.
- Limited Fixed-Line Legacy:Sparse copper network density prevents hybrid fiber-copper upgrade paths, forcing full fiber-overbuild investments.
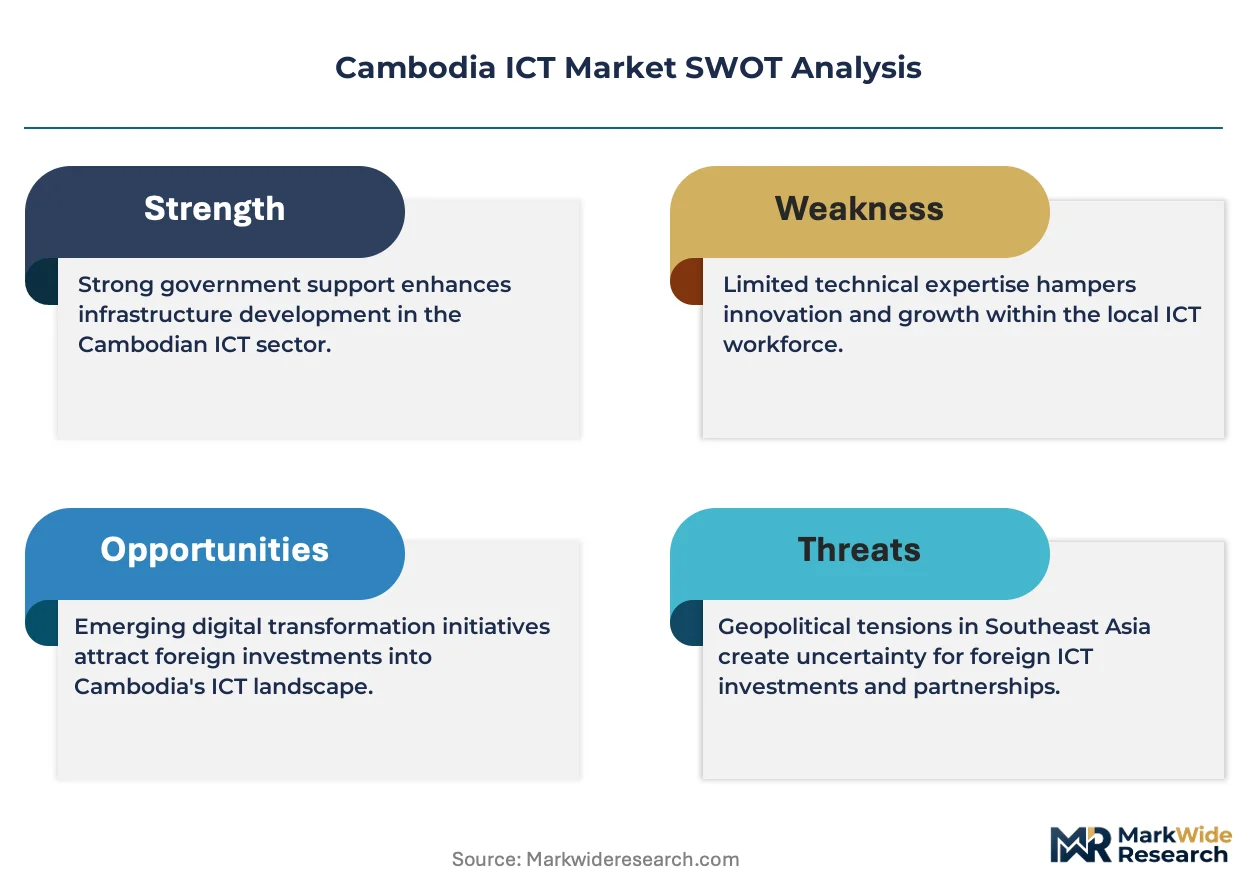
Strategic Opportunities
- Siem Reap-Tonle Sap Corridor:Tourism-dependent provinces lack enterprise-grade connectivity, creating whitespace for SD-WAN services targeting hospitality chains.
- Agricultural IoT Convergence:Integration of drone-based crop monitoring with mobile money platforms enables precision farming subscription models.
- Data Center Localization:Pending data sovereignty provisions in draft cybersecurity legislation incentivize edge computing facilities in Phnom Penh Special Economic Zone.
Industry Challenges
- Network Engineer Scarcity:Domestic universities produce fewer than 200 certified telecommunications specialists annually, forcing reliance on Vietnamese and Thai contracting firms.
- Interconnection Disputes:The Telecom Regulator of Cambodia's asymmetric termination rate rulings generate recurring arbitration between incumbent and challenger operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cambodia ICT Market |
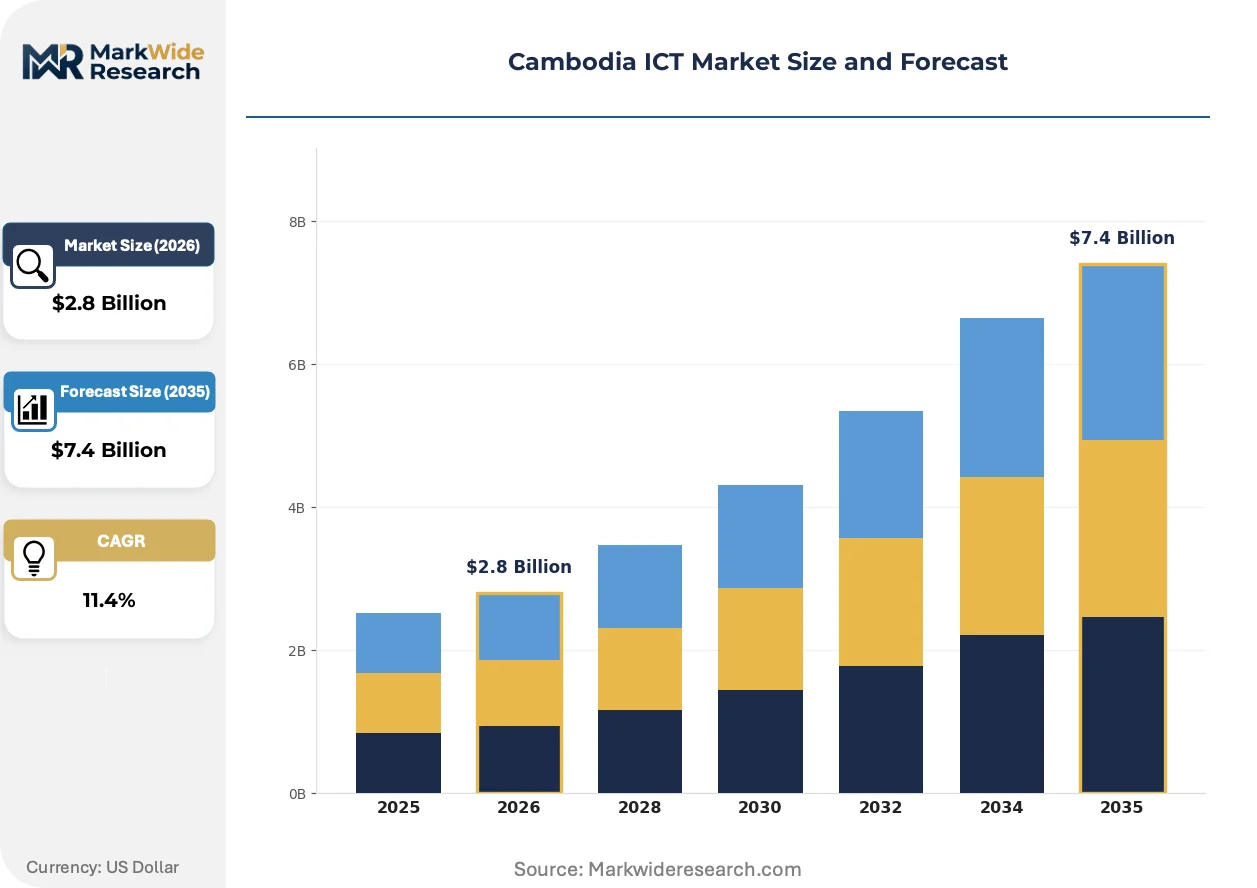
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Cybersecurity, Artificial Intelligence, Big Data Product Type: Software Solutions, Networking Equipment, IT Services, Mobile Devices End User: Businesses, Educational Institutions, Government Agencies, SMEs Service Type: Consulting Services, Implementation, Support Services, Managed Services |
| Companies Covered | EZECOM, Metfone, Smart Axiata, Huawei Technologies, SEATEL Cambodia, Viettel Cambodia, Cambodia Data Communication, IBM, Cellcard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cambodia ICT Market Strategic Shifts
Software-defined architectures are dismantling traditional hardware-centric deployment models across Cambodia's telecommunications infrastructure. Three concurrent developments are restructuring competitive positioning.
Open RAN architectures are modularizing base station hardware into interoperable subcomponents. Tier-two operators in Battambang and Kampong Cham are piloting multi-vendor radio access networks to reduce dependency on single-source equipment suppliers. This decomposition is modularizing capital deployment, allowing incremental capacity expansion without full site rebuilds.
The Telecom Regulator of Cambodia's 2024 quality-of-service benchmarking regime mandates continuous latency and packet-loss reporting. Operators must now install passive monitoring probes at provincial exchange points, increasing compliance overhead but creating transparency differentials for enterprise SLA marketing. Wholesale bandwidth resellers face the steepest adaptation costs as retail clients demand verifiable performance data.
SME purchasing patterns are compressing contract durations for cloud infrastructure from annual to quarterly renewal cycles. Local system integrators in Phnom Penh's Toul Kork district are responding with pay-as-you-grow compute packages that bundle Microsoft 365 licenses with managed firewall services. This flexibility preference is most pronounced among garment sector exporters seeking to align IT spending with order-book volatility.
Cambodia ICT Market Segmentation
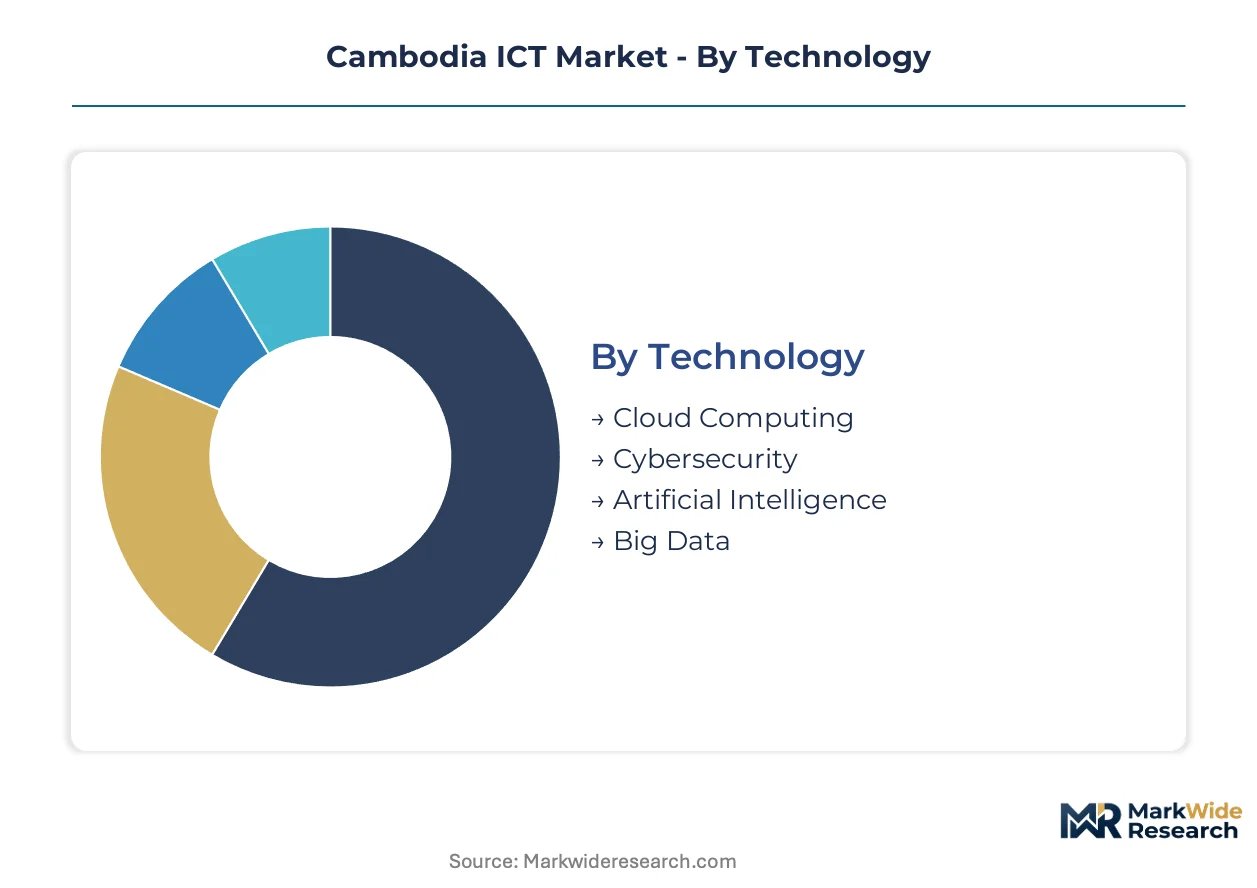
Segmentation in Cambodia's ICT market reveals how infrastructure investment priorities diverge between established enterprise demand and emerging digital service consumption. Understanding these splits enables targeted positioning across Phnom Penh's commercial corridor and provincial expansion zones.
Technology:
Cloud Computing commands premium pricing from multinational-backed enterprises, while Cybersecurity and AI solutions serve mid-market adopters seeking compliance-ready platforms.
- Cloud Computing:Subscription-based infrastructure delivery enables SMEs to bypass capital-intensive server procurement. Demand concentrates in Phnom Penh's garment export sector, where seasonal order fluctuations require elastic compute capacity without fixed overhead.
- Cybersecurity:Network perimeter defense, endpoint protection, and compliance auditing services address the National Bank of Cambodia's tightening data protection expectations. Financial institutions in the capital's emerging fintech corridor drive procurement as digital wallet penetration expands.
- Artificial Intelligence:Machine learning applications for credit scoring and agricultural yield prediction attract development-stage investment from mobile network operators.
- Big Data:Analytics platforms processing transaction flows and customer behavior patterns support retail banking and e-commerce platform optimization.
Mature deployment sits with Cloud Computing. Newer deployment is concentrated in Artificial Intelligence.
Product Type:
Software Solutions generate recurring revenue through licensing, while Networking Equipment and IT Services reflect project-based procurement cycles tied to infrastructure buildouts.
- Software Solutions:Enterprise resource planning, customer relationship management, and accounting platforms replace legacy systems across family-owned conglomerates. Government tax automation programs create concentrated contract flow through the Ministry of Economy and Finance's digitization mandates.
- Networking Equipment:Routers, switches, and base station components carry BIS-equivalent certification requirements that extend procurement timelines. Mobile operators expanding 4G coverage into Kampong Thom and Preah Vihear provinces absorb the largest equipment volumes.
- IT Services:System integration and legacy migration projects serve banks transitioning from branch-centric to mobile-first service models.
- Mobile Devices:Smartphone distribution channels penetrate agricultural households as mobile money adoption accelerates rural financial inclusion.
Volume leadership belongs to Software Solutions. Margin expansion is concentrating in Networking Equipment.
End User:
Large Businesses anchor professional services demand, while SMEs and Educational Institutions represent volume expansion opportunities with differentiated price sensitivity.
- Businesses:Corporate headquarters and manufacturing facilities require enterprise-grade connectivity with guaranteed service level agreements. Phnom Penh-based conglomerates in real estate and banking drive premium infrastructure spending.
- Government Agencies:National digital identity systems and customs automation platforms command disproportionate contract value through multi-year framework agreements. The Ministry of Posts and Telecommunications channels procurement through centralized tender processes.
- Educational Institutions:Universities and technical colleges seek learning management systems and campus-wide WiFi deployment.
- SMEs:Small retailers and service businesses adopt cloud productivity suites and basic cybersecurity packages through bundled reseller channels.
Contract concentration sits with Government Agencies. Volume growth is accelerating fastest among SMEs.
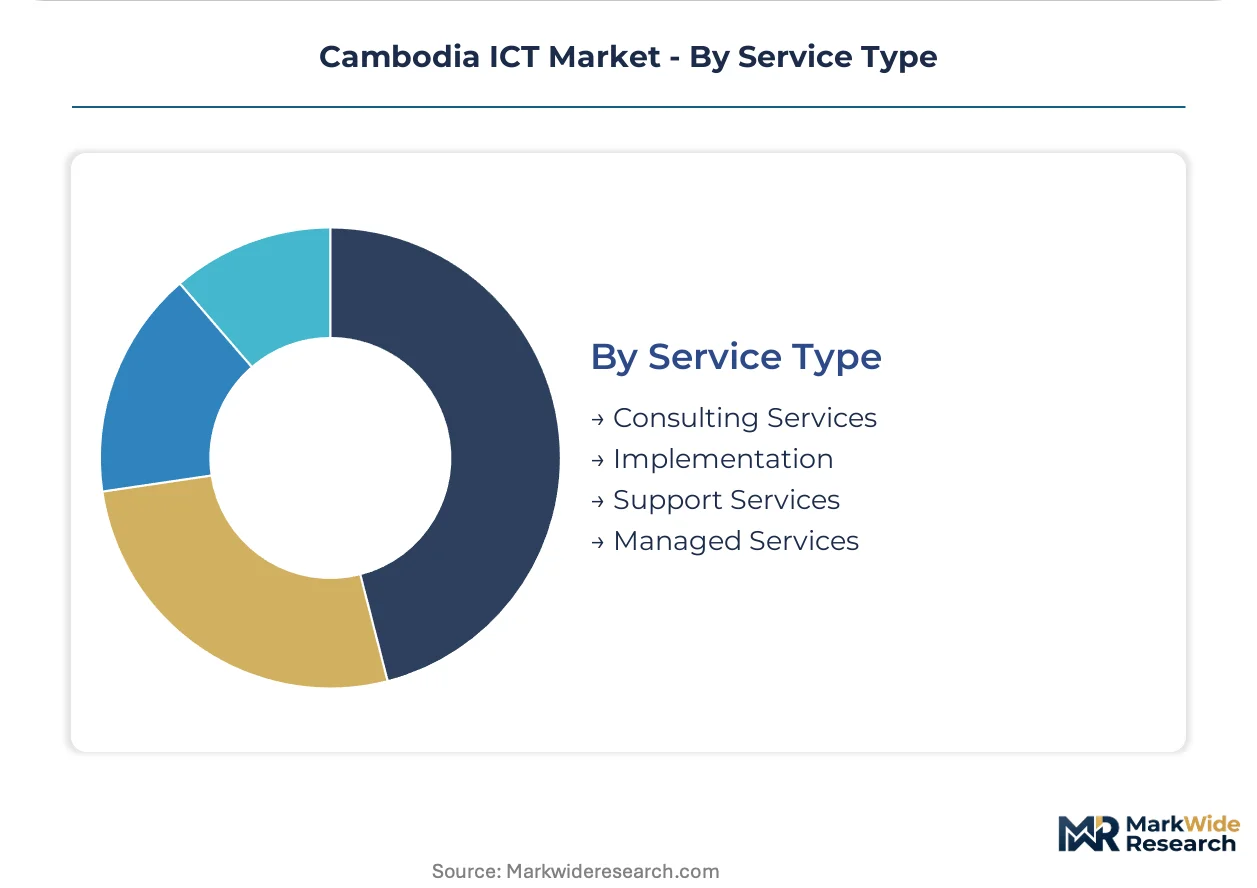
Service Type:
Implementation services capture upfront project value, while Managed Services and Support Services build recurring revenue streams with longer customer lifecycles.
- Implementation:System deployment, data migration, and integration services accompany new software and infrastructure rollouts. Telecom operators expanding fiber-to-the-home in provincial urban centers require specialized contracting capacity.
- Managed Services:Outsourced network monitoring, security operations center functions, and cloud environment management reduce in-house technical staffing requirements. Domestic enterprises facing network engineer scarcity increasingly favor operational expenditure models over captive IT teams.
- Consulting Services:Digital transformation strategy and regulatory compliance advisory support foreign market entrants navigating licensing frameworks.
- Support Services:Help desk, maintenance, and break-fix coverage extend solution lifecycles for cost-conscious mid-market buyers.
Recurring revenue maturity sits with Managed Services. Project-based expansion is concentrating in Implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phnom Penh Special Economic Zone concentrates Cambodia's ICT infrastructure investment through tax incentives and streamlined customs procedures for equipment imports. The zone hosts domestic data center development and enterprise connectivity hubs. Provincial expansion corridors radiate from this capital anchor into emerging commercial zones.
Phnom Penh Capital Region
Financial technology clusters and government digitization programs drive concentrated demand for cloud infrastructure and cybersecurity services. The Ministry of Posts and Telechannels spectrum allocation decisions shape operator investment priorities. Toul Kork district houses system integrators serving garment sector exporters with elastic compute packages.
Siem Reap-Tonle Sap Corridor
Tourism-dependent hospitality chains generate whitespace demand for SD-WAN and enterprise-grade connectivity solutions. The Telecom Regulator of Cambodia's quality-of-service mandates extend coverage obligations into these provinces. Siem Reap city anchors hospitality technology upgrades while surrounding agricultural zones remain underserved.
Sihanoukville Coastal Zone
Submarine cable landings at this port city reduce international bandwidth costs for domestic internet service providers. The Ministry of Posts and Telecommunications licenses submarine cable operators through specialized maritime infrastructure frameworks. Sihanoukville's special economic zone attracts edge computing facilities targeting cross-border data traffic.
Battambang-Kampong Cham Secondary Cities
Open RAN pilot programs in these provincial centers test multi-vendor radio access networks to reduce equipment supplier dependency. The National Bank of Cambodia's mobile financial services regulations accelerate digital wallet penetration among agricultural households. Battambang city hosts tier-two operator infrastructure consolidation projects.
Kampong Thom-Preah Vihear Rural Periphery
Unreliable grid connectivity elevates diesel generator costs for rural tower operators serving sparse populations. The Ministry of Posts and Telecommunications imposes rural coverage obligations as a condition of spectrum license renewal. Mobile money platforms target unbanked agricultural households in these provinces for financial inclusion expansion.
Cambodia ICT Market Competitive Environment
Top-tier vendors anchor nationwide infrastructure deployment, while mid-tier challengers compete through provincial fiber expansion and specialized enterprise services. The market exhibits tiered concentration around mobile network operators with integrated fixed-line capabilities. Three archetypes dominate: spectrum-rich incumbents with 4G coverage depth, fiber-focused challengers targeting provincial urban centers, and enterprise specialists delivering leased-line services to commercial districts. Competitive moves center on infrastructure sharing agreements and fiber-to-the-home rollout acceleration.
Within the integrated operator tier, Smart Axiata and Metfone exemplify contrasting geographic strategies. EZECOM occupies a position as the enterprise connectivity specialist. Huawei Technologies represents the equipment supply archetype underpinning base station deployment cycles. Cellcard and SEATEL Cambodia sit within the challenger tier competing for mobile subscriber share through pricing differentiation.
| Leading Market Players |
|---|
| EZECOM |
| Metfone |
| Smart Axiata |
| Huawei Technologies |
| SEATEL Cambodia |
| Viettel Cambodia |
| Cambodia Data Communication |
| IBM |
| Cellcard |
| Others |
Value Chain & Pricing Dynamics
Open RAN modularization is dismantling single-vendor lock-in across Cambodia's base station deployments, compressing hardware procurement costs while fragmenting supplier concentration across interoperable subcomponent vendors. This decomposition simultaneously enables tier-two operators to negotiate volume discounts and forces incumbents to absorb integration complexity premiums.
Pricing Analysis
Lead-time-driven pricing stratification dominates equipment procurement, with BIS-equivalent certification timelines extending base station component delivery windows by four to six months and commanding premium placement fees. Subscription-based cloud infrastructure carries three-tier pricing differentiation across enterprise, mid-market, and micro-SME tiers, with garment sector exporters driving elasticity demands. Cost compression in provincial fiber expansion is intensifying because diesel generator dependencies in Kampong Thom and Preah Vihear elevate operational expenditure burdens. Government agencies exhibit lowest price sensitivity due to multi-year framework agreement structures, while agricultural household mobile money adopters represent the most price-constrained segment.
Supply Chain Analysis
Dual-sourcing mandates from the Telecom Regulator of Cambodia's quality-of-service benchmarking regime require operators to qualify passive monitoring probe suppliers from multiple vendor ecosystems. Hardware procurement draws from China, South Korea, and Vietnam for base station components, optical transmission equipment, and fiber cable respectively. Critical dependencies center on 700 MHz to 2.6 GHz spectrum-compatible radio units, submarine cable landing station equipment, and diesel generator sets for rural tower sites. Single-source vulnerability concentrates in proprietary RAN software stacks pending Open RAN interoperability maturation. Distribution runs through Phnom Penh-based system integrators in Toul Kork district for enterprise cloud bundles, with direct operator procurement dominating networking equipment flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cambodia's ICT sector presents a consolidation play as spectrum reallocation mandates and rural coverage obligations force subscale operators into asset-light repositioning or exit. The Ministry of Posts and Telecommunications' infrastructure sharing requirements accelerate this pressure.
For Market Incumbents: Extend fiber-to-the-home coverage depth in Battambang and Kampong Cham to preempt challenger land grabs, while consolidating Open RAN pilot investments to reduce Huawei dependency exposure. Vertical integration into edge computing facilities within Phnom Penh Special Economic Zone captures data localization premiums from pending cybersecurity legislation. For New Entrants and Emerging Players: Direct-to-SME cloud resale channels through Toul Kork system integrators bypass capital-intensive infrastructure buildouts while capturing quarterly renewal cycle flexibility preferences. Target Siem Reap hospitality chains with SD-WAN services where incumbent enterprise-grade coverage remains whitespace, leveraging pay-as-you-grow compute packaging to align with seasonal tourism revenue volatility. For Investors and Strategic Acquirers: Exit pathways concentrate in fiber-focused challengers with provincial urban center footprints, as Smart Axiata and Metfone seek coverage-gap fill-through acquisition over greenfield build. Long-term viability hinges on spectrum portfolio depth and data center localization readiness. The signal to watch is Ministry of Posts and Telecommunications enforcement timing on data sovereignty provisions in draft cybersecurity legislation.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Infrastructure Deployment | Multi-vendor radio access networks reduce single-source equipment dependency for tier-two operators in provincial centers. |
| Submarine Cable Capacity Expansion | Sihanoukville landing station investments lower international bandwidth costs for domestic internet service providers. |
| Edge Computing Facility Localization | Phnom Penh Special Economic Zone data centers capture data sovereignty premiums from pending cybersecurity legislation. |
| Agricultural IoT Platform Integration | Drone-based crop monitoring bundled with mobile money enables precision farming subscription models in rice belt provinces. |
| Managed Services Portfolio Buildout | Outsourced security operations center functions address domestic network engineer scarcity through operational expenditure models. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with telecom network engineers, Ministry of Posts and Telecommunications licensing officials, garment sector IT procurement officers, and cloud system integrators. Secondary sources encompassed Telecom Regulator of Cambodia quality-of-service reports, National Bank of Cambodia payment service provider licensing databases, and submarine cable operator maritime infrastructure disclosures. Bottom-up demand modeling across enterprise connectivity, government digitization, and rural financial inclusion segments triangulated against top-down infrastructure investment flow analysis.
Granularity-level modeling deployed technology dimension splits across cloud computing, cybersecurity, artificial intelligence, and big data analytics, with end-user segmentation distinguishing government agency framework agreements from SME quarterly renewal patterns. Product type differentiation captured software solutions licensing cycles against networking equipment project-based procurement. CAGR derivation reflected subscriber penetration curves, base station deployment schedules, and data center capacity absorption rates across the projection horizon. Forecast inputs incorporated spectrum reallocation timelines, submarine cable landing schedules, and rural electrification progress indicators.
Inputs from regulatory filings and operator disclosures were available through the study window; gaps in draft cybersecurity legislation finalization and data protection rule enforcement timing introduce uncertainty bands around data localization investment forecasts. Deviation in Ministry of Posts and Telecommunications rural coverage obligation enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Indonesia ICT Market
Telecommunications
Brazil Telecom Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Global 4G LTE Market
Telecommunications
Germany ICT Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
Chile Telecom Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
Denmark ICT Market
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
IP Telephony Market
Telecommunications
5G Equipment Market
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
Managed M2M Services Market
Telecommunications
Land Professional Mobile Radio Market