
 Philippines Telecom Market | 2026-2036
Philippines Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Telecom Market Outlook
Copper infrastructure is pivoting toward fiber optic cable as the dominant transmission medium across Philippine archipelago networks. PLDT leverages its legacy right-of-way agreements to accelerate fiber deployment across Luzon island clusters. Globe Telecom sustains capital intensity in 5G radio access networks while competing in prepaid mobile segments. Converge Information and Communications Technology Solutions anchors its position in residential broadband through pure-fiber plays in underserved provincial markets.
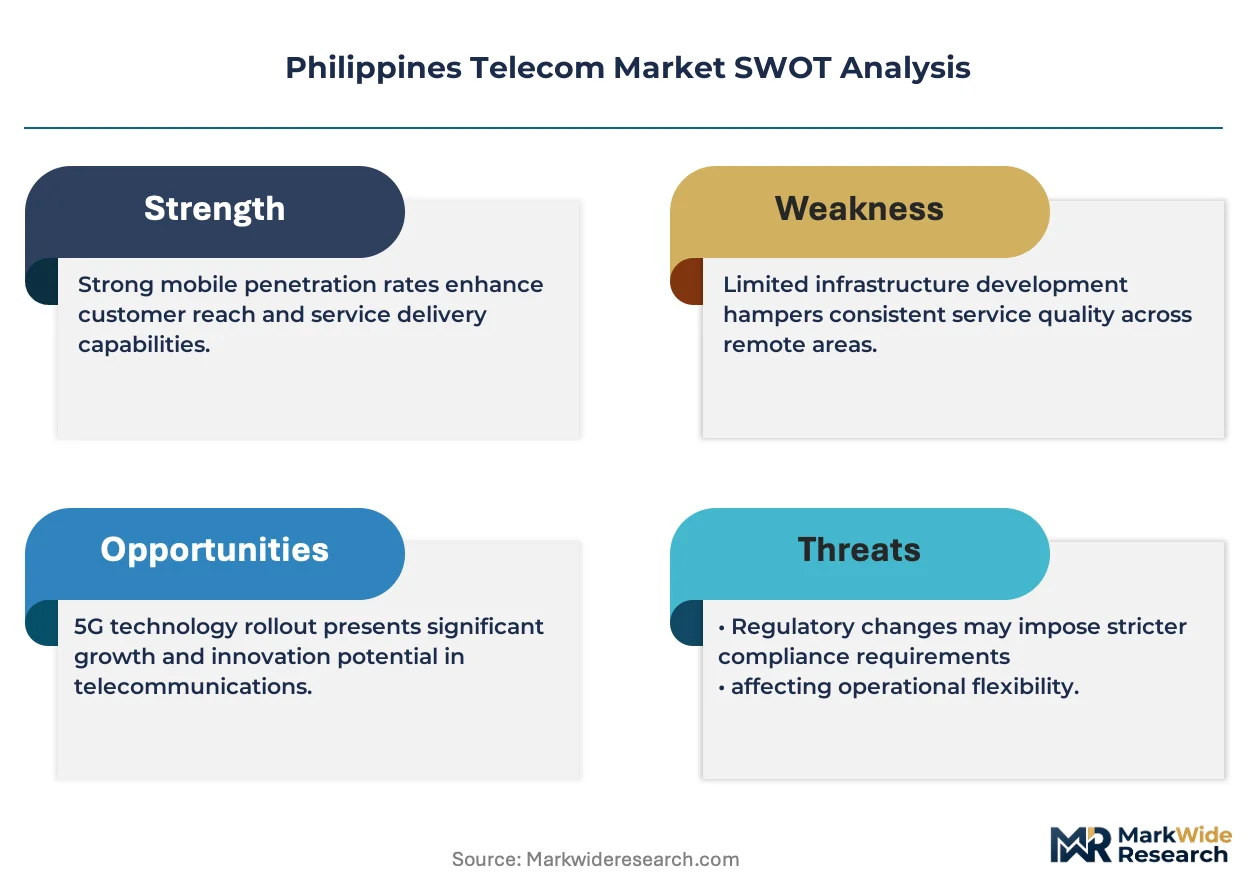
Philippines Telecom encompasses wireless and wireline communication services delivered through cellular towers, submarine cables, terrestrial fiber, and satellite links operating across frequencies from 700 MHz to 28 GHz. The sector enables voice, data, and multimedia transmission for consumer, enterprise, and government end users across an archipelago of over 7,600 islands. Mobile service currently generates the largest revenue pool among service types, though fiber broadband represents the fastest-expanding segment as household penetration remains below regional peers. 5G technology deployment is concentrating in dense urban corridors, while 4G LTE continues to dominate subscriber volumes across provincial areas where return on infrastructure investment constrains next-generation rollout.
The National Telecommunications Commission governs spectrum allocation and interconnection rules, while the Department of Information and Communications Technology oversees the National Broadband Plan that shapes public-private deployment priorities. The DICT's common tower policy reduces infrastructure duplication costs and accelerates site builds in geographically challenging terrain. Stakeholders must monitor spectrum auction timelines and tower permitting efficiency as determinants of capital deployment velocity across the Philippine archipelago.
Market Dynamics
Fiber-to-the-home deployment is electrifying capital allocation across Philippine telecom infrastructure as the National Broadband Plan mandates universal connectivity targets by 2028. Tower sharing agreements and spectrum refarming are compressing deployment timelines while intensifying competition for site permits in dense urban corridors.
Growth Catalysts
- Common Tower Policy:The DICT's infrastructure sharing framework reduces site duplication costs and accelerates 5G radio access network builds across geographically challenging terrain.
- Prepaid Mobile Data:Mass-market consumer segments in provincial areas drive subscriber volume expansion through affordable data packages and digital wallet integration.
- Submarine Cable Systems:New international bandwidth capacity landing in Batangas and La Union is electrifying domestic backhaul economics and reducing transit dependency.
Market Restraints
- Right-of-Way Friction:Local government permitting delays for fiber trenching in Metro Manila constrain last-mile deployment velocity despite national policy mandates.
- Copper Stranding Risk:Legacy DSL infrastructure in secondary cities faces accelerated depreciation as subscriber migration to fiber compresses residual value recovery timelines.
- Geographic Dispersion:The archipelago's 7,600 islands fragment backhaul economics and elevate satellite dependency for remote barangay connectivity.
Strategic Opportunities
- Mindanao Island Cluster:Underserved provinces in the southern Philippines present fiber greenfield opportunities with lower competitive intensity than Luzon markets.
- Enterprise SD-WAN:Financial services and business process outsourcing verticals are electrifying demand for managed network services with guaranteed latency tiers.
- Open RAN Architecture:Multi-vendor radio access network disaggregation creates procurement alternatives to incumbent equipment suppliers in 5G densification projects.
Industry Challenges
- Fiber Splicing Technician Scarcity:Specialized workforce gaps in provincial labor markets delay activation timelines and elevate contractor costs for last-mile completion.
- Legacy Billing Integration:Convergent service bundles require real-time charging platform overhauls that strain IT transformation budgets and extend vendor lock-in periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Telecom Market |
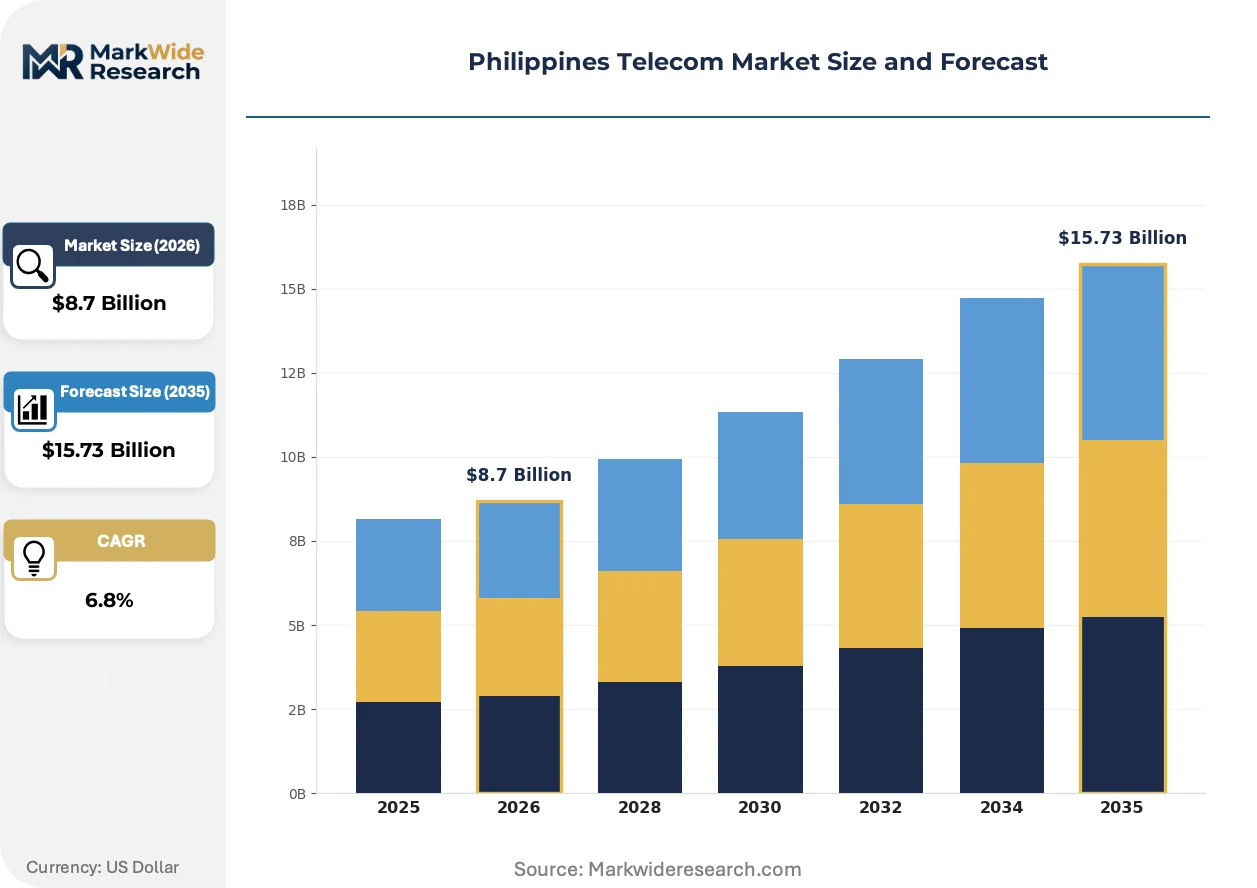
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed Line, Internet, Broadband Technology: 3G, 4G LTE, 5G, Fiber Optic Customer Type: Consumer, Corporate, Government, SME Distribution Channel: Retail, Online, Direct Sales, Partners |
| Companies Covered | DITO Telecommunity, Radius Telecom, Globe Telecom, Cignal, Bayantel, Smart Communications, Converge Information and Communications Technology Solutions, NOW Telecom, PLDT, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Telecom Market Strategic Shifts
Network virtualization and spectrum efficiency technologies are compressing infrastructure economics while enabling service differentiation beyond raw bandwidth metrics. Philippine operators are electrifying software-defined capabilities to automate provisioning and reduce operational expenditure intensity.
Open radio access network standards are electrifying vendor diversification in 5G deployments as PLDT and Globe Telecom trial multi-supplier configurations for urban small cell densification. The shift reduces single-source dependency on traditional equipment providers while introducing interoperability testing complexity that delays commercial launch timelines.
The National Telecommunications Commission's 2023 spectrum reallocation framework is compressing available bandwidth for legacy 3G services and mandating accelerated refarming toward 4G and 5G bands. Mobile network operators must retire circuit-switched voice infrastructure and migrate subscribers to VoLTE platforms, with rural coverage obligations attached to new frequency assignments.
Enterprise procurement of connectivity services is electrifying toward consumption-based models with guaranteed service level agreements rather than fixed port contracts. Financial services and logistics verticals in Metro Manila and Cebu are adopting usage-variable pricing with latency penalties, displacing traditional committed information rate structures in managed service negotiations.
Philippines Telecom Market Segmentation
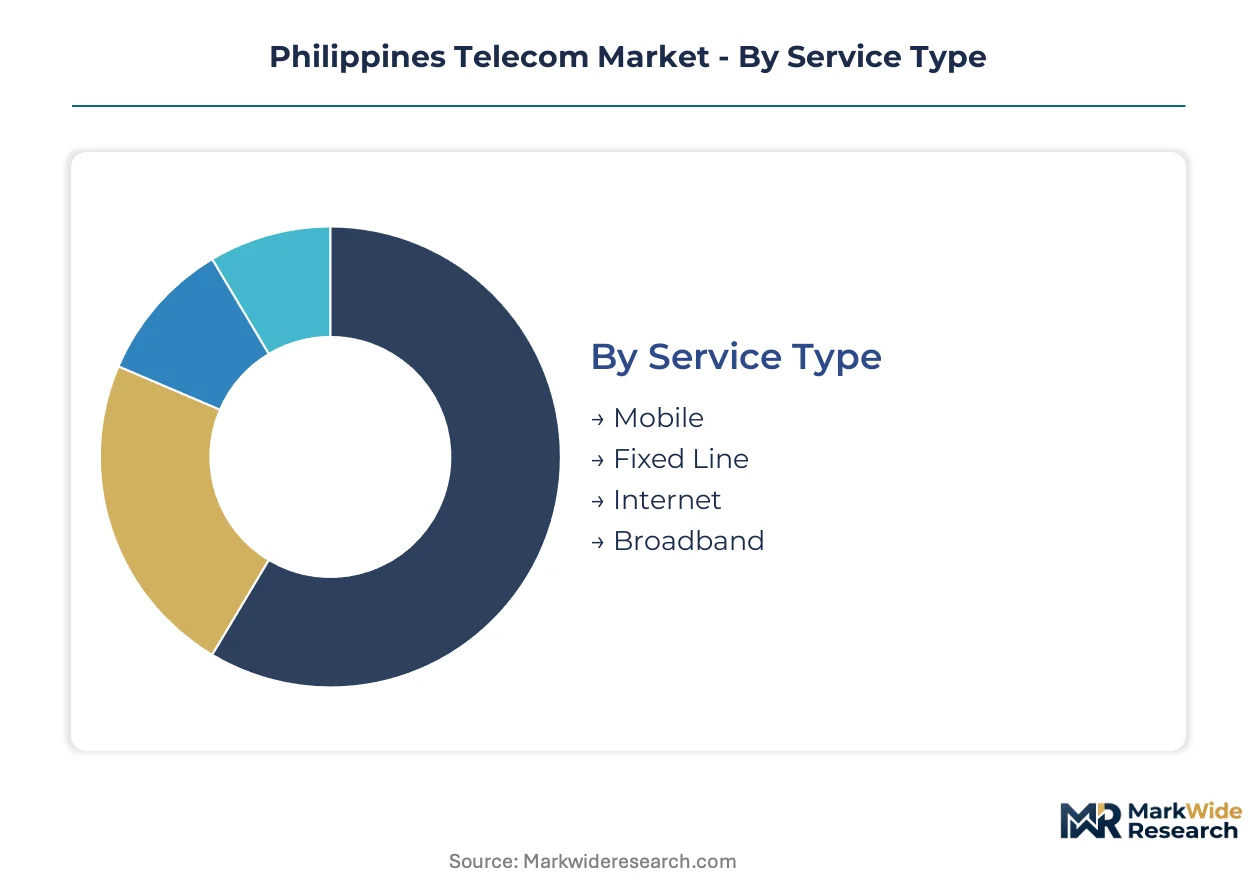
Telecom segmentation in the Philippines reveals divergent infrastructure economics across service delivery modes. Understanding these partitions clarifies where capital deployment yields differential returns across the archipelago's fragmented geography.
Service Type:
Customization intensity varies sharply across this category, from standardized mass-market mobile packages to bespoke enterprise connectivity contracts with guaranteed service levels.
- Mobile:Voice and data services delivered through cellular infrastructure dominate subscriber volumes nationwide. Prepaid data packages in provincial CALABARZON and Central Visayas regions electrify volume expansion as digital wallet integration reduces friction for unbanked consumers.
- Internet:Narrowband and legacy DSL services persist in secondary cities where fiber trenching economics remain marginal. Subscriber migration to fiber broadband compresses residual value timelines for copper-dependent infrastructure.
- Broadband:High-speed fiber-to-the-home connections represent the steepest expansion trajectory as the National Broadband Plan mandates universal connectivity targets. Metro Manila households drive initial penetration, with provincial rollouts accelerating through common tower policy facilitation.
- Fixed Line:Legacy copper-based voice services face structural decline as VoLTE platforms displace circuit-switched infrastructure. Government and enterprise retention contracts sustain limited deployment in central business districts.
Most installed capacity flows through Mobile. Expansion is steepest in Broadband.
Technology:
Cost tier differentiation separates mature spectrum bands with depreciated infrastructure from capital-intensive next-generation deployments requiring fresh radio access network builds.
- 4G LTE:Dominant subscriber technology across provincial areas where return on infrastructure investment constrains 5G densification. The 700 MHz and 2600 MHz bands carry bulk data traffic outside Metro Manila corridors.
- 5G:Millimeter-wave and sub-6 GHz deployments concentrate in dense urban corridors with tower infrastructure density supporting radio access network economics. Site permitting efficiency in Metro Manila and Cebu determines commercial launch velocity.
- Fiber Optic:Pure-fiber transmission infrastructure anchors the National Broadband Plan's universal connectivity mandate. Submarine cable landings in Batangas and La Union electrify domestic backhaul capacity for island-wide deployment.
- 3G:Spectrum refarming mandates from the National Telecommunications Commission compress available bandwidth for legacy circuit-switched services. Accelerated retirement timelines attach to new frequency assignments.
4G LTE carries the majority of active subscriptions. 5G claims the fastest capacity addition rate.
Customer Type:
Volume concentration sits with mass-market segments, while margin accretion concentrates in contractual relationships with guaranteed service level agreements.
- Consumer:Individual and household subscribers purchasing prepaid mobile data and residential broadband packages. Provincial barangay electrification through affordable data bundles expands addressable market reach.
- Corporate:Large enterprises in financial services and business process outsourcing verticals procuring managed network services with latency guarantees. Metro Manila and Cebu operations anchor demand concentration.
- SME:Small and medium enterprises adopting converged voice-data packages with flexible scaling terms. Digital transformation subsidies from the Department of Information and Communications Technology accelerate adoption curves.
- Government:National and local government units procuring connectivity for administrative operations and public service delivery. National Broadband Plan procurement frameworks standardize vendor selection.
Consumer segments generate the largest revenue pool. Corporate contracts yield the highest per-connection margins.
Distribution Channel:
Customer acquisition economics diverge between high-touch relationship management for enterprise accounts and low-friction digital onboarding for prepaid mobile segments.
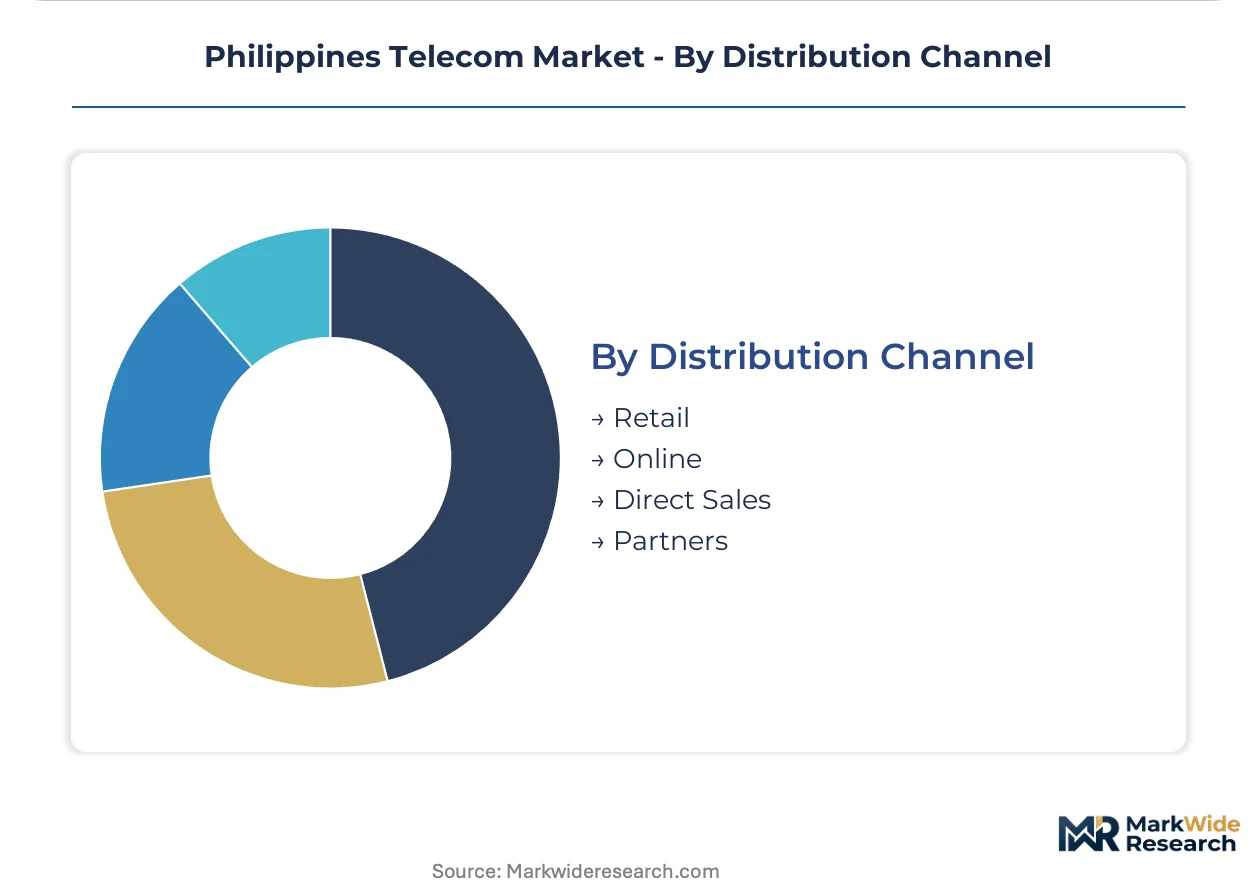
- Retail:Physical storefronts and authorized dealer networks distribute SIM cards and prepaid load in high-foot-traffic locations. Provincial mall presence determines market share in secondary cities.
- Online:Digital platforms enable SIM-to-door delivery and electronic wallet integration for prepaid top-ups. Metro Manila smartphone penetration supports highest conversion rates.
- Direct Sales:Enterprise account teams negotiate customized connectivity contracts with guaranteed service levels. Relationship tenure correlates with contract renewal probability.
- Partners:System integrators and value-added resellers bundle connectivity with adjacent IT services. Financial services and logistics verticals prefer consolidated procurement relationships.
Retail maintains the widest geographic footprint. Online channels are climbing the fastest in transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila anchors Philippine telecom infrastructure investment as tower density and fiber deployment accelerate across the capital region. The National Broadband Plan shapes connectivity priorities nationwide. Sub-regional variation in infrastructure economics creates divergent competitive dynamics across the archipelago.
Metro Manila
Corporate SD-WAN procurement from financial services and BPO verticals electrifies enterprise connectivity demand in Makati and Ortigas central business districts. The National Telecommunications Commission's spectrum reallocation framework mandates VoLTE migration timelines that compress legacy infrastructure value. 5G small cell densification concentrates in Bonifacio Global City and Quezon City corridors where site permitting efficiency determines rollout velocity.
CALABARZON
Prepaid mobile data adoption among unbanked consumer segments expands subscriber volumes across Cavite, Laguna, Batangas, Rizal, and Quezon provinces. The Department of Information and Communications Technology's common tower policy reduces infrastructure duplication costs and accelerates site builds. Batangas hosts submarine cable landings that electrify domestic backhaul capacity for island-wide fiber deployment.
Central Visayas
Cebu City's business process outsourcing cluster generates concentrated demand for managed network services with latency guarantees. The DICT's digital transformation subsidies accelerate SME adoption of converged voice-data packages. Mactan Island and Cebu City proper anchor submarine cable connectivity that reduces transit dependency for Visayas island networks.
Davao Region
Mindanao's southern provinces present fiber greenfield opportunities with lower competitive intensity than saturated Luzon markets. The National Broadband Plan's universal connectivity targets by 2028 mandate public-private deployment partnerships in underserved areas. Davao City anchors regional backhaul infrastructure while surrounding provinces rely on satellite links for remote barangay connectivity.
Ilocos Region
La Union's submarine cable landing points diversify international bandwidth entry away from Batangas concentration. The DICT's infrastructure sharing framework facilitates tower builds across geographically challenging terrain in northern Luzon. San Fernando City and Laoag anchor provincial fiber deployment as right-of-way agreements with legacy utilities accelerate trenching timelines.
Philippines Telecom Market Competitive Environment
Global equipment vendors compete with regional infrastructure champions across radio access network procurement and submarine cable deployment. The Philippine market structures around three distinct tiers: integrated incumbents with legacy right-of-way portfolios, pure-fiber challengers targeting underserved provincial markets, and mobile-focused operators sustaining prepaid segment dominance. Strategic moves concentrate on tower sharing agreements, spectrum refarming partnerships, and fiber-to-the-home greenfield expansion in Mindanao island clusters.
Among integrated incumbents, PLDT and Globe Telecom occupy positions shaped by decades of infrastructure accumulation and regulatory relationship depth. Converge Information and Communications Technology Solutions exemplifies the pure-fiber challenger archetype, anchoring residential broadband growth through provincial market focus without legacy mobile infrastructure burdens. DITO Telecommunity represents the third-force mobile operator model, competing for prepaid subscriber volumes against established duopoly positions.
| Leading Market Players |
|---|
| DITO Telecommunity |
| Radius Telecom |
| Globe Telecom |
| Cignal |
| Bayantel |
| Smart Communications |
| Converge Information and Communications Technology Solutions |
| NOW Telecom |
| PLDT |
| Others |
Value Chain & Pricing Dynamics
Family-owned regional tower contractors anchor infrastructure deployment across the Philippine archipelago, concentrating supply-side bargaining power while compressing margins for multinational equipment vendors competing for radio access network contracts. Their entrenched local government relationships shape site permitting economics and filter pricing discipline through to end-user subscription rates.
Pricing Analysis
Input-cost pass-through from submarine cable landing fees and spectrum auction premiums filters into subscriber pricing through three-tier structures across premium fiber, standard LTE, and economy prepaid tiers. Price differentiation rests on bandwidth guarantees and installation priority timelines, with enterprise SD-WAN contracts commanding the highest premiums. Cost compression in the prepaid mobile segment intensifies as DITO Telecommunity challenges established duopoly positions. Consumer households in provincial barangays exhibit the steepest price sensitivity, while corporate BPO contracts in Makati and Cebu tolerate premium positioning for latency-assured connectivity.
Supply Chain Analysis
Regional distribution centers in Metro Manila and Cebu anchor hub-and-spoke logistics for radio access network equipment, with secondary nodes in Davao serving Mindanao island clusters. The supply chain draws from China for base station hardware, South Korea for fiber optic cable, and Japan for precision components. Single-source vulnerability concentrates in 5G millimeter-wave antenna supply where Huawei and Ericsson dominate procurement pipelines. Distribution runs through authorized dealer networks and direct carrier procurement teams, with tower co-location agreements reducing redundant infrastructure transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines Telecom Market functions as a geographic-arbitrage play where fiber deployment costs in Mindanao undercut Luzon saturation levels by half, while regulatory permitting velocity in CALABARZON provinces outpaces Metro Manila right-of-way friction.
For Market Incumbents: Deepen vertical integration into submarine cable landing infrastructure to secure backhaul cost advantages against emerging fiber challengers. Accelerate VoLTE platform migration ahead of National Telecommunications Commission spectrum refarming mandates to preserve subscriber retention. Lock in common tower partnerships with DICT-accredited infrastructure providers to forestall site permit competition from DITO Telecommunity expansion. For New Entrants and Emerging Players: Enter via underserved provincial Mindanao markets where fiber penetration lags Luzon benchmarks by years and competitive intensity remains muted. Target SME segments in Davao City and Cagayan de Oro with converged voice-data bundles subsidized by DICT digital transformation grants. Deploy direct sales teams with guaranteed installation timelines to differentiate against incumbent service backlogs. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-fiber challengers lacking legacy mobile infrastructure burdens yet commanding residential broadband growth trajectories. Long-term viability hinges on National Broadband Plan execution continuity across political cycles. Monitor DICT common tower accreditation velocity as the inflection signal for infrastructure deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-to-the-Home Expansion | Addresses universal connectivity mandates under the National Broadband Plan while capturing provincial household migration from legacy DSL. |
| Common Tower Partnership | Reduces site duplication costs and accelerates 5G radio access network builds across geographically challenging terrain. |
| VoLTE Platform Migration | Preserves spectrum allocation under National Telecommunications Commission refarming rules while retiring circuit-switched infrastructure. |
| Enterprise SD-WAN Launch | Captures financial services and BPO vertical demand for managed network services with guaranteed latency tiers in Metro Manila. |
| Submarine Cable Diversification | La Union landing points reduce Batangas transit dependency and electrify domestic backhaul economics for Visayas island networks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with network planning executives at PLDT and Globe Telecom, DICT policy officers, tower infrastructure contractors, and enterprise procurement leads at BPO operators. Secondary validation drew from National Telecommunications Commission spectrum allocation records, DICT National Broadband Plan progress reports, submarine cable landing statistics, and SEC filings of listed carriers. Bottom-up subscriber projections and top-down infrastructure investment flows were triangulated against regional deployment announcements.
Segment-weighting approaches modeled service type, technology generation, customer archetype, and distribution channel dimensions across the projection horizon. CAGRs were derived from historical penetration trajectories and policy-mandated deployment schedules. Forecast inputs incorporated common tower build-out rates, fiber splicing technician availability curves, and right-of-way permitting velocity by province.
Inputs from regulatory filings and carrier disclosures were available through the study window; gaps in real-time tower construction data and provincial labor market statistics introduce uncertainty bands around infrastructure rollout timelines. Forecasts reflect documented assumptions regarding National Broadband Plan funding continuity and spectrum auction timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
South Africa Telecom Market
Telecommunications
5G RAN Market
Telecommunications
GPON Equipment Market
Telecommunications
Russia ICT Market
Telecommunications
Prepaid Communication Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Norway Telecom Market
Telecommunications
Cloud PBX Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Denmark ICT Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Voip Phone Market
Telecommunications
A2P Messaging Market
Telecommunications
5G Connections Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Egypt Telecom Market