
 Global Underwater Acoustic Communication Market | 2026-2036
Global Underwater Acoustic Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Global Underwater Acoustic Communication Market Outlook
Project finance structures tied to long-term defense service contracts are reshaping competitive entry in underwater acoustic communication. Teledyne Technologies leverages its integrated sensor-to-platform portfolio to capture multi-year naval awards. Kongsberg Gruppen anchors its position through captive control over transducer manufacturing and Norwegian fjord test facilities. L3Harris Technologies competes by specializing in frequency-hopping encryption layers for classified subsea datalinks.
Underwater acoustic communication transmits data through pressure waves in marine environments, typically operating below 100 kHz to minimize absorption loss across seawater channels with salinity-dependent attenuation curves. The technology serves military command networks, offshore energy infrastructure monitoring, and distributed oceanographic sensor grids. Acoustic modems dominate current revenue as navies retrofit legacy platforms with software-defined waveform capability. Spread spectrum architectures represent the fastest-expanding technology segment because they suppress multipath interference in shallow continental shelf operations. Defense end users command the deepest margin pools due to classified certification barriers and decade-long platform integration cycles.
The US Navy's underwater communication certification protocols, NATO's STANAG standards for interoperable sonar datalinks, and Japan's METI guidelines for marine resource exploration equipment collectively dictate product roadmaps and market access timelines. ISO 9001 and IEC 60529 ingress protection ratings further constrain supplier qualification for permanent subsea installations. Stakeholders must monitor how autonomous underwater vehicle swarm architectures will redistribute demand between centralized hub modems and distributed peer-to-peer acoustic nodes.
Market Dynamics
Autonomous underwater vehicle swarm architectures are redistributing demand between centralized hub modems and distributed peer-to-peer acoustic nodes, compressing procurement cycles and fragmenting supplier relationships.
Growth Catalysts
- STANAG Interoperability Mandates:NATO's standardized sonar datalink protocols force cross-border equipment compatibility, compelling member navies to upgrade legacy platforms with software-defined waveform capability.
- Offshore Energy Infrastructure:Subsea sensor networks for pipeline monitoring and carbon capture verification drive modem deployment across continental shelf operations in the North Sea and Gulf of Mexico.
- Spread Spectrum Encoding:Advances in low-frequency spread spectrum architectures suppress multipath interference, extending reliable transmission ranges beyond traditional shallow-water limits into deep-ocean environments.
Market Restraints
- Transducer Supply Concentration:Captive manufacturing capabilities cluster in Norwegian and Japanese defense-industrial bases, creating single-source vulnerabilities for NATO procurement programs.
- Salinity-Dependent Attenuation:Seawater absorption curves vary unpredictably across temperature and salinity gradients, degrading link reliability in littoral zones with freshwater influx.
- Decade-Long Platform Integration:Submarine and autonomous vehicle certification cycles lock modem suppliers into fixed-price development contracts with limited margin recovery mechanisms.
Strategic Opportunities
- Indo-Pacific Fleet Expansion:Japan's METI guidelines for marine resource exploration equipment create aligned demand for dual-use acoustic modems serving both defense and commercial seabed mining applications.
- Software-Defined Radio Convergence:Integration of reconfigurable FPGA architectures with acoustic transducer arrays enables single-platform support for multiple waveform standards, collapsing hardware SKU requirements.
- Peer-to-Peer Mesh Architectures:Swarm-based autonomous vehicle coordination eliminates centralized hub dependencies, opening modular node sales to non-traditional defense contractors.
Industry Challenges
- Classified Certification Barriers:US Navy underwater communication protocols require cleared personnel and facility infrastructure, excluding commercial suppliers from margin-rich defense contracts.
- Multipath Compensation Engineering:Shallow-water channel modeling demands specialized acoustic propagation expertise, constraining talent pools to university research labs and legacy sonar manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Underwater Acoustic Communication Market |
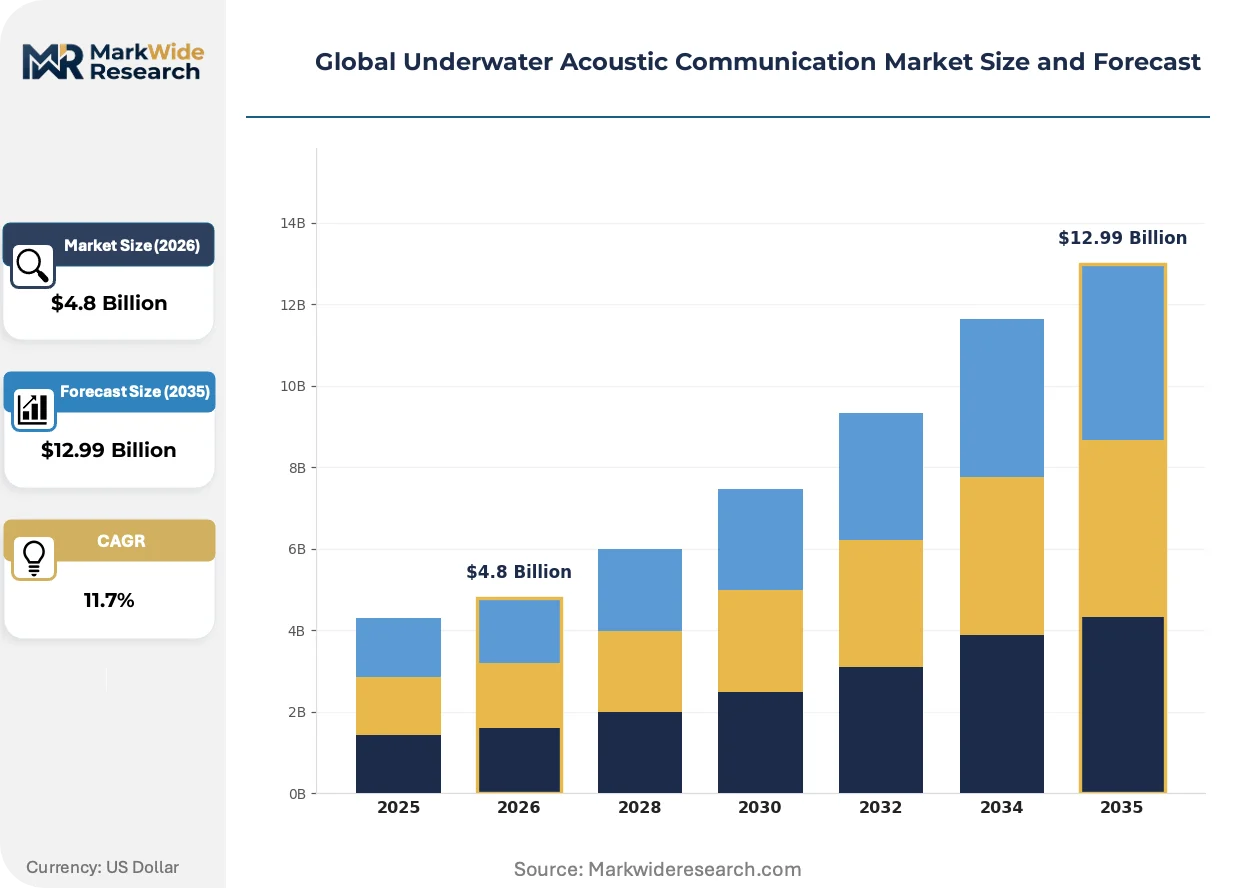
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Modems, Underwater Sensors, Communication Arrays, Transducers Technology: Frequency Hopping, Spread Spectrum, Chirp Signal, Sonar Techniques End User: Defense, Oil & Gas, Environmental Monitoring, Marine Research Application: Subsea Communication, Underwater Exploration, Surveillance, Data Collection |
| Companies Covered | Teledyne Technologies Incorporated, L3Harris Technologies, Kongsberg Gruppen, Thales Group, EvoLogics GmbH, Sonardyne International, Ultra Electronics, Nortek, Moog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Underwater Acoustic Communication Market Strategic Shifts
Waveform virtualization and regulatory harmonization are compressing equipment lifecycles while opening new procurement channels for non-traditional suppliers.
Machine-learning-based channel estimation is collapsing the performance gap between adaptive equalization and fixed-filter architectures. Naval research laboratories in Norway and the United States are deploying neural-network-trained modems for real-time multipath prediction. This compression of algorithm development cycles enables software-only upgrades that displace hardware refresh programs.
Japan's METI guidelines for marine resource exploration equipment are mandating interoperability certification for seabed instrumentation. Domestic suppliers must demonstrate acoustic modem compatibility with government survey platforms to qualify for exploration licenses. Equipment manufacturers are responding by open-sourcing physical layer protocols to accelerate third-party certification.
Long-term service contracting is displacing capital purchase models for autonomous underwater vehicle fleets. Energy companies in the North Sea now lease integrated communication packages with guaranteed uptime rather than owning modem hardware. Norway's Equinor and BP's Aberdeen operations have pioneered outcome-based agreements where suppliers retain equipment ownership and liability for link availability.
Global Underwater Acoustic Communication Market Segmentation
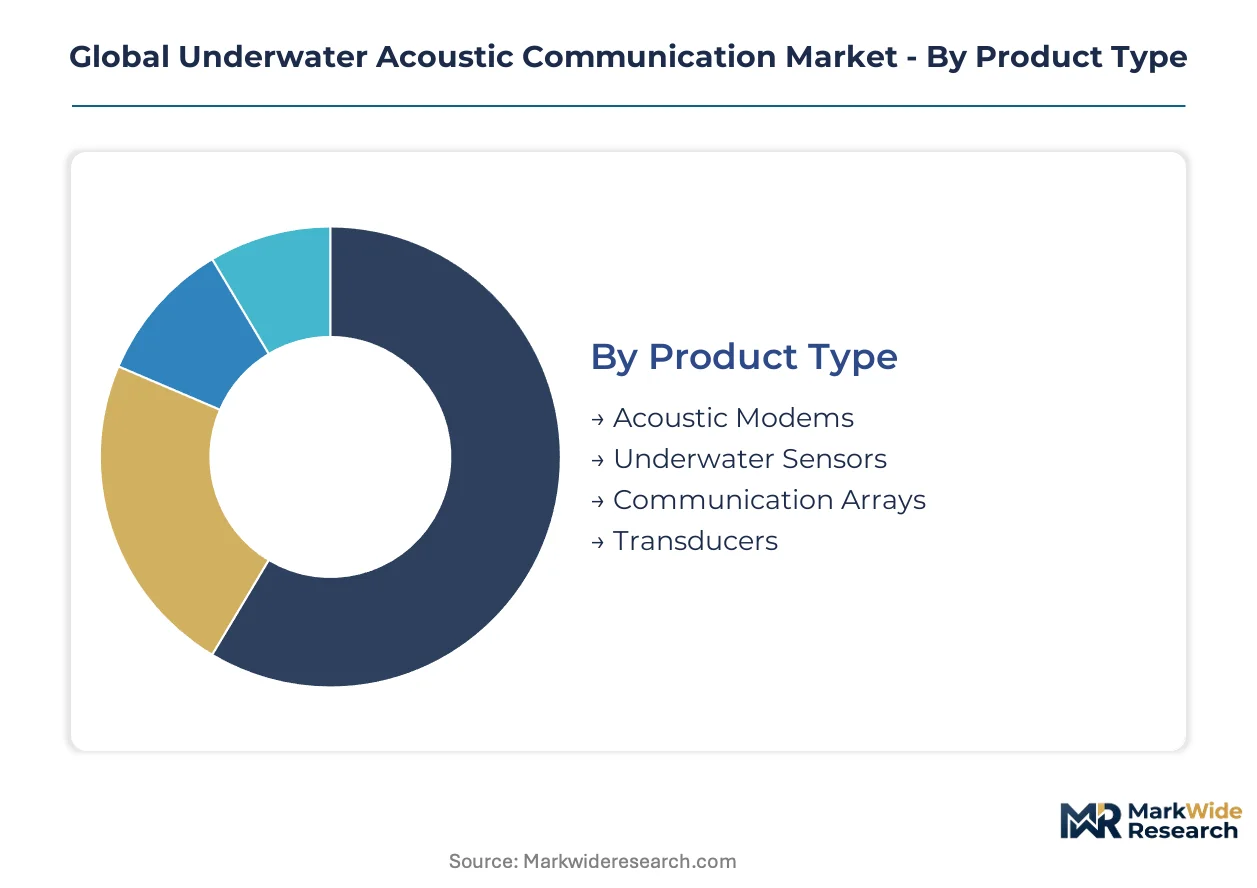
Segmentation in underwater acoustic communication reflects divergent physics constraints and procurement economics across defense, energy, and scientific end uses. Product architecture, waveform technology, and platform integration requirements create distinct margin pools and supplier qualification barriers.
Product Type:
Cost tier separates commodity transducer components from integrated modem systems with software-defined waveform capability.
- Acoustic Modems:Self-contained transmitter-receiver units with embedded signal processing firmware. NATO navies in Norway and the United States drive procurement for retrofit programs on legacy submarines and autonomous underwater vehicles.
- Underwater Sensors:Pressure, temperature, and salinity instruments with acoustic telemetry backhaul. Environmental monitoring networks across Japan's coastal zones and North Sea carbon capture sites concentrate demand for low-power, long-deployment units.
- Communication Arrays:Multi-element transducer assemblies for beamforming and directional transmission.
- Transducers:Piezoelectric or magnetostrictive elements converting electrical signals to acoustic pressure waves.
Acoustic modems hold installed capacity. Underwater sensors are rotating up the share rankings.
Technology:
Application environment dictates waveform selection, with shallow-water multipath tolerance and deep-ocean range extension driving divergent engineering priorities.
- Spread Spectrum:Direct-sequence and frequency-hopping architectures that spread signal energy across wide bandwidths to suppress interference. Shallow continental shelf operations in the Gulf of Mexico and North Sea favor this approach for reliable data links through complex boundary reflections.
- Frequency Hopping:Rapid carrier switching across discrete channels to evade narrowband interference and enable multiple-access networks. Classified submarine datalinks in United States and United Kingdom fleets require hardened implementations with encryption-layer integration.
- Chirp Signal:Frequency-swept pulses optimizing signal-to-noise ratio for long-range detection.
- Sonar Techniques:Active and passive acoustic methods adapted for communication rather than ranging.
Spread spectrum dominates shallow-water revenue. Frequency hopping maintains defense premium positioning.
End User:
Customer type stratifies sharply between classified defense procurement with decade-long certification cycles and commercial lease arrangements with uptime guarantees.
- Defense:Naval command networks, submarine force coordination, and autonomous vehicle swarm coordination. Indo-Pacific fleet expansion in Japan and NATO modernization programs in Norway concentrate procurement for interoperable STANAG-compliant equipment.
- Oil & Gas:Subsea infrastructure monitoring, pipeline leak detection, and carbon capture verification. Equinor and BP operations in the North Sea have shifted toward outcome-based service contracts where suppliers retain hardware ownership.
- Environmental Monitoring:Distributed sensor grids for climate research and ecosystem tracking.
- Marine Research:Oceanographic data collection and seabed mapping operations.
Defense holds installed capacity. Oil & gas contracting models are rotating up the share rankings.
Application:
Volume concentration tracks platform deployment scale, with fixed infrastructure nodes outpacing mobile platform integration in unit economics.
- Subsea Communication:Permanent or semi-permanent datalinks connecting seabed equipment to surface gateways. Pipeline monitoring networks across the North Sea and Gulf of Mexico drive recurring revenue through long-term service agreements.
- Surveillance:Covert detection and tracking networks requiring low-probability-of-intercept waveforms. Japan's coastal defense priorities and NATO Baltic Sea operations sustain demand for specialized hardware with classified certification.
- Underwater Exploration:Mobile mapping and resource assessment missions.
- Data Collection:Time-series sensor logging with delayed or real-time acoustic retrieval.
Subsea communication holds installed capacity. Surveillance applications are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement programs and offshore energy infrastructure mandates are concentrating modem deployment across NATO and Indo-Pacific fleets. National regulators in Norway, Japan, and the United States are accelerating certification timelines for autonomous underwater vehicle integration.
United States
Naval modernization programs and autonomous vehicle swarm development drive procurement for STANAG-compliant equipment. The US Navy's underwater communication certification protocols require cleared personnel and facility infrastructure, creating classified barriers for commercial suppliers. Research clusters in Rhode Island and California concentrate software-defined waveform development for submarine datalink retrofit programs.
Norway
Equinor's outcome-based service contracting for North Sea subsea infrastructure rotates demand toward leased communication packages with uptime guarantees. Norwegian fjord test facilities support captive transducer manufacturing capabilities that anchor Kongsberg Gruppen's integrated sensor-to-platform portfolio. Stavanger and Bergen host concentrated engineering talent for multipath compensation in shallow continental shelf operations.
Japan
Coastal defense priorities and marine resource exploration licensing create aligned demand for dual-use acoustic modems. METI guidelines mandate interoperability certification for seabed instrumentation, forcing domestic suppliers to demonstrate acoustic modem compatibility with government survey platforms. Tokyo and Yokohama clusters concentrate environmental monitoring sensor networks for climate research applications.
United Kingdom
Frequency-hopping encryption layers for classified subsea datalinks sustain demand from Royal Navy submarine force coordination programs. NATO STANAG interoperability mandates compel cross-border equipment compatibility upgrades across legacy platforms. Aberdeen operations anchor North Sea oil and gas pipeline monitoring networks with long-term service agreements for carbon capture verification infrastructure.
Germany
EvoLogics GmbH's Berlin-based engineering anchors European specialist capability in peer-to-peer mesh architectures for swarm-based autonomous vehicle coordination. German defense procurement aligns with NATO STANAG standards for interoperable sonar datalinks, compelling software-defined waveform adoption. Hamburg and Kiel clusters concentrate oceanographic research applications with distributed sensor grid deployments.
Global Underwater Acoustic Communication Market Competitive Environment
On the supply side, the industry is consolidating around integrated sensor-to-platform portfolios and captive transducer manufacturing capabilities. Three strategic archetypes dominate: vertically integrated defense contractors with classified certification infrastructure, specialized acoustic modem developers with software-defined waveform expertise, and marine technology conglomerates with in-house test facility assets. Competitive moves concentrate on multi-year naval service contracting and FPGA-based hardware convergence to collapse SKU requirements.
Within the defense-contractor tier, Teledyne Technologies Incorporated and L3Harris Technologies exemplify archetypes built around cleared facility infrastructure and encryption-layer specialization. Kongsberg Gruppen occupies a position representing captive manufacturing control over transducer production and Norwegian test facility access. Among European specialists, EvoLogics GmbH and Sonardyne International sit within the modular node developer category serving swarm architecture redistribution toward distributed peer-to-peer acoustic networks.
| Leading Market Players |
|---|
| Teledyne Technologies Incorporated |
| L3Harris Technologies |
| Kongsberg Gruppen |
| Thales Group |
| EvoLogics GmbH |
| Sonardyne International |
| Ultra Electronics |
| Nortek |
| Moog |
| Others |
Value Chain & Pricing Dynamics
Single-source transducer manufacturing dependencies in Norwegian and Japanese defense-industrial bases determine both tiered pricing spreads across defense-commercial segments and supply chain vulnerability profiles for NATO procurement programs. This concentration forces buyers into long-term fixed-price development contracts with limited margin recovery mechanisms while compressing commercial modem pricing through leased service alternatives.
Pricing Analysis
Certification level creates the primary spread between defense-grade STANAG-compliant systems and commercial environmental monitoring units. Pricing stratifies across classified military datalinks, dual-use offshore energy infrastructure packages, and commodity scientific sensor telemetry. Cost compression in commercial tiers intensifies as Equinor and BP shift toward outcome-based service contracts where suppliers retain hardware ownership. Defense end users exhibit lowest price sensitivity due to decade-long platform integration cycles and cleared-facility qualification barriers.
Supply Chain Analysis
Piezoelectric ceramic feedstocks and magnetostrictive alloy inputs draw from Japanese and German specialty materials suppliers. Transducer manufacturing clusters in Norway, Japan, and the United States anchor captive production capabilities for Kongsberg Gruppen and Teledyne Technologies. Single-source vulnerability runs through Norwegian fjord test facilities required for shallow-water multipath validation. Distribution runs through direct naval procurement channels, energy sector service contractors, and oceanographic research consortiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based service contracting for autonomous underwater vehicle fleets expands faster than hardware sales, creating attach opportunities for uptime guarantees and predictive maintenance analytics. Recurring revenue layers from guaranteed link availability contracts now exceed capital equipment margins in North Sea oil and gas operations.
For Market Incumbents: Harden classified certification infrastructure against emerging software-defined radio competitors by deepening STANAG interoperability investments and securing multi-year naval service contracts. Captive control over Norwegian and Japanese test facilities remains a critical defensive lever against modular node developers entering swarm architecture markets.
For New Entrants and Emerging Players: Build out peer-to-peer mesh modem capabilities for autonomous vehicle swarm coordination, targeting the fragmented supplier relationships created by compressed procurement cycles. Environmental monitoring sensor networks in Japan's coastal zones and distributed oceanographic grids offer the most penetrable entry points without cleared-facility requirements.
For Investors and Strategic Acquirers: The market sits at a platform-integration phase that favors software-defined waveform specialists with FPGA convergence capabilities. Long-term viability over a multi-year defense modernization window rests on acquiring firms with embedded naval research laboratory relationships. Watch machine-learning-based channel estimation deployment as the inflection signal for algorithm-driven hardware displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Waveform Convergence | FPGA integration with acoustic transducer arrays collapses NATO STANAG hardware SKU requirements for multi-standard platforms. |
| Outcome-Based Service Contracting | Equinor and BP lease models transfer equipment ownership risk to suppliers while locking in long-term revenue streams. |
| Machine-Learning Channel Estimation | Neural-network-trained modems at Norwegian and US naval labs enable software-only upgrades displacing hardware refresh cycles. |
| Peer-to-Peer Mesh Architecture Development | Swarm-based autonomous vehicle coordination eliminates centralized hub dependencies and opens modular node procurement channels. |
| Dual-Use Commercial Certification | Japan's METI interoperability mandates for seabed mining create aligned demand pathways for defense-capable acoustic modems. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across naval program managers, autonomous vehicle fleet operators, offshore energy infrastructure engineers, and oceanographic research directors. Secondary validation drew from NATO STANAG documentation, US Navy certification protocols, Japan's METI guideline releases, and Equinor service contract disclosures. Bottom-up unit economics for modem deployments were triangulated against top-down defense procurement budget allocations across the analysis window.
Calibration against historical platform integration cycles and waveform technology transitions informed projection modeling across product type, technology segment, end user category, and application domain. CAGRs were derived from segment-level growth rate reconciliation with fleet expansion announcements and energy sector capital commitment patterns. Spread spectrum adoption curves and frequency-hopping encryption layer investments served as industry-specific forecast anchors.
Stress conditions across transducer supply disruption scenarios, salinity-gradient link degradation events, and autonomous vehicle swarm architecture shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about NATO interoperability mandate timelines and offshore energy decarbonization spending trajectories. Cross-checking against naval procurement database tracking and energy sector service contract registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Cambodia ICT Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Managed M2M Services Market
Telecommunications
5G Core Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Thailand Telecom Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Ghana Telecom Market
Telecommunications
Philippines Telecom Market
Telecommunications
Mobile Voice Market
Telecommunications
Promotional Sms Market