
 5G MVNO Market | 2026-2036
5G MVNO Market Size, Share, and Industry Trends Forecast 2026-2036
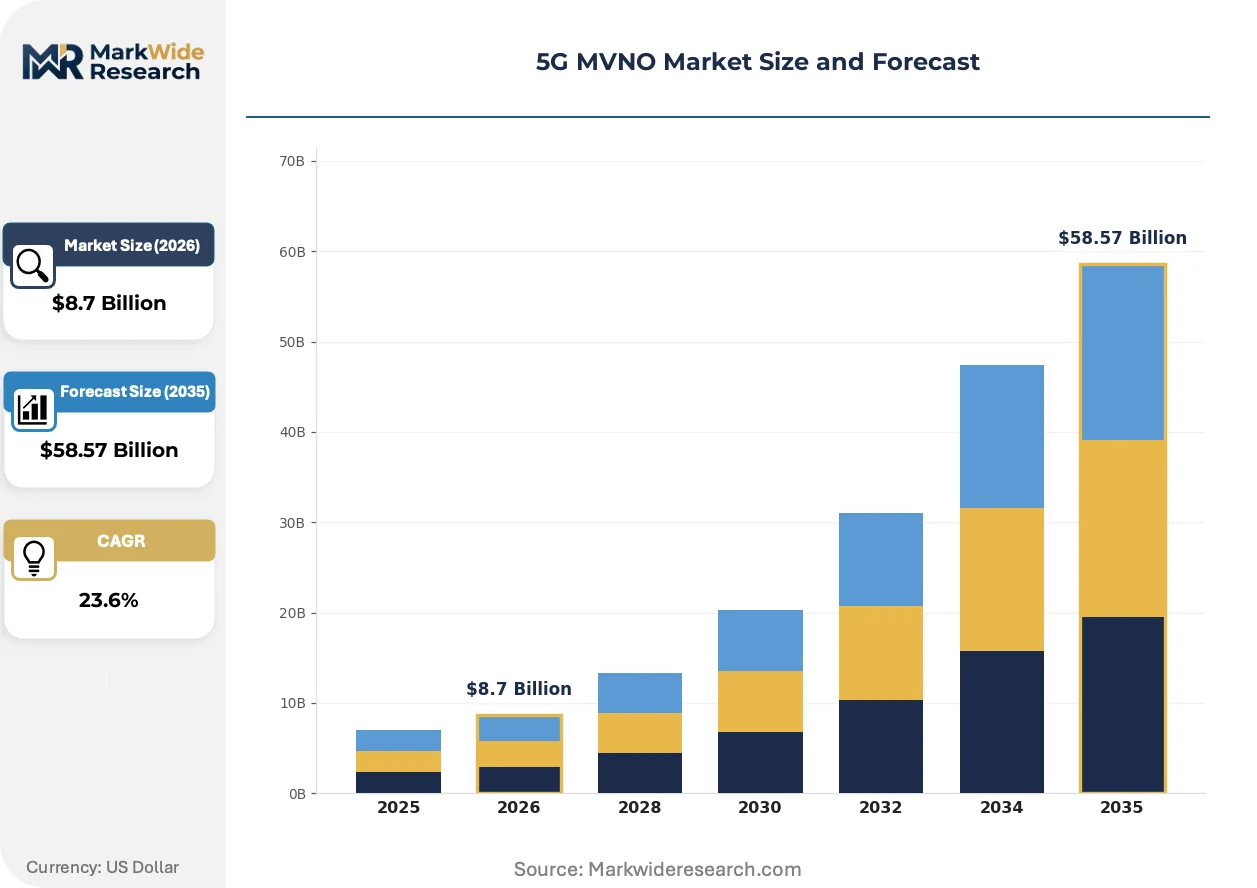
5G MVNO Market Outlook
Buyer concentration among enterprise IoT deployers is hardening as industrial manufacturers and logistics operators consolidate connectivity procurement under single-vendor frameworks. Mint Mobile leverages aggressive digital-first customer acquisition to sustain low overhead subscriber growth in the consumer segment. TracFone Wireless Inc. anchors its position through prepaid distribution dominance across rural and price-sensitive demographics. Tesco Mobile competes by bundling retail loyalty programs with flexible data allowances in European markets.
A 5G Mobile Virtual Network Operator leases bulk capacity from host Mobile Network Operators and resells connectivity services under its own brand without owning physical radio infrastructure. These operators rely on network slicing protocols and QoS agreements to guarantee latency thresholds as low as one millisecond for enterprise and mission-critical applications. Bundled service plans currently dominate revenue as consumers and small businesses prefer unified voice, data, and messaging packages over standalone offerings. Standalone 5G architecture represents the fastest-expanding technology segment as host MNOs migrate core networks away from legacy LTE dependency. Enterprise customer contracts command premium positioning due to customized SLAs and dedicated network slice provisioning.
The FCC governs wholesale access terms and spectrum leasing conditions in the United States while the EU AI Act and GDPR impose data governance standards on cross-border subscriber management platforms. Ofcom in the United Kingdom enforces net neutrality provisions that directly shape MVNO pricing flexibility and service differentiation boundaries. Stakeholders must monitor evolving wholesale rate negotiations between host MNOs and their reseller partners as these agreements determine margin sustainability across all deployment models.
Market Dynamics
Network slicing protocols are redistributing power between host MNOs and their reseller partners as enterprise IoT contracts demand guaranteed latency thresholds. Wholesale rate negotiations now determine margin sustainability across all deployment models.
Growth Catalysts
- Enterprise IoT Deployments:Industrial manufacturers consolidate connectivity procurement under single-vendor frameworks, accelerating subscriber acquisition in manufacturing clusters.
- FCC Spectrum Auction Rules:Reshaped wholesale access economics create entry pathways for digital-first operators seeking bulk capacity agreements.
- Standalone 5G Architecture:Host MNO migration away from LTE dependency unlocks dedicated network slice provisioning for mission-critical applications.
Market Restraints
- Host MNO Supply Concentration:Wholesale capacity availability concentrates among three national carriers in the United States, creating dependency risk for reseller pricing.
- Spectrum Leasing Cost Volatility:Bulk capacity acquisition costs fluctuate with auction clearing prices, compressing reseller margins unpredictably.
- Net Neutrality Framework Friction:Ofcom provisions in the United Kingdom constrain service differentiation boundaries, limiting premium tier creation.
Strategic Opportunities
- Hyperscale Cloud Direct Slicing:Amazon Web Services and Microsoft Azure negotiate direct network agreements with host MNOs, bypassing traditional wholesale layers.
- EU AI Act Compliance Services:Cross-border subscriber management platforms require GDPR-aligned data governance, creating specialized MVNO service demand.
- Private Network Convergence:Integration of 5G LAN capabilities with public network slicing enables hybrid deployment models for campus environments.
Industry Challenges
- Network Slice Orchestration Expertise:Talent scarcity in QoS engineering and edge computing architecture constrains operational scaling.
- Legacy Billing System Integration:Real-time charging for sliced services requires core platform overhauls that strain capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G MVNO Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data-Only, Voice-Only, Bundled, Wholesale Customer Type: Consumer, Small Business, Enterprise, Government Deployment Model: Hosted, On-Premises, Managed, Hybrid Technology: Standalone, Non-Standalone, Edge Computing, IoT Integration |
| Companies Covered | Mint Mobile, Tesco Mobile, TracFone Wireless Inc., Giffgaff, Lebara, Lycamobile Group, Cricket Wireless, Boost Mobile, Virgin Mobile, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G MVNO Market Strategic Shifts
Digital-native customer acquisition models are compressing traditional distribution economics while regulatory frameworks on both sides of the Atlantic reshape competitive boundaries. Technology evolution and procurement pattern shifts are converging to redefine value capture.
Standalone 5G core networks are expanding into enterprise connectivity provisioning as host MNOs retire LTE-dependent infrastructure. Industrial manufacturers in automotive and logistics verticals adopt these architectures fastest. The technology is expanding into premium contract tiers that guarantee sub-10 millisecond latency for automated guided vehicle coordination.
GDPR and the EU AI Act impose cross-border data governance standards on subscriber management platforms operating across European member states. These frameworks mandate explicit consent architectures and algorithmic transparency for automated network optimization. MVNOs serving multinational enterprises must restructure data residency protocols, with Germany and France enforcing the strictest interpretations.
Unified connectivity procurement is consolidating vendor relationships as industrial manufacturers abandon multi-carrier strategies. Single-source frameworks with customized SLAs now displace fragmented supplier portfolios in manufacturing clusters. This concentration is most visible in the United States, where logistics operators negotiate direct network slicing agreements that bypass traditional wholesale intermediaries.
5G MVNO Market Segmentation
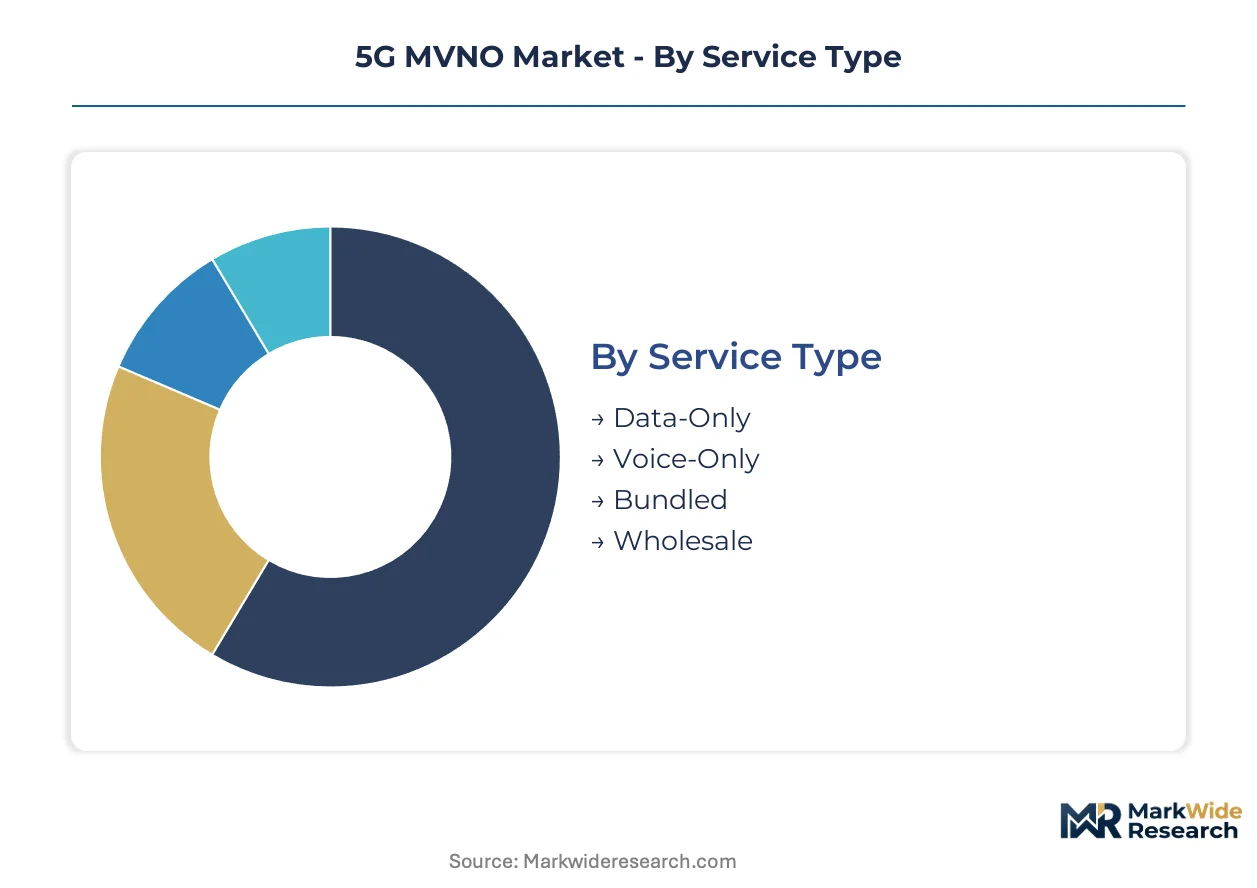
5G MVNO operators structure their commercial strategies around distinct service configurations and customer profiles. Each segmentation dimension reflects divergent margin profiles, technical requirements, and competitive intensity that shape go-to-market positioning.
Service Type:
Enterprise procurement teams prioritize total cost predictability over per-gigabyte rates when evaluating connectivity contracts.
- Bundled:Unified voice, data, and messaging packages dominate revenue concentration across consumer and small business accounts. Industrial manufacturers in automotive clusters favor these arrangements for simplified vendor management and consolidated billing overhead.
- Data-Only:Pure data connectivity without voice components serves IoT sensor networks and machine-to-machine applications. Logistics operators deploying automated guided vehicle fleets in German manufacturing hubs drive premium tier demand for guaranteed throughput.
- Voice-Only:Traditional voice service resale persists in price-sensitive demographics and legacy enterprise PBX replacement scenarios. Rural distribution channels in the United States sustain residual volume through prepaid frameworks.
- Wholesale:Bulk capacity resale to sub-branded operators or vertical specialists enables margin extraction without direct subscriber acquisition costs. FCC spectrum auction rules reshape economics for digital-first entrants seeking host MNO agreements.
Bundled plans lead on scale; data-only offerings lead on momentum.
Customer Type:
Contract value concentration shifts dramatically across buyer categories, with enterprise accounts commanding customized SLAs that consumer segments cannot access.
- Enterprise:Multinational manufacturers negotiate dedicated network slices with latency guarantees below 10 milliseconds. These contracts require GDPR-aligned data governance for cross-border subscriber management platforms serving EU member states.
- Small Business:Unified connectivity procurement consolidates under single-vendor frameworks as these organizations abandon fragmented multi-carrier strategies. Campus environments in United States logistics clusters favor hybrid deployment models combining public slicing with private 5G LAN capabilities.
- Consumer:Digital-first acquisition models compress traditional distribution economics through aggressive online onboarding. Prepaid dominance persists across rural United States demographics with price-sensitive purchasing patterns.
- Government:Public sector contracts mandate explicit security certifications and domestic data residency protocols. Ofcom net neutrality provisions in the United Kingdom constrain pricing flexibility for these accounts.
Enterprise segments lead on contract value; small business categories lead on acquisition velocity.
Deployment Model:
Operational control requirements determine whether MVNOs maintain infrastructure ownership or delegate to host operator platforms.
- Hosted:Full reliance on host MNO core networks minimizes capital expenditure for new market entrants. Three national carriers in the United States concentrate wholesale capacity availability, creating dependency risk for reseller pricing.
- Managed:Outsourced network operations with retained branding appeal to mid-tier operators lacking internal QoS engineering expertise. Talent scarcity in edge computing architecture constrains operational scaling for this model.
- Hybrid:Integration of public network slicing with private 5G LAN capabilities serves campus manufacturing environments. Automotive verticals adopt these configurations fastest for automated production line coordination.
- On-Premises:Dedicated core network infrastructure enables maximum service differentiation and latency control. Spectrum leasing cost volatility compresses margins unpredictably for operators pursuing this capital-intensive path.
Hosted deployments lead on adoption breadth; hybrid configurations lead on expansion trajectory.
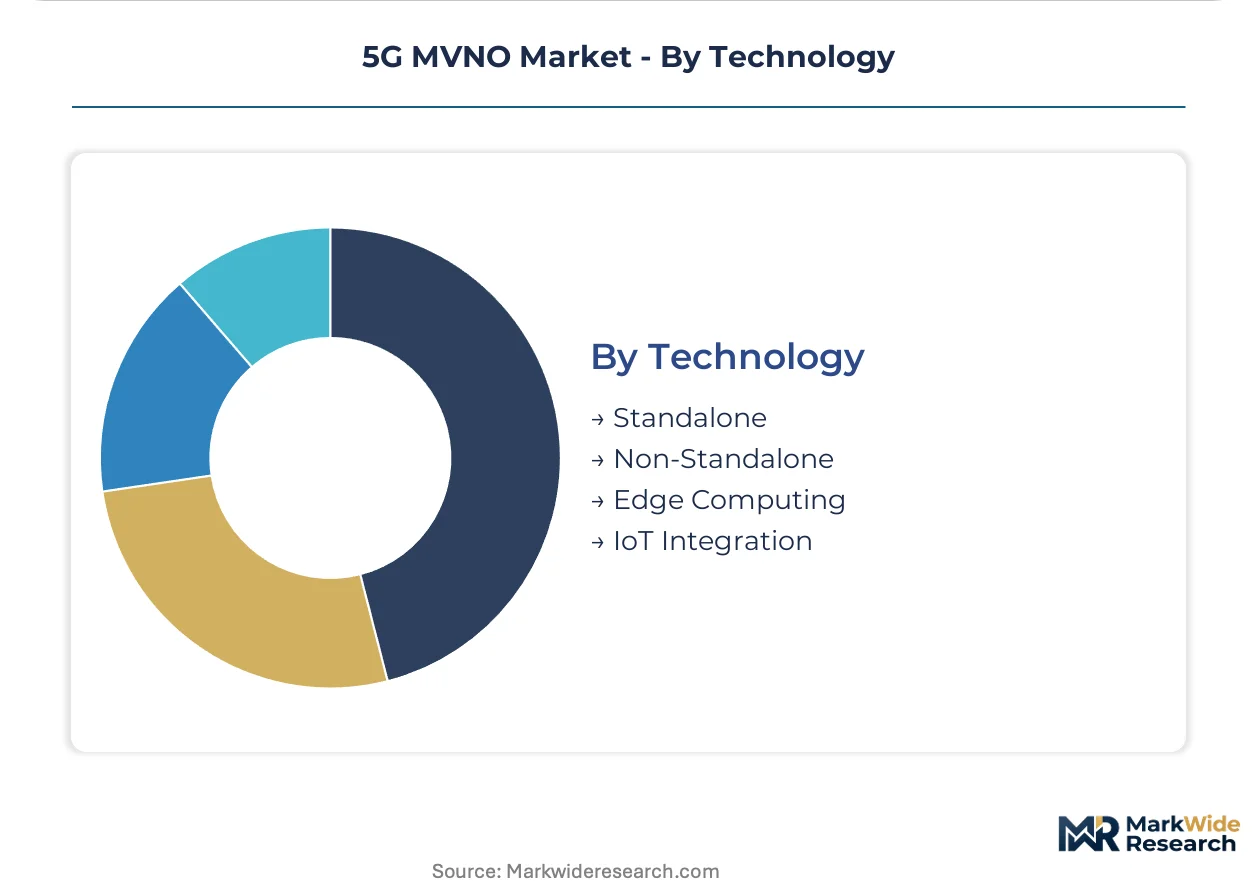
Technology:
Core network architecture choices determine whether operators can provision dedicated slices or remain tethered to legacy LTE dependencies.
- Standalone:Pure 5G core networks unlock dedicated slice provisioning for mission-critical applications. Host MNO migration away from LTE dependency is expanding this segment most quickly into enterprise connectivity tiers.
- IoT Integration:Specialized protocols for massive machine-type communications serve sensor-dense industrial environments. GDPR and the EU AI Act impose cross-border data governance standards on subscriber management platforms utilizing these technologies.
- Non-Standalone:LTE anchor dependency persists for cost-optimized consumer offerings and coverage-limited geographies. Legacy billing system integration challenges strain capital allocation for real-time charging upgrades.
- Edge Computing:Distributed compute nodes co-located with radio access infrastructure enable sub-millisecond latency for time-sensitive applications. Hyperscale cloud providers negotiate direct network agreements that bypass traditional wholesale layers.
Standalone architecture leads on premium positioning; IoT integration leads on vertical penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States carriers command premium wholesale rates while German industrial clusters drive enterprise slicing demand at scale. Regulatory divergence between FCC auction frameworks and EU data governance standards creates divergent entry economics for new operators.
United States
Enterprise logistics operators and hyperscale cloud providers anchor demand concentration across manufacturing corridors. FCC spectrum auction rules reshape wholesale access economics and create entry pathways for digital-first resellers. Industrial clusters in Michigan and Ohio consolidate connectivity procurement under single-vendor frameworks with customized SLAs.
Germany
Automotive manufacturers and automated guided vehicle fleet operators drive premium tier demand for guaranteed sub-10 millisecond latency. GDPR and the EU AI Act impose cross-border data governance standards on subscriber management platforms serving multinational enterprises. Manufacturing hubs in Bavaria and Baden-Württemberg adopt hybrid deployment models combining public slicing with private 5G LAN capabilities.
United Kingdom
Retail-integrated operators and price-sensitive consumer segments sustain prepaid distribution volume across urban and rural demographics. Ofcom net neutrality provisions constrain service differentiation boundaries and limit premium tier creation flexibility. Logistics corridors in the Midlands and Northern England negotiate direct network agreements that bypass traditional wholesale intermediaries.
France
Cross-border enterprise contracts and multinational manufacturing operations require GDPR-aligned data residency protocols with strictest national interpretations. The EU AI Act mandates explicit consent architectures for automated network optimization across subscriber management platforms. Industrial zones in Île-de-France and Auvergne-Rhône-Alpes restructure procurement around unified single-source frameworks.
Japan
Precision manufacturing and industrial IoT sensor networks drive demand for massive machine-type communications protocols. METI industrial policy frameworks shape spectrum allocation priorities and wholesale partnership structures for virtual operators. Automotive production clusters in Aichi Prefecture and electronics manufacturing in Kansai region adopt standalone 5G core architectures fastest.
5G MVNO Market Competitive Environment
United States-based operators anchor the premium enterprise tier; European specialists hold retail-integrated and ethnic community segments. Host MNO supply concentration among three national carriers in the United States creates dependency risk that compresses reseller margin sustainability. Strategic archetypes include digital-native customer acquisition platforms, retail-bundled loyalty integrators, and wholesale capacity aggregators. Dominant competitive moves center on direct network slicing agreements with hyperscale cloud providers and vertical specialization into industrial IoT verticals.
Within the digital-native acquisition archetype, Mint Mobile exemplifies aggressive online onboarding models that sustain low overhead subscriber growth. Among retail-bundled operators, Tesco Mobile occupies a position integrating supermarket loyalty programs with flexible data allowances. TracFone Wireless Inc. anchors the prepaid distribution dominance model across rural United States demographics and price-sensitive purchasing segments.
| Leading Market Players |
|---|
| Mint Mobile |
| Tesco Mobile |
| TracFone Wireless Inc. |
| Giffgaff |
| Lebara |
| Lycamobile Group |
| Cricket Wireless |
| Boost Mobile |
| Virgin Mobile |
| Others |
Value Chain & Pricing Dynamics
FCC net neutrality mandates and EU AI Act compliance requirements gate qualified supply access for premium-tier 5G MVNO positioning. Wholesale rate negotiations with host MNOs concentrate pricing power among three national carriers in the United States, compressing reseller margin sustainability across all deployment models.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for enterprise network slicing contracts. Three-tier pricing structure across premium, standard, and economy levels dominates, with latency guarantees and GDPR certification grade driving price differentiation. Pricing pressure stems from spectrum leasing cost volatility at auction clearing prices. Small business segments exhibit highest price sensitivity; enterprise IoT deployers with customized SLAs show lowest.
Supply Chain Analysis
GDPR-aligned data governance certification gates supply qualification for cross-border subscriber management platforms. Core network infrastructure concentrates in the United States, Germany, and Japan. Raw material dependencies include semiconductor components for edge computing nodes, radio access equipment, and core network software licenses. Single-source vulnerability runs through host MNO supply concentration among three national carriers. Distribution runs through direct wholesale agreements with hyperscale cloud providers and retail-bundled loyalty integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory compounder. The EU AI Act's explicit consent architecture mandates reshape competitive boundaries for cross-border subscriber management platforms.
For Market Incumbents: To counter hyperscale cloud provider direct slicing agreements with host MNOs, deepen backward integration into edge computing infrastructure ownership and secure exclusive QoS engineering talent pools. Capacity additions in German manufacturing clusters anchor defensive positioning.
For New Entrants and Emerging Players: Digital-native customer acquisition routes unlock white-space penetration in United States rural demographics and United Kingdom price-sensitive prepaid segments. Campus hybrid deployment models combining public slicing with private 5G LAN capabilities represent the most penetrable application tier. Partner with industrial manufacturers in automotive verticals for vertical specialization.
For Investors and Strategic Acquirers: Roll-up economics work for digital-first MVNO platforms because host MNO wholesale rate standardization creates scalable margin structures. Five-to-ten year viability hinges on standalone 5G core migration completion. Target acquisition archetype: managed deployment model operators with retained branding and outsourced network operations. Watch hyperscale cloud provider direct network agreements as the inflection indicator signaling wholesale layer disintermediation.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Network Slicing Agreement | Bypasses traditional wholesale layers for AWS and Microsoft Azure with host MNOs. |
| Edge Computing Infrastructure Buildout | Enables sub-millisecond latency guarantees for automotive automated guided vehicle coordination. |
| GDPR Compliance Service Launch | Captures specialized MVNO demand from multinational enterprise cross-border contracts. |
| Hybrid Deployment Model Expansion | Integrates public network slicing with private 5G LAN for campus manufacturing environments. |
| QoS Engineering Talent Acquisition | Addresses operational scaling constraints from network slice orchestration expertise scarcity. |
Study Parameters
Multiple input streams — host MNO wholesale strategy executives, enterprise IoT procurement leads, MVNO operational directors, and regulatory affairs specialists — were reconciled with secondary validation from FCC spectrum auction filings, EU AI Act implementation guidance, Ofcom net neutrality determinations, and host MNO SEC disclosures. Bottom-up subscriber acquisition modeling and top-down wholesale capacity estimation were triangulated.
Historical capacity deployment patterns were cross-referenced against panel input from network infrastructure vendors across the projection horizon. Segmentation dimensions modeled include service type, customer tier, deployment model, and core network architecture. CAGRs were derived from wholesale rate trajectory analysis and enterprise contract value expansion. Standalone 5G core migration timelines and hyperscale cloud direct agreement velocity served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for standalone 5G core migration would alter the outlook. Forecasts reflect underlying assumptions about host MNO wholesale rate stability and spectrum auction clearing price ranges. A model refresh is warranted upon material change in FCC spectrum auction rulemaking or EU AI Act enforcement interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Mobile Fronthaul and Backhaul Market
Telecommunications
Denmark Telecom Market
Telecommunications
United Arab Emirates Telecom Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Dialer Market
Telecommunications
Poland Telecom Market
Telecommunications
South Africa Telecom Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Ghana Telecom Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
Oman Telecommunication Market
Telecommunications
Kenya Telecom Market
Telecommunications
Esim Subscription Market