
 Datacenter Analytics Market | 2026-2036
Datacenter Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Datacenter Analytics Market Outlook
AI-driven observability is fragmenting traditional datacenter management architectures into specialized layers for compute, storage, and network telemetry. Microsoft leverages its Azure Monitor stack to anchor enterprise workloads across hybrid environments. Nvidia dominates GPU-centric performance analytics through its proprietary telemetry frameworks. Dell Technologies competes in on-premises instrumentation with hardware-integrated sensor arrays that feed real-time dashboards.
Datacenter analytics encompasses software, hardware, and service platforms that ingest operational telemetry from servers, cooling systems, and power distribution units to optimize energy efficiency, uptime, and resource allocation. These systems process metrics such as PUE ratios, thermal gradients, and workload latency at millisecond granularity to enable automated orchestration decisions. Software and platform segments lead current revenue pools due to recurring subscription models and API-based integration demands. Edge computing deployments represent the fastest-growing structural category as latency-sensitive applications require distributed analytics nodes outside core facilities. Hardware analytics modules face margin compression from commoditized sensor markets despite rising unit volumes.
FCC guidelines on critical infrastructure cybersecurity intersect with EPA energy efficiency mandates to shape procurement specifications for federal and commercial datacenter operators. The EU AI Act and GDPR compliance frameworks in Europe impose algorithmic transparency requirements on automated capacity planning and fault prediction systems. Stakeholders must monitor evolving energy disclosure rules from multiple national regulators while calibrating investment between cloud-native and edge-distributed analytics architectures.
Market Dynamics
Real-time telemetry processing at millisecond granularity is compressing decision cycles across power, cooling, and compute orchestration, forcing infrastructure operators to rebuild operational architectures around streaming analytics rather than batch reporting systems.
Growth Catalysts
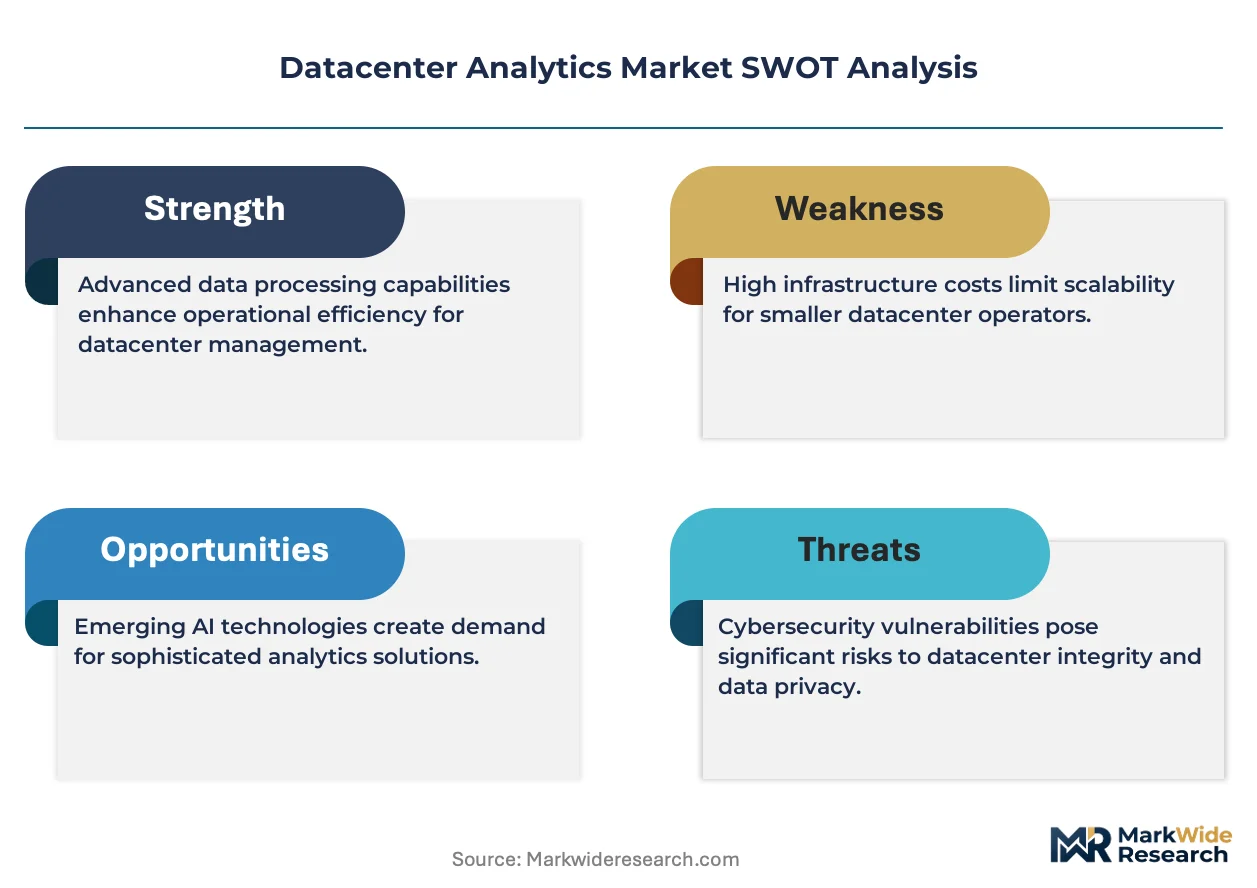
- EU AI Act compliance mandates:Automated capacity planning systems in European facilities must demonstrate algorithmic transparency, driving procurement of auditable analytics platforms.
- Hyperscale cluster concentration:Northern Virginia and Dallas-Fort Worth operators are deploying unified telemetry layers across multi-megawatt facilities to optimize PUE ratios.
- Edge node proliferation:Latency-sensitive manufacturing and autonomous systems require distributed analytics nodes outside core datacenter footprints.
Market Restraints
- Sensor hardware commoditization:Standardized temperature and power monitoring chips from Asian contract manufacturers are compressing margins for integrated hardware-software bundles.
- GDPR data residency friction:Cross-border telemetry streaming faces localization requirements that fragment centralized analytics architectures.
- Legacy SCADA integration debt:Brownfield facilities with proprietary industrial control protocols resist API-based telemetry ingestion without expensive gateway retrofits.
Strategic Opportunities
- India's PLI scheme for datacenter infrastructure:Domestic capacity buildouts in Mumbai and Chennai create demand for localized analytics deployment and support services.
- Digital twin convergence:Physics-based simulation engines are merging with operational telemetry to enable predictive thermal and electrical modeling.
- FERC demand response participation:Grid-interactive power analytics qualify hyperscale operators for frequency regulation revenue streams in organized electricity markets.
Industry Challenges
- Site reliability engineering talent scarcity:Hybrid skill sets combining electrical engineering, software development, and thermal physics command premium compensation and extended hiring timelines.
- Multi-vendor telemetry standardization gaps:Proprietary metrics from server, storage, and network equipment vendors resist normalization into unified dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Datacenter Analytics Market |
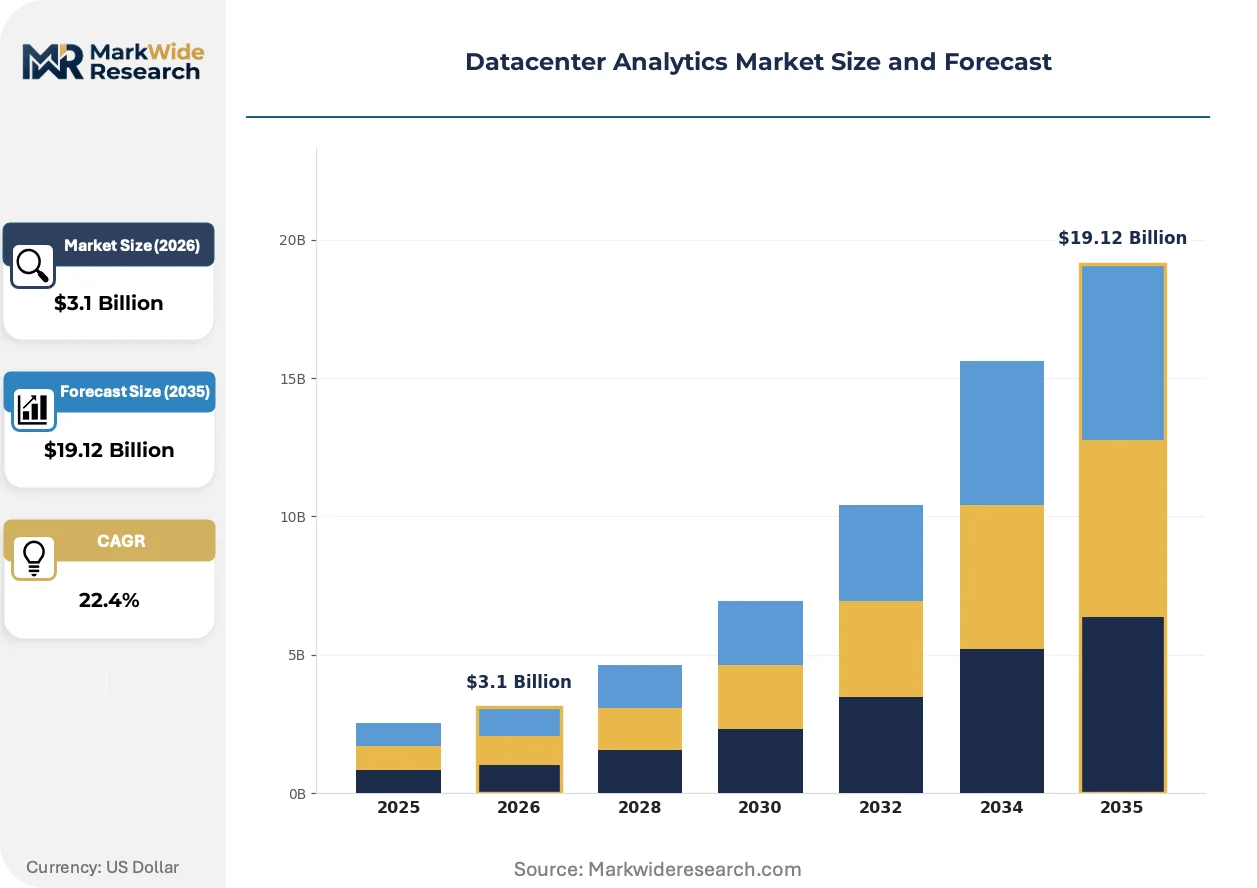
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $19.12 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
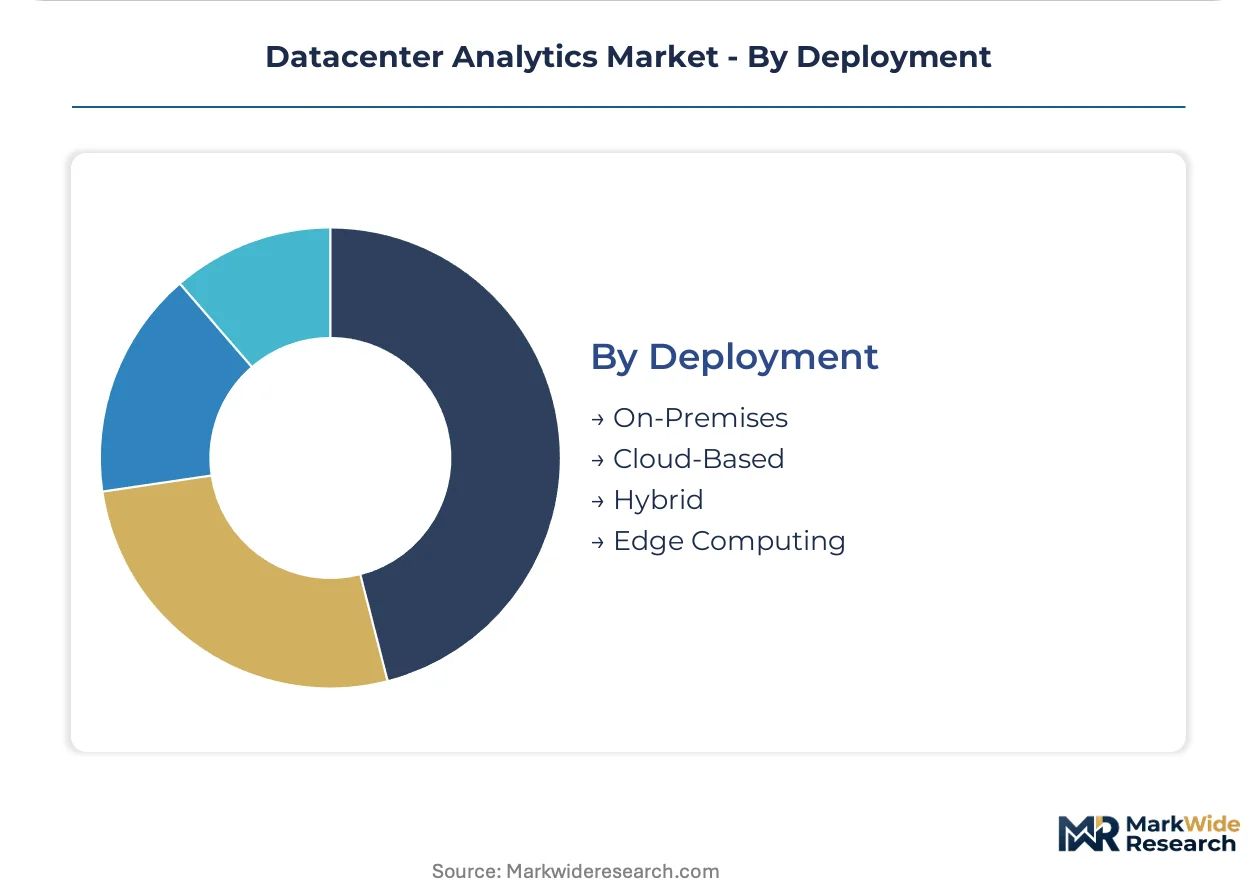
| Segmentation | Product Type: Software, Hardware, Service, Platform Application: Performance Monitoring, Capacity Planning, Fault Management, Security Analysis End User: Enterprises, Service Providers, Government, Educational Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Amazon Web Services (AWS), Microsoft, Google, Dell Technologies, Hewlett Packard Enterprise, Nvidia, IBM, Broadcom, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Datacenter Analytics Market Strategic Shifts
Datacenter analytics is pivoting from retrospective reporting toward predictive orchestration, with three distinct vectors reshaping how operational data generates actionable intelligence.
Agentic AI for autonomous infrastructure management is migrating from experimental pilots to production deployments. Hyperscale operators in Northern Virginia are deploying large language model-based systems that interpret natural language alerts and execute automated remediation workflows. This migration from rule-based automation compresses mean-time-to-resolution and reduces overnight staffing requirements for tier-one facilities.
EPA energy efficiency disclosure mandates are tightening reporting granularity for commercial datacenter operators above 100 kilowatts. The industrial consequence is mandatory sub-metering at rack-level power distribution units rather than facility-wide aggregation. Colocation providers are responding by retrofitting intelligent power strips and API-accessible branch circuit monitors to maintain lease competitiveness.
Consumption-based analytics licensing is displacing perpetual software agreements across enterprise and colocation segments. Buyers now prefer metering aligned with actual monitored device counts or data ingestion volumes rather than upfront capacity commitments. This pattern is most visible in Germany and the Netherlands, where sustainability-linked financing structures favor operational expenditure treatment for monitoring infrastructure.
Datacenter Analytics Market Segmentation
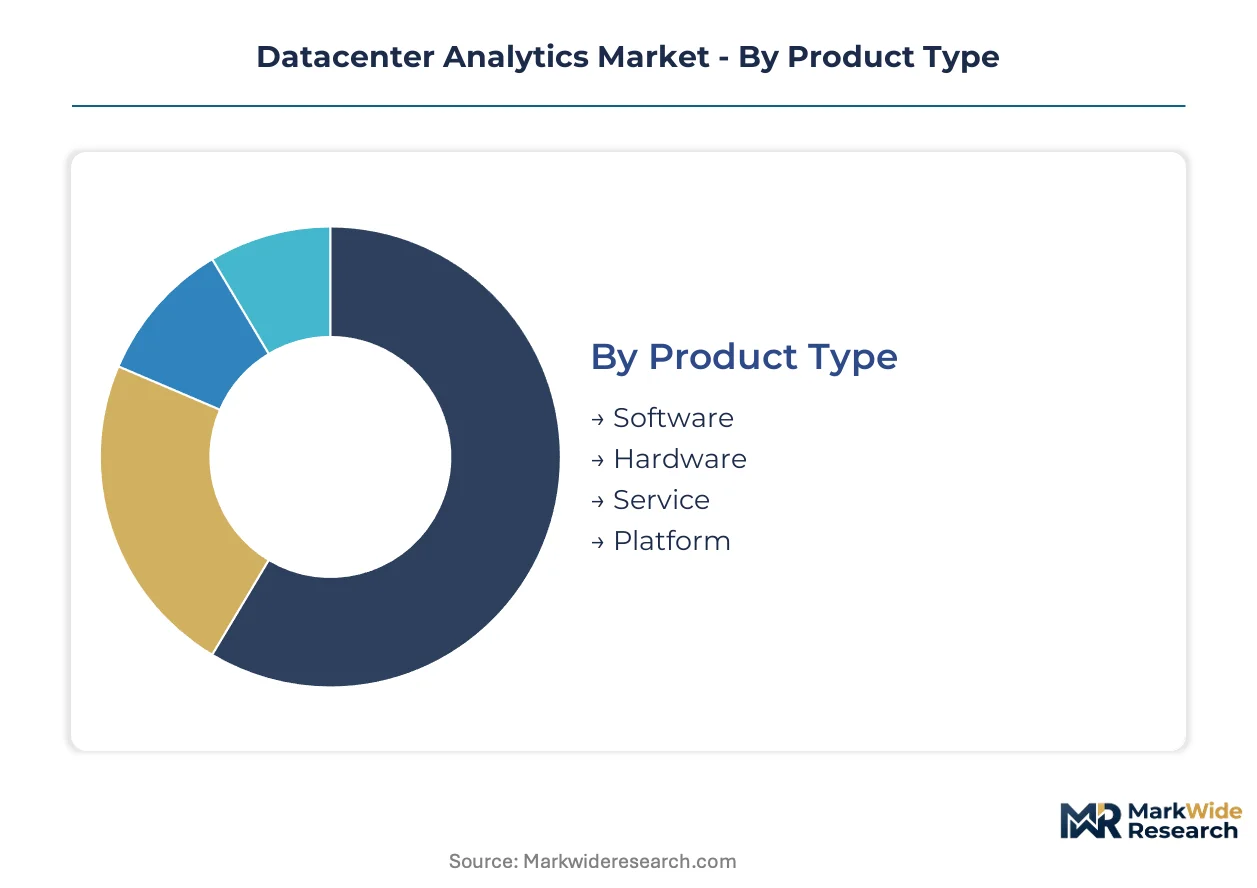
Datacenter analytics segments exhibit divergent replacement cycles, with software platforms refreshing every 18-24 months while hardware sensors operate on 5-7 year depreciation schedules. Understanding these temporal patterns shapes procurement timing and vendor relationship strategies for infrastructure operators.
Product Type:
Software and platform segments turn over fastest due to quarterly release cycles and API versioning demands, while hardware modules face extended procurement timelines tied to facility buildout schedules.
- Software:Subscription-based telemetry ingestion tools process PUE ratios, thermal gradients, and workload latency at millisecond granularity. Demand concentrates among hyperscale operators in Northern Virginia and Dallas-Fort Worth seeking automated orchestration capabilities. Cloud-native deployment models accelerate refresh cycles as vendors push continuous integration pipelines.
- Platform:Unified analytics layers integrate compute, storage, and network telemetry into centralized dashboards with role-based access controls. European facilities under EU AI Act compliance mandates drive procurement of auditable platforms with algorithmic transparency documentation. These systems command premium pricing due to multi-vendor normalization requirements.
- Hardware:Integrated sensor arrays from Dell Technologies and others capture power distribution unit metrics and cooling system telemetry. Asian contract manufacturers have commoditized temperature and power monitoring chips, compressing margins despite rising unit volumes.
- Service:Professional implementation and managed analytics support for brownfield SCADA integration and legacy protocol gateway deployment. India's PLI scheme for datacenter infrastructure creates localized demand for deployment and training services in Mumbai and Chennai.
Software anchors the volume base while platform gains share at the steepest rate.
Application:
Cost tier differentiation separates premium predictive systems from standard monitoring tools, with fault management commanding the highest per-seat pricing due to uptime guarantee dependencies.
- Performance Monitoring:Real-time GPU-centric analytics through proprietary telemetry frameworks dominate high-performance computing deployments. Nvidia's instrumentation layers capture memory bandwidth and thermal throttling events for AI training clusters.
- Capacity Planning:Automated workload forecasting tools must demonstrate algorithmic transparency under EU AI Act requirements in European facilities. These systems qualify operators for FERC demand response revenue streams through grid-interactive power analytics.
- Fault Management:Agentic AI systems interpret natural language alerts and execute automated remediation workflows, compressing mean-time-to-resolution. Site reliability engineering talent scarcity limits deployment velocity despite strong operator demand.
- Security Analysis:FCC cybersecurity guidelines for critical infrastructure intersect with telemetry encryption requirements, shaping procurement specifications for federal operators.
Performance monitoring holds the largest installed base while fault management climbs the fastest.
End User:
Customer type segmentation reveals divergent procurement authority structures, with service providers centralizing vendor decisions while enterprises distribute purchasing across IT and facilities teams.
- Service Providers:Colocation and hyperscale operators deploy unified telemetry layers across multi-megawatt facilities to optimize PUE ratios. Consumption-based licensing models displace perpetual agreements as these buyers prefer metering aligned with actual monitored device counts.
- Enterprises:Hybrid cloud adopters leverage Azure Monitor stacks and competing platforms to anchor workloads across on-premises and cloud environments. Microsoft captures significant share through existing enterprise relationships and Office 365 integration.
- Government:Federal datacenter operators face intersecting EPA energy efficiency mandates and FCC cybersecurity guidelines, requiring sub-metering at rack-level power distribution units above 100 kilowatts.
- Educational Institutions:Research universities with HPC clusters require GPU-centric analytics for thermal management of AI training infrastructure, though budget constraints limit deployment scale.
Service providers dominate current procurement volumes while government segments expand most quickly due to regulatory compliance deadlines.
Deployment:
Geography of processing—core versus distributed—determines architecture selection, with latency requirements pushing analytics closer to data sources.
- Cloud-Based:Centralized telemetry aggregation from Microsoft, Amazon, and Google enables cross-facility benchmarking and machine learning model training at scale. GDPR data residency friction fragments architectures as European telemetry faces localization requirements.
- Edge Computing:Distributed analytics nodes outside core datacenter footprints serve latency-sensitive manufacturing and autonomous systems. This structural category expands most quickly as 5G deployment and IoT sensor proliferation generate processing demands beyond core facility capacity.
- Hybrid:Split architectures retain sensitive workload telemetry on-premises while bursting analytics processing to cloud resources. Northern Virginia operators lead deployment of these configurations to balance compliance and scalability.
- On-Premises:Air-gapped installations for classified or regulated workloads resist API-based telemetry ingestion without expensive gateway retrofits. Legacy SCADA integration debt slows modernization timelines.
Cloud-based deployment retains the largest revenue share while edge computing gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based hyperscale operators export datacenter analytics expertise and platform architectures to European and Asia-Pacific facilities seeking operational modernization. This trade corridor shapes technology transfer patterns and procurement specifications across destination markets.
United States
Hyperscale cluster concentration in Northern Virginia and Dallas-Fort Worth drives demand for unified telemetry layers across multi-megawatt facilities. EPA energy efficiency disclosure mandates require sub-metering at rack-level power distribution units above 100 kilowatts. The Northern Virginia corridor hosts the densest concentration of cloud-native analytics deployments worldwide.
Germany
Industrial manufacturing and automotive sectors require latency-sensitive edge analytics for production line optimization. EU AI Act compliance mandates algorithmic transparency for automated capacity planning systems in Frankfurt and Munich facilities. The Rhine-Main cluster anchors continental European demand for auditable platform procurement.
India
Domestic capacity buildouts in Mumbai and Chennai create localized demand for deployment and support services. The PLI scheme for datacenter infrastructure accelerates foreign direct investment into analytics platform localization. Tamil Nadu's Chennai corridor emerges as the primary southern hub for hardware-integrated sensor array installation.
United Kingdom
Financial services and fintech sectors drive consumption-based analytics licensing preferences aligned with operational expenditure treatment. GDPR data residency requirements fragment centralized architectures for cross-border telemetry streaming. The London metropolitan area concentrates hybrid cloud analytics adoption among enterprise buyers.
Japan
Precision manufacturing and robotics industries demand millisecond-granularity thermal and power telemetry for quality control integration. METI efficiency standards shape procurement specifications for facility-wide monitoring infrastructure. The Tokyo-Osaka corridor leads Asia-Pacific adoption of physics-based digital twin convergence for predictive modeling.
Datacenter Analytics Market Competitive Environment
Channel-controlling players compete with product-specialist players across software, platform, hardware, and service segments. The market exhibits tiered consolidation with hyperscale cloud providers anchoring cloud-native deployment channels while hardware-integrated specialists defend on-premises positions. Three archetypes dominate: cloud-native platform aggregators, hardware-telemetry integrators, and GPU-centric performance specialists. Competitive intensity concentrates on strategic partnerships for API ecosystem expansion and consumption-based licensing model transitions.
Within the cloud-native platform tier, Microsoft and Amazon Web Services anchor enterprise workload migration through hybrid environment integration. Dell Technologies occupies a position among hardware-integrated instrumentation providers feeding real-time dashboard architectures. Nvidia exemplifies the GPU-centric performance analytics archetype through proprietary telemetry frameworks capturing memory bandwidth and thermal events for AI training clusters.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Nvidia |
| IBM |
| Broadcom |
| Oracle |
| Others |
Value Chain & Pricing Dynamics
Taiwanese sensor foundries in Hsinchu anchor hardware module supply, translating semiconductor capacity tightness into margin pressure for integrated analytics bundles sold to European and North American facility operators.
Pricing Analysis
Cost-plus contracts with quarterly indexation to DRAM and NAND spot markets dominate hardware-software bundled procurement. Three-tier pricing structure across enterprise-grade, mid-market, and entry-level deployments separates buyers by API call volume and thermal sensor density. Price differentiation hinges on ISO 27001 certification tier and embedded AI inference capability. Cost compression in entry-level hardware modules is intensifying because Asian contract manufacturers have standardized power monitoring chip designs.
Supply Chain Analysis
Upstream feedstock for thermal sensors draws from Taiwanese semiconductor foundries, South Korean memory fabricators, and Chinese rare earth processors. Critical dependencies include precision temperature transducers, high-bandwidth memory modules, and gallium nitride power components. Single-source vulnerability concentrates in EUV lithography equipment for advanced node chips. Distribution runs through direct OEM relationships with hyperscale operators and value-added resellers serving mid-market colocation providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Datacenter analytics sits in early-cycle expansion as agentic AI pilots migrate to production deployment across Northern Virginia hyperscale facilities, creating pull-through demand for auditable telemetry platforms.
For Market Incumbents: Insulate recurring revenue streams by embedding consumption-based licensing deeper into existing Azure Monitor and competing cloud-native stacks. Threat from GPU-centric performance specialists like Nvidia demands backward integration into thermal sensor hardware to defend platform stickiness. Prioritize certification investment for EU AI Act algorithmic transparency documentation. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-driven domestic capacity buildouts where localized deployment and training services face limited incumbent saturation. Target Mumbai and Chennai facility operators with brownfield SCADA integration expertise. Go-to-market angle: fixed-fee gateway retrofit packages that accelerate legacy protocol modernization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform aggregators with normalized multi-vendor telemetry capabilities over point-solution hardware vendors. Long-term viability across the analysis window rests on API ecosystem breadth and FERC demand response qualification. Acquisition target archetype: digital twin convergence specialists with physics-based thermal modeling engines. Signal to watch: EPA sub-metering mandate enforcement intensity above 100-kilowatt thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified telemetry layers from Microsoft Azure anchor hybrid cloud workloads across Northern Virginia facilities. |
| Acquisition of Specialist Firm | Digital twin convergence targets compress predictive thermal modeling development timelines for hyperscale operators. |
| Strategic Partnership | API ecosystem expansion with Dell Technologies hardware-integrated sensor arrays deepens on-premises instrumentation reach. |
| Geographic Expansion | Localized analytics deployment in Tamil Nadu's Chennai corridor captures PLI scheme infrastructure investment flows. |
| Product Launch | Agentic AI remediation systems reduce overnight staffing requirements for tier-one facilities in Dallas-Fort Worth. |
Study Parameters
Operator-level perspectives from datacenter facility managers, site reliability engineers, colocation procurement leads, and cloud platform integration specialists anchored the qualitative base. Primary interviews combined with secondary validation against SEC filings from hyperscale cloud providers, EPA energy disclosure databases, and EU AI Act regulatory guidance documents. Bottom-up telemetry platform deployment counts and top-down infrastructure capex triangulation shaped market sizing.
Scenario-bracketing framed analytical sensitivity around edge node proliferation velocity and agentic AI adoption curves. Segmentation dimensions modeled include deployment architecture, end-user type, application function, and regional regulatory cluster. CAGRs derived from facility buildout pipeline analysis and software refresh cycle patterns. Forecast inputs incorporated FERC demand response participation rates and EU AI Act compliance deadline phasing.
Macroeconomic conditions sit as an overlay; deviation in hyperscale capex commitment cycles and electricity pricing volatility would shift the trajectory. Forecasts reflect documented assumptions on edge computing latency requirements and SCADA modernization timelines. Cross-checking against hyperscaler quarterly infrastructure investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
UAE Geospatial Analytics Market
Analytics
Workforce Analytics Market
Analytics
Behavior Analytics Market
Analytics
Scientific Text Analytics and Annotators Market
Analytics
Analytics of Things (Aot) Market
Analytics
Extract, Transform, Load (ETL) Market
Analytics
Global Streaming Analytics Market
Analytics
APAC Data Wrangling Market
Analytics
Latin America Location Based Data Analytics Market
Analytics
Europe Data Monetization Market
Analytics
ASEAN Geospatial Analytics Market
Analytics
Legal Analytics Market
Analytics
Data Mining Tools Market
Analytics
Cloud-Based Business Analytics Software Market
Analytics
Marketing Analytics Market
Analytics
Global AI Video Analytics Market