
 Asia Pacific Telecom Expense Management Market | 2026-2036
Asia Pacific Telecom Expense Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Telecom Expense Management Market Outlook
Market Context
Managed service revenue is rewriting how vendors capture value across the Asia Pacific telecom expense management landscape. Tangoe leverages its cloud-native platform architecture to anchor recurring revenue streams across multinational enterprise accounts. CGI Inc. sustains competitive positioning through deep systems integration capabilities and long-standing carrier relationships. Accenture differentiates by embedding telecom expense analytics within broader digital transformation mandates for large Australian and Japanese clients.
Technical Definition and Segments
Asia Pacific telecom expense management comprises software platforms and professional services that audit, allocate, and optimize enterprise spending on fixed-line, mobile, and data communications infrastructure, typically processing invoice volumes exceeding ten thousand monthly statements per large deployment. The primary commercial purpose centers on eliminating billing errors, enforcing corporate rate plans, and ensuring regulatory-compliant usage documentation across distributed workforces. Cloud-based deployment models now lead new implementations, while managed services capture the deepest margin pools through multi-year outsourcing contracts. AI-enabled technology segments represent the fastest-growing capability layer, though on-premise installations persist among government agencies with stringent data sovereignty requirements.
Regulatory Outlook
TRAI in India enforces telecom billing transparency rules that directly elevate demand for automated invoice validation and dispute management platforms. Australia's ACMA and Japan's MIC impose similar accountability frameworks, collectively pushing enterprises toward certified expense management solutions with embedded compliance reporting. Stakeholders must monitor how emerging data localization requirements across Southeast Asian markets reshape deployment architecture decisions and vendor qualification criteria.
Market Dynamics
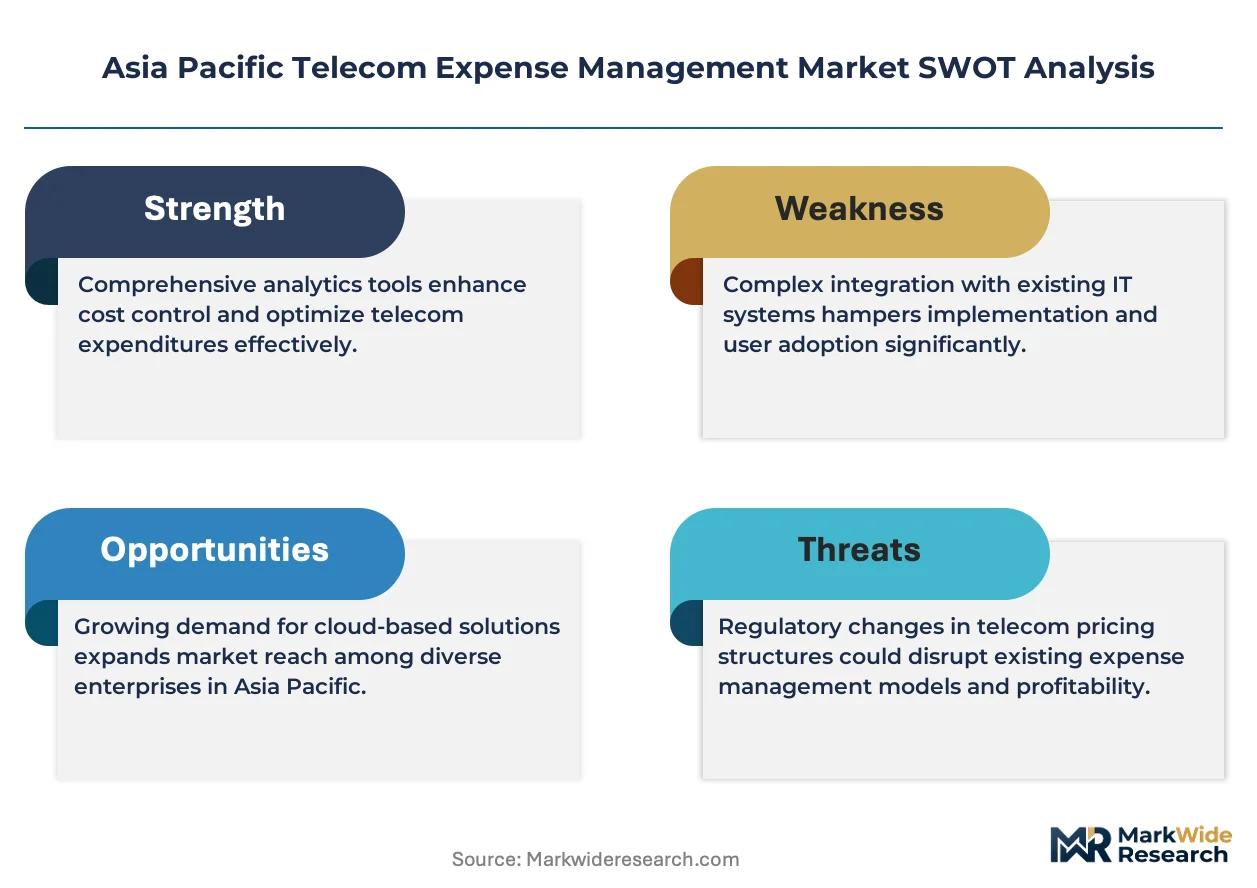
Enterprise migration from on-premise telecom management systems to cloud-native platforms is compressing deployment cycles and forcing incumbent vendors to re-architect delivery models across the Asia Pacific region.
Growth Catalysts
- TRAI billing transparency mandates:India's regulatory push for automated invoice validation is compelling enterprises to adopt certified expense management platforms with embedded dispute resolution workflows.
- Financial services spend visibility requirements:Australian banks and insurers face tightening ACMA accountability frameworks that elevate demand for real-time telecom cost allocation across distributed operations.
- AI-enabled anomaly detection:Machine learning algorithms processing mobile and data usage patterns are reducing billing error detection cycles from weeks to hours in large enterprise deployments.
Market Restraints
- Data sovereignty compliance costs:Government agencies in Japan and Australia require on-premise installations with localized data storage, inflating deployment costs versus cloud alternatives.
- Carrier billing format fragmentation:Inconsistent invoice structures across Southeast Asian mobile operators force vendors to maintain expensive custom parsing engines for each market.
- Skilled platform integration specialists:Shortage of engineers capable of bridging legacy ERP systems with modern telecom APIs constrains rollout velocity for mid-market enterprises.
Strategic Opportunities
- Indonesia's underpenetrated mid-market:Fragmented SME telecom spending across Jakarta and Surabaya lacks systematic management, creating whitespace for standardized SaaS offerings.
- 5G usage-based pricing models:Emerging enterprise 5G contracts with variable rate structures demand dynamic expense management tools that legacy platforms cannot support.
- Singapore's smart nation procurement frameworks:Government mandates for transparent vendor spend management are opening public sector contracts to certified telecom expense platforms.
Industry Challenges
- Multi-carrier contract harmonization:Enterprises operating across Australia, Japan, and India must reconcile disparate rate plans and service-level agreements within unified dashboards.
- API standardization delays:Inconsistent carrier data interfaces across the region force vendors to maintain brittle custom integrations that break when carriers update billing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Telecom Expense Management Market |
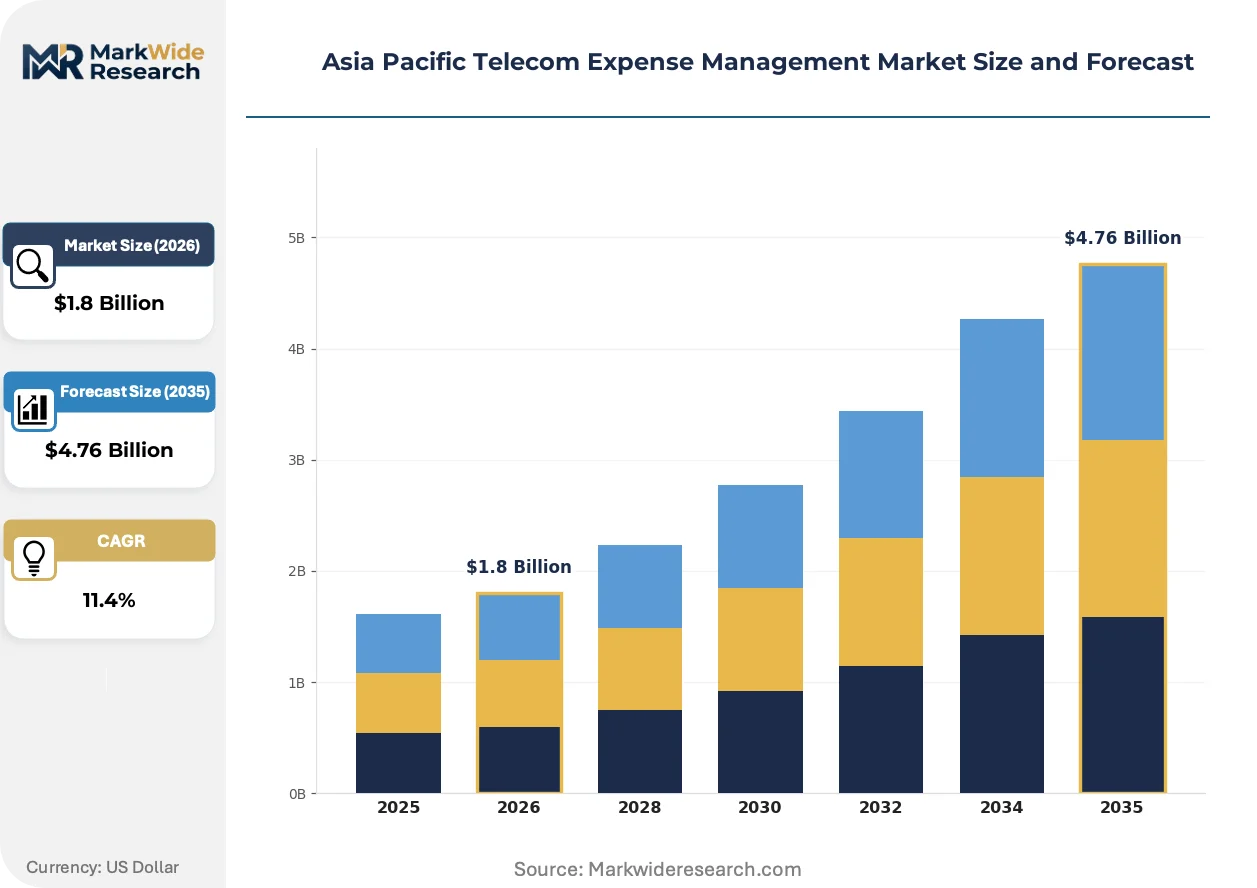
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Services, Software Solutions, Consulting, Support Services Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Enterprises, Small & Medium Businesses, Government Agencies, Non-Profits Technology: AI, Analytics, Automation, Mobile Solutions |
| Companies Covered | Avotus, CGI Inc., Tangoe, Vodafone Group, Accenture, Calero-MDSL, WidePoint Corporation, Dimension Data, Sakon, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Telecom Expense Management Market Strategic Shifts
Artificial intelligence and regulatory pressure are converging to transform how enterprises procure, deploy, and optimize telecom expense management capabilities across Asia Pacific markets.
AI-powered invoice auditing is hybridizing traditional expense management by combining optical character recognition with predictive analytics to flag anomalous charges before payment authorization. Australian financial services firms and Japanese manufacturers are deploying these hybrid platforms at accelerated rates, compressing the traditional 90-day audit cycle into continuous real-time validation. The technology is hybridizing vendor competitive positioning by merging software automation with managed service expertise, forcing pure-play software providers to build professional services capabilities or cede enterprise accounts to integrated competitors.
India's TRAI billing accuracy regulations are mandating automated dispute documentation and carrier response tracking for enterprises above defined spend thresholds. The framework is elevating procurement standards by requiring certified platform validation before contract award in government and regulated sectors. Indian IT services firms and multinational banks with Mumbai and Bangalore operations are responding by embedding compliance reporting directly into procurement workflows rather than treating it as retrospective audit activity.
Enterprise buyers are consolidating vendor relationships from fragmented point solutions toward integrated telecom, mobility, and cloud expense management platforms. The shift is compressing procurement cycles as CFOs demand single-source accountability for communications spend across fixed, mobile, and SaaS infrastructure. This concentration is most visible in Australia's government and financial services verticals, where shared services organizations are mandating unified platforms to satisfy ACMA transparency requirements while reducing vendor management overhead.
Asia Pacific Telecom Expense Management Market Segmentation
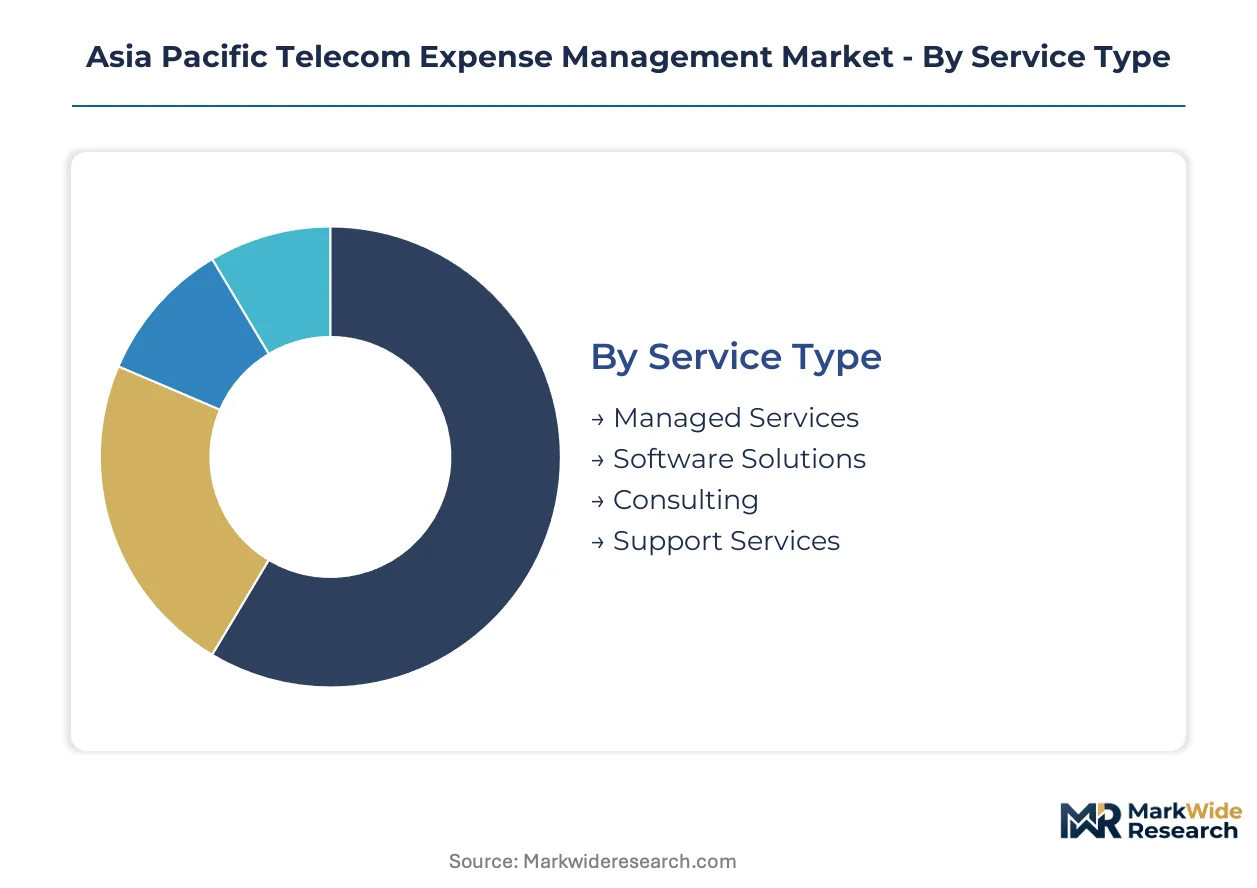
Service delivery models and deployment architectures fragment the Asia Pacific telecom expense management landscape into distinct value capture tiers. Vendors must align capabilities across managed services, software platforms, and emerging AI layers to match divergent enterprise procurement patterns.
Service Type:
Mature outsourcing contracts coexist with emerging self-service platforms across the maturity spectrum.
- Managed Services:Comprehensive outsourcing of invoice processing, dispute resolution, and carrier negotiation functions. Australian financial services and Japanese manufacturers favor multi-year contracts with guaranteed cost reduction targets embedded in service-level agreements.
- Software Solutions:Cloud-native platforms enabling internal telecom cost management with configurable workflows. India's TRAI-mandated transparency requirements are accelerating procurement of automated validation engines among IT services firms with Mumbai and Bangalore headquarters.
- Consulting:Advisory engagements for contract renegotiation and rate plan optimization. Brief interventions address specific carrier disputes or migration planning for 5G transitions.
- Support Services:Helpdesk and technical assistance for platform administration. Tier-1 vendors bundle these with core software subscriptions to reduce customer churn.
Managed Services retains volume leadership; Software Solutions holds the steepest expansion curve.
Deployment:
Cost tier differentiation separates premium on-premise installations from standardized cloud offerings.
- Cloud-Based:Scalable architectures with subscription pricing and rapid deployment cycles. Singaporean government agencies under smart nation mandates are procuring these platforms to satisfy transparent spend management requirements.
- On-Premise:Localized infrastructure with dedicated hardware for data sovereignty compliance. Australian and Japanese government entities mandate these deployments despite 40-60% higher total cost of ownership.
- Hybrid:Split configurations retaining sensitive data on-premise while leveraging cloud analytics. Indonesian banks with Jakarta headquarters adopt this model to balance regulatory caution with operational agility.
- SaaS:Pure subscription models with minimal customization and fastest time-to-value. Mid-market enterprises across Southeast Asia favor this approach for mobile expense management.
Cloud-Based deployments dominate new implementations; SaaS is gaining share fastest among cost-constrained buyers.
End User:
Application complexity varies sharply between centralized enterprise procurement and distributed small business adoption.
- Enterprises:Multinational corporations with monthly invoice volumes exceeding ten thousand statements. These buyers demand unified dashboards reconciling Australia, Japan, and India carrier contracts within single accountability frameworks.
- Small & Medium Businesses:Organizations with fragmented telecom spending lacking systematic management. Surabaya and Jakarta-based SMEs represent underpenetrated whitespace for standardized offerings.
- Government Agencies:Public sector entities with stringent compliance and transparency mandates. ACMA accountability frameworks in Australia and Singapore's procurement regulations elevate demand for certified platforms.
- Non-Profits:Cost-sensitive organizations prioritizing basic invoice validation over advanced analytics. Limited procurement sophistication constrains addressable spend per account.
Enterprises retain volume leadership; Government Agencies hold the steepest expansion curve.
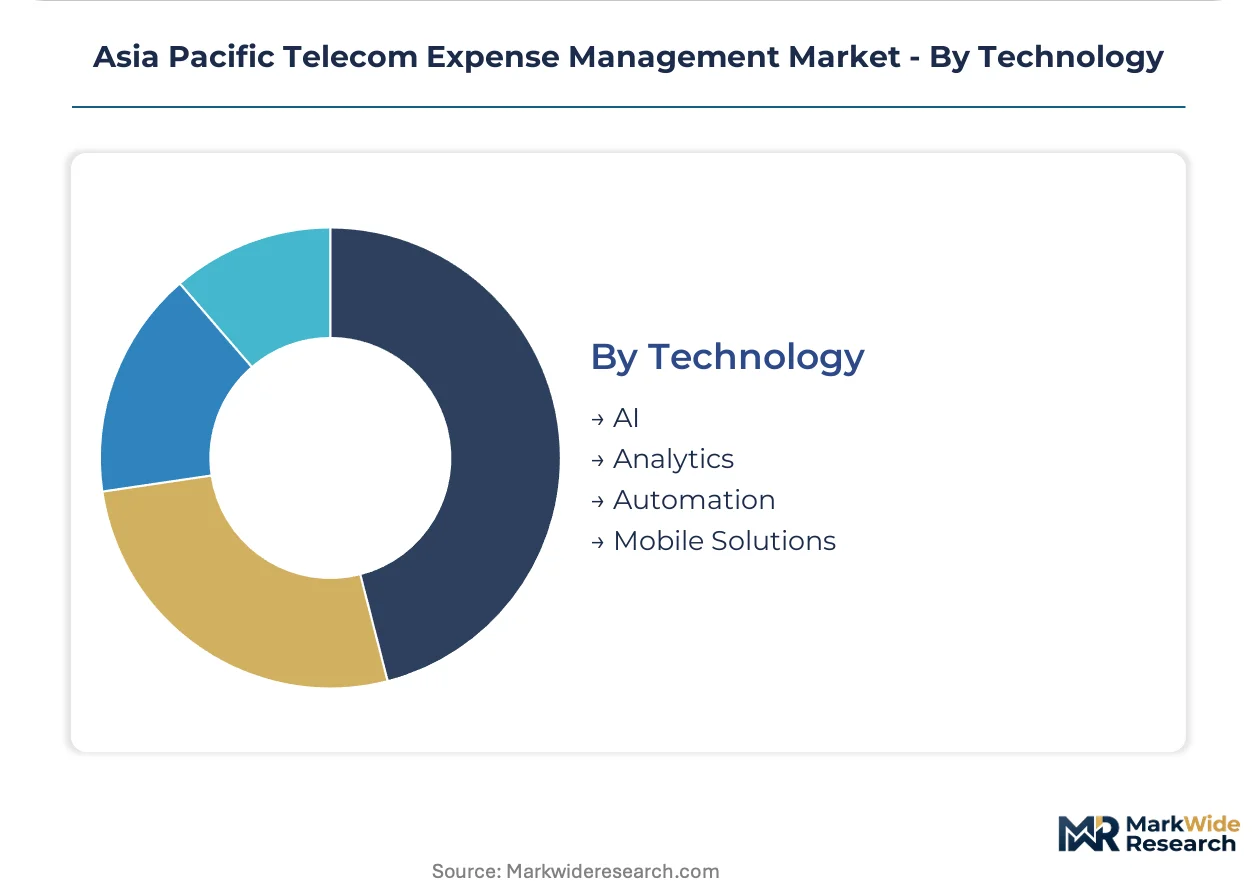
Technology:
Margin concentration follows capability sophistication from basic automation through predictive AI layers.
- AI:Machine learning algorithms processing usage patterns to flag anomalous charges before payment authorization. Australian banks deploy these systems to compress 90-day audit cycles into continuous real-time validation.
- Analytics:Business intelligence dashboards for cost allocation and trend visualization. Shared services organizations mandate these capabilities to satisfy CFO demands for communications spend visibility.
- Automation:Rules-based workflow engines for invoice ingestion and approval routing. Foundational capability layer with diminishing differentiation as vendors standardize offerings.
- Mobile Solutions:Smartphone applications for field workforce expense submission and policy enforcement. Growing importance as distributed workforces expand across the region.
Analytics retains volume leadership; AI holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian financial services and government sectors anchor regional demand through stringent spend visibility mandates, while India's TRAI-driven procurement reforms accelerate platform adoption at fundamentally different price points and deployment speeds.
Australia
ACMA accountability frameworks compel banks and insurers to implement real-time telecom cost allocation across distributed operations. Government shared services organizations mandate unified platforms to satisfy transparency requirements while reducing vendor management overhead. Sydney and Melbourne financial services clusters drive premium-tier demand for AI-enabled anomaly detection systems.
India
TRAI billing transparency rules elevate procurement standards for automated invoice validation and dispute management platforms. IT services firms with Mumbai and Bangalore headquarters embed compliance reporting directly into procurement workflows. The National Capital Region witnesses accelerated adoption among multinational banks responding to retrospective audit mandates.
Japan
MIC accountability frameworks push enterprises toward certified expense management solutions with embedded compliance reporting. Government agencies require on-premise installations with localized data storage despite substantially higher total cost of ownership. Tokyo and Osaka manufacturing clusters favor multi-year managed service contracts with guaranteed cost reduction targets.
Singapore
Smart nation procurement frameworks mandate transparent vendor spend management across public sector contracts. Government agencies procure cloud-based platforms to satisfy real-time visibility requirements. The city-state's financial services sector concentrates demand for unified dashboards reconciling regional carrier contracts.
Indonesia
Fragmented SME telecom spending across Jakarta and Surabaya lacks systematic management, creating whitespace for standardized SaaS offerings. Banking regulators encourage expense transparency without mandating specific platform certifications. Mid-market enterprises favor pure subscription models with minimal customization for mobile expense management.
Asia Pacific Telecom Expense Management Market Competitive Environment
Capability concentration sits with integration specialists; scale advantage sits with cloud-native platform providers. The vendor base stratifies across three tiers: multinational consultancies embedding telecom analytics within broader digital transformation mandates, pure-play software vendors re-architecting delivery models around subscription pricing, and carrier-affiliated service providers leveraging billing relationships. Dominant competitive moves include multi-year outsourcing contract pursuit and AI capability layer integration.
Within the cloud-native tier, Tangoe exemplifies recurring revenue capture through multinational enterprise accounts. CGI Inc. occupies a position among systems integration specialists sustaining competitive positioning through long-standing carrier relationships. Accenture anchors the consultancy tier by embedding telecom expense analytics within broader digital transformation mandates for large Australian and Japanese clients.
| Leading Market Players |
|---|
| Avotus |
| CGI Inc. |
| Tangoe |
| Vodafone Group |
| Accenture |
| Calero-MDSL |
| WidePoint Corporation |
| Dimension Data |
| Sakon |
| Others |
Value Chain & Pricing Dynamics
Singapore-Jakarta data corridor freight costs compress margin structures for cloud-native platform vendors serving Indonesian mid-market buyers while amplifying price premiums for Australian government on-premise deployments. This logistics tension concentrates vendor pricing power among those with localized hosting partnerships across the archipelago, forcing SaaS providers to absorb delivery cost volatility or surrender share to carrier-affiliated competitors with captive infrastructure.
Pricing Analysis
Long-term managed service offtake contracts dominate enterprise procurement in Australian financial services and Japanese manufacturing, embedding guaranteed cost reduction targets within multi-year service-level agreements. Price differentiation rests on certification tier—ACMA-compliant platforms command substantial premiums over uncertified alternatives—and customization depth for legacy ERP integration. Cost compression in mid-market SaaS tiers intensifies as standardized mobile expense management tools proliferate across Southeast Asia. Government agencies in Australia and Japan exhibit lowest price sensitivity due to data sovereignty mandates, while Indonesian SMEs prioritize pure subscription models with minimal implementation fees.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscaler data centers concentrated in Singapore, Australia, and Japan, with compute and storage resources forming the primary cost stack for platform delivery. Software development talent clusters in Bangalore, Sydney, and Tokyo, creating geographic dependencies for AI-enabled anomaly detection engineering. Single-source vulnerability sits with carrier API standardization delays across Southeast Asia, where inconsistent billing data formats force vendors to maintain brittle custom parsing engines. Distribution runs through direct enterprise sales teams for large accounts and channel partners for mid-market penetration, with carrier billing relationships providing alternative pathways in fragmented markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection in this market centers on interoperability consolidation, where vendor survival hinges on unified dashboard capabilities spanning fixed, mobile, and cloud infrastructure rather than point solutions for isolated spend categories.
For Market Incumbents: Pre-empt displacement by pure-play AI vendors through embedding predictive analytics within existing managed service contracts before renewal cycles. Deepen upstream control over carrier API integration layers to lock out competitors dependent on standardized data feeds. Invest in ACMA and TRAI certification maintenance as defensive moats against unqualified entrants bidding on government and financial services mandates.
For New Entrants and Emerging Players: Surabaya and Jakarta mid-market whitespace offers lowest competitive density for standardized SaaS mobile expense management with rapid deployment cycles. Target Indonesian banking sector procurement officers seeking expense transparency without mandated platform certification. Lead with smartphone-native field workforce applications that bypass legacy ERP integration complexity dominating incumbent sales cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-enabled platform vendors with demonstrated carrier API standardization capabilities and recurring revenue concentration above project-based consulting. Long-term viability across the analysis window rests on migration from on-premise installations toward cloud-native architectures with embedded compliance reporting. Monitor TRAI enforcement intensity and ACMA audit frequency as inflection indicators for regulatory-driven procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Capability Layer Integration | Machine learning anomaly detection compresses audit cycles for Australian banks from quarterly to continuous validation. |
| Carrier API Standardization Partnership | Direct billing data agreements with Singtel and Telstra reduce custom parsing maintenance costs for platform vendors. |
| ACMA Certification Investment | Compliance accreditation unlocks Australian government shared services contracts with multi-year procurement horizons. |
| Indonesia Geographic Expansion | Jakarta and Surabaya mid-market penetration captures SME telecom spend lacking systematic management platforms. |
| Hybrid Deployment Architecture Development | Split cloud-on-premise configurations satisfy Indonesian bank regulatory caution without sacrificing analytics agility. |
Study Parameters
Operator-level perspectives from telecom procurement officers, IT finance directors, carrier billing system architects, and managed service contract managers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against TRAI regulatory filings, ACMA transparency mandate documentation, hyperscaler capex disclosures, and enterprise software procurement databases. Bottom-up deployment sizing across service type, deployment model, and end-user segments triangulated with top-down market aggregation from vendor revenue disclosures and carrier service revenue breakdowns.
Scenario-bracketing framed the analytical approach across the projection horizon, with base, optimistic, and conservative cases reflecting varying assumptions for 5G enterprise adoption velocity and regulatory enforcement intensity. Segmentation dimensions modeled include service delivery type, deployment architecture, organization size tier, technology capability layer, and country-specific regulatory cluster. CAGRs derived from fitted growth curves applied to base-year sizing, with inputs from AI adoption surveys in Australian financial services and TRAI compliance audit frequency trends in Indian IT services.
Practitioners should monitor carrier billing system modernization timelines and data localization requirement announcements across Southeast Asian markets for early signals of forecast revision. Cross-checking against hyperscaler regional data center expansion announcements and ACMA audit penalty distributions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Telecommunication Market
Telecommunications
Philippines Telecom Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Poland Telecom Market
Telecommunications
Promotional Sms Market
Telecommunications
DECT System Market
Telecommunications
Virtual CPE (Vcpe) Market