
 Automotive Special Purpose Logic IC Market | 2026-2036
Automotive Special Purpose Logic IC Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Special Purpose Logic IC Market Outlook
Modular system-on-chip packaging is shifting how Tier-1 suppliers evaluate logic IC procurement, compressing vendor selection cycles from discrete component sourcing to platform-level decisions. NXP Semiconductors leverages its automotive-qualified CMOS portfolio to anchor supply relationships with European OEMs. Texas Instruments competes through vertical integration into wafer fabrication, sustaining margin control across analog and mixed-signal categories. Infineon Technologies specializes in power IC modules for traction inverters, dominating silicon and silicon carbide interfaces for electrified powertrains.
Automotive special purpose logic ICs are application-specific integrated circuits engineered to execute dedicated signal processing, timing, and control functions under AEC-Q100 temperature and reliability specifications, typically operating between minus 40 and 150 degrees Celsius. These devices manage sensor interfacing, protocol translation, and deterministic real-time responses across vehicle subsystems where general-purpose processors fail to meet latency or power constraints. Mixed-signal ICs capture expanding margin pools as electrification architectures demand tighter integration between analog sensor fronts and digital control loops. Power ICs lead volume consumption due to proliferation of DC-DC converters and gate drivers across 48-volt mild hybrid and battery electric platforms.
Functional safety mandates from ISO 26262 and semiconductor reliability protocols under AEC-Q100 shape product roadmaps and qualification timelines for every supplier serving OEM and Tier-1 channels. The U.S. Department of Commerce export controls on advanced manufacturing equipment and China's MIIT domestic substitution targets are fragmenting supply chain strategies across geographic boundaries. Stakeholders must monitor how regional content requirements and dual-use technology restrictions reshape foundry partnerships and second-source qualifications.
Market Dynamics
Sensor fusion architectures for advanced driver assistance systems are compressing discrete component procurement into platform-level decisions, forcing Tier-1 suppliers to restructure vendor qualification timelines and consolidate around system-on-chip partnerships.
Growth Catalysts
- EU Green Deal emission frameworks:The regulation mandates higher semiconductor content per vehicle as OEMs electrify powertrains, directly expanding logic IC consumption across 48-volt and battery electric platforms.
- Silicon carbide traction inverters:Power IC modules managing silicon and silicon carbide interfaces are capturing expanding volume as electrification architectures proliferate DC-DC converters and gate drivers.
- Germany:Automotive electronics clusters around Munich and Stuttgart anchor European IC demand, concentrating design-in activity and foundry partnerships within this geography.
Market Restraints
- Advanced manufacturing equipment access:U.S. Department of Commerce export controls fragment foundry partnerships and extend second-source qualification timelines for suppliers serving multiple geographies.
- MIIT domestic substitution targets:China's industrial policy accelerates captive production capacity, reducing import dependency and reshaping competitive access for foreign logic IC vendors.
- Functional safety certification burden:ISO 26262 mandates and AEC-Q100 reliability protocols impose 18-24 month qualification cycles that constrain product roadmap velocity and R&D amortization.
Strategic Opportunities
- India PLI scheme for automotive electronics:Production-linked incentives attract semiconductor packaging and test investments, creating localized supply options for OEMs diversifying beyond East Asian concentration.
- Sensor-to-digital convergence:Mixed-signal ICs integrating analog sensor fronts with digital control loops capture margin expansion as electrification architectures demand tighter subsystem integration.
- Platform-level procurement contracts:Modular system-on-chip packaging enables suppliers to embed deeper into Tier-1 roadmaps, compressing discrete component sourcing into multi-year architecture commitments.
Industry Challenges
- Deterministic real-time engineering talent:Scarcity of specialists capable of optimizing latency and power constraints under AEC-Q100 temperature specifications extends development cycles and inflates compensation.
- Dual-use technology restriction navigation:Suppliers must maintain parallel qualification tracks for restricted and unrestricted process nodes, duplicating validation costs and complicating inventory management.
- Legacy vehicle architecture integration:New logic IC designs face friction interfacing with established CAN and LIN bus systems, requiring bridge components that add cost and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Special Purpose Logic IC Market |
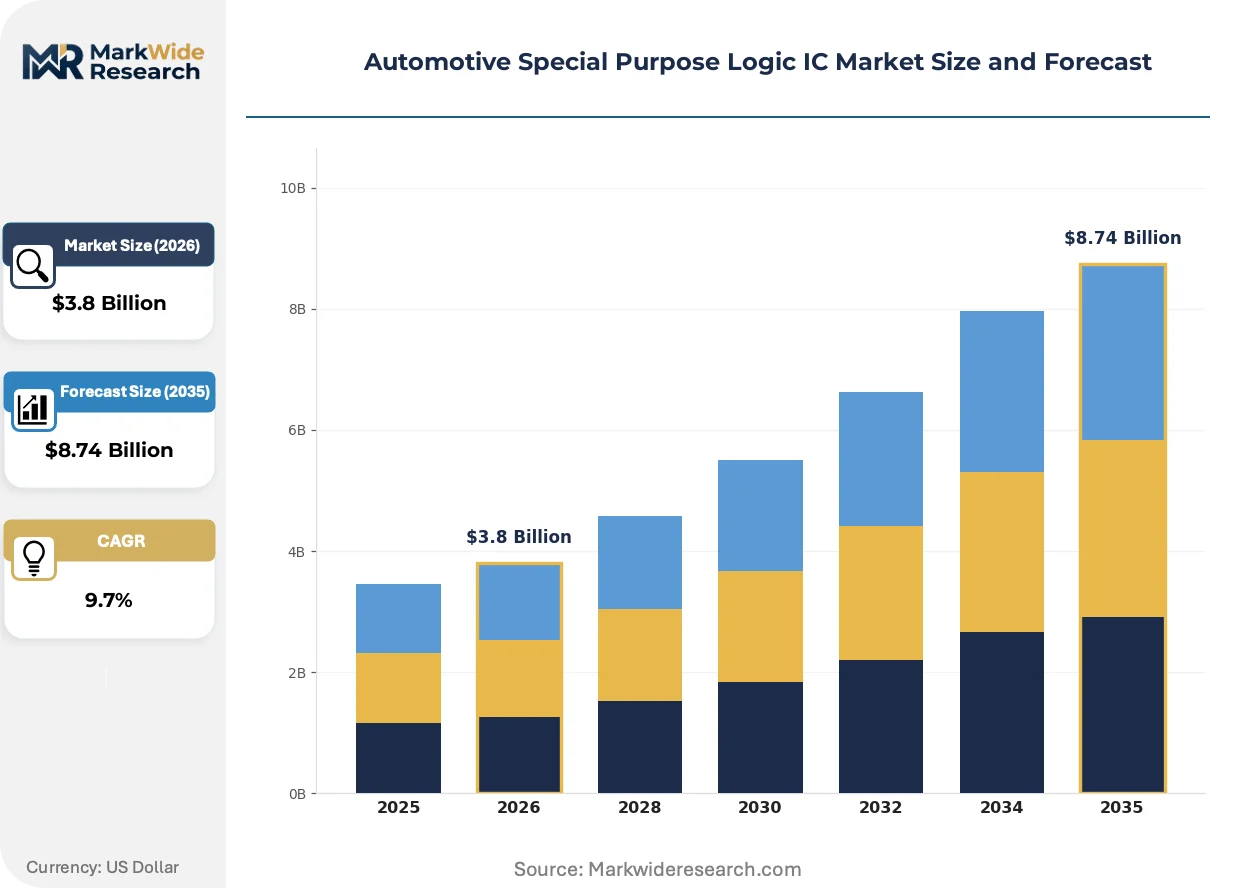
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ICs, Digital ICs, Mixed-Signal ICs, Power ICs Application: Safety Systems, Infotainment Systems, Power Management, Driver Assistance Technology: CMOS, Bipolar, BiCMOS, GaN End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Renesas Electronics, Qualcomm, STMicroelectronics, Analog Devices, Texas Instruments, NXP Semiconductors, Broadcom, ROHM, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Special Purpose Logic IC Market Strategic Shifts
Functional safety mandates and supply chain fragmentation are accelerating architectural consolidation, with three distinct forces reshaping how logic ICs are designed, qualified, and procured across vehicle platforms.
Chiplets integrating heterogeneous process nodes are consolidating signal processing and power management functions into unified substrates. Tier-1 suppliers adopting these advanced packages compress board space and thermal budgets by 30-40% versus discrete implementations. The structural consequence is consolidating Tier-2 component vendors into platform-level partnerships with fewer, deeper supplier relationships.
REACH substance restrictions and RoHS compliance updates are forcing material substitutions in packaging and interconnect metallurgy. European OEMs now mandate full material disclosure upstream to foundry partners, extending qualification protocols. Power IC categories face the tightest compliance windows as traction inverter applications fall under expanded substance scrutiny.
Automakers are unbundling after-sales semiconductor inventory risk from traditional component contracts, transferring obsolescence liability to suppliers through lifecycle guarantee clauses. This restructuring concentrates procurement leverage with OEMs possessing volume scale across multiple vehicle platforms. German and Japanese automakers lead this contractual evolution, with North American OEMs following within 18-24 month lag patterns.
Automotive Special Purpose Logic IC Market Segmentation
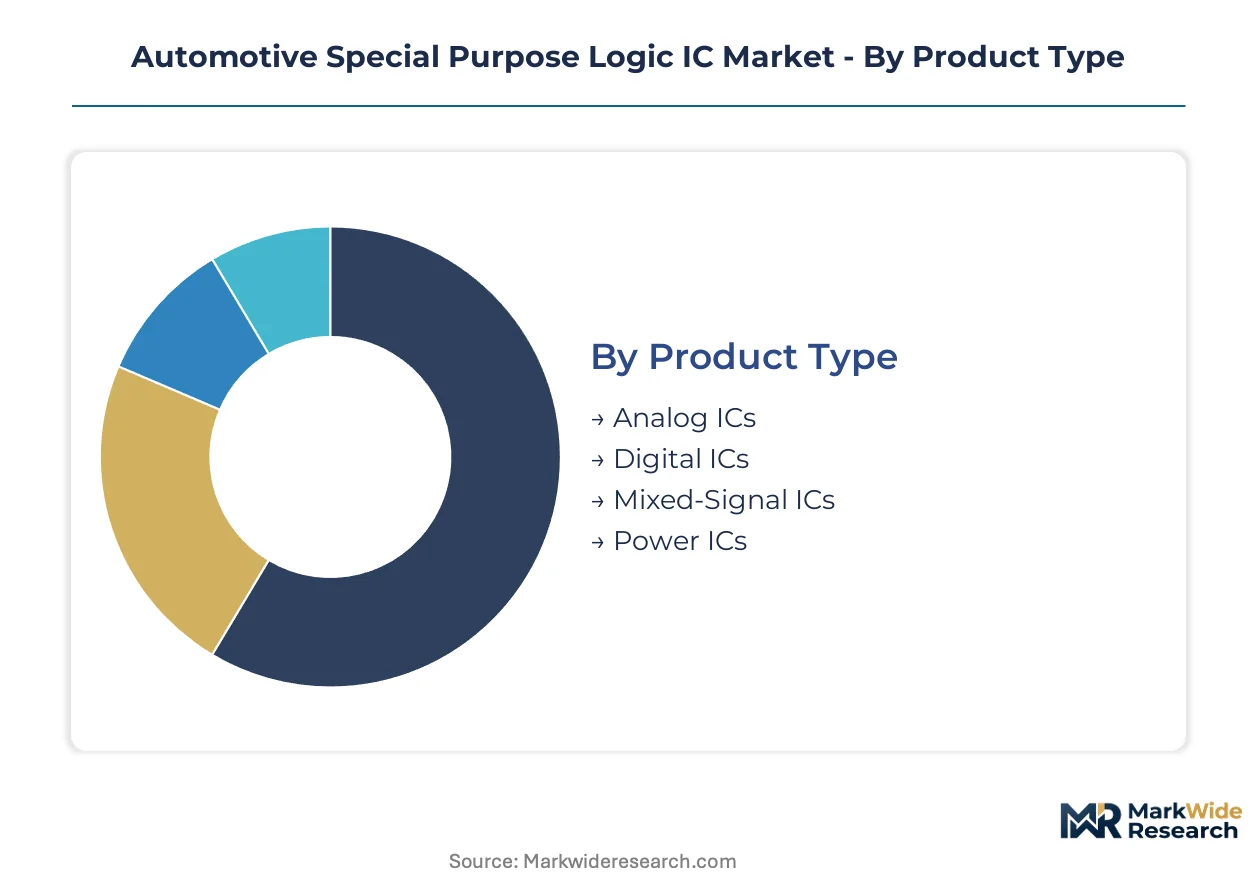
Automotive special purpose logic ICs fragment across four critical axes that determine design priorities, qualification burdens, and margin capture. Product type dictates thermal and reliability specifications under AEC-Q100 protocols. Application segments impose divergent latency requirements and functional safety tiers per ISO 26262. Technology nodes balance power efficiency against foundry access constraints. End-user channels concentrate procurement leverage differently across OEM direct sourcing and Tier-1 platform integration.
Product Type:
Silicon process maturity and integration density separate these categories, with electrification architectures pulling demand toward higher-complexity mixed-signal and power variants.
- Power ICs:Gate drivers and DC-DC converters operate across minus 40 to 150 degrees Celsius with deterministic switching characteristics. Traction inverters for battery electric and 48-volt mild hybrid platforms in Germany, China, and the United States concentrate procurement volumes as OEMs electrify powertrains under EU Green Deal and EPA emission frameworks.
- Mixed-Signal ICs:Devices integrating analog sensor interfaces with digital control loops execute protocol translation and real-time signal conditioning. Advanced driver assistance systems demanding tighter subsystem integration in Stuttgart and Munich electronics clusters drive design-in activity for these higher-margin categories.
- Analog ICs:Dedicated signal processing and voltage reference functions serve legacy vehicle architectures requiring discrete component reliability.
- Digital ICs:Pure logic functions execute timing and control operations where general-purpose processors fail latency constraints.
Power ICs lead on scale; mixed-signal ICs lead on momentum.
Application:
Functional safety classification and real-time determinism requirements segment procurement priorities across vehicle subsystems.
- Driver Assistance:Sensor fusion architectures for camera, radar, and lidar interfaces demand sub-millisecond latency with ASIL-D safety ratings. NHTSA and EU vehicle safety regulations mandating automatic emergency braking and lane-keeping assistance in the United States and European Union expand addressable content per vehicle.
- Safety Systems:Airbag deployment, anti-lock braking, and electronic stability control execute deterministic responses under fault conditions. ISO 26262 certification timelines extending 18-24 months constrain supplier qualification velocity for these mission-critical functions.
- Power Management:Battery monitoring and thermal management ICs protect electrified powertrain investments across OEM platforms.
- Infotainment Systems:Protocol bridges and display controllers manage human-machine interfaces where latency tolerances relax relative to safety-critical domains.
Driver assistance captures the steepest expansion trajectory; safety systems anchor revenue stability.
Technology:
Process node availability and wide-bandgap material maturity determine performance ceilings and supply security across foundry partnerships.
- CMOS:Automotive-qualified complementary metal-oxide-semiconductor dominates volume production with established AEC-Q100 qualification paths. European and East Asian foundry networks supply mature nodes for sensor interfacing and control logic across Tier-1 supplier roadmaps.
- GaN:Gallium nitride power devices enable higher switching frequencies and reduced thermal losses in traction inverters. U.S. Department of Commerce export controls on advanced manufacturing equipment fragment access to epitaxial growth capacity for foreign suppliers.
- BiCMOS:Bipolar-CMOS integration serves precision analog-to-digital conversion in mixed-signal applications.
- Bipolar:Discrete transistor processes persist in legacy voltage regulation and timing functions.
CMOS dominates production scale; GaN gains share fastest in electrification applications.
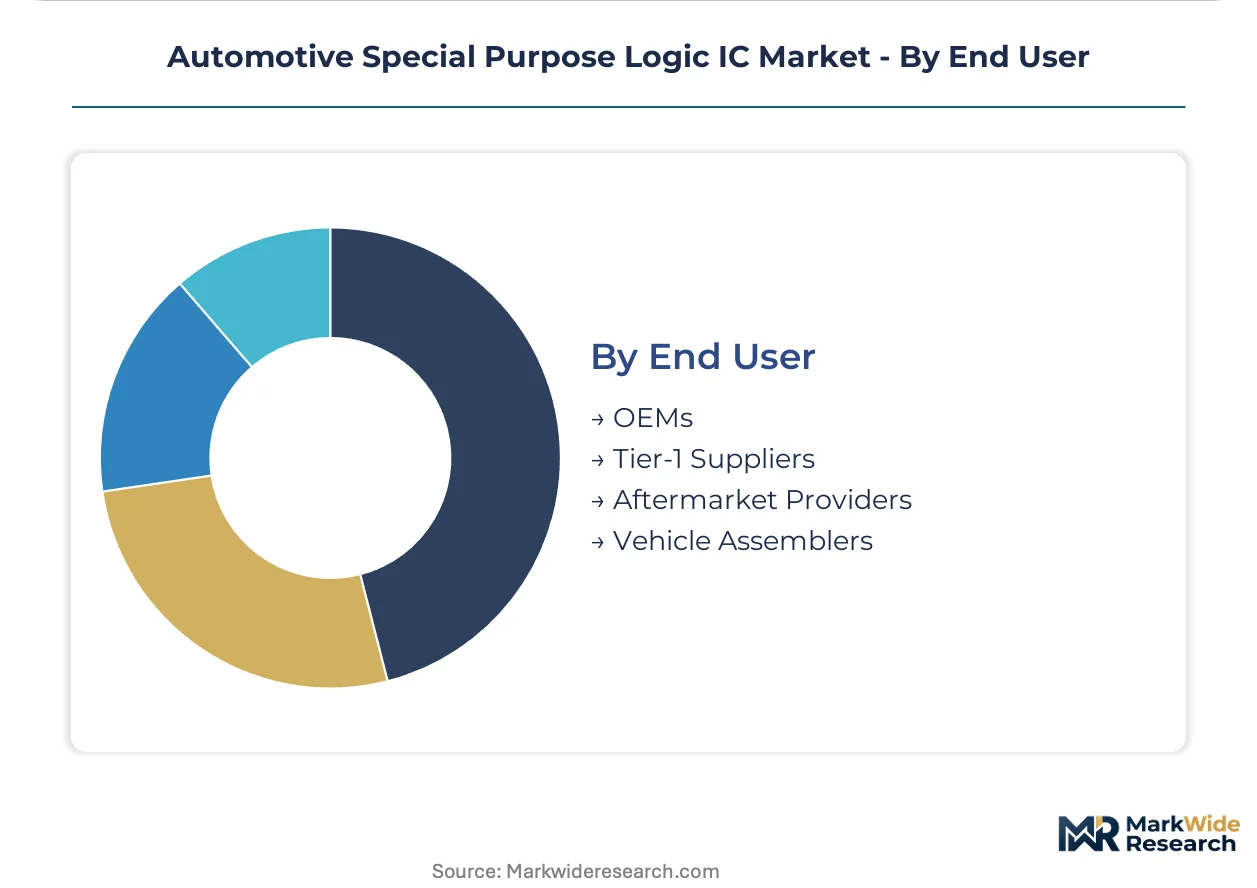
End User:
Procurement leverage and lifecycle liability allocation concentrate differently across direct OEM relationships and Tier-1 platform sourcing.
- Tier-1 Suppliers:Continental, Bosch, and Denso consolidate discrete component procurement into multi-year system-on-chip platform commitments. Modular packaging decisions in German and Japanese electronics clusters compress vendor qualification timelines and embed suppliers deeper into architecture roadmaps.
- OEMs:Volkswagen, Toyota, and Ford exercise direct sourcing for strategic semiconductor categories, transferring obsolescence risk to suppliers through lifecycle guarantee clauses. This contractual evolution concentrates procurement leverage with volume-scale automakers.
- Vehicle Assemblers:Contract manufacturing arrangements in emerging production regions access localized packaging and test capacity.
- Aftermarket Providers:Replacement component distributors serve legacy fleet maintenance with extended availability requirements.
Tier-1 suppliers anchor design-in volume; OEMs concentrate contractual leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive special purpose logic IC production originated in German precision engineering clusters during the 1980s, then diffused to Japanese electronics corridors and American semiconductor corridors through the 1990s. Foundry capacity now spans three continents with design-in authority concentrated in original equipment manufacturer headquarters.
Germany
EU Green Deal mandates on vehicle emissions accelerate logic IC consumption across electrified powertrain platforms. KBA enforces type-approval standards that embed semiconductor reliability requirements into homologation protocols. Munich and Stuttgart electronics clusters anchor European design-in activity, with Tier-1 suppliers consolidating procurement around system-on-chip architectures for advanced driver assistance systems.
United States
NHTSA automatic emergency braking regulations expand addressable semiconductor content per vehicle across Detroit and California automotive design centers. EPA emission frameworks push OEMs toward higher semiconductor density in powertrain electrification. Austin and Phoenix semiconductor corridors host foundry investments serving domestic OEM qualification timelines.
China
MIIT domestic substitution targets accelerate captive production capacity for automotive logic ICs across electrified vehicle platforms. Dual carbon goals mandate semiconductor-intensive powertrain architectures. Shanghai and Shenzhen electronics clusters concentrate design activity, with local foundries expanding automotive-qualified CMOS capacity under national industrial policy directives.
Japan
METI automotive semiconductor supply chain resilience programs incentivize domestic fabrication capacity for mission-critical vehicle electronics. JIS standards embed AEC-Q100 reliability protocols into component procurement specifications. Nagoya and Tokyo electronics corridors anchor Tier-1 supplier engineering centers, with mixed-signal IC design activity concentrating around Toyota and Honda platform roadmaps.
South Korea
MFDS automotive electronics safety frameworks align with ISO 26262 functional safety mandates across Seoul Capital Area semiconductor clusters. Government battery electric vehicle subsidies expand logic IC demand for traction inverter and battery management applications. Samsung and Hyundai platform integration drives foundry partnerships for automotive-qualified process nodes.
Automotive Special Purpose Logic IC Market Competitive Environment
Premium-margin players sit above commodity-margin players across functional safety certification tiers, with ASIL-D qualified suppliers capturing pricing power in driver assistance and safety system categories. The vendor base concentrates around three strategic archetypes: diversified semiconductor conglomerates with automotive-qualified CMOS portfolios, power IC specialists with silicon carbide traction inverter expertise, and mixed-signal integrators bridging analog sensor fronts with digital control loops. Dominant competitive moves include backward integration into captive wafer fabrication and multi-year platform-level procurement contracts that embed suppliers into Tier-1 architecture roadmaps.
Within the diversified conglomerate tier, NXP Semiconductors and Texas Instruments occupy positions defined by geographic anchoring and manufacturing structure. Infineon Technologies exemplifies the power IC specialist archetype with its German AG structure and traction inverter focus. These three entities represent distinct strategic postures: European automotive electronics cluster integration, American vertical manufacturing control, and German powertrain electrification specialization.
| Leading Market Players |
|---|
| Renesas Electronics |
| Qualcomm |
| STMicroelectronics |
| Analog Devices |
| Texas Instruments |
| NXP Semiconductors |
| Broadcom |
| ROHM |
| Infineon Technologies |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer spot indices and 300mm substrate contract pricing cascade through automotive logic IC supply chains into three distinct procurement tiers. Tier-1 suppliers purchasing AEC-Q100 qualified power modules face cost-plus structures tethered to foundry utilization rates, while aftermarket distributors absorb inventory risk through lifecycle guarantee clauses. OEM direct sourcing concentrates pricing leverage with volume-scale automakers operating across German and Japanese electronics clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified safety ICs from industrial-grade alternatives. Certification grade and volume scale drive price differentiation, with ISO 26262 qualified devices commanding 40-60% premiums over non-automotive equivalents. Cost compression in standard-tier mixed-signal categories is intensifying because foundry capacity expansion in East Asia feeds component oversupply. Aftermarket providers exhibit highest price sensitivity due to extended availability requirements and fragmented demand.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Long Beach anchor hub-and-spoke patterns for automotive-qualified components. Taiwan, South Korea, and Germany concentrate wafer fabrication and packaging capacity for AEC-Q100 devices. Raw material dependencies span 300mm silicon wafers, high-purity copper interconnects, and ceramic substrate materials. Single-source vulnerability around advanced CMOS nodes fragments procurement strategies as U.S. Department of Commerce export controls restrict equipment access. Distribution runs through authorized Tier-1 supplier channels and OEM direct allocation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as electrification architectures shift demand toward ASIL-D certified power management and sensor fusion ICs. Premium specification requirements for traction inverters and battery management systems reward suppliers with functional safety credentials and captive foundry access.
For Market Incumbents: Cement platform-level procurement relationships with German and Japanese Tier-1 suppliers through multi-year system-on-chip architecture commitments. Expand backward integration into 300mm wafer fabrication to defend margin position against commodity pricing pressure in standard-tier categories. Prioritize AEC-Q100 qualification velocity to maintain design-in precedence as ISO 26262 certification timelines extend.
For New Entrants and Emerging Players: The 40-60% price-point gap between ASIL-D premium devices and industrial-grade alternatives opens white-space in mid-tier sensor interfacing applications. Target India's PLI scheme for automotive electronics packaging investments to establish localized supply credibility with OEMs diversifying beyond East Asian concentration. Pursue mixed-signal IC design partnerships with Stuttgart and Munich engineering clusters as a go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with mixed-signal specialists possessing analog-to-digital integration capabilities for electrification architectures. Long-term viability over a multi-year horizon favors suppliers with automotive-qualified CMOS portfolios and existing Tier-1 platform embeddings. Watch for inflection signals in silicon carbide traction inverter adoption rates as a demand accelerator for power IC categories.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidates discrete component procurement around system-on-chip architectures with German Tier-1 suppliers. |
| Battery Supply Agreement | Secures long-term foundry allocation for power management ICs serving 48-volt and battery electric platforms. |
| Software-Defined Vehicle Investment | Aligns logic IC roadmaps with OEM requirements for deterministic real-time processing in sensor fusion systems. |
| Geographic Manufacturing Footprint | Localizes packaging and test capacity under India's PLI scheme to diversify beyond East Asian supply concentration. |
| Charging Infrastructure Partnership | Extends power IC design-in activity into DC-DC converter applications for high-voltage charging systems. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply estimates. Primary interviews engaged Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, foundry operations managers, and semiconductor reliability specialists. Secondary validation drew from vehicle production databases, AEC-Q100 qualification registries, customs trade records, and SEC semiconductor filings. Bottom-up segment sizing and top-down market triangulation reconciled volume and value outputs.
Historical reference periods anchored the forecast window through production-weighted indexing across vehicle platforms and electrification architectures. Segmentation dimensions modeled include product type, application safety tier, technology node, and end-user channel. CAGRs derived from regression analysis against vehicle semiconductor content trajectories and foundry capacity expansion schedules. Forecast inputs incorporated EU Green Deal emission mandates, MIIT domestic substitution targets, and NHTSA safety regulation timelines.
Caveats apply where U.S. Department of Commerce export control expansion, MIIT capacity buildout acceleration, or ISO 26262 protocol revisions could materially shift the outlook. Forecasts reflect assumptions about foundry utilization stability and Tier-1 supplier consolidation patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Isolated Interface Chip Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Standard Logic IC Market
IC (Integrated Circuits)
Global Special Purpose Logic IC Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Lithium Battery Charger Ics Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Automotive Integrated Circuit (Ics) Market
IC (Integrated Circuits)
GNSS IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
South Korea Integrated Circuits Market
IC (Integrated Circuits)
Li-Ion Battery Protection Ics Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market