
 Lithium Battery Charger Ics Market | 2026-2036
Lithium Battery Charger Ics Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery Charger Ics Market Outlook
The EU Battery Regulation is broadening design requirements for charger ICs deployed in European-bound battery packs. Texas Instruments leverages its analog portfolio depth to sustain design wins across automotive qualification tiers. Analog Devices anchors its position through precision voltage-reference technology that meets AEC-Q100 stress tests. STMicroelectronics competes by integrating protection logic and power-path management into single-die solutions that reduce BOM counts for tier-one module suppliers.
Lithium battery charger ICs are mixed-signal power management devices that regulate charge current and voltage profiles through constant-current and constant-voltage phases, with switching frequencies typically ranging from hundreds of kilohertz to several megahertz to optimize efficiency across load conditions. These devices protect cells from overvoltage, thermal runaway, and excessive charge rates in applications from smartphones to grid-scale storage. Switching chargers capture the dominant share of value owing to their efficiency advantages in high-current electric vehicle and industrial deployments, while wireless chargers represent the fastest-expanding category as Qi2 and proprietary magnetic-alignment protocols penetrate consumer electronics and automotive cabins. Integrated chargers that combine power conversion with battery-management communication stack are consolidating margin pools as OEMs seek to reduce vendor counts and simplify supply chains.
FCC certification requirements in the US govern electromagnetic emissions from switching topologies, while the EU AI Act and CE marking frameworks extend conformity obligations to charger ICs embedded in smart energy systems. China's MIIT enforces GB standards that mandate temperature sensing accuracy and fail-safe behavior in public charging infrastructure. Stakeholders must monitor how regional safety thresholds diverge and decide whether to qualify unified silicon platforms or develop geography-specific variants.
Market Dynamics
Switching charger ICs face mounting specification pressure as electric vehicle battery packs exceed 100 kWh and cell chemistries diversify toward silicon-anode and solid-state architectures. Tier-one module suppliers now demand single-die integration of power-path management, protection logic, and battery-management communication to compress bill-of-material counts and simplify qualification cycles.
Growth Catalysts
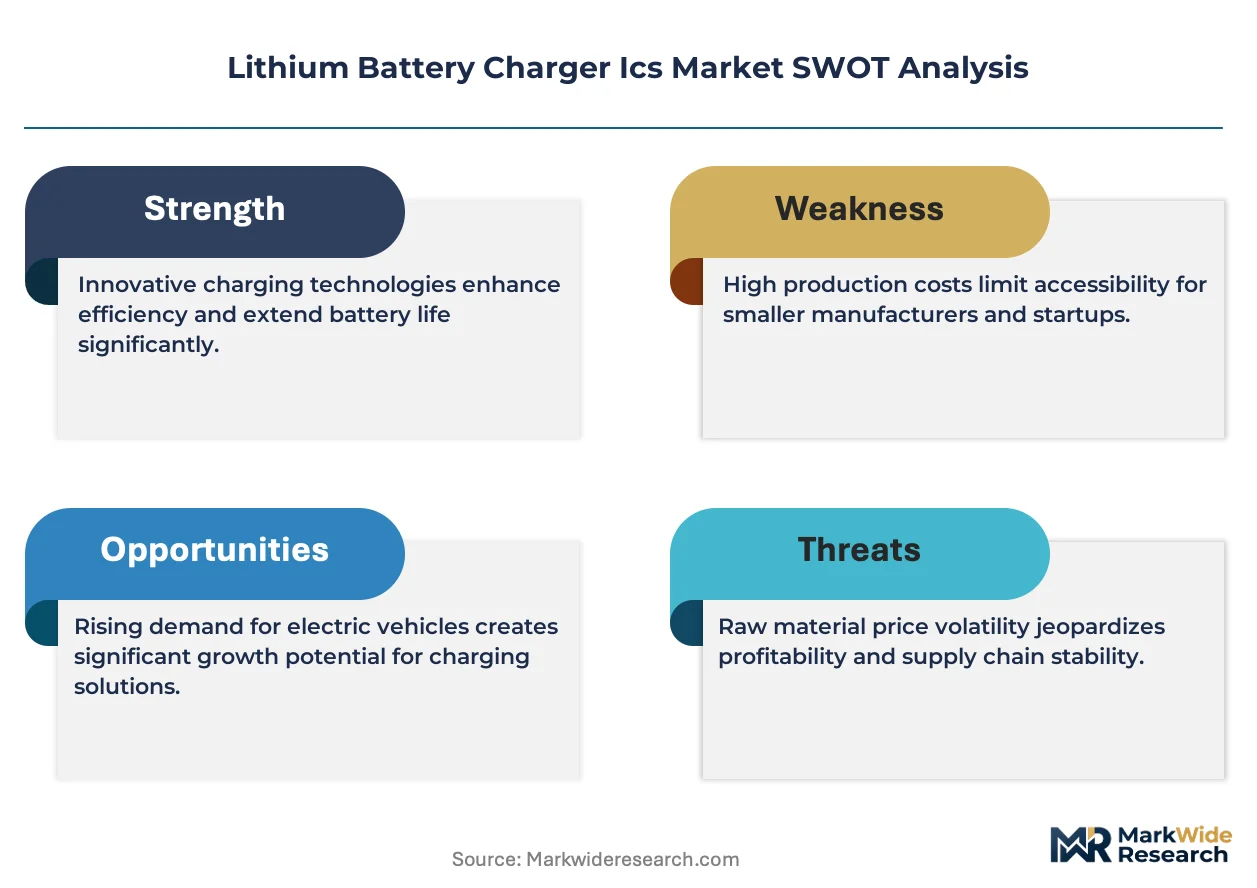
- EU Battery Regulation:Cell-level safety mandates cascading into charger IC design requirements are forcing European-bound pack producers to upgrade switching architectures and thermal sensing precision.
- Guangdong cluster concentration:Pack assembly lines clustering near Shenzhen are pulling local demand for high-current switching chargers with integrated power-path control.
- Qi2 magnetic-alignment protocols:Wireless charging penetration into automotive cabins and consumer electronics is expanding addressable silicon content per vehicle and per household.
Market Restraints
- Silicon carbide substrate costs:Wide-bandgap material price volatility constrains margin expansion for high-frequency switching topologies targeting 800V EV architectures.
- Foundry concentration in Taiwan:Advanced BCD process capacity bottlenecks at TSMC and UMC limit supply elasticity for automotive-qualified charger ICs during demand surges.
- EMI suppression complexity:FCC certification requirements for switching frequencies above 2 MHz extend development timelines and raise non-recurring engineering costs for multi-topology platforms.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Cell manufacturing incentives are attracting pack assembly investment to Gujarat and Tamil Nadu, creating fresh demand for switching chargers with BIS certification.
- Grid-scale storage integration:Utility-scale battery deployments require charger ICs with multi-cell balancing communication stacks, opening margin pools beyond automotive.
- GaN-Si hybrid topologies:Convergence of gallium nitride power stages with silicon control logic enables efficiency gains in 3kW+ industrial chargers without full process migration costs.
Industry Challenges
- Automotive functional safety certification:ISO 26262 ASIL-B qualification for charger ICs demands specialized failure-mode analysis talent scarce outside Tier-1 semiconductor vendors.
- Legacy 12V system coexistence:48V mild-hybrid architectures require bidirectional charger ICs capable of seamless voltage-domain translation, complicating validation matrices.
- Supply chain reconfiguration:Geopolitical friction is forcing dual-qualification of silicon platforms across China GB standards and AEC-Q100, duplicating non-recurring engineering spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery Charger Ics Market |
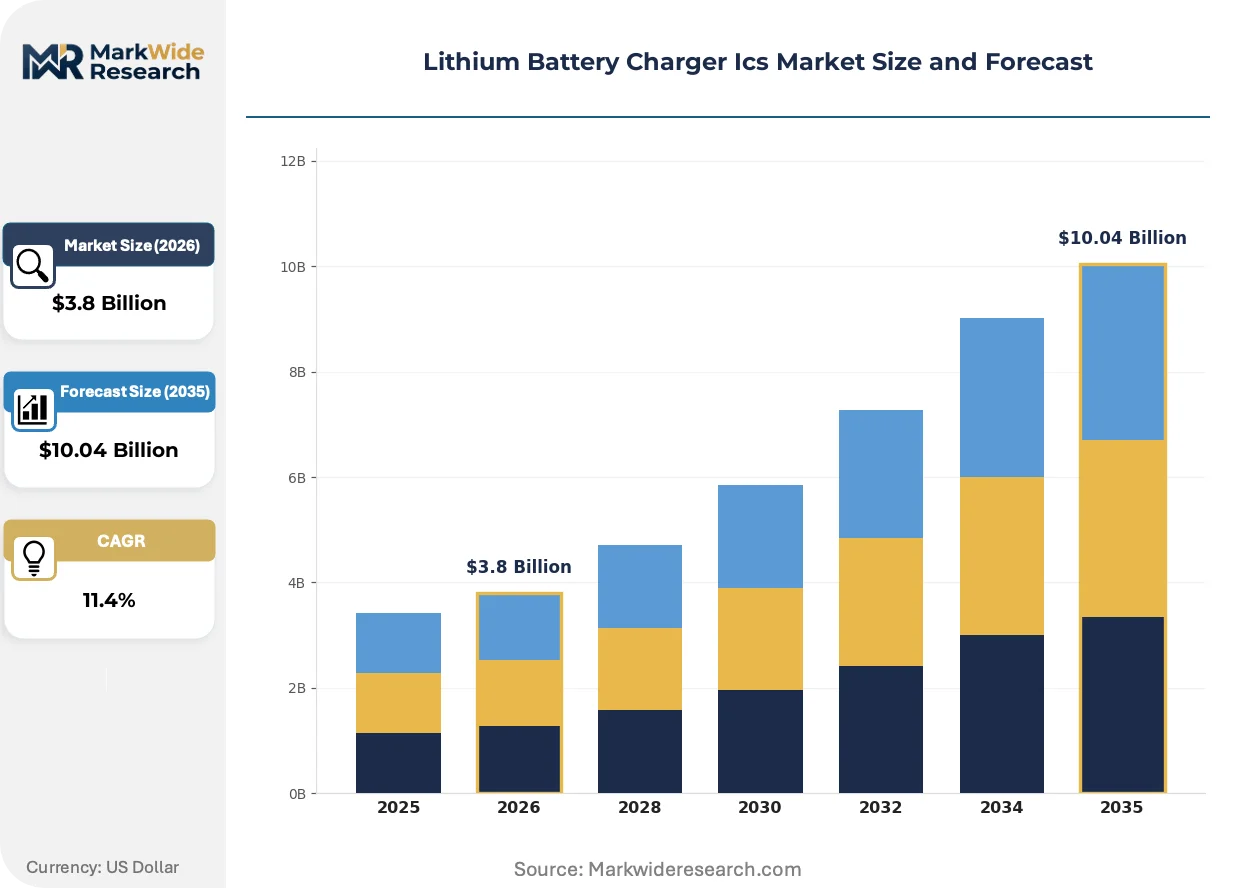
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Chargers, Switching Chargers, Wireless Chargers, Integrated Chargers Technology: Constant Current, Constant Voltage, Pulse Charging, Quick Charge End User: Consumer Electronics, Electric Vehicles, Industrial Equipment, Renewable Energy Installation: On-board Chargers, Off-board Chargers, Portable Solutions, Embedded Systems |
| Companies Covered | Texas Instruments, Analog Devices, STMicroelectronics, Microchip Technology, ON Semiconductor, ROHM, NXP Semiconductors, Renesas Electronics, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery Charger Ics Market Strategic Shifts
Distributed power architectures and protocol convergence are compressing traditional tiering between consumer, industrial, and automotive charger IC specifications. Integration depth now determines competitive position more than switching frequency or efficiency benchmarks alone.
GaN-on-silicon power stages are decentralizing thermal management requirements in high-density charger designs. Automotive cabin wireless charging suppliers are adopting these devices to eliminate heatsink volume beneath center consoles. This topology shift is enabling placement flexibility previously impossible with silicon MOSFET-based solutions.
China's MIIT enforcement of GB/T 18487.1 temperature sensing accuracy mandates is tightening fail-safe behavior requirements for public infrastructure charger ICs. Domestic pack assemblers must now source ICs with redundant thermal monitoring and hardware-imposed charge termination. European suppliers qualifying for Chinese EV exports are redesigning protection logic to meet these thresholds.
Fleet operators and energy storage developers are consolidating vendor relationships around integrated charger-BMS communication stacks. Direct CAN-FD and Modbus integration in charger ICs is displacing discrete microcontroller mediation in 100kWh+ industrial packs. Germany's KBA type-approval process for commercial vehicle battery systems is accelerating this preference shift among European commercial EV procurement teams.
Lithium Battery Charger Ics Market Segmentation
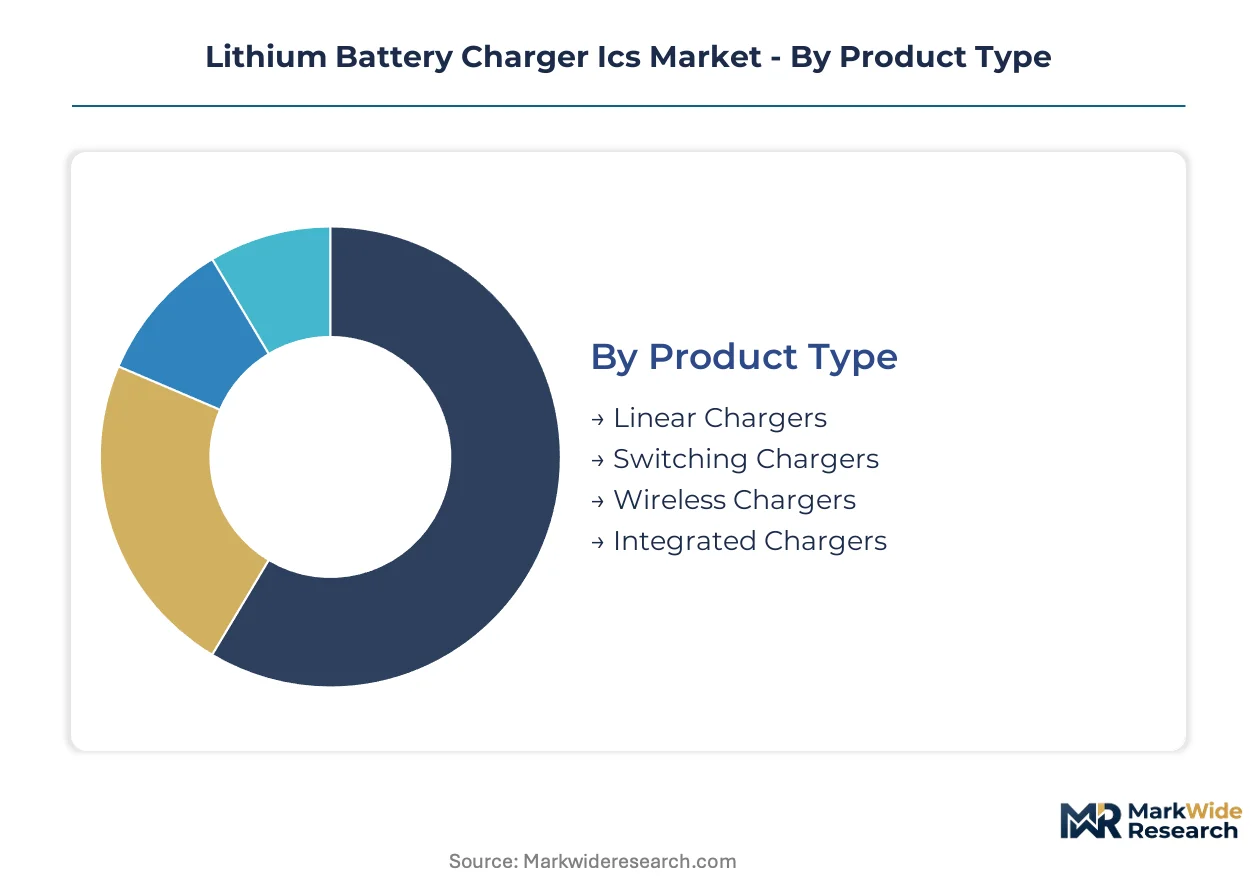
Segmentation in lithium battery charger ICs reflects diverging performance thresholds across power levels, thermal constraints, and regulatory environments. Upgrade cycles vary dramatically—from 18-month consumer refresh rates to decade-long industrial qualification timelines—shaping vendor portfolio architecture and margin capture.
Product Type:
Replacement cycles in charger IC architectures accelerate as battery chemistries evolve and efficiency mandates tighten across automotive and consumer tiers.
- Switching Chargers:Buck-boost topologies with synchronous rectification achieve efficiencies above 94% in high-current EV and industrial deployments. Electric vehicle manufacturers in China's Guangdong province are scaling procurement of 800V-capable switching architectures as pack capacities exceed 100 kWh.
- Wireless Chargers:Magnetic-resonant and inductive pads operating at 110-205 kHz eliminate connector wear in automotive cabins and sealed industrial environments. Qi2 protocol adoption in European and North American vehicle interiors is expanding silicon content per vehicle by integrating multi-coil alignment systems.
- Linear Chargers:Low-dropout architectures dominate sub-1A consumer applications where cost minimization outweighs thermal efficiency penalties.
- Integrated Chargers:Single-die solutions combining power-path management, protection logic, and battery-management communication reduce BOM counts for tier-one module suppliers.
Switching chargers sit at the top of the volume ranking, with wireless chargers climbing the fastest.
Technology:
Cost tier differentiation in charging protocols separates premium precision architectures from economy implementations with relaxed voltage tolerance.
- Constant Voltage:Precision voltage-reference circuits terminate charge at 4.2V ±0.5% for cobalt-oxide cells, with Analog Devices and Texas Instruments competing on AEC-Q100 qualification depth.
- Quick Charge:Adaptive voltage scaling from 5V to 20V enables 100W+ delivery in consumer and automotive USB-PD implementations.
- Constant Current:Current-mode control loops regulate charge rate during bulk phase, prevalent in industrial forklift and grid-storage applications.
- Pulse Charging:Intermittent current injection reduces lithium plating in silicon-anode cells, emerging in next-generation EV architectures.
Constant voltage dominates installed base, while quick charge gains share fastest in premium consumer and automotive USB-PD sockets.
End User:
Application-driven specification divergence forces vendors to maintain parallel qualification tracks across consumer, automotive, and industrial stress-test regimes.
- Electric Vehicles:On-board chargers require ISO 26262 ASIL-B functional safety, 800V bus compatibility, and GB/T 18487.1 temperature sensing accuracy for Chinese market access. Germany's KBA type-approval process accelerates preference for integrated charger-BMS communication stacks in commercial vehicle procurement.
- Consumer Electronics:Smartphones, tablets, and wearables drive volume through 18-month design cycles with aggressive cost-down targets and Qi wireless integration.
- Industrial Equipment:Forklifts, medical devices, and robotics demand 10-year availability guarantees and extended temperature ranges.
- Renewable Energy:Grid-scale storage deployments require multi-cell balancing communication and Modbus/CAN-FD integration for utility SCADA compatibility.
Electric vehicles command the highest ASP tier, with renewable energy climbing fastest as utility-scale deployments expand.
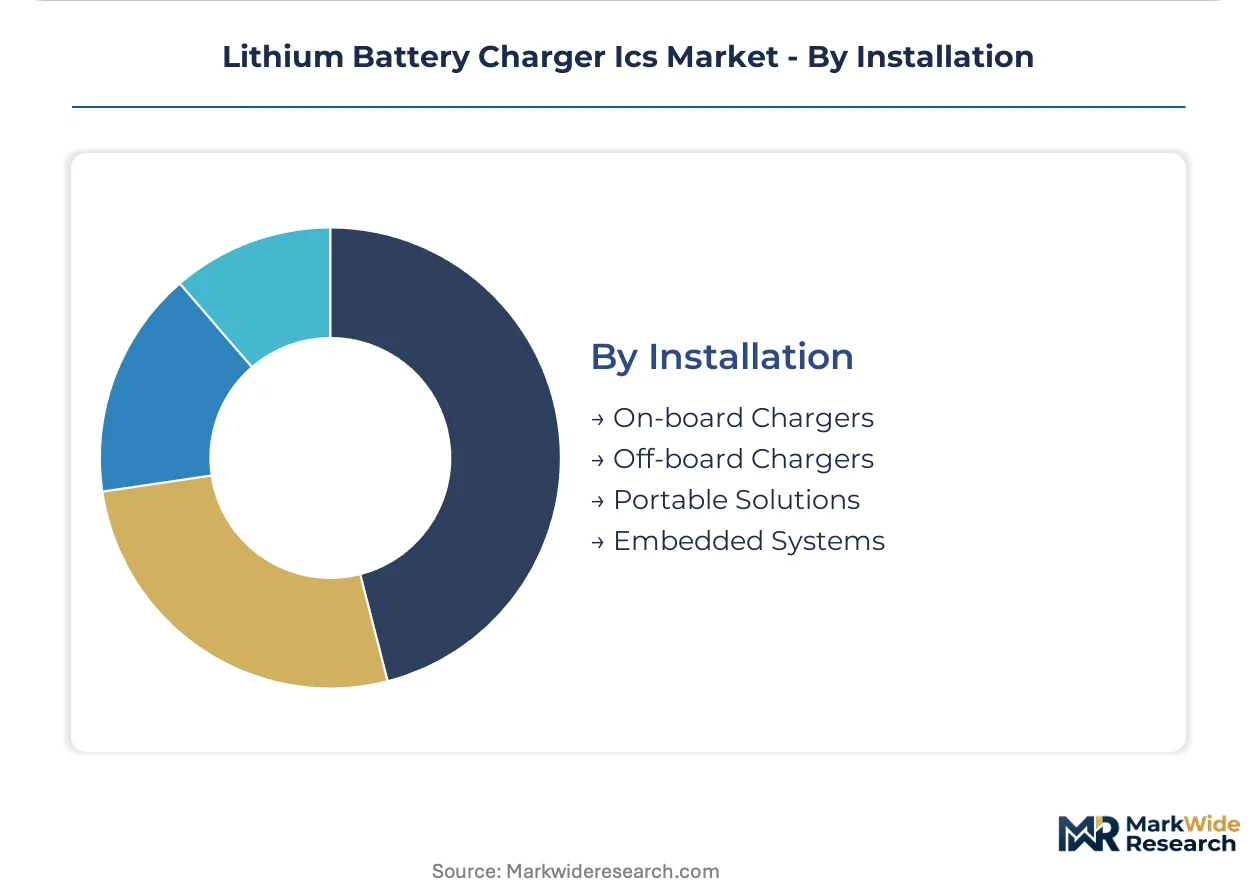
Installation:
Customer type segmentation separates OEM-integrated designs from aftermarket and portable configurations with distinct margin and support requirements.
- On-board Chargers:Permanently installed AC-DC conversion in EV powertrains must survive vibration, thermal cycling, and 15-year service life. FCC Part 15 emissions compliance and EU EMC directives govern switching frequency selection and EMI suppression design.
- Embedded Systems:Charger ICs integrated into battery pack modules with direct BMS communication are displacing discrete microcontroller mediation in 100kWh+ industrial packs.
- Off-board Chargers:Standalone DC fast-charging stations require liquid-cooled power stages and GB standard compliance for Chinese public infrastructure deployment.
- Portable Solutions:Power banks and mobile charging accessories prioritize power density and universal protocol support over thermal performance.
On-board chargers lead by revenue concentration, with embedded systems expanding most quickly through pack-level integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics engineering talent clusters in Shenzhen, Dallas, and Munich anchor regional design capabilities for lithium battery charger ICs. Foundry proximity and pack assembly concentration determine procurement patterns across major manufacturing geographies.
United States
Automotive OEMs in Detroit and Silicon Valley drive demand for ISO 26262-qualified switching architectures. FCC Part 15 emissions compliance governs switching frequency selection for on-board chargers. Texas instruments design centers in Dallas-Fort Worth anchor analog portfolio development for AEC-Q100 qualification tiers.
China
MIIT enforcement of GB/T 18487.1 temperature sensing accuracy mandates is tightening fail-safe requirements for public infrastructure deployment. Dual carbon goals accelerate 800V EV architecture adoption. Pack assembly lines cluster in Guangdong province near Shenzhen, pulling local demand for high-current switching chargers with integrated power-path control.
Germany
Commercial vehicle procurement teams prioritize integrated charger-BMS communication stacks under KBA type-approval processes. EU Battery Regulation cell-level safety mandates cascade into charger IC design requirements. Bavaria-based automotive suppliers qualify silicon platforms for both AEC-Q100 and emerging GB standards.
Japan
METI industrial policy supports precision voltage-reference technology development for silicon-anode cell architectures. JIS standards govern thermal sensing accuracy in industrial forklift applications. Kansai region manufacturers supply 10-year availability guarantees for medical device and robotics deployments.
South Korea
Battery cell producers in Gyeonggi-do province scale procurement of pulse charging architectures for next-generation silicon-anode cells. MFDS medical device regulations extend to charger ICs in healthcare equipment. Seoul Capital Area fabless designers specialize in Qi2 magnetic-alignment protocols for automotive cabin integration.
Lithium Battery Charger Ics Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the lithium battery charger IC landscape. IDM vendors with captive BCD process capacity face fabless challengers leveraging TSMC and UMC foundry partnerships. Three archetypes dominate: analog portfolio generalists, automotive qualification specialists, and wireless charging protocol innovators. Competitive moves center on single-die integration to compress BOM counts and dual-qualification strategies spanning China GB standards and AEC-Q100 automotive tiers.
Among analog portfolio generalists, Texas Instruments and Analog Devices occupy positions sustained by voltage-reference precision and qualification depth. STMicroelectronics exemplifies the integration-focused archetype, anchoring European supply relationships through protection logic consolidation. These three companies represent distinct competitive vectors—portfolio breadth, precision technology, and system integration—rather than overlapping positioning.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| STMicroelectronics |
| Microchip Technology |
| ON Semiconductor |
| ROHM |
| NXP Semiconductors |
| Renesas Electronics |
| Vishay Intertechnology |
| Others |
Value Chain & Pricing Dynamics
EU Battery Regulation mandates for cell-level safety are forcing tier-one module suppliers to absorb qualification cost premiums for AEC-Q100 and GB dual-certified silicon, compressing margin pools for unbundled component vendors while rewarding integrated solution providers with pricing power.
Pricing Analysis
Bundled single-die solutions command premium positioning against unbundled discrete alternatives. Pricing stratifies across automotive-grade, industrial-grade, and consumer-grade certification tiers, with ISO 26262 ASIL-B qualification adding substantial margin capture. Cost compression in consumer linear chargers is intensifying because foundry capacity competition from automotive orders squeezes allocation. Fleet procurement teams show highest price sensitivity, while medical device OEMs accept premium positioning for 10-year availability guarantees.
Supply Chain Analysis
Power electronics engineering talent scarcity in Taiwan, South Korea, and Japan constrains BCD process development velocity. Advanced wafer supply draws from TSMC and UMC foundries, with silicon carbide substrates feeding from Cree/Wolfspeed and II-VI channels. Single-source vulnerability concentrates at advanced node capacity for automotive-qualified devices. Distribution runs through tier-one module suppliers and direct OEM qualification programs rather than broad-line distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Battery Regulation cell-level mandates and China's GB/T 18487.1 temperature sensing requirements are accelerating demand for dual-qualified silicon platforms.
For Market Incumbents: To counter fabless challengers leveraging TSMC partnerships, Texas Instruments and Analog Devices should deepen captive BCD capacity investments and accelerate single-die integration roadmaps. Securing automotive qualification depth ahead of ISO 26262 ASIL-B tier expansions protects margin tiers against modular competition from STMicroelectronics. For New Entrants and Emerging Players: Enter via India's PLI scheme for ACC batteries, where Gujarat and Tamil Nadu pack assembly investments create fresh demand for BIS-certified switching chargers without entrenched incumbent relationships. Target grid-scale storage integration opportunities requiring multi-cell balancing communication stacks, using Modbus/CAN-FD protocol expertise as the go-to-market wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with GaN-Si hybrid topology specialists who can capture 3kW+ industrial charger efficiency gains without full process migration costs. Five-to-ten year viability favors asset-light designers with proven foundry partnerships over capital-heavy IDMs facing capacity constraint risks. Monitor silicon-anode cell chemistry adoption curves as the inflection signal for pulse charging architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Die Integration Roadmap | Reduces BOM counts for tier-one module suppliers qualifying under EU Battery Regulation mandates. |
| Dual-Certification Investment | Enables simultaneous AEC-Q100 and GB standard qualification for China EV export markets. |
| GaN-Si Hybrid Topology Development | Captures efficiency gains in 800V architectures without silicon carbide substrate cost exposure. |
| India Manufacturing Footprint | Positions for PLI scheme incentives as ACC battery cell production concentrates in Gujarat. |
| Wireless Charging Protocol Licensing | Monetizes Qi2 magnetic-alignment IP as automotive cabin integration accelerates in Europe. |
Study Parameters
Direct dialogue with semiconductor procurement managers at tier-one automotive module suppliers, power electronics design engineers at EV OEMs, and foundry account executives anchored qualitative assessment. Secondary validation drew from MIIT GB standard filings, EU Battery Regulation implementation guidance, SEC 10-K disclosures from analog semiconductor vendors, and IHS Markit vehicle production databases. Bottom-up demand modeling triangulated against top-down semiconductor consumption estimates.
Segment-level outputs across the projection horizon reflect product type, end-user application, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted penetration curves for switching versus linear architectures, with EV battery capacity trajectories and wireless charging protocol adoption rates serving as primary forecast inputs.
The model holds under stable foundry capacity allocation and gradual regulatory harmonization; deviation in Taiwan geopolitical friction or abrupt GB standard tightening would shift qualification timelines and margin structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Computer and Peripherals Special Purpose Logic Ic Market
IC (Integrated Circuits)
Global Application Specific Consumer Analog Integrated Circuit Market
IC (Integrated Circuits)
Energy Metering IC Chip Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
CMOS Power Amplifier Market
IC (Integrated Circuits)
China Integrated Circuit (IC) Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Comparator IC Market
IC (Integrated Circuits)
Readout Integrated Circuits (ROIC) Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
South Korea Integrated Circuits Market
IC (Integrated Circuits)
Display LSI IC Market
IC (Integrated Circuits)
Global Application Specific Computer Analog IC Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market