
 3D Electronics Market | 2026-2036
3D Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
3D Electronics Market Outlook
The 3D electronics sector is pivoting on a widening gap between aerospace-grade printed circuit systems and commodity consumer antenna products. Nano Dimension Ltd. leverages proprietary dragonfly systems to dominate high-mix, low-volume defense and satellite prototyping. HP Inc. anchors industrial-scale polymer electronics through its Multi Jet Fusion platform, targeting production-grade sensor housings. Optomec Inc. specializes in aerosol jet deposition for conformal electronics on curved automotive surfaces, sustaining technology leadership in geometrically complex applications.
3D electronics encompasses additive manufacturing processes that deposit conductive, dielectric, and semiconductive materials onto three-dimensional substrates to create functional electronic devices without traditional planar PCB constraints. These systems typically operate with trace resolutions below 50 micrometers using silver nanoparticle inks or conductive polymers cured through photonic or thermal sintering, serving applications where miniaturization, weight reduction, or non-planar form factors prove essential. Antenna segments lead current revenue generation as 5G infrastructure and automotive radar demand conformal, frequency-optimized geometries that subtractive methods cannot produce. Medical device applications represent the fastest-expanding opportunity as FDA scrutiny of implantable electronics intensifies demand for biocompatible, patient-specific printed sensors. Inkjet printing technology occupies the deepest margin pools due to material efficiency and digital tooling advantages at production scale.
EPA regulations governing volatile organic compound emissions from solvent-based conductive inks constrain formulation choices for manufacturers serving North American automotive and aerospace clients. REACH restrictions on cadmium and lead content in electronic materials force European producers toward silver and copper nanoparticle alternatives, elevating raw material costs while improving recyclability profiles. FDA quality system regulations and ISO 13485 standards shape verification protocols for printed medical electronics, extending development timelines but creating compliance moats for qualified suppliers. Stakeholders must monitor convergence between semiconductor packaging roadmaps and additive electronics capabilities to anticipate where printed 3D circuitry displaces conventional interconnection technologies.
Market Dynamics
The 3D electronics sector pivots on automotive electrification mandating conformal antenna geometries that subtractive manufacturing cannot deliver, forcing tier-one suppliers to retool for non-planar circuit integration.
Growth Catalysts
- Automotive Radar Integration:Electric vehicle platforms in Germany and China require frequency-optimized 3D-printed antenna arrays for advanced driver-assistance systems, pulling capital into aerosol jet deposition capacity.
- REACH Material Substitution:ECHA restrictions on cadmium and lead in conductive formulations accelerate silver nanoparticle ink adoption across European medical device prototyping clusters.
- Photonic Sintering:Thermal processing bottlenecks are dissolving as inline UV-cure systems reduce conductive trace curing from hours to seconds, enabling production-scale throughput for sensor housings.
Market Restraints
- Silver Price Volatility:Conductive ink formulations remain hostage to London Metal Exchange silver pricing, compressing margins for deposition service providers when spot markets spike.
- German Equipment Concentration:Precision motion systems for micro-dispensing heads source predominantly from Baden-Württemberg machine shops, creating single-region vulnerability for global supply chains.
- Trace Resolution Ceilings:Aerosol jet deposition struggles to achieve sub-20-micrometer features required for next-generation millimeter-wave antenna feeds, capping performance in 5G infrastructure applications.
Strategic Opportunities
- India Medical Electronics:CDSCO fast-track pathways for implantable printed sensors remain underexploited by foreign deposition equipment vendors despite domestic hospital procurement expansion.
- AI-Driven Topology Optimization:Convergence between generative design software and multi-material printing is unlocking antenna geometries impossible to conceive through manual CAD workflows.
- Japan METI Carbon Neutrality:Subsidies for low-temperature curing processes favor photonic sintering over thermal ovens, tilting equipment procurement toward UV-based deposition lines in precision manufacturing hubs.
Industry Challenges
- Multi-Physics Simulation Talent:Electromagnetic-thermal-mechanical co-design for conformal electronics requires skill sets scarce outside aerospace defense clusters in Massachusetts and Bavaria.
- FDA 510(k) Pathway Compression:Printed medical electronics face extended verification timelines as FDA quality system regulations struggle to accommodate patient-specific device geometries without batch-level equivalence.
- Legacy PCB Integration:Hybrid assemblies combining additive 3D traces with traditional planar substrates demand rework protocols that most contract manufacturers have not standardized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Electronics Market |
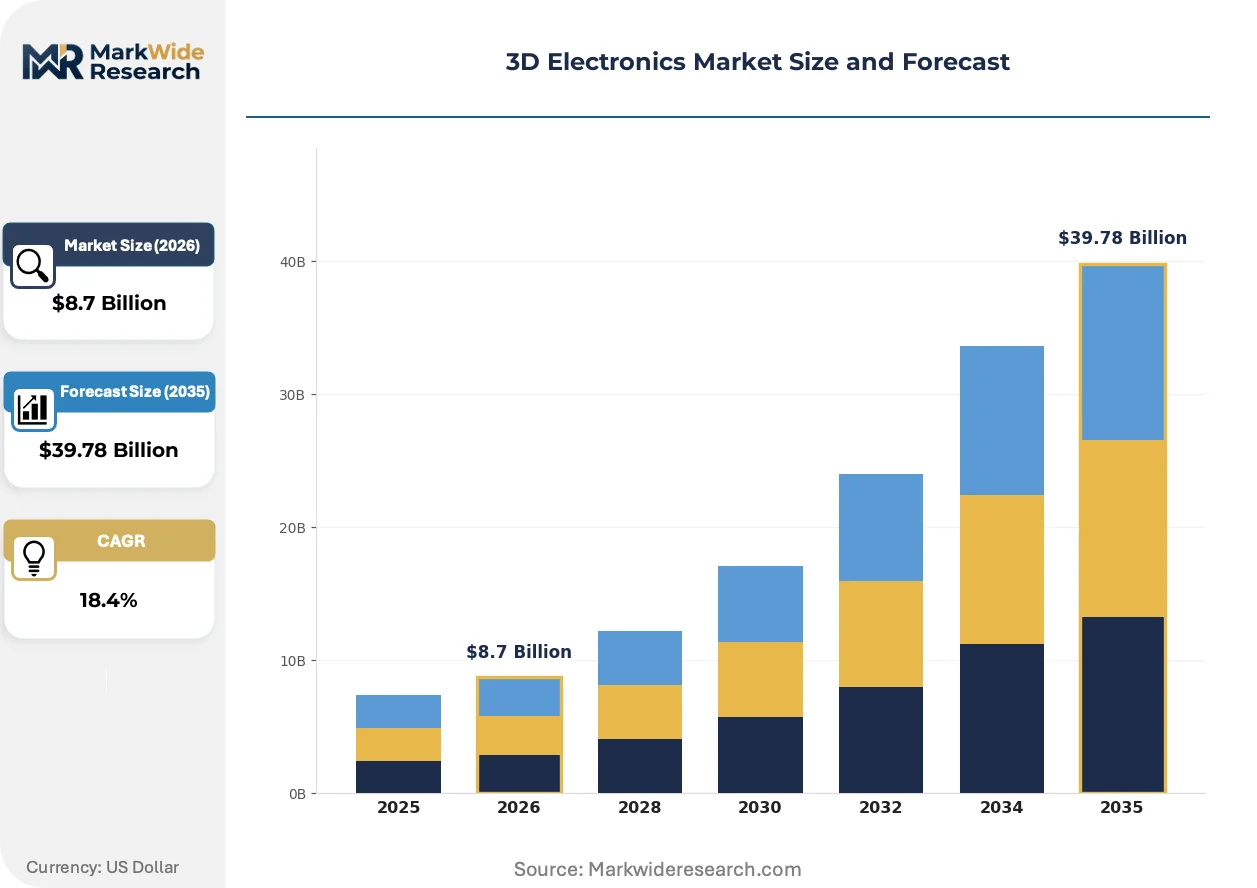
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Printed Circuits, LED Displays, Sensors, Antennas Technology: Laser Printing, Inkjet Printing, Stereolithography, Fused Deposition Modeling Application: Consumer Electronics, Aerospace, Automotive, Medical Devices End User: Manufacturers, Researchers, Designers, Hobbyists |
| Companies Covered | Nano Dimension Ltd., Optomec Inc., nScrypt Inc., Stratasys Ltd., 3D Systems, Inc., DuPont de Nemours, Inc., HP Inc., Henkel AG & Co. KGaA, Molex LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Electronics Market Strategic Shifts
Process automation and regulatory material bans are converging to restructure how conductive geometries migrate from prototype labs to certified production environments.
Multi-material inkjet systems are automating the deposition of alternating conductive and dielectric layers within single build cycles, eliminating manual assembly steps for complex sensor packages. Automotive tier-one suppliers in Stuttgart and Detroit are piloting these lines for radar dome production, compressing tooling lead times from months to days while maintaining trace impedance tolerances.
EPA volatile organic compound emission limits are constraining solvent-based conductive ink formulations across North American automotive supply chains, forcing reformulation toward water-based silver dispersions. This regulatory pressure elevates capital requirements for drying equipment but opens qualification pathways for suppliers meeting California Air Resources Board thresholds.
Hospital procurement committees are consolidating vendor lists around FDA-registered deposition houses capable of ISO 13485 traceability, displacing fragmented job-shop relationships. This concentration is most visible in Minnesota and Massachusetts medical device corridors, where original equipment manufacturers now mandate validated process parameters over unit-cost bidding.
3D Electronics Market Segmentation
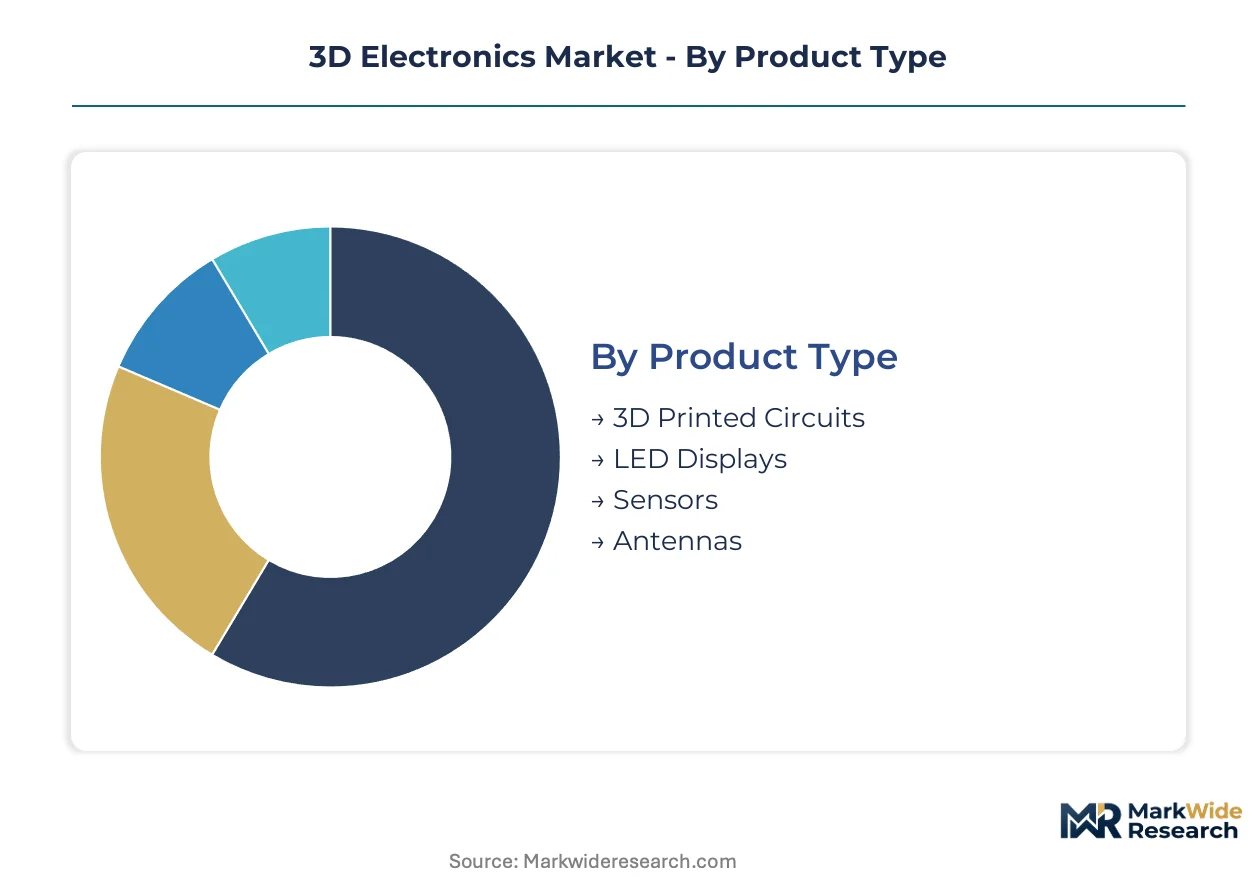
3D electronics segmentation reveals how additive manufacturing capabilities fragment across precision thresholds and volume scales. Product architecture, deposition technology, and end-use certification requirements each create distinct competitive arenas with divergent margin profiles.
Product Type:
Customization intensity spans from patient-specific medical sensors to mass-produced automotive antenna arrays, with standardization economics governing capital allocation.
- 3D Printed Circuits:Multi-layer conductive traces deposited on non-planar substrates eliminate traditional PCB lamination steps. Demand concentrates in Bavaria and Massachusetts defense clusters where conformal interconnections reduce satellite payload mass.
- Antennas:Frequency-optimized geometries with sub-millimeter feature resolution enable 5G and automotive radar applications impossible through subtractive methods. Stuttgart automotive suppliers and Shenzhen telecom infrastructure deployers drive capacity expansion for conformal radar domes.
- Sensors:Biocompatible printed electrodes for continuous glucose monitoring and neural interfaces.
- LED Displays:Flexible, curved illumination panels for automotive interior and wearable applications.
Most installed capacity flows through Antennas. Expansion is steepest in Sensors.
Technology:
Cost tiers separate photonic-cure precision systems from thermal-process commodity deposition, with equipment price points spanning two orders of magnitude.
- Inkjet Printing:Piezoelectric drop-on-demand deposition achieves sub-50-micrometer trace resolution with material efficiency exceeding 95 percent. Production-scale sensor housing lines in Detroit and Toyota City favor this modality for multi-material build cycles.
- Aerosol Jet Deposition:Atomized nanoparticle streams conform to curved automotive and aerospace surfaces with 3D trace capabilities. BMW and Lockheed Martin prototyping centers in Munich and Palo Alto anchor demand for geometrically complex antenna feeds.
- Laser Printing:Direct-write selective laser sintering of conductive powders for rigid structural electronics.
- Stereolithography:Photopolymer resin curing combined with conductive ink backfilling for high-density interconnect prototypes.
- Fused Deposition Modeling:Extrusion-based polymer deposition with integrated conductive filament for low-cost functional prototyping.
Volume throughput concentrates in Inkjet Printing. Technology development investment flows most heavily toward Aerosol Jet Deposition.
Application:
Customer type stratification separates FDA-regulated medical device development from unregulated consumer prototyping, with certification timelines driving margin differentiation.
- Automotive:Electric vehicle architectures mandate conformal antenna and sensor assemblies for ADAS and V2X communication. German tier-one suppliers in Baden-Württemberg and Chinese EV manufacturers in Shanghai pull capacity for radar-integrated bumper modules.
- Medical Devices:Implantable and wearable printed electronics face FDA 510(k) and ISO 13485 quality system requirements. Minnesota and Massachusetts hospital procurement corridors concentrate demand for patient-specific neural and cardiac sensors.
- Aerospace:Satellite and unmanned systems requiring weight-optimized, vibration-resistant conformal circuitry.
- Consumer Electronics:Wearable and IoT devices prioritizing form factor over performance specifications.
Revenue concentration sits with Automotive. Regulatory compliance investment is deepest in Medical Devices.
End User:
Maturity gradients separate validated production environments from experimental prototyping stages, with equipment purchasing authority distributed across organizational functions.
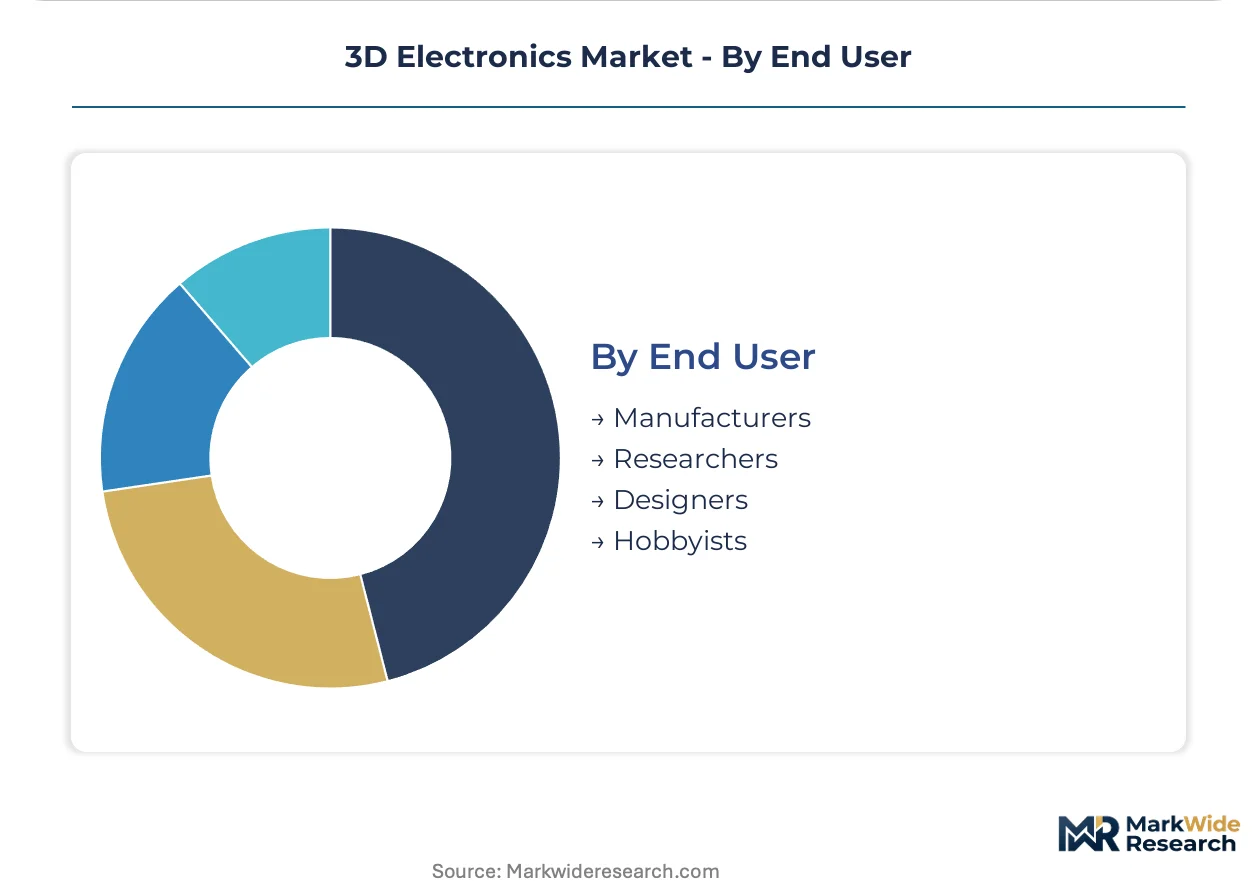
- Manufacturers:Tier-one automotive, aerospace, and medical device OEMs operating validated deposition lines with statistical process control. Production-scale procurement in Germany, Japan, and the United States dominates equipment revenue.
- Researchers:University and national laboratory facilities advancing materials science and process physics. MIT, Fraunhofer IPA, and AIST Tsukuba anchor fundamental development in conductive polymer and nanoparticle sintering.
- Designers:Product development consultancies bridging concept and manufacturing feasibility.
- Hobbyists:Desktop 3D printer owners experimenting with conductive filament extrusion.
Capital deployment flows predominantly through Manufacturers. Research publication volume is expanding fastest among Researchers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision deposition equipment manufacturing while the United States dominates defense and medical prototyping demand, creating divergent regional specialization patterns across the 3D electronics value chain.
United States
Defense satellite programs and FDA-regulated medical device corridors in Massachusetts and Minnesota drive conformal circuit demand. EPA volatile organic compound limits constrain solvent-based ink formulations, forcing water-based silver dispersion adoption. Palo Alto and Boston anchor aerosol jet prototyping centers serving Lockheed Martin and Medtronic supply chains.
Germany
Automotive electrification mandates from Stuttgart tier-one suppliers pull capacity for radar-integrated bumper modules. REACH cadmium and lead restrictions accelerate silver nanoparticle ink substitution across Baden-Württemberg industrial clusters. Fraunhofer IPA in Stuttgart coordinates materials science research with BMW and Bosch production lines.
China
Electric vehicle manufacturers in Shanghai and Shenzhen deploy conformal antenna arrays for advanced driver-assistance systems. MIIT industrial standards shape equipment certification protocols for domestic deposition system vendors. Yangtze River Delta precision manufacturing hubs integrate imported German motion systems with local ink formulation capabilities.
Japan
Toyota City and Nagoya industrial zones favor inkjet printing for multi-material sensor housing production at automotive scale. METI carbon neutrality subsidies tilt procurement toward photonic sintering equipment over thermal ovens. AIST Tsukuba advances low-temperature curing research for flexible substrate applications.
India
Hospital procurement expansion in Delhi and Mumbai creates demand for implantable printed sensors. CDSCO fast-track pathways for medical electronics remain underexploited by foreign equipment vendors. Karnataka and Maharashtra medical device corridors concentrate domestic prototyping capacity for cardiac and neural monitoring applications.
3D Electronics Market Competitive Environment
Top-tier vendors anchor high-mix defense and satellite prototyping, while mid-scale fabricators compete on automotive sensor housing throughput. The vendor base stratifies across precision thresholds, with photonic-cure specialists commanding premium pricing against thermal-process commodity deposition. Two strategic archetypes dominate: equipment-integrated material suppliers and pure-play deposition service providers. Competitive moves concentrate on strategic partnerships for regulatory compliance certification and capacity expansion in automotive-adjacent geographies.
Within the equipment-integrated tier, Nano Dimension Ltd. and Optomec Inc. exemplify divergent specialization vectors, with the former representing high-mix defense prototyping and the latter occupying geometrically complex automotive surface applications. HP Inc. anchors industrial-scale polymer electronics production, sitting within the mass-manufacturing archetype distinct from precision-focused competitors. These three entities collectively span the technology spectrum from satellite-grade conformal circuits to production-grade sensor housings, illustrating how competitive positioning fragments across resolution and volume axes rather than consolidating around unified platforms.
| Leading Market Players |
|---|
| Nano Dimension Ltd. |
| Optomec Inc. |
| nScrypt Inc. |
| Stratasys Ltd. |
| 3D Systems, Inc. |
| DuPont de Nemours, Inc. |
| HP Inc. |
| Henkel AG & Co. KGaA |
| Molex LLC |
| Others |
Value Chain & Pricing Dynamics
EPA volatile organic compound emission limits and REACH cadmium restrictions gate qualified supply for premium-tier deposition services, reserving premium pricing access to vendors with certified water-based silver formulations and photonic sintering infrastructure. Buyers without regulatory-compliant supply chains face exclusion from automotive and medical procurement corridors where certification premiums command substantial price advantages.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for inkjet printing systems while aerosol jet deposition retains premium positioning. Three-tier pricing structure across precision defense prototyping, validated automotive production, and commodity sensor housings differentiates based on trace resolution and FDA/ISO certification status. Cost compression in standard-tier sensor housings intensifies because Chinese equipment vendors are expanding photonic-cure capacity. Automotive tier-one suppliers exhibit highest price sensitivity; satellite defense contractors demonstrate lowest sensitivity due to mission-critical performance requirements.
Supply Chain Analysis
Single-source vulnerability sits with Baden-Württemberg precision motion systems for micro-dispensing heads, concentrating critical equipment manufacturing in southwestern Germany. Geographic supply concentration spans Germany, Japan, and the United States for deposition equipment; silver nanoparticle inks draw from South Korean and Japanese chemical processors. Raw material dependencies center on London Metal Exchange silver pricing, photonic-cure polymer resins, and piezoelectric printhead ceramics. Tariff exposure on German motion systems threatens North American capacity expansion timelines. Distribution runs through validated production houses in Stuttgart, Detroit, and Toyota City rather than fragmented job-shop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through photonic sintering cost-down curves and regulatory compliance premiums that concentrate procurement among qualified vendors. Water-based ink formulation transitions and inline UV-cure automation are compressing production costs while elevating certification barriers.
For Market Incumbents: Hedge against silver price volatility through long-term offtake agreements with South Korean and Japanese chemical suppliers. Defensive positioning requires backward integration into photonic-cure equipment manufacturing or exclusive partnerships with Baden-Württemberg motion system shops. Capacity additions in China threaten standard-tier pricing; incumbents should deepen FDA/ISO certification moats in medical and aerospace segments where compliance timelines deter new entrants. For New Entrants and Emerging Players: The premium-to-economy price gap in aerosol jet deposition creates white-space opportunity in mid-tier automotive sensor housings. Target India's CDSCO fast-track pathways for implantable printed sensors, where foreign equipment vendors remain underexploited despite hospital procurement expansion. Position through water-based silver ink qualification to bypass EPA emission constraints that exclude solvent-based competitors from North American automotive supply chains. For Investors and Strategic Acquirers: Roll-up economics work for regional deposition service providers because FDA 510(k) verification timelines and ISO 13485 certification costs fragment the medical electronics vendor base. Five-to-ten year viability hinges on photonic sintering technology maturation and automotive electrification sustaining conformal antenna demand. Acquisition targets should demonstrate validated process parameters with statistical process control. The signal to watch is MIIT equipment certification timelines in China, which would accelerate domestic vendor consolidation and reshape import-dependent supply structures.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Sintering Equipment Deployment | Inline UV-cure systems from AIST Tsukuba research reduce curing from hours to seconds, enabling automotive-scale throughput. |
| Water-Based Silver Ink Qualification | EPA-compliant formulations open California Air Resources Board pathways while elevating capital requirements for drying infrastructure. |
| Backward Integration into Motion Systems | Captive supply of Baden-Württemberg precision dispensing heads mitigates single-region vulnerability for global deposition lines. |
| CDSCO Regulatory Pathway Investment | Fast-track certification for implantable sensors captures Delhi and Mumbai hospital procurement expansion before foreign vendor saturation. |
| Multi-Material Inkjet Automation | Alternating conductive-dielectric deposition in single build cycles eliminates manual assembly for complex radar dome packages. |
Study Parameters
Direct dialogue with deposition equipment engineers, automotive tier-one procurement directors, FDA regulatory affairs specialists, and hospital biomedical engineering committees grounded qualitative assessment. Secondary validation drew from EPA emission filing databases, ECHA REACH substance restriction updates, CDSCO medical device approval records, and SEC 10-K disclosures from listed additive manufacturing vendors. Bottom-up capacity modeling triangulated against top-down automotive electrification and satellite deployment forecasts.
Segment-level projections across the analysis window integrated product architecture precision thresholds, deposition technology cost tiers, and end-use certification requirements. The analytical framework modeled inkjet printing and aerosol jet deposition adoption curves separately, with CAGRs derived from equipment shipment data and materials consumption patterns. Industry-specific inputs included silver nanoparticle ink pricing volatility indices, photonic sintering throughput benchmarks, and automotive radar integration timelines from OEM platform disclosures.
The model assumes a particular technology adoption path; alternative pathways for laser-based selective powder sintering would alter the outlook if trace resolution thresholds advance beyond current aerosol jet ceilings. Forecasts embed assumptions regarding REACH material substitution timelines and EPA enforcement consistency that regulatory amendments could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Smart Window Market
Emerging and Next Generation Technologies
Inp Lasers Market
Emerging and Next Generation Technologies
Haptic Technology Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
Next Gen TV (ATSC TV) Market
Emerging and Next Generation Technologies
Nanoparticle Technology Market
Emerging and Next Generation Technologies
Piezoelectric Nanogenerator Market
Emerging and Next Generation Technologies
Global Next Generation Computing Market
Emerging and Next Generation Technologies
Nanodiamond Market
Emerging and Next Generation Technologies
Laser Technology Market
Emerging and Next Generation Technologies
Chipless RFID Market
Emerging and Next Generation Technologies
Metamaterial Medium Market
Emerging and Next Generation Technologies
Global 3D TSV and 2.5D Market
Emerging and Next Generation Technologies
Microfluidics Prototype Market
Emerging and Next Generation Technologies
Stretchable Electronics Market
Emerging and Next Generation Technologies
Switchable Smart Film Market