
 Global Next Generation Computing Market | 2026-2036
Global Next Generation Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Next Generation Computing Market Foresight
The EU AI Act is realigning the cost-of-entry calculus for next-generation computing vendors selling into European financial and healthcare applications. IBM Corporation leverages its quantum network partnerships to sustain early-mover positioning in regulated industries. NVIDIA Corporation anchors its growth strategy through captive supply of GPU architectures purpose-built for neuromorphic and AI training workloads.
Next generation computing encompasses heterogeneous processing architectures—quantum superconducting qubits operating at millikelvin temperatures, neuromorphic memristor crossbars, photonic interferometric meshes, and edge-optimized tensor processing units—that execute computationally intractable problems across optimization, inference, and simulation tasks. Quantum computing currently dominates capital deployment, while edge computing captures the broadest installation base as latency-sensitive AI inference migrates from centralized clouds to manufacturing floors and autonomous platforms. Optical computing represents the fastest-expanding segment for specialized matrix multiplication in data centers, though its addressable market remains narrow relative to semiconductor-based alternatives.
The FDA governs clinical validation requirements for diagnostic algorithms deployed on neuromorphic hardware in US healthcare settings, while the FCC shapes spectrum allocation that determines edge computing density in telecommunications. China's MIIT and NMPA coordinate national standards for quantum cryptography and cloud security, creating divergent compliance pathways for multinational vendors. Stakeholders must monitor how fragmented regulatory timelines across Washington, Brussels, and Beijing reshape localization requirements for both hardware fabrication and algorithm training datasets.
Market Dynamics
Quantum error correction roadmaps are compressing commercialization timelines for fault-tolerant systems, forcing neuromorphic and photonic alternatives to accelerate their own maturity curves to maintain relevance in high-performance computing procurement cycles.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making systems in European financial services must demonstrate algorithmic transparency, creating procurement pull for explainable quantum and neuromorphic architectures that natively support audit trails.
- Federal quantum computing initiatives:United States national laboratory partnerships are concentrating demand for superconducting qubit systems, with DOE and NSF funding streams directly underwriting pilot deployments in materials simulation and cryptography.
- Edge inference latency requirements:Manufacturing floors and autonomous platforms are migrating AI workloads from centralized clouds, expanding installation base for tensor processing units optimized for millisecond-response inference at the network periphery.
Market Restraints
- Dilution refrigerator supply concentration:Superconducting quantum systems depend on cryogenic infrastructure sourced from a narrow supplier base in Finland and the United States, creating single-point-of-failure risk for scaling millikelvin-qubit deployments.
- Helium-3 isotope scarcity:Quantum computing cooling systems and neutron detection applications compete for constrained global supply of this non-renewable resource, with Russian and Qatari export quotas directly constraining fabrication capacity expansion.
- FDA clinical validation timelines:Neuromorphic diagnostic hardware faces multi-year approval pathways for algorithmic medical devices, compressing addressable market for healthcare applications relative to less regulated verticals.
Strategic Opportunities
- India's semiconductor PLI scheme:Production-linked incentives for domestic chip fabrication create localization pathways for neuromorphic and photonic foundry services targeting South Asian edge computing deployments.
- Photonic-quantum hybrid architectures:Interferometric mesh processors are converging with trapped-ion systems to enable room-temperature quantum networking, opening data center interconnect applications previously reserved for cryogenic platforms.
- Japan's METI quantum cryptography roadmap:National standards for quantum-safe communications are mandating replacement timelines for financial and government infrastructure, generating replacement-cycle demand through 2030.
Industry Challenges
- Cryogenic control electronics integration:Bridging room-temperature classical systems with millikelvin qubit planes requires specialized microwave engineering talent pools concentrated at fewer than twelve global research institutions.
- Cross-border algorithm training data localization:China's NMPA and MIIT data sovereignty requirements conflict with EU GDPR research exemptions, fragmenting dataset assembly for multinational neuromorphic training workloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Next Generation Computing Market |
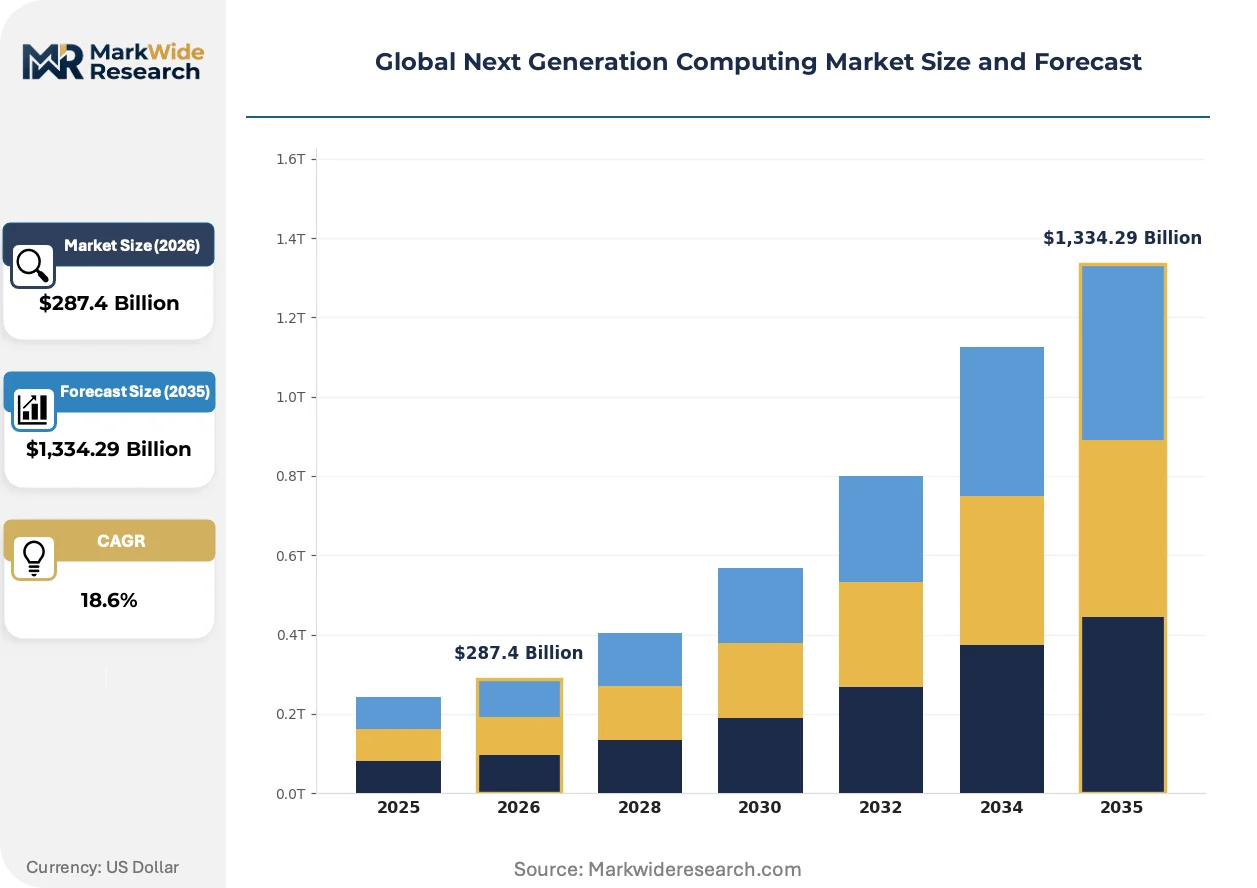
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $1,334.29 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Quantum Computing, Neuromorphic Computing, Edge Computing, Optical Computing Application: Artificial Intelligence, Machine Learning, Data Analytics, Cloud Computing End User: Healthcare, Finance, Education, Telecommunications Deployment: On-Premises, Hybrid Cloud, Public Cloud, Private Cloud |
| Companies Covered | IBM Corporation, Amazon Web Services, Inc., Intel Corporation, Microsoft Corporation, NVIDIA Corporation, Cisco Systems Inc., Alphabet Inc., Hewlett Packard Enterprise, Advanced Micro Devices, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Next Generation Computing Market Shifts & Advancements
Silicon photonics fabrication techniques are crossing over from telecommunications transceivers into matrix multiplication accelerators, reshaping how specialized computing hardware achieves economies of scale.
Photonic tensor cores are converging with CMOS foundry processes to enable wafer-scale optical processors for data center inference workloads. Amazon Web Services and Microsoft Azure procurement teams are evaluating pilot deployments for transformer model serving. This convergence is compressing cost-per-TOPS metrics for specialized AI hardware relative to electronic alternatives.
The EU AI Act's risk classification framework is forcing algorithmic transparency disclosures for high-risk automated decision systems. Financial services firms deploying quantum optimization for portfolio construction must now document model interpretability. European vendors are responding by prioritizing variational quantum eigensolver architectures over black-box quantum annealing approaches.
Defense and intelligence agencies are consolidating procurement authority for quantum key distribution hardware under national cybersecurity directorates. Traditional channel structures involving systems integrators are giving way to direct manufacturer relationships with classified program offices. This concentration is most visible in United States federal contracting, where NIST post-quantum cryptography migration timelines are accelerating budget allocation.
Global Next Generation Computing Market Segmentation
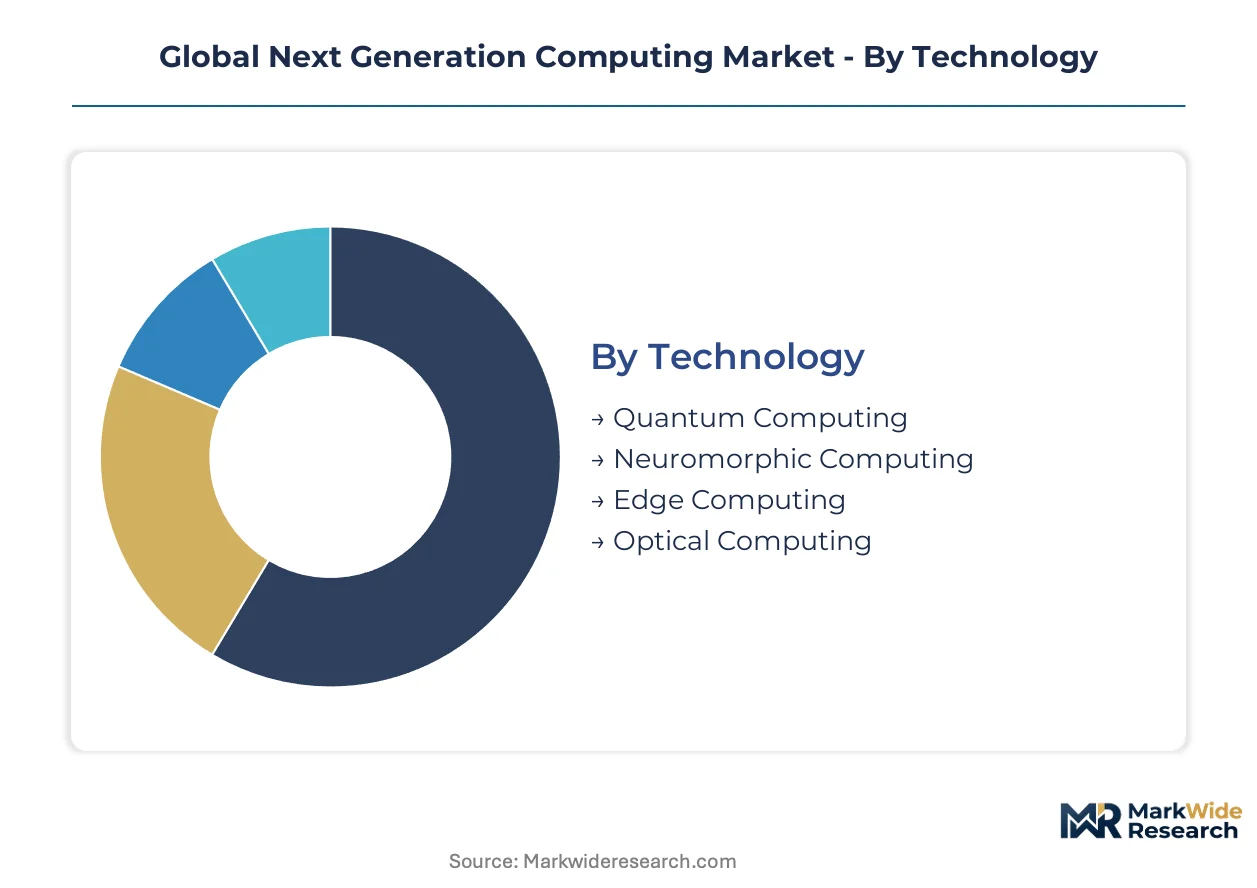
Heterogeneous processing architectures demand distinct regulatory pathways across healthcare diagnostics, financial algorithmic trading, and classified defense applications. Segmentation reveals how certification burdens concentrate in quantum and neuromorphic deployments while edge computing spreads across lighter-touch verticals.
Technology:
FDA 510(k) clearance governs neuromorphic diagnostic hardware, while FCC spectrum allocations shape edge computing density. EU AI Act risk classifications impose algorithmic transparency mandates on quantum optimization systems sold into European financial services.
- Quantum Computing:Superconducting qubit systems operating at millikelvin temperatures execute computationally intractable optimization and cryptography problems. United States national laboratory partnerships concentrate procurement through DOE and NSF funding streams for materials simulation workloads.
- Neuromorphic Computing:Memristor crossbar arrays emulate biological neural architectures for ultra-low-power inference. FDA clinical validation timelines compress healthcare addressable market relative to manufacturing quality control applications.
- Edge Computing:Tensor processing units optimized for millisecond-response inference at network peripheries.
- Optical Computing:Photonic interferometric meshes for specialized matrix multiplication in data centers.
Edge Computing sits at the top of the volume ranking, with Optical Computing climbing the fastest.
Application:
Cost tiers stratify sharply between cloud-scale training workloads requiring capital-intensive infrastructure and edge inference deployments running on commodity hardware.
- Artificial Intelligence:Transformer model training and serving drives GPU cluster procurement at hyperscale data centers. Amazon Web Services and Microsoft Azure pilot programs are evaluating photonic tensor cores for inference acceleration.
- Machine Learning:Federated learning frameworks distribute training across edge devices without centralizing sensitive data. GDPR research exemptions in Europe conflict with China's NMPA data sovereignty requirements, fragmenting multinational deployment architectures.
- Data Analytics:Portfolio optimization and risk modeling in financial services.
- Cloud Computing:Centralized quantum processing as-a-service offerings.
Artificial Intelligence commands the largest infrastructure commitment, with Machine Learning expanding most quickly at the network edge.
End User:
Customer type determines procurement authority concentration, from direct manufacturer relationships with classified program offices to fragmented hospital system purchasing committees.
- Healthcare:Diagnostic algorithms on neuromorphic hardware face multi-year FDA approval pathways. Neuromorphic edge devices for continuous patient monitoring bypass centralized cloud latency constraints in hospital networks.
- Finance:EU AI Act mandates algorithmic transparency for automated portfolio construction. Variational quantum eigensolver architectures gain preference over black-box quantum annealing for audit trail compliance.
- Education:Research cloud access for academic quantum computing experiments.
- Telecommunications:FCC spectrum allocation determines edge computing density for 5G network slicing.
Finance generates the steepest pricing premiums, with Healthcare trailing on regulatory timeline drag.
Deployment:
Supply concentration in cryogenic infrastructure and helium-3 isotope sourcing favors on-premises quantum installations over cloud alternatives for the near term.
- On-Premises:Captive superconducting quantum systems requiring dilution refrigerators sourced from Finland and United States suppliers. Helium-3 scarcity from Russian and Qatari export quotas constrains multi-tenant cloud scaling.
- Hybrid Cloud:Sensitive inference workloads processed locally with training orchestrated remotely. India's semiconductor PLI scheme creates localization pathways for hybrid edge deployments targeting South Asian manufacturing floors.
- Public Cloud:Shared quantum processing resources accessed via API.
- Private Cloud:Single-tenant dedicated infrastructure for regulated workloads.
On-Premises dominates quantum capital deployment, with Hybrid Cloud gaining share fastest as latency requirements harden at manufacturing peripheries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized microwave engineering talent pools concentrate at fewer than twelve global research institutions, anchoring quantum computing development in specific national ecosystems. This workforce distribution shapes where cryogenic control electronics integration advances fastest.
United States
DOE and NSF funding streams underwrite pilot deployments of superconducting qubit systems at national laboratories. FCC spectrum allocation decisions determine edge computing density for telecommunications infrastructure. The Boston-Cambridge corridor houses concentrated neuromorphic hardware research bridging MIT and Harvard spinouts.
China
MIIT and NMPA coordinate national standards for quantum cryptography and cloud security across state-owned enterprise procurement. The country's national technology regulator enforces data sovereignty requirements that fragment multinational training dataset assembly. Yangtze River Delta cities host photonic foundry services scaling silicon photonics fabrication.
Germany
EMA and national banking regulators scrutinize algorithmic transparency for quantum optimization in Frankfurt financial services. KBA certification requirements extend to autonomous systems using neuromorphic edge processors. Bavaria's Munich-Ingolstadt corridor concentrates automotive neuromorphic testing for manufacturing quality control.
Japan
METI quantum cryptography roadmap mandates replacement timelines for financial infrastructure through 2030. PMDA clinical validation pathways govern diagnostic algorithms on neuromorphic hardware in Osaka-Tokyo hospital networks. Kansai region photonics clusters advance interferometric mesh processors for room-temperature quantum networking.
India
BIS semiconductor standards and RBI fintech regulations shape procurement for quantum-safe banking infrastructure. The national production-linked incentive scheme creates localization pathways for neuromorphic foundry services. Karnataka's Bangalore cluster anchors edge computing deployment for South Asian manufacturing floors.
Global Next Generation Computing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across heterogeneous processing architectures. The vendor base stratifies into three tiers: hyperscale cloud operators captive-owning infrastructure, semiconductor incumbents controlling fabrication access, and specialized cryogenic hardware suppliers. Dominant competitive moves include strategic partnerships with national laboratory networks and backward integration into dilution refrigerator supply chains.
Within the cloud-operator tier, Amazon Web Services, Microsoft Corporation, and IBM Corporation exemplify divergent approaches to quantum networking procurement. AWS anchors its position through photonic tensor core evaluation programs. Microsoft occupies a regulatory-engagement position shaped by EU AI Act compliance tooling. IBM represents the national laboratory partnership archetype with sustained early-mover positioning in federally funded deployments.
| Leading Market Players |
|---|
| IBM Corporation |
| Amazon Web Services, Inc. |
| Intel Corporation |
| Microsoft Corporation |
| NVIDIA Corporation |
| Cisco Systems Inc. |
| Alphabet Inc. |
| Hewlett Packard Enterprise |
| Advanced Micro Devices, Inc. |
| Others |
Supply & Pricing Matrix
Performance-tier bifurcation between cryogenic quantum systems and commodity edge processors manifests in divergent pricing architectures and supply chain configurations. Premium superconducting deployments bundle dilution refrigerator maintenance with qubit access fees, while edge tensor processing units compete on unbundled per-unit procurement with minimal service attachment.
Pricing Analysis
Quantum-as-a-service bundles hardware access with cryogenic infrastructure support, while edge computing follows unbundled per-unit transactional models. Price differentiation rests on certification grade for FDA-cleared neuromorphic diagnostic hardware versus uncertified manufacturing inference accelerators. Cost compression in edge tensor processing units intensifies as hyperscale cloud operators internalize chip design. Financial services procurement committees demonstrate lowest price sensitivity for explainable quantum optimization systems, while South Asian manufacturing floors drive hardest per-unit negotiations.
Supply Chain Analysis
Dual-sourcing requirements for dilution refrigerators mandate qualification of both Finnish and United States suppliers for superconducting quantum deployments. Geographic supply concentration centers on Taiwan for silicon photonics foundry services, Finland for cryogenic infrastructure, and the United States for superconducting qubit fabrication. Raw material dependencies encompass helium-3 isotopes for millikelvin cooling, gallium arsenide substrates for photonic interferometers, and specialized microwave cabling for cryogenic control planes. Single-source vulnerability in helium-3 sourcing from Russian and Qatari export quotas constrains scaling timelines. Distribution runs through direct manufacturer relationships with national laboratory procurement offices and classified program authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
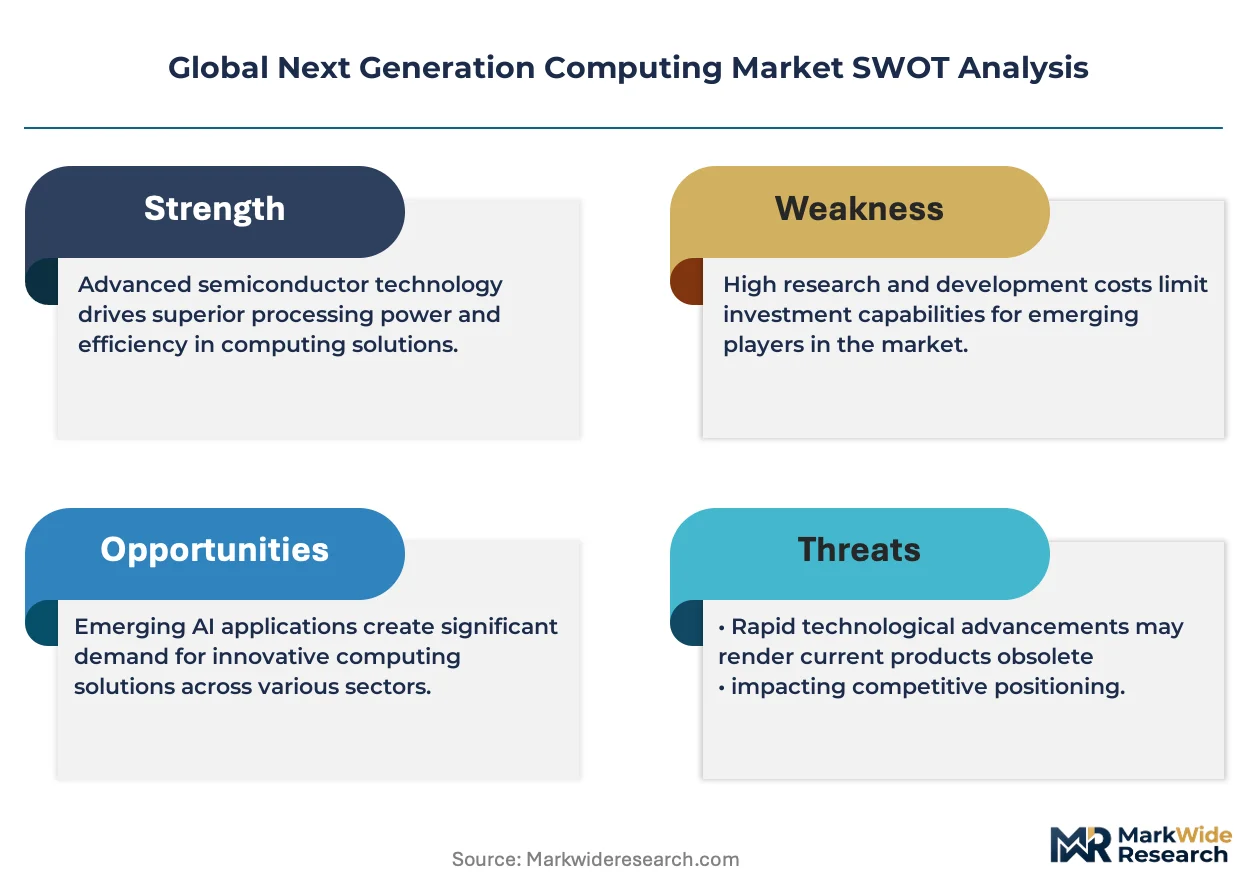
Geographic-arbitrage opportunities concentrate where India's semiconductor PLI scheme offers fabrication cost advantages against EU AI Act compliance burdens in European financial services procurement.
For Market Incumbents: Cement early-mover positioning through backward integration into dilution refrigerator supply chains and captive helium-3 sourcing agreements. IBM Corporation and analogous national laboratory partners should lock exclusive cryogenic infrastructure allocation before competitor qualification. Threat of photonic-quantum hybrid architectures displacing superconducting systems demands accelerated fault-tolerant roadmaps. For New Entrants and Emerging Players: Launch via India's semiconductor PLI scheme to access localized neuromorphic foundry services for South Asian edge computing deployments. White-space targets include room-temperature photonic tensor cores for data center inference and quantum-safe cryptography hardware for Japan's METI-mandated financial infrastructure replacement. Most penetrable segment: hybrid cloud deployments for latency-sensitive manufacturing quality control. For Investors and Strategic Acquirers: Consolidation pressure builds where cryogenic control electronics engineering talent pools concentrate at fewer than twelve global research institutions. Long-term viability favors vendors with demonstrated fault-tolerant quantum roadmaps and established national laboratory partnerships. Acquisition target archetype: specialized microwave engineering teams bridging room-temperature classical systems with millikelvin qubit planes. Signal to watch: NIST post-quantum cryptography standardization timelines accelerating federal budget allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryogenic Infrastructure | Captive dilution refrigerator supply secures scaling capacity for superconducting qubit deployments. |
| Photonic-Quantum Hybrid Architecture Development | Room-temperature interferometric meshes bypass helium-3 scarcity constraining millikelvin systems. |
| EU AI Act Compliance Tooling Investment | Explainable variational quantum eigensolver architectures satisfy algorithmic transparency mandates for Frankfurt financial services. |
| India Semiconductor PLI Localization | Domestic foundry access reduces landed cost for South Asian edge computing manufacturing deployments. |
| National Laboratory Partnership Expansion | DOE and NSF funding streams underwrite pilot superconducting systems for materials simulation workloads. |
Research Methodology
Coverage spans the United States, China, Germany, Japan, and India, with primary inputs from each regional cluster combining structured interviews with quantum hardware engineering directors, cryogenic infrastructure procurement officers, FDA regulatory affairs leads, hyperscale cloud platform engineers, and national laboratory program managers. Secondary validation draws from DOE funding disclosures, EMA algorithmic transparency guidance, METI quantum cryptography roadmaps, SEC hyperscaler capex filings, and BIS semiconductor standards documentation. Bottom-up deployment estimates triangulate against top-down market sizing across heterogeneous processing architectures.
Granularity-level modeling distinguishes superconducting qubit, neuromorphic memristor, photonic interferometric, and edge tensor processing unit technologies across the analysis window. Segmentation dimensions include deployment model, end-user vertical, and regulatory compliance tier. CAGRs derive from installed base projections weighted by capital intensity differentials. Industry-specific forecast inputs encompass helium-3 export quota trajectories and EU AI Act implementation timelines.
Several conditions sit outside the modeled scope, including breakthrough advances in room-temperature superconducting materials and unanticipated shifts in NIST post-quantum cryptography standardization. Forecasts reflect assumptions regarding sustained federal quantum computing funding and stable cryogenic infrastructure supply chains. Deviation in helium-3 isotope availability or EU AI Act enforcement severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging and Next Generation Technologies
Global Digital Twin Technology Market
Emerging and Next Generation Technologies
Internet of Nano Things Market
Emerging and Next Generation Technologies
Flexible Electronics Market
Emerging and Next Generation Technologies
Nanoelectronics Market
Emerging and Next Generation Technologies
Global Metamaterials Technologies Market
Emerging and Next Generation Technologies
Ultra-Thin Solar Cells Market
Emerging and Next Generation Technologies
Graphene Nanoplatelets Market
Emerging and Next Generation Technologies
AI Edge Computing Market
Emerging and Next Generation Technologies
Global Terahertz Components and Systems Market
Emerging and Next Generation Technologies
North America Next Generation Computing Market
Emerging and Next Generation Technologies
North America Wigig Market
Emerging and Next Generation Technologies
Metal Additive Manufacturing Systems Market
Emerging and Next Generation Technologies
Flexible Hybrid Electronics (FHE) Market
Emerging and Next Generation Technologies
North America Cleanroom Technology Market
Emerging and Next Generation Technologies
AI PC Market
Emerging and Next Generation Technologies
Haptic Technology Market