
 Printer Ribbons Market | 2026-2036
Printer Ribbons Market Size, Share, and Industry Trends Forecast 2026-2036
Printer Ribbons Market Analytics
A capital-intensity divergence between in-house film-coating capabilities and outsourced converting operations is reorganizing competitive tiers. Zebra Technologies leverages backward integration into thermal transfer ribbon manufacturing to control substrate quality and secure healthcare contracts. Armor-IIMAK competes through European coating facilities that sustain just-in-time supply to automotive label converters. DNP Group anchors its position via proprietary resin-wax formulations that dominate high-durability logistics applications in East Asia.
Printer ribbons are elongated strips of substrate—typically polyester, nylon, or vinyl films ranging from 25 to 110 millimeters in width—impregnated with wax, resin, or hybrid ink formulations and engineered to transfer pigment onto receiving media through thermal, impact, or inkjet mechanisms. Their primary commercial purpose is to produce durable, machine-readable marks including barcodes, serial numbers, and compliance labels across manufacturing, logistics, and institutional workflows. Thermal transfer ribbons occupy the largest value share due to their indispensability in variable-data labeling for regulated supply chains, while dot matrix ribbons retain residual demand in multi-part form printing within government and utility billing operations. Dye sublimation ribbons command premium positioning in photo-finishing and ID-card personalization where continuous-tone output and edge definition justify higher unit costs.
REACH restrictions on solvent-based coating chemistries and EPA emissions standards for volatile organic compounds in converting facilities shape formulation roadmaps and capital allocation across the industry. FDA Unique Device Identification mandates for medical device labeling reinforce demand for ISO-certified thermal transfer grades that withstand sterilization and long-term storage. Stakeholders must monitor regulatory tightening on per- and polyfluoroalkyl substances in ribbon coatings, as pending restrictions could force rapid reformulation cycles and qualification delays.
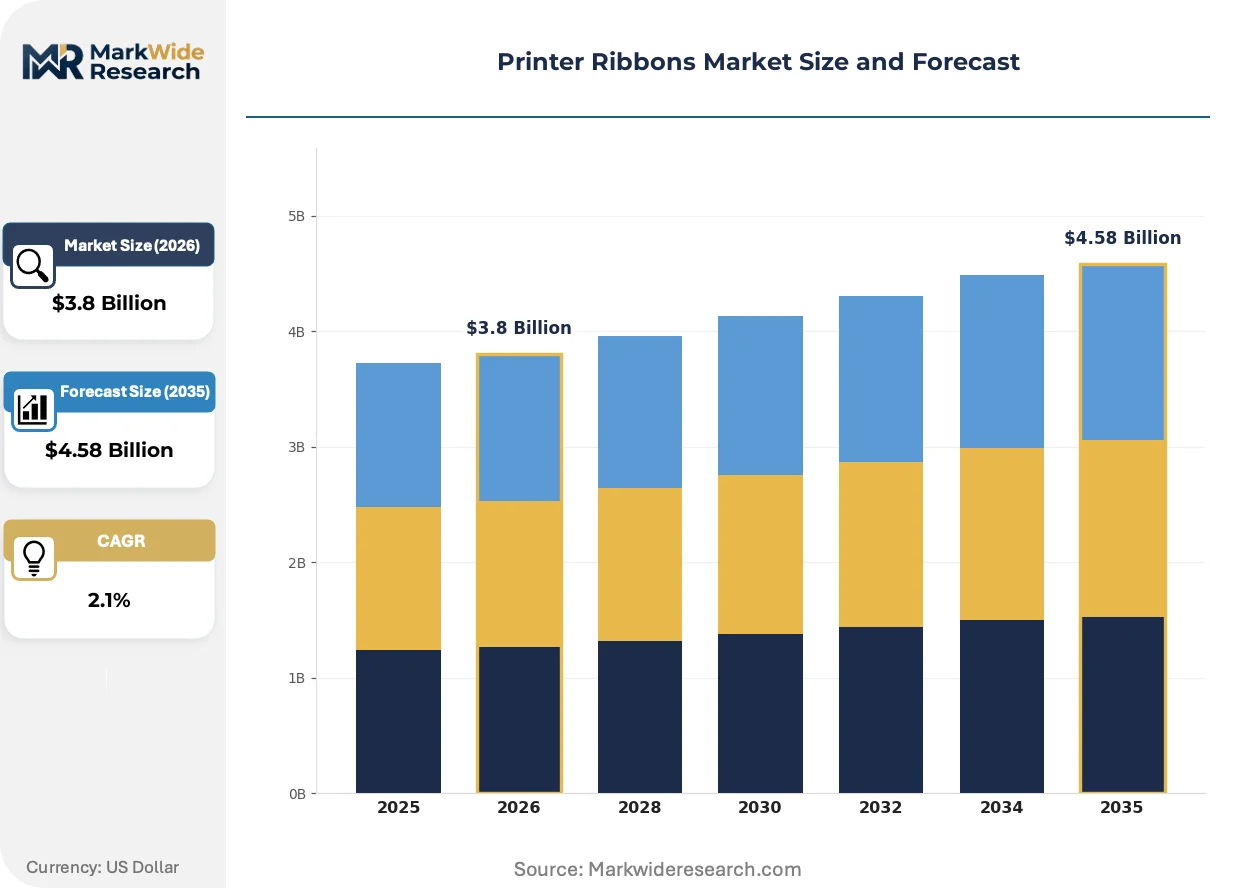
Market Dynamics
The EU F-Gas Regulation phase-down is forcing solvent-free coating process investments across thermal transfer ribbon manufacturing, while REACH restrictions on volatile organic compounds reshape formulation roadmaps and capital allocation priorities.
Growth Catalysts
- FDA Unique Device Identification mandates:Medical device labeling requirements in the United States sustain ISO-certified thermal transfer ribbon procurement for sterilization-resistant applications.
- Germany automotive parts traceability:Durable barcode mandates for component tracking drive ribbon consumption in supplier networks serving BMW, Mercedes-Benz, and Volkswagen assembly plants.
- Solvent-free thermal coating processes:Water-based resin-wax formulations replace solvent chemistries, opening qualification pathways for healthcare and food-contact labeling segments.
Market Restraints
- Petroleum-derived substrate costs:Polyester and nylon film prices track crude oil volatility, compressing margin buffers for converters without backward integration into film extrusion.
- East Asian resin supply concentration:Specialty wax and resin formulation inputs cluster in Chinese and Japanese chemical manufacturing, exposing buyers to logistics disruption risks.
- Digital label substitution:Direct thermal printing and inkjet technologies displace ribbon-based systems in short-run variable-data applications.
Strategic Opportunities
- India pharmaceutical serialization:Track-and-trace regulations for drug packaging create demand for high-durability thermal transfer grades in secondary labeling operations.
- RFID-thermal hybrid labels:Convergence of printed antenna structures with traditional barcode ribbons enables single-pass encoding for logistics asset tracking.
- EU Green Deal procurement incentives:Public sector purchasing criteria favor suppliers with verified solvent-free coating certifications and carbon footprint disclosures.
Industry Challenges
- Reformulation qualification timelines:Per- and polyfluoroalkyl substance restrictions pending under ECHA evaluation force rapid coating chemistry transitions with customer re-approval delays.
- Legacy printer fleet compatibility:Narrower ribbon widths and modified ink laydown specifications create integration friction with installed base dot matrix and thermal transfer hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Printer Ribbons Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.58 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Thermal Transfer, Inkjet, Dot Matrix, Dye Sublimation Material: Polyester, Vinyl, Nylon, Wax Color: Black, Red, Blue, Green End User: Retail, Healthcare, Education, Manufacturing |
| Companies Covered | Zebra Technologies, Seiko Epson, Armor-IIMAK, DNP Group, Canon, Dai Nippon Printing, ITW ShineMark, General Co., Ltd., Ricoh Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Printer Ribbons Market Evolving Landscape
Active materials research and regulatory chemistry restrictions are compressing traditional formulation cycles while opening pathways for bio-based and water-borne alternatives in high-compliance labeling segments.
Near-edge thermal transfer printhead technology is miniaturizing heating element arrays to 300 dots-per-inch densities and below, enabling finer barcode resolution on pharmaceutical vial labels and micro-device packaging. Medical device contract manufacturers in Switzerland and Germany are adopting these systems to meet ISO/IEC 15415 print quality specifications. The technology is miniaturizing ribbon substrate requirements, pushing film gauges below 4.5 microns and demanding tighter thickness tolerances from polyester suppliers.
REACH authorization procedures for diphenylmethane diisocyanate and selected solvent carriers are eliminating legacy coating chemistries from European manufacturing lines by 2027. Converting facilities in Belgium and the Netherlands face capital equipment decisions between water-based line conversions and site closures. Thermal transfer ribbon grades certified for food-contact and medical-device applications bear the highest compliance burden, with reformulation cycles extending 18-24 months.
Hospital and clinic networks are consolidating label supply contracts through group purchasing organizations, compressing supplier counts and demanding consolidated SKU portfolios across wristband, pharmacy, and specimen labeling applications. Large integrated delivery networks in the United States now specify single-source thermal transfer programs with volume commitments and technical service bundling. This concentration shifts pricing leverage toward buyers with multi-facility procurement scale and standardizes ribbon specifications across previously fragmented departmental purchasing.
Printer Ribbons Market Segmentation
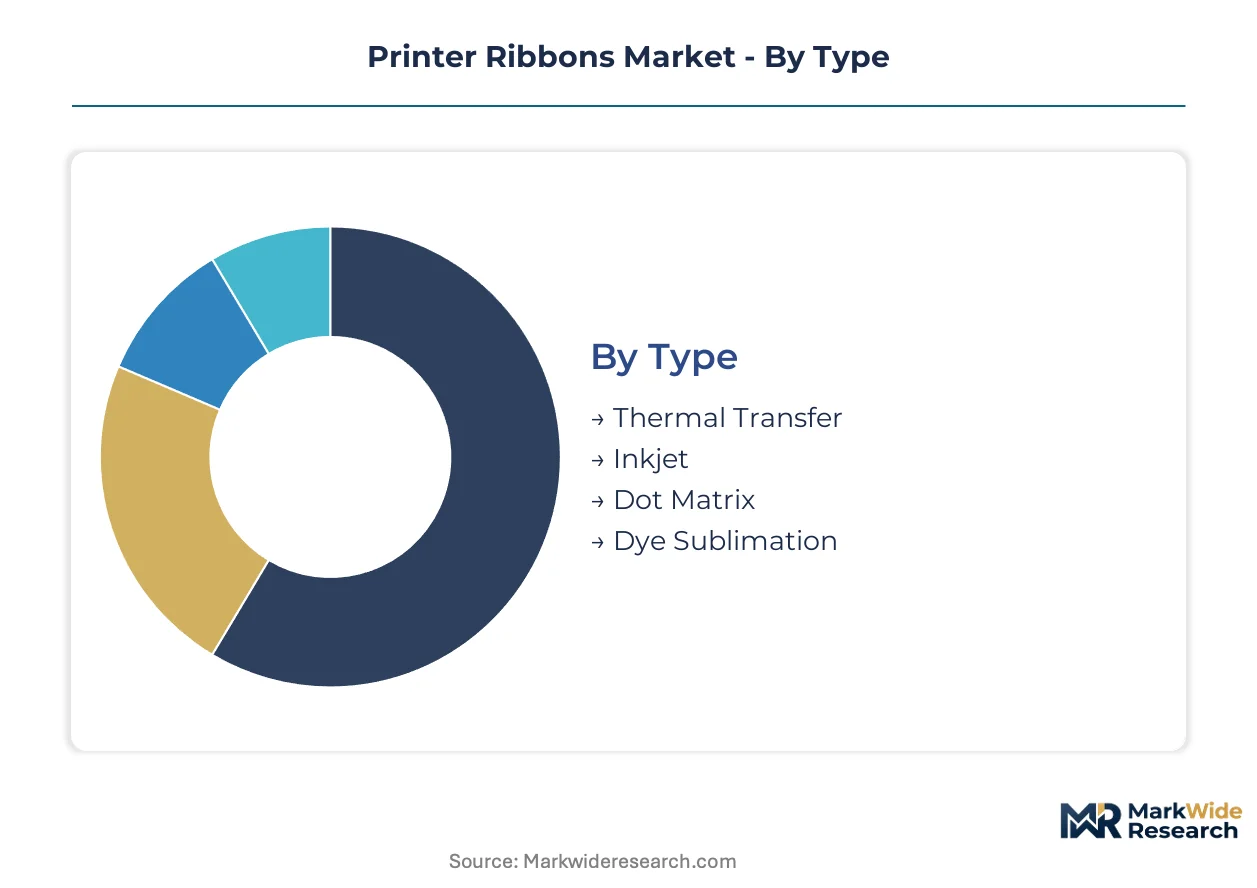
Printer ribbon segmentation reflects divergent compliance burdens across regulated supply chains. Thermal transfer grades face FDA sterilization mandates; dot matrix ribbons serve legacy government billing systems with minimal regulatory overlay.
Type:
REACH authorization procedures and FDA UDI mandates create divergent qualification timelines across ribbon technologies.
- Thermal Transfer:Wax-resin or pure resin formulations transfer pigment through heated printhead elements onto synthetic label stocks. Healthcare serialization in Germany and pharmaceutical track-and-trace in India concentrate procurement of ISO-certified grades that withstand gamma sterilization.
- Inkjet:Continuous or drop-on-demand systems deposit solvent-based or UV-curable inks without mechanical contact. Short-run variable-data applications in European logistics are displacing ribbon systems where direct marking satisfies durability requirements.
- Dot Matrix:Fabric or film substrates impregnated with oil-based inks strike paper through mechanical pins. Residual demand persists in US utility billing and government form printing where multi-part carbonless copies remain required.
- Dye Sublimation:Solid dye panels vaporize through thermal transfer into polymer-receptive coatings. Photo-finishing kiosks and ID card personalization in Japan and South Korea sustain premium positioning for continuous-tone output.
Thermal transfer handles the majority of throughput; dye sublimation is climbing the fastest on share in credentialing applications.
Material:
Substrate selection tracks petroleum price volatility and coating compatibility requirements.
- Polyester:Biaxially oriented polyethylene terephthalate films provide dimensional stability and thermal resistance. Automotive component labeling in Germany and medical device packaging in Switzerland specify sub-5-micron gauges for near-edge printhead compatibility.
- Vinyl:Polyvinyl chloride formulations offer flexibility and chemical resistance for curved surfaces. Chemical drum labeling and hazardous materials marking in US industrial facilities drive specification.
- Nylon:Polyamide substrates deliver toughness and ink receptivity for impact printing. Dot matrix applications in government and utility billing retain this material for multi-part form durability.
- Wax:Petroleum-derived or synthetic paraffin formulations provide low-cost pigment transfer for short-life paper labels. Food retail price marking in India and Southeast Asia concentrates demand for economy-grade thermal transfer.
Polyester dominates value capture; vinyl is expanding most quickly in chemical handling applications.
Color:
Color selection correlates with regulatory marking conventions and supply chain visibility protocols.
- Black:Carbon black pigment formulations deliver maximum contrast for barcode scanning and OCR recognition. Universal specification across logistics, healthcare, and manufacturing segments sustains volume concentration.
- Red:Iron oxide or organic dye systems signal expiration dates, recall status, or priority handling. Pharmaceutical secondary packaging in Europe and North America drives specification for alert conditions.
- Blue:Phthalocyanine or anthraquinone pigments distinguish lot codes and shift identifiers in multi-line manufacturing. Automotive supplier networks in Germany use blue for component variant marking.
- Green:Chromium-based or organic green dyes indicate environmental compliance or organic certification status. EU Green Deal procurement criteria and organic food labeling in France and Italy sustain niche demand.
Black carries the volume base; red is gaining share fastest in pharmaceutical compliance marking.
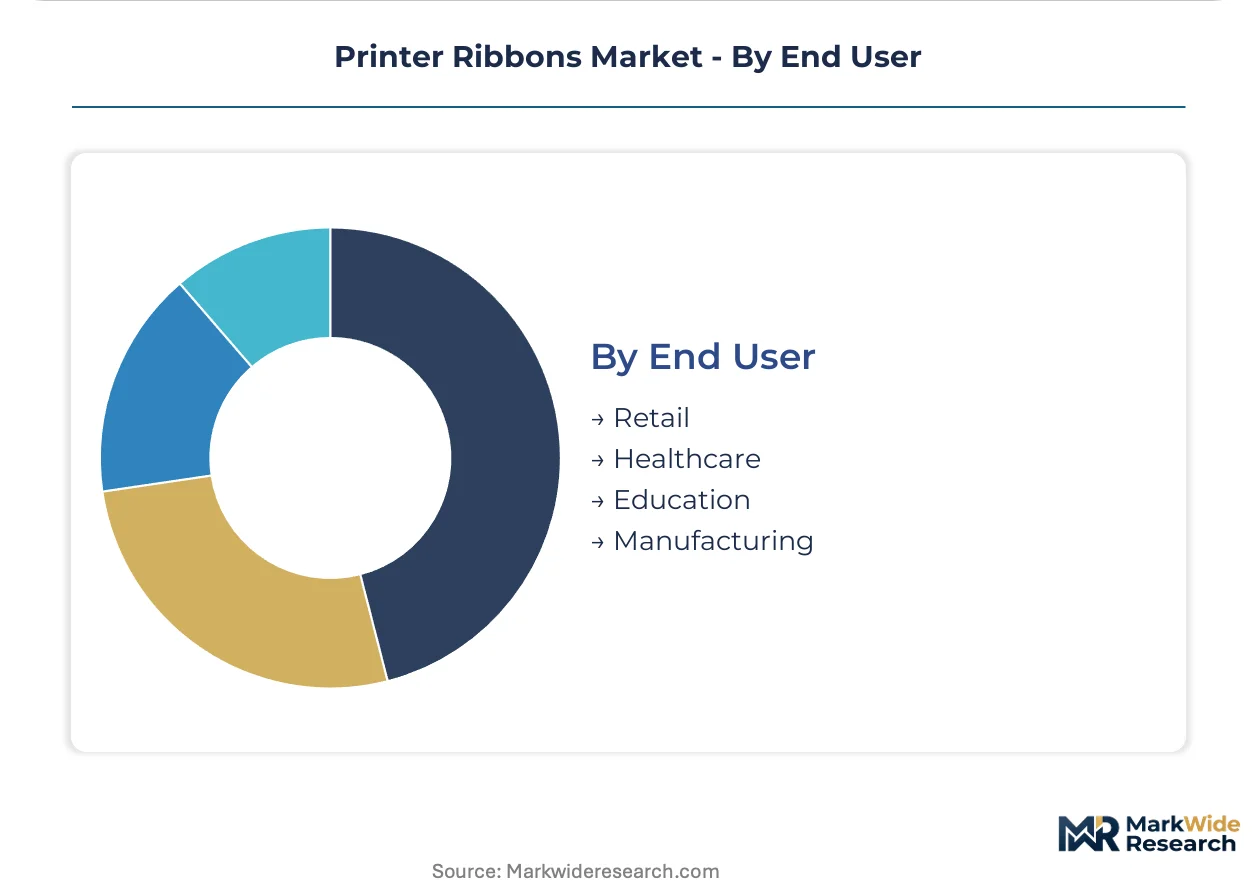
End User:
End-use concentration reflects sector-specific durability requirements and regulatory exposure.
- Healthcare:Patient wristband, prescription, and specimen labeling demand sterilization-resistant thermal transfer grades. FDA UDI mandates and EU MDR labeling rules enforce ISO-certified procurement through group purchasing organization consolidation.
- Manufacturing:Component traceability, work-in-process tracking, and finished goods identification require abrasion-resistant resin formulations. Automotive supply chains in Germany and electronics assembly in East Asia concentrate specification of high-durability grades.
- Retail:Shelf-edge pricing, promotional tagging, and loyalty card printing utilize wax-based thermal transfer for cost-sensitive short-life applications. Private label converters in India serve domestic supermarket chains.
- Education:Library asset tracking, student ID issuance, and administrative form printing span thermal transfer and dye sublimation technologies. University procurement in the United States consolidates through cooperative purchasing agreements.
Healthcare commands premium positioning; manufacturing delivers the steepest expansion trajectory in traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity for wax-grade thermal transfer ribbons, while German automotive suppliers and Swiss medical device manufacturers absorb substantial premiums for resin formulations that survive sterilization cycles and chemical exposure.
Germany
Automotive component traceability mandates from BMW, Mercedes-Benz, and Volkswagen assembly plants drive durable barcode ribbon consumption through supplier tiers. The EU F-Gas Regulation forces solvent-free coating investments at converting facilities in Baden-Württemberg and Bavaria. Stuttgart-based label converters now qualify water-based resin-wax formulations for under-hood component marking.
United States
FDA Unique Device Identification rules sustain ISO-certified thermal transfer procurement for medical device sterilization-resistant labels. Hospital group purchasing organizations consolidate contracts across wristband, pharmacy, and specimen labeling applications. Minneapolis and Boston medical device clusters specify sub-5-micron polyester grades for near-edge printhead compatibility.
India
Pharmaceutical serialization regulations for drug packaging create demand for high-durability thermal transfer grades in secondary labeling operations. Domestic supermarket chains drive wax-based ribbon consumption for short-life price marking. Mumbai and Ahmedabad private label converters serve retail networks with economy-grade formulations.
Japan
Dye sublimation ribbons command premium positioning for photo-finishing kiosks and ID card personalization requiring continuous-tone output. METI chemical management standards shape resin-wax formulation roadmaps for domestic coating facilities. Tokyo and Osaka specialty converters supply high-definition credentialing systems for corporate and government clients.
Switzerland
Medical device contract manufacturers adopt near-edge thermal transfer systems to meet ISO/IEC 15415 print quality specifications for micro-device packaging. Swissmedic labeling requirements enforce sterilization-resistant grade procurement through qualified supplier programs. Basel and Zurich precision manufacturing clusters specify sub-4.5-micron film gauges for pharmaceutical vial applications.
Printer Ribbons Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that relies on outsourced film converting and toll coating arrangements. Backward integration into polyester substrate manufacturing separates the upper tier from converters dependent on merchant film supply. Three archetypes dominate: full-stack manufacturers controlling resin formulation through substrate extrusion; regional coating specialists leveraging just-in-time logistics for automotive label converters; and technology licensors supplying proprietary ink systems to private-label assemblers. Capacity expansion in water-based coating lines and strategic partnerships for RFID-thermal hybrid label development represent the dominant competitive vectors.
Within the integrated manufacturing tier, Zebra Technologies exemplifies backward integration into thermal transfer ribbon production to secure substrate quality control and healthcare contract access. Armor-IIMAK occupies a position among European coating specialists sustaining proximity supply to automotive label converters in Germany and France. DNP Group anchors the resin-wax formulation archetype through proprietary chemistry dominance in high-durability logistics applications across East Asia.
| Leading Market Players |
|---|
| Zebra Technologies |
| Seiko Epson |
| Armor-IIMAK |
| DNP Group |
| Canon |
| Dai Nippon Printing |
| ITW ShineMark |
| General Co., Ltd. |
| Ricoh Electronics |
| Others |
Value Network & Pricing Analysis
ISO 15415 print quality certification gates supply qualification for medical device labeling while simultaneously enabling three-tier price stratification across sterilization-resistant, industrial-grade, and economy formulations. Buyers in Swiss and German healthcare clusters absorb substantial premiums for sub-4.5-micron polyester grades, while Indian pharmaceutical converters drive aggressive cost compression in wax-based thermal transfer segments.
Pricing Analysis
After-sales technical service contracts and GPO-bundled supply agreements drive lifetime value beyond transactional ribbon sales. Three-tier pricing structure across premium resin, standard wax-resin, and economy wax levels reflects certification burden and substrate gauge differentiation. Pricing pressure stems from direct thermal printing substitution in short-run logistics applications, compressing margins in standard-tier segments. Hospital procurement consolidation in the United States and retail price sensitivity in India represent opposite extremes of buyer leverage.
Supply Chain Analysis
Inventory lead times for specialty resin-wax formulations extend qualification cycles while polyester film supply concentrates in China, Japan, and Germany. Raw material dependencies center on petroleum-derived polyester substrates, paraffin wax feedstocks, and proprietary resin chemistries from East Asian chemical manufacturers. Single-source vulnerability in Japanese and Chinese specialty resin supply exposes converters to logistics disruption. Distribution runs through qualified label converter networks and direct OEM supply contracts to automotive and medical device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based coating capability and sub-5-micron film extrusion expertise constitute scarce assets that concentrate competitive advantage among integrated manufacturers, while toll-dependent converters face qualification barriers and margin compression.
For Market Incumbents: Compound coating chemistry leadership through captive resin formulation and water-based line conversion ahead of REACH authorization deadlines. Secure multi-year GPO contracts with U.S. hospital networks to lock out emerging competitors. Defend against direct thermal substitution by embedding RFID-thermal hybrid solutions in logistics asset-tracking programs. For New Entrants and Emerging Players: Technical service gaps in Indian pharmaceutical serialization and Southeast Asian food retail labeling present accessible entry points. Target domestic label converters in Mumbai and Ahmedabad with economy-grade wax formulations and rapid custom color matching. Build market presence through toll-coating partnerships with established film suppliers rather than capital-intensive backward integration. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down and pending ECHA per- and polyfluoroalkyl substance restrictions reshape the acquisition landscape toward water-based coating specialists and qualified medical-grade suppliers. Five-to-ten-year viability favors manufacturers with demonstrated FDA UDI and EU MDR certification pathways. Monitor qualification timeline announcements from Belgian and Dutch converting facilities as inflection indicators for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Line Conversion | REACH authorization procedures in Belgium and Netherlands force chemistry transitions by 2027. |
| Sub-5-Micron Polyester Backward Integration | Near-edge printhead adoption in Swiss medical device clusters demands tighter substrate tolerances. |
| RFID-Thermal Hybrid Label Development | Single-pass encoding convergence enables logistics asset tracking for German automotive supplier networks. |
| GPO Contract Consolidation | U.S. hospital purchasing organization concentration shifts pricing leverage toward multi-facility procurement scale. |
| India Pharmaceutical Serialization Partnership | Track-and-trace regulations for drug packaging create demand for high-durability thermal transfer grades. |
Research Methodology
Initial hypotheses were tested against primary input from thermal transfer ribbon plant managers, medical device label procurement leads, automotive supplier quality engineers, and private-label converter operations directors and refined through secondary validation. Sources included FDA UDI guidance documents, ECHA REACH authorization registers, EU F-Gas Regulation implementation reports, and customs trade data for polyester film and resin-wax formulations. Bottom-up volume modeling across ribbon types, substrate materials, and end-use segments triangulated with top-down market sizing from coating capacity and installed printer base estimates.
Variance decomposition across the projection horizon isolated volume drivers by segment: thermal transfer grade tier, substrate gauge specification, sterilization resistance certification, and regional regulatory cluster. CAGRs were derived from segment-level growth rate distributions weighted by base-year value shares. Industry-specific inputs included near-edge printhead adoption curves in medical device manufacturing, pharmaceutical serialization compliance deadlines in India, and solvent-free coating conversion capital expenditure pipelines in European converting facilities.
Forecasts assume regulatory continuity in EU REACH authorization timelines and FDA UDI enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
Retail Printers and Consumables Market
Printers
Electrophotographic Printing Market
Printers
Global Thermal Printing Market
Printers
Inkjet Printers Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Laser Printer Market
Printers
Thermal and Inkjet Disc Printers Market
Printers
Single Function Printer Market
Printers
Nanographic Printing Market
Printers
Refurbished Printers Market
Printers
Copier, MFP and Printer Market
Printers
NCR Printers Market
Printers
Aerosol Printing and Graphics Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Mobile Printer Market
Printers
Global UV LED Printers Market