
 Global Embedded Display Market | 2026-2036
Global Embedded Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Embedded Display Market Foresight
South Korea is tilting toward advanced OLED and MicroLED capacity expansion for embedded applications. Samsung Electronics leverages vertical integration across semiconductor and display fabrication to sustain technology leadership. LG Display anchors premium automotive and aviation display supply through specialized OLED production lines. BOE Technology Group competes aggressively on manufacturing scale in LCD and emerging MicroLED segments.
Embedded displays integrate flat-panel screens with dedicated controllers, touch sensors, and system-on-chip modules for fixed-function industrial or consumer equipment. These assemblies typically operate within temperature ranges of minus 20 to 70 degrees Celsius and incorporate projected capacitive or resistive touch layers for human-machine interface applications. TFT LCD occupies the largest installed base across industrial control panels and medical equipment due to mature supply chains and cost structures. OLED is displacing legacy technologies in wearable devices and premium automotive clusters where contrast ratios and form-factor flexibility command margin premiums. E-Ink sustains niche dominance in battery-constrained smart home interfaces and logistics tracking displays.
FCC certification governs electromagnetic emissions for embedded displays deployed in US aviation and telecommunications infrastructure. EASA and EU AI Act requirements are elevating functional safety and transparency standards for displays in autonomous automotive and aerospace systems. ISO 13485 and FDA quality system regulations shape product validation protocols for medical equipment manufacturers. Stakeholders must monitor how divergent regional certification timelines affect platform development costs and geographic market access strategies.
Market Dynamics
Automotive electrification is compressing display refresh cycles from seven-year platforms to three-year redesigns, forcing panel suppliers to accelerate qualification timelines for instrument cluster and HUD integration.
Growth Catalysts
- EU Green Deal:Carbon-neutral manufacturing mandates are pulling embedded display production toward renewable-powered fabs in Germany and the Netherlands, creating localized supply advantages for European automotive Tier 1s.
- Avionics modernization:FAA NextGen cockpit upgrades and EASA CS-25 amendments are mandating higher-resolution primary flight displays, opening certified panel demand from retrofit and OEM channels simultaneously.
- Touch-layer integration:On-cell capacitive architectures are collapsing module thickness and assembly steps, enabling curved automotive cluster designs that differentiate premium vehicle interiors.
Market Restraints
- Indium supply concentration:Over 80% of indium refining for ITO transparent electrodes originates from Chinese smelters, exposing display makers to export quota volatility and price spikes.
- RoHS substance restrictions:ECHA's tightening cadmium and lead exemptions are forcing reformulation of quantum-dot phosphors and solder alloys, extending R&D validation timelines by 12-18 months.
- MicroLED yield barriers:Mass transfer defect rates above 0.001% prevent cost-competitive scaling for sub-10-inch panels, locking the technology into premium watch and automotive prototype tiers.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for electronics manufacturing are attracting display module assembly investments targeting textile machinery and process control panel demand.
- EU AI Act transparency:Explainability requirements for autonomous vehicle HMI are creating certified "glass cockpit" upgrade cycles where interpretable display architectures command specification premiums.
- Medical home monitoring:FDA 510(k) pathway streamlining for remote patient monitoring devices is opening embedded e-paper and low-power LCD demand for disposable diagnostic peripherals.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D certified firmware developers remain concentrated at German and Japanese automotive suppliers, constraining new entrant qualification capacity.
- Dual regulatory convergence:Simultaneous FCC Part 15 and EASA DO-160G certification for aviation-grade displays requires parallel test matrices that extend time-to-revenue by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Embedded Display Market |
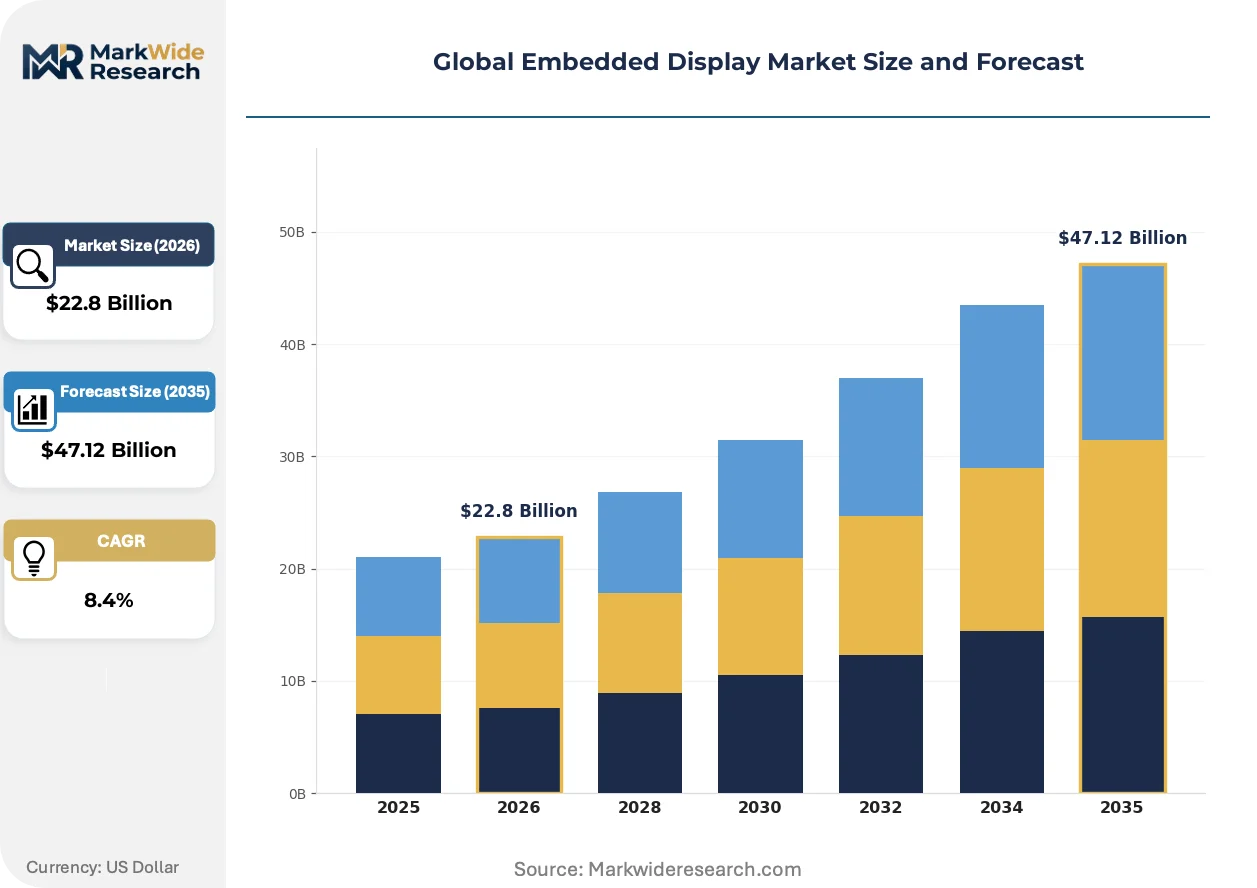
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, LCD, TFT, E-Ink, LED, MicroLED Technology: Capacitive Touch, Resistive Touch, Projected Capacitive, Infrared Touch, Optical Touch, MEMS Application: Wearable Devices, Industrial Control Panels, Consumer Electronics, Aviation Instrumentation, Smart Home Devices, Gaming Consoles End User: Manufacturers of Medical Equipment, Telecommunications Providers, Aerospace Firms, Electronic OEMs, Defense Contractors, Automotive Electronics Firms |
| Companies Covered | Avnet, Inc., Samsung Electronics Co., Ltd., LG Display Co., Ltd., Texas Instruments Incorporated, Intel Corporation, Winstar Display Co., Ltd., BOE Technology Group Co., Ltd., AU Optronics Corp., Planar Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Embedded Display Market Shifts & Advancements
Display architecture is fragmenting along functional-safety tiers, with automotive and medical applications diverging from consumer-grade modules through hardened controller designs and traceable supply chains.
LTPO backplane technology is virtualizing refresh rate control across frame-by-frame workloads, enabling always-on cluster displays without thermal runaway. German automotive OEMs are specifying LTPO for 2026 platform launches, anticipating 30-40% backlight power reduction versus conventional LTPS. This virtualization of power management is compressing the performance gap between OLED and premium LCD in size-constrained cockpit locations.
REACH SVHC candidate list expansion is forcing substitution of halogenated flame retardants in display housing resins, with ECHA 2023-2024 updates targeting phosphorus-based alternatives that require requalification of UL 94 V-0 ratings. Module assemblers in Poland and Hungary are consolidating resin sourcing to suppliers with pre-validated halogen-free portfolios, shifting procurement criteria from unit cost to compliance velocity.
Aviation MRO procurement is consolidating around long-term availability contracts that unbundle display hardware from installation and calibration services, reversing the traditional bundled aftermarket model. Lufthansa Technik and ST Engineering are piloting component-leasing structures for cockpit display upgrades, transferring obsolescence risk to suppliers in exchange for guaranteed 15-year part availability. This service unbundling is most advanced in European and Southeast Asian maintenance hubs where fleet commonality enables pooled inventory models.
Global Embedded Display Market Segmentation
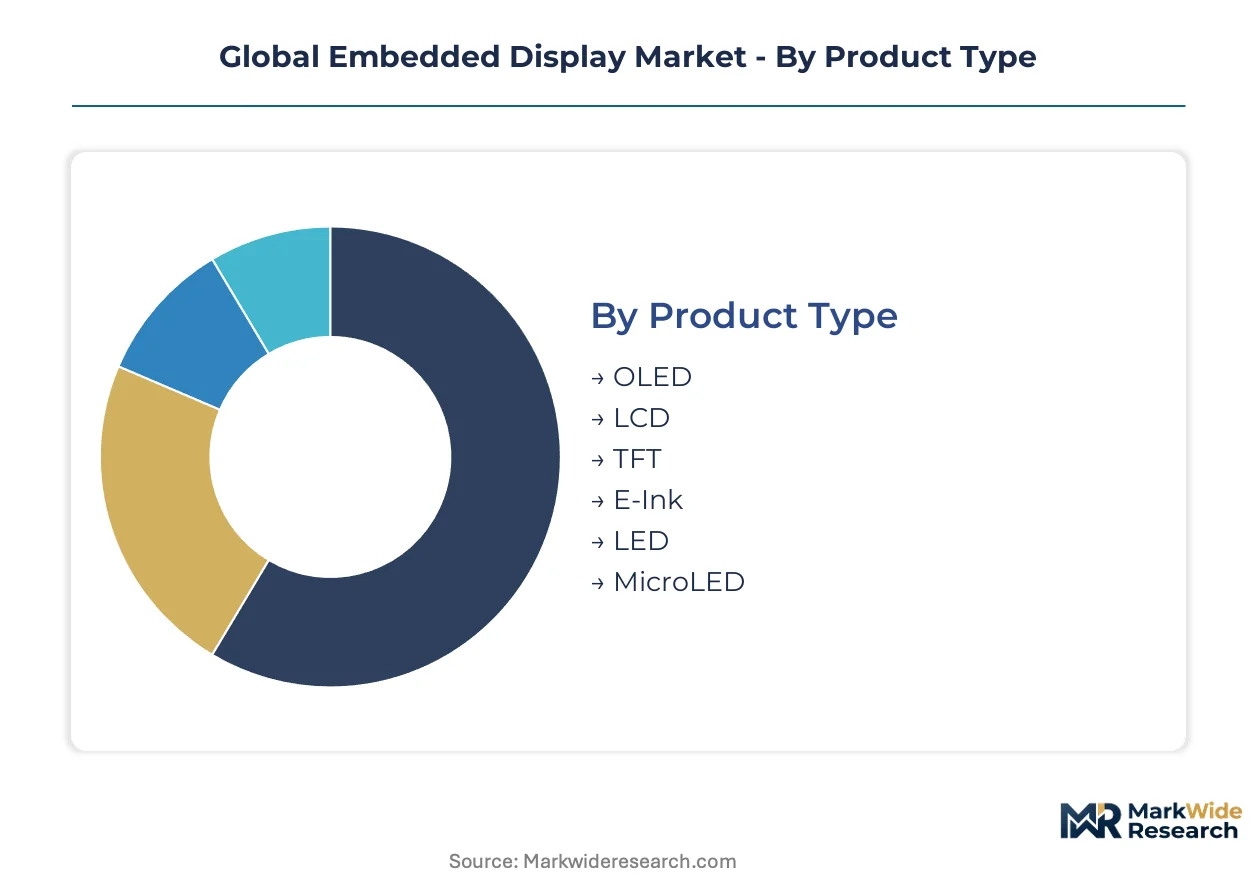
Embedded display procurement patterns diverge sharply across product architectures and touch-layer specifications, with after-sales calibration and firmware update obligations varying by segment intensity. Service contracts for aviation and medical applications command multi-year availability guarantees that reshape total cost of ownership calculations for buyers.
Product Type:
After-sales-service intensity peaks in automotive and aviation segments where display modules require periodic recalibration, firmware patches, and obsolescence management over 10-15 year operational lifecycles.
- LCD:Mature thin-film transistor architectures dominate industrial control panels and medical imaging equipment where supply chain stability outweighs performance premiums. Demand concentrates in German and Japanese manufacturing automation sectors, constrained by indium tin oxide supply volatility from Chinese refining operations.
- OLED:Organic electroluminescent layers enable flexible form factors and superior contrast ratios for wearable devices and premium automotive clusters. Korean panel fabricators anchor supply through vertically integrated semiconductor and display production, with German OEMs specifying LTPO backplanes for 2026 platform launches.
- TFT:Thin-film transistor active-matrix addressing supports high-refresh-rate industrial monitors and gaming peripherals.
- E-Ink:Bistable electrophoretic technology sustains ultra-low-power logistics tracking and smart home interfaces.
- LED:Direct-view and edge-lit configurations illuminate large-format digital signage and outdoor industrial readouts.
- MicroLED:Gallium nitride micro-emitter arrays promise breakthrough brightness for augmented reality headsets and next-generation automotive head-up displays.
By volume, LCD leads. By growth pace, OLED is ahead.
Technology:
Touch-sensing architecture selection hinges on environmental durability requirements and electromagnetic interference tolerance across aviation, medical, and defense applications.
- Projected Capacitive:Multi-touch recognition through indium tin oxide electrode grids enables curved automotive cluster designs and smartphone-class responsiveness. German Tier 1 suppliers specify on-cell integration to collapse module thickness, with FAA certification timelines extending qualification cycles for avionics implementations.
- Capacitive Touch:Surface capacitance detection supports single-point interaction in cost-sensitive consumer electronics and point-of-sale terminals. Chinese module assemblers drive manufacturing scale for industrial and white-goods applications, constrained by RoHS substance restrictions on electrode materials.
- Resistive Touch:Pressure-activated membrane layers function through gloved operation in factory floor and medical sterile environments.
- Infrared Touch:LED emitter-detector arrays enable vandal-resistant public kiosks and outdoor gaming installations.
- Optical Touch:Camera-based gesture recognition supports large-format interactive whiteboards and digital signage.
- MEMS:Micro-electromechanical haptic feedback actuators integrate force sensation into automotive center console interfaces.
Projected capacitive dominates revenue contribution, while MEMS haptic layers are expanding most quickly in premium automotive specifications.
Application:
Application-specific certification requirements fragment procurement criteria, with medical and aviation displays commanding traceable supply chains absent from consumer electronics sourcing.
- Aviation Instrumentation:Primary flight displays and multifunction head-down units require EASA CS-25 and FAA TSO-C113 certification for brightness, viewing angle, and mean time between failures. Lufthansa Technik and ST Engineering pilot component-leasing structures that transfer obsolescence risk to suppliers over 15-year availability contracts.
- Industrial Control Panels:Human-machine interfaces for process automation operate across minus 20 to 70 degrees Celsius thermal envelopes with projected capacitive or resistive touch layers. Indian textile machinery and process equipment manufacturers drive module assembly investments under PLI scheme incentives.
- Wearable Devices:Smartwatches and fitness trackers prioritize OLED power efficiency and form-factor flexibility.
- Consumer Electronics:Kitchen appliances and white goods integrate basic LCD readouts with minimal touch functionality.
- Smart Home Devices:Thermostats and security panels leverage E-Ink for battery-constrained always-on status displays.
- Gaming Consoles:Handheld systems and arcade cabinets demand high-refresh-rate TFT panels with optical touch overlays.
Industrial control panels anchor shipment volume, while aviation instrumentation claims the steepest expansion trajectory driven by MRO upgrade cycles.
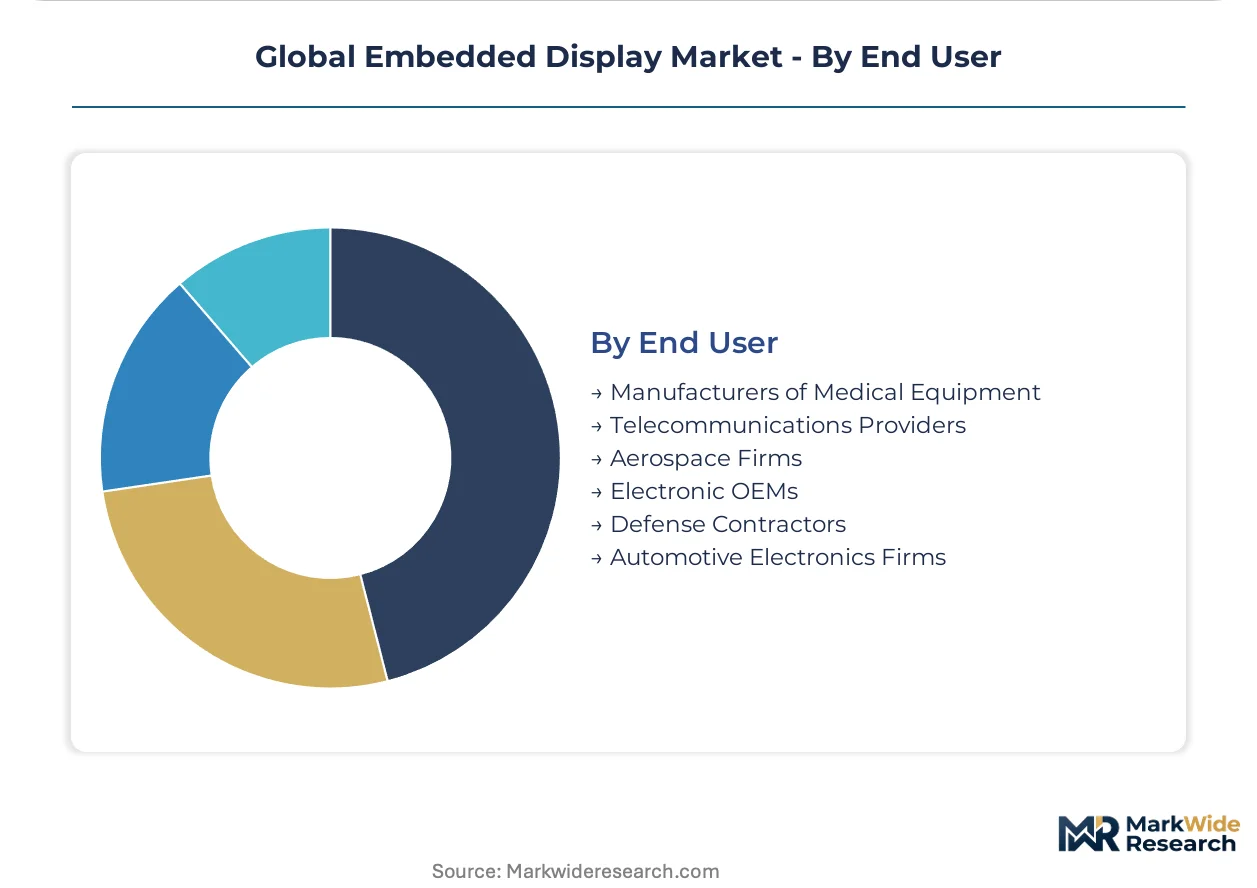
End User:
End-user procurement sophistication spans from commodity spot purchasing in consumer electronics to multi-year qualification partnerships in aerospace and defense.
- Automotive Electronics Firms:Tier 1 suppliers such as Continental and Bosch compress display refresh cycles from seven-year platforms to three-year redesigns for instrument cluster and head-up display integration. EU AI Act transparency requirements for autonomous vehicle HMI are creating certified glass cockpit upgrade specifications.
- Manufacturers of Medical Equipment:FDA 510(k) pathway streamlining for remote patient monitoring devices opens embedded e-paper and low-power LCD demand for disposable diagnostic peripherals. ISO 13485 quality system regulations shape validation protocols for patient-facing displays.
- Aerospace Firms:Boeing and Airbus procurement teams mandate DO-160G environmental testing and EASA design approval for cockpit display replacements.
- Defense Contractors:Raytheon and Lockheed Martin programs require ITAR-controlled supply chains with domestic sourcing preferences.
- Telecommunications Providers:Ericsson and Nokia specify FCC Part 15 electromagnetic emissions compliance for network infrastructure monitoring panels.
- Electronic OEMs:Foxconn and Jabil consolidate display module purchasing across multiple end-product categories.
Electronic OEMs aggregate the largest procurement volumes, while medical equipment manufacturers are gaining share fastest through remote monitoring device proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European display module import capacity, while the Yangtze River Delta's semiconductor fabrication clusters anchor Asia-Pacific supply chain density for embedded panel manufacturing.
China
BOE Technology Group and domestic panel makers are scaling capacity for industrial and consumer applications across the Yangtze River Delta. MIIT's dual carbon goals are tightening energy efficiency standards for display fabs in Jiangsu and Anhui provinces. Shenzhen's electronics manufacturing corridor concentrates module assembly operations serving white goods and automotive Tier 1 suppliers.
Germany
Continental and Bosch compress display refresh cycles from seven-year platforms to three-year redesigns for instrument cluster integration. KBA enforces EU AI Act transparency requirements for autonomous vehicle HMI certification. Bavaria's automotive electronics corridor anchors glass cockpit specification development for 2026 platform launches.
South Korea
Samsung Electronics leverages backward integration across semiconductor and display fabrication to sustain technology leadership in OLED capacity. MFDS medical device regulations shape validation protocols for patient-facing diagnostic displays. Gyeonggi Province's display fabrication belt concentrates LTPO backplane production for wearable and automotive applications.
United States
FAA NextGen cockpit upgrades mandate higher-resolution primary flight displays from retrofit and OEM channels. FCC Part 15 governs electromagnetic emissions for aviation and telecommunications infrastructure panels. Texas Instruments anchors controller semiconductor supply from Dallas-Fort Worth fabrication facilities serving industrial automation demand.
India
PLI scheme incentives for electronics manufacturing attract display module assembly investments targeting textile machinery and process control panels. BIS certification requirements shape product validation timelines for industrial equipment integration. Gujarat's Special Economic Zones concentrate contract manufacturing operations for European automotive Tier 1 procurement.
Global Embedded Display Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in a structure that fragments across display fabrication, controller semiconductor, and module assembly layers. Korean and Chinese panel fabricators anchor capacity expansion through captive supply of backplane semiconductors. Three archetypes dominate: vertically integrated display-OEM hybrids, specialized controller semiconductor suppliers, and contract module assemblers. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as firms race to qualify for compressed automotive redesign cycles.
Among Korean fabricators, Samsung Electronics Co., Ltd. and LG Display Co., Ltd. occupy positions exemplifying the vertically integrated archetype, with the former representing backward integration into semiconductor production and the latter anchoring specialized OLED supply lines for premium automotive and aviation specifications. BOE Technology Group Co., Ltd. exemplifies the scale-driven Chinese competitor archetype, competing aggressively on manufacturing scale across LCD and emerging MicroLED segments.
| Leading Market Players |
|---|
| Avnet, Inc. |
| Samsung Electronics Co., Ltd. |
| LG Display Co., Ltd. |
| Texas Instruments Incorporated |
| Intel Corporation |
| Winstar Display Co., Ltd. |
| BOE Technology Group Co., Ltd. |
| AU Optronics Corp. |
| Planar Systems, Inc. |
| Others |
Supply & Pricing Matrix
Indium refining concentration in Chinese smelters for ITO transparent electrodes funnels margin capture toward downstream panel fabricators with captive semiconductor capacity, compressing module assemblers between raw material volatility and fixed-price automotive contracts.
Pricing Analysis
REACH and RoHS substance restrictions dictate the pricing tier structure across the embedded display market. Three-tier pricing structure across aviation-certified, automotive-qualified, and industrial-grade levels segments buyers by validation intensity and traceability requirements. Pricing pressure stems from indium supply quota volatility exposing mid-tier module assemblers to margin compression. Electronic OEMs exhibit highest price sensitivity through consolidated spot purchasing, while aerospace firms accept premium positioning for 15-year availability guarantees.
Supply Chain Analysis
Foxconn, Jabil, and Wistron hold dominant contract manufacturing capacity for embedded display module assembly. Taiwan, South Korea, and China anchor geographic supply concentration through backplane semiconductor fabrication and panel production. Raw material dependencies center on indium for ITO electrodes, gallium nitride for MicroLED emitters, and halogen-free flame retardants for housing resins. Single-source vulnerability in Chinese indium refining creates structural supply risk. Distribution runs through direct OEM partnerships for automotive and aviation tiers, with spot market channels serving industrial and consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The embedded display market is entering a cyclical recovery phase driven by compressed automotive redesign cycles compressing from seven-year platforms to three-year iterations.
For Market Incumbents: Entrench position through backward integration into controller semiconductor production and accelerated qualification for LTPO backplane specifications. Korean panel fabricators face substitution threat from Chinese scale competitors in LCD segments; defensive capacity addition in Gyeonggi Province and Bavaria automotive corridors preserves specification premiums. Certification investment in ISO 26262 ASIL-D firmware development locks in automotive Tier 1 relationships.
For New Entrants and Emerging Players: Build out specialized module assembly operations targeting India's PLI scheme incentives for textile machinery and process control panel demand. White-space concentrates in medical home monitoring devices where FDA 510(k) pathway streamlining opens embedded e-paper and low-power LCD demand. Go-to-market angle: partner with European automotive Tier 1s seeking dual-source qualification for glass cockpit architectures under EU AI Act transparency mandates.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated controller-display specialists with captive backplane semiconductor capacity and established automotive qualification pipelines. Long-term viability favors firms with proven EASA and FAA certification track records over pure-play panel fabricators exposed to commodity LCD cycles. Signal to watch: MicroLED mass transfer yield breakthrough below 0.001% defect rates as inflection indicator for premium tier displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| LTPO Backplane Capacity Expansion | German OEM specifications for 2026 platform launches drive 30-40% backlight power reduction versus LTPS alternatives. |
| Halogen-Free Resin Portfolio Consolidation | ECHA SVHC list expansion forces module assemblers in Poland and Hungary toward pre-validated UL 94 V-0 compliant suppliers. |
| Aviation Component-Leasing Structures | Lufthansa Technik and ST Engineering pilot 15-year availability contracts transferring obsolescence risk to display suppliers. |
| India PLI Scheme Module Assembly Investment | Gujarat Special Economic Zones attract European automotive Tier 1 procurement seeking geographic diversification. |
| ISO 26262 ASIL-D Firmware Certification | Functional safety engineering scarcity at German and Japanese automotive suppliers constrains new entrant qualification capacity. |
Research Methodology
Initial hypotheses were tested against primary input from display module procurement managers, automotive Tier 1 platform engineers, aviation MRO directors, medical device regulatory affairs leads, and industrial automation plant engineers and refined through secondary validation against SEC 10-K filings, EASA certification databases, FDA 510(k) submission records, and customs trade data. Bottom-up shipment modeling across product architectures and touch-layer specifications triangulated against top-down value estimates from panel fabrication capacity disclosures.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include display technology type, touch-sensing architecture, application certification tier, and regional regulatory cluster. CAGRs were derived from installation base expansion rates and replacement cycle compression in automotive platforms. Industry-specific forecast inputs incorporated aviation MRO upgrade pipelines and medical remote monitoring device proliferation trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese scale competitors in MicroLED segments or sudden indium export quota restrictions would shift outcomes. Quarterly review of ECHA SVHC list updates, FAA NextGen cockpit upgrade procurement schedules, and automotive platform launch delays is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
North America Industrial Display Market
Display Technologies
Smart Screen Market
Display Technologies
United States Microdisplay Market
Display Technologies
Foldable Screens Market
Display Technologies
Global Haptic Touchscreen Market
Display Technologies
Digital Kiosk Display Market
Display Technologies
Commercial Display Market
Display Technologies
Computer Monitor Market
Display Technologies
Global Display Panel Market
Display Technologies
Large Format Display (LFD) Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Advanced (3D/4D) Visualization Systems Market
Display Technologies
IGZO Display Market
Display Technologies
Touch Screen Display Market
Display Technologies
North America Head-Up Display Market
Display Technologies
Alphanumeric LCD Modules Market