
 Cell Disrupters Market | 2026-2036
Cell Disrupters Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Disrupters Market Insights
Contract research organizations are unwinding demand share from traditional academic buyers as outsourced biologics development accelerates. Thermo Fisher Scientific leverages its consumables-to-instrument bundling to sustain recurring revenue streams across high-throughput screening workflows. Beckman Coulter anchors its position through centrifugation-integrated disruption platforms that reduce sample preparation steps. Merck KGaA differentiates via membrane protein extraction protocols optimized for ion channel drug discovery.
Cell disrupters are mechanical or physical devices engineered to rupture cell walls and membranes through controlled energy input, typically operating at power densities between 50 and 1500 W for ultrasonic systems and pressures up to 27000 psi for high-pressure homogenizers, enabling downstream recovery of intracellular proteins, nucleic acids, or organelles. Sonication equipment retains the largest installed base among product types due to capital accessibility and protocol familiarity, though microfluidizers command premium pricing in nanoscale liposome manufacturing where narrow particle size distribution is mandatory. Mechanical disruption technology dominates throughput-sensitive pharmaceutical applications, while enzymatic disruption protocols expand in food processing where label-friendly extraction methods replace chemical lysis agents.
FDA enforces current Good Manufacturing Practice validation for cell disruption equipment used in active pharmaceutical ingredient production, while EU MDR requires traceable qualification documentation for devices contacting biological material destined for therapeutic use. ISO 13485 certification increasingly gates supplier access to pharmaceutical original equipment manufacturer procurement lists. Stakeholders must monitor evolving harmonization between FDA process analytical technology guidelines and EMA quality risk management expectations to preempt compliance-driven equipment replacement cycles.
Market Dynamics
Contract research organizations now absorb unit shipments once dominated by academic laboratories, rewiring procurement patterns around high-throughput screening workflows and consumables bundling rather than standalone capital equipment.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates force pharmaceutical manufacturers to replace legacy disruption equipment with validated, traceable systems, sustaining replacement demand across GMP facilities.
- Biologics manufacturing clusters:Expansion of antibody and cell therapy production in Germany, the United States, and China concentrates demand for high-pressure homogenizers capable of consistent intracellular protein recovery.
- Enzymatic disruption protocols:Food processors adopt label-friendly extraction methods to replace chemical lysis agents, opening unit shipment growth in clean-label ingredient supply chains.
Market Restraints
- Stainless steel and precision pump supply:Concentration of high-pressure homogenizer component sourcing in German and Swiss machining centers creates input cost volatility and extended lead times.
- Ultrasonic probe degradation:Titanium alloy cavitation erosion limits sonicator tip lifespan to 500-2000 hours, forcing unplanned maintenance windows that interrupt continuous bioprocessing.
- EU MDR traceability documentation:Therapeutic-use equipment now requires qualification dossiers that extend vendor onboarding cycles by 8-14 months, freezing spot procurement.
Strategic Opportunities
- India biologics CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru lack scaled mechanical disruption capacity, creating first-mover positioning for equipment vendors with localized service networks.
- Microfluidizer-nanoparticle convergence:Liposome and lipid nanoparticle manufacturing for mRNA delivery requires narrow particle size distribution that only microfluidic disruption achieves reliably.
- ISO 13485 certification gating:Pharmaceutical OEM procurement lists now exclude uncertified suppliers, rewarding early compliance investment with captive supplier status.
Industry Challenges
- Process analytical technology integration:Biopharma customers demand real-time cell lysis monitoring via in-line turbidity or conductivity sensors, requiring firmware development capabilities few equipment vendors possess.
- Centrifugation-disruption workflow unification:Beckman Coulter's integrated platforms reduce sample preparation steps, forcing competitors to reconfigure standalone equipment architectures or concede high-throughput screening accounts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Disrupters Market |
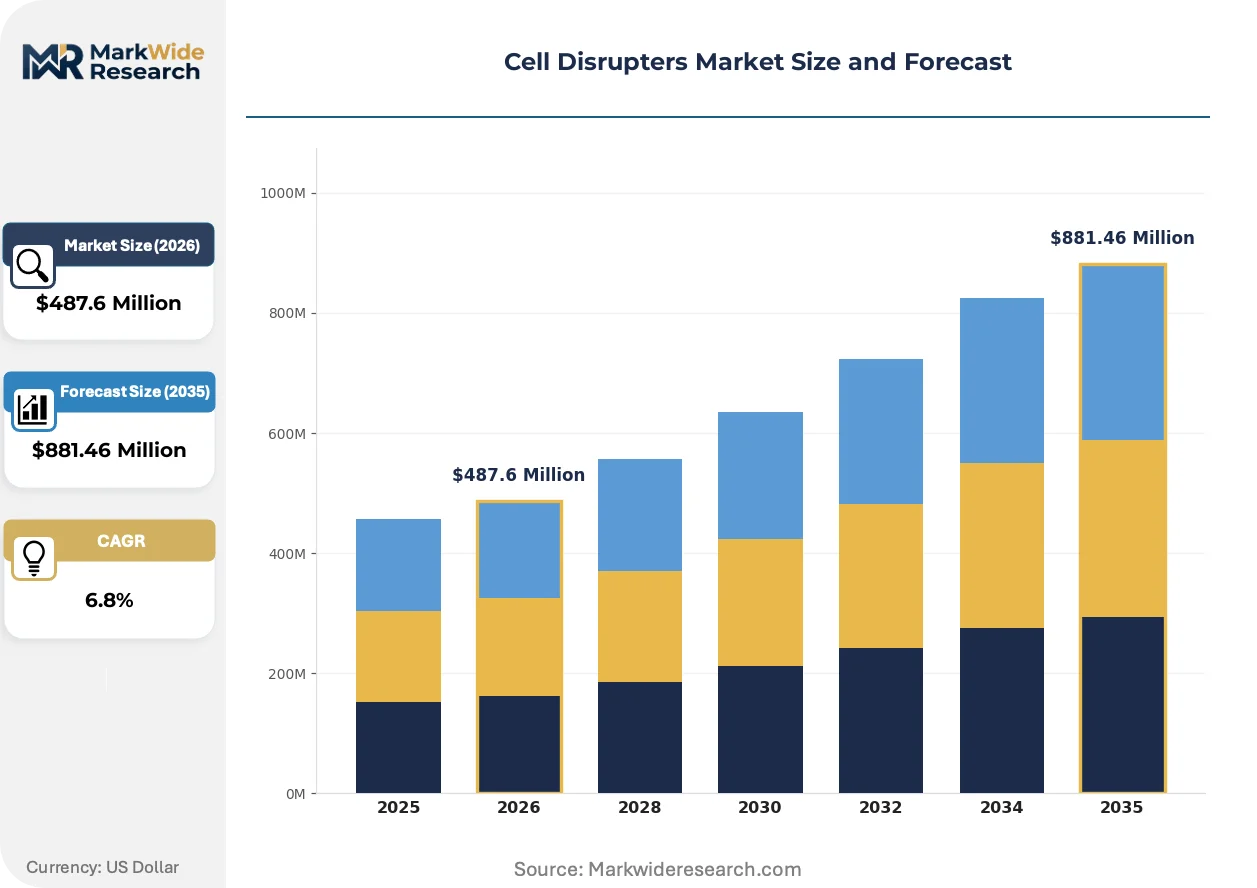
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sonication, Homogenizers, Bead Mill, Microfluidizers Application: Biotechnology, Pharmaceutical, Research Laboratories, Food Processing Technology: Mechanical Disruption, Chemical Disruption, Enzymatic Disruption, Thermal Disruption End User: Academia, Pharmaceutical Companies, Food Manufacturers, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific, Beckman Coulter, Merck KGaA, Bio-Rad Laboratories, QIAGEN, Analytik Jena, Hielscher Ultrasonics, Parr Instrument Company, Stansted Fluidic Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Disrupters Market Trends and Innovations
Equipment architectures are fragmenting as biopharma workflows splinter between legacy batch processing and emerging continuous manufacturing paradigms, forcing vendors to support incompatible validation protocols simultaneously.
Microfluidic disruption technology is fragmenting the premium equipment tier as nanoscale liposome manufacturers abandon ultrasonic homogenization for microfluidizer platforms that deliver coefficient of variation below 15% in particle size distribution. Gene therapy CDMOs in Boston and Basel now specify microfluidic protocols in technical purchasing agreements. This specification creep is compressing addressable market share for conventional high-pressure homogenizers in viral vector manufacturing.
EMA quality risk management guidelines are converging with FDA process analytical technology frameworks, forcing equipment vendors to harmonize qualification documentation across Atlantic regulatory regimes. Dual-compliant validation packages now determine vendor shortlisting for multinational biologics manufacturers. European contract manufacturers report 30% faster FDA pre-approval inspection clearance when equipment dossiers reference EMA ICH Q9 methodology.
Service contract unbundling is accelerating as capital-constrained biotech startups reject multi-year maintenance agreements in favor of per-incident technical support purchased through digital marketplaces. Equipment financiers in San Diego and Cambridge now bundle disruption hardware with pay-per-use service credits rather than traditional warranty extensions. This consumption-model pivot is most visible among Series B-funded cell therapy developers with uncertain clinical timelines.
Cell Disrupters Market Segmentation
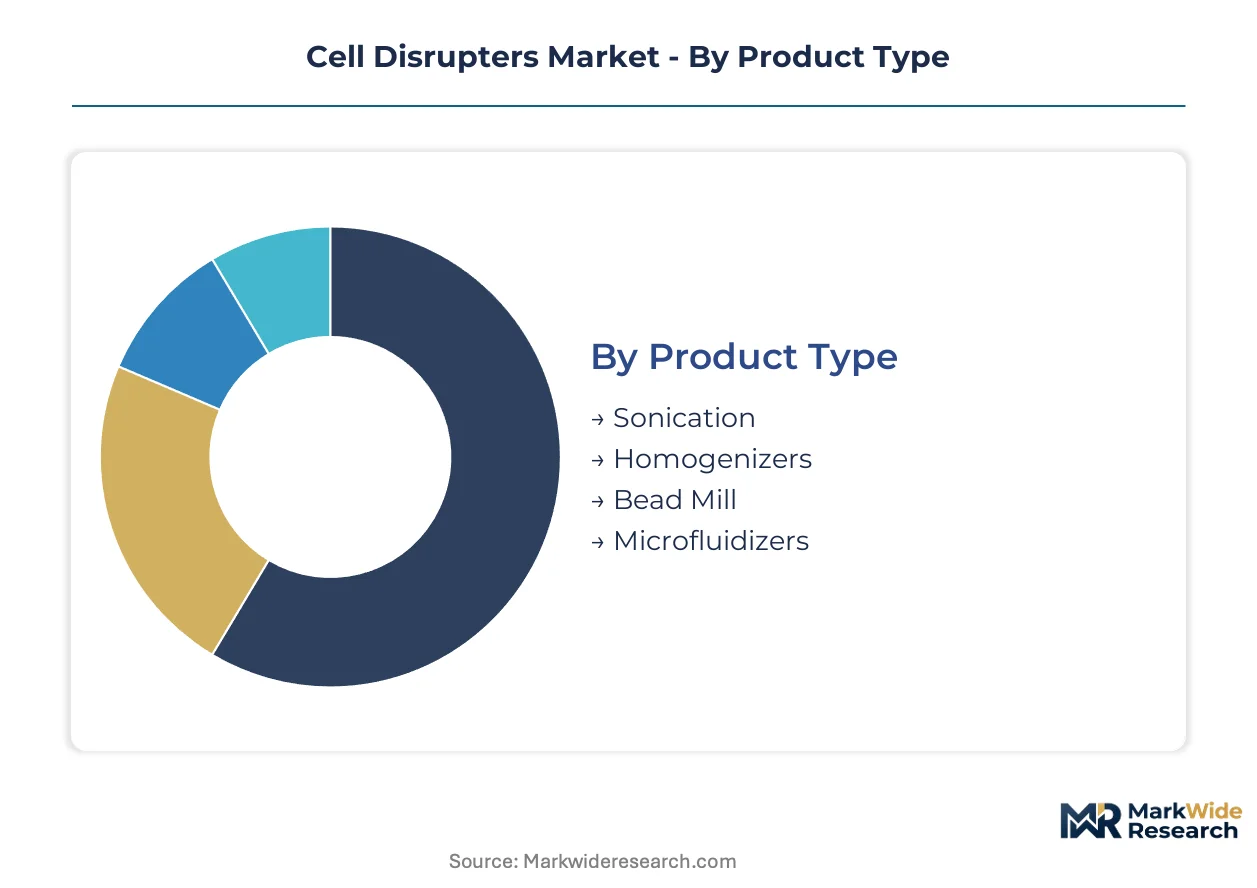
Cell disrupter procurement patterns diverge sharply across product architectures and end-use workflows. Equipment specifications, validation requirements, and consumables bundling economics create distinct margin pools that reward targeted positioning over broad portfolio coverage.
Product Type:
Margin concentration follows capital intensity and consumables lock-in, with premium pricing achievable where particle size precision gates downstream process yield.
- Sonication:Ultrasonic systems operating at 50-1500 W power density dominate academic and early-stage biotech installed bases due to protocol familiarity and lower capital barriers. Demand clusters in United States research corridors where FDA pre-submission studies require rapid cell lysis method development without GMP infrastructure investment.
- Homogenizers:High-pressure systems delivering up to 27000 psi anchor pharmaceutical manufacturing workflows for intracellular protein recovery. Germany's antibody production clusters and China's biologics CDMO expansion sustain replacement cycles as equipment reaches validated service life under cGMP documentation requirements.
- Bead Mill:Mechanical grinding platforms suit high-throughput bacterial lysis in industrial enzyme production. Food processors in clean-label ingredient supply chains favor bead milling for scalable cell wall disruption without chemical residuals.
- Microfluidizers:Microfluidic disruption commands premium positioning in nanoscale liposome manufacturing where coefficient of variation below 15% is mandatory. Gene therapy CDMOs in Boston and Basel now specify microfluidic protocols in technical purchasing agreements, compressing addressable share for conventional homogenizers.
Sonication holds installed capacity across education and exploratory research segments. Microfluidizers are rotating up the share rankings as lipid nanoparticle manufacturing scales for mRNA therapeutic delivery.
Application:
Volume distribution tracks biologics manufacturing expansion, with therapeutic production workflows absorbing disproportionate equipment qualification investment relative to discovery-stage applications.
- Biotechnology:Cell and gene therapy developers require disruption platforms compatible with sensitive viral vector and plasmid DNA recovery. United States coastal clusters and Swiss manufacturing hubs drive specification standards that cascade to contract manufacturing partners globally.
- Pharmaceutical:Active pharmaceutical ingredient production mandates FDA-validated equipment with electronic records compliance under 21 CFR Part 11. Replacement demand sustains as legacy systems fail qualification audits or reach end-of-validated-life documentation limits.
- Research Laboratories:Academic and government institutions prioritize capital accessibility and protocol flexibility over throughput optimization. Budget constraints favor sonication and bead mill configurations with minimal consumables dependency.
- Food Processing:Clean-label ingredient extraction protocols displace chemical lysis methods, opening enzymatic and mechanical disruption growth. European processors lead adoption under EFSA scrutiny of residual processing aids in finished ingredients.
Pharmaceutical applications command qualification premium pricing. Biotechnology is climbing the fastest as cell therapy manufacturing capacity expands.
Technology:
Process validation burden and downstream purification complexity determine technology selection, with mechanical methods dominating where regulatory documentation must demonstrate reproducible lysis efficiency.
- Mechanical Disruption:Physical force application through shear, impact, or pressure delivers consistent, scalable results with minimal batch-to-batch variation. High-pressure homogenization and microfluidics anchor pharmaceutical workflows where process analytical technology integration enables real-time lysis monitoring.
- Chemical Disruption:Detergent and solvent-based lysis retains niche positioning for membrane protein extraction where mechanical methods risk denaturation. Ion channel drug discovery programs at Merck KGaA and specialized CROs sustain demand for optimized detergent protocols.
- Enzymatic Disruption:Cell wall-degrading enzymes enable label-friendly extraction without harsh mechanical stress or chemical residuals. Food manufacturers adopt enzymatic methods to meet clean-label positioning requirements in European and North American consumer markets.
- Thermal Disruption:Heat-induced lysis serves specialized applications requiring simultaneous sterilization and cell rupture. Limited adoption reflects protein denaturation risks that constrain downstream recovery yields in therapeutic protein manufacturing.
Mechanical disruption retains pharmaceutical process validation dominance. Enzymatic methods are gaining share fastest in food processing clean-label transitions.
End User:
Procurement authority and budget cycle predictability segment the customer base, with contract research organizations rewiring demand patterns around consumables bundling and service contract flexibility.
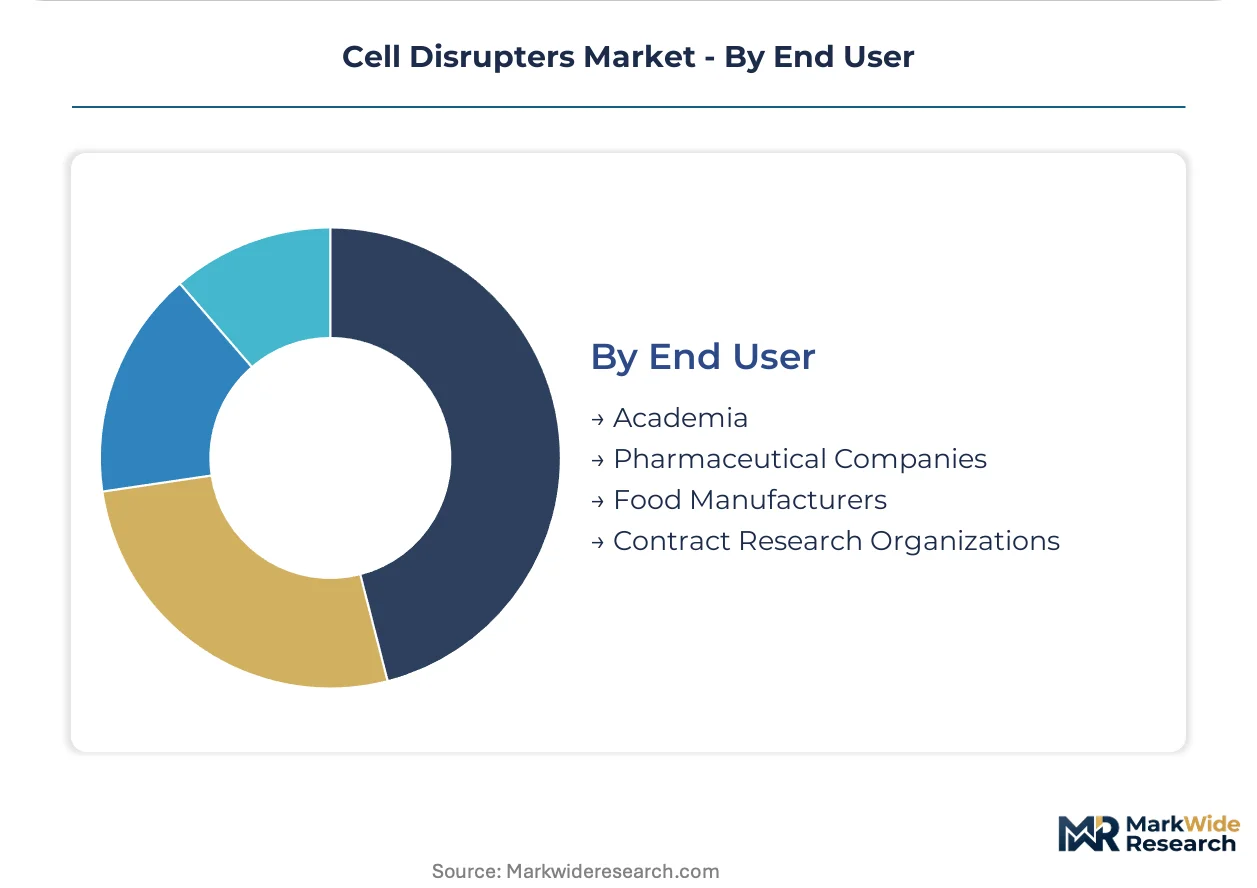
- Academia:University and government research institutions prioritize capital cost minimization and protocol publication compatibility. Thermo Fisher Scientific's consumables-to-instrument bundling captures recurring revenue despite limited equipment replacement frequency.
- Pharmaceutical Companies:In-house biologics manufacturers demand validated equipment with comprehensive qualification documentation and multi-year service agreements. FDA pre-approval inspection readiness dictates vendor selection and replacement timing.
- Food Manufacturers:Industrial processors seek scalable throughput with clean-label compliance certification. European and Chinese ingredient suppliers invest in enzymatic and mechanical platforms to replace chemical extraction methods under tightening consumer transparency expectations.
- Contract Research Organizations:Outsourced development specialists drive high-throughput screening workflow integration and reject multi-year maintenance contracts in favor of consumption-model service purchasing. Series B-funded cell therapy developers in San Diego and Cambridge accelerate this procurement pattern shift.
Pharmaceutical companies anchor equipment validation premium pricing. Contract research organizations are rotating up the share rankings as outsourced biologics development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision machining centers export high-pressure homogenizer components to United States biologics manufacturers, creating a transatlantic trade corridor that concentrates supply-side capacity in Central Europe while demand-side clusters expand across North American coastal metros.
United States
Cell therapy CDMOs in Boston and San Diego drive microfluidizer procurement for lipid nanoparticle manufacturing. FDA 21 CFR Part 11 compliance mandates force pharmaceutical manufacturers to replace legacy disruption equipment with validated, traceable systems. The Greater Boston biotech corridor now specifies microfluidic protocols in technical purchasing agreements for gene therapy applications.
Germany
Antibody production clusters in Bavaria and North Rhine-Westphalia sustain replacement cycles for high-pressure homogenizers reaching validated service life. EU MDR traceability requirements extend vendor onboarding cycles by 8-14 months, freezing spot procurement for therapeutic-use equipment. Stuttgart-area machining centers supply precision pump components to global homogenizer assemblers.
China
Biologics CDMO expansion in Shanghai and Suzhou concentrates demand for mechanical disruption platforms capable of consistent intracellular protein recovery. NMPA alignment with ICH quality guidelines accelerates equipment qualification documentation requirements. The Yangtze River Delta biomanufacturing hub now absorbs unit shipments once dominated by academic laboratories.
India
Contract development organizations in Hyderabad and Bengaluru lack scaled mechanical disruption capacity, creating positioning opportunities for equipment vendors with localized service networks. CDSCO manufacturing practice inspections tighten validation protocols for active pharmaceutical ingredient production. The Genome Valley biotech cluster drives specification standards that cascade to manufacturing partners.
Switzerland
Gene therapy developers in Basel anchor premium-tier microfluidizer demand for viral vector manufacturing workflows. Swissmedic quality risk management guidelines converge with FDA process analytical technology frameworks, forcing equipment vendors to harmonize qualification documentation. The Basel biopharma corridor specifies dual-compliant validation packages in multinational procurement agreements.
Cell Disrupters Market Competitive Landscape
Player mix skews toward diversified life science conglomerates with consumables-to-instrument bundling capabilities. The competitive structure concentrates around three strategic archetypes: integrated platform vendors leveraging centrifugation-disruption workflow unification, precision component specialists anchoring high-pressure homogenizer supply chains, and enzymatic protocol developers serving clean-label extraction niches. Dominant competitive moves include M&A-driven portfolio diversification into adjacent sample preparation workflows and geographic expansion through localized service network deployment in emerging biologics manufacturing clusters.
Among diversified life science conglomerates, Thermo Fisher Scientific and Beckman Coulter exemplify the integrated platform archetype, while Merck KGaA occupies a position within the specialized reagent and protocol development tier. These three entities represent distinct strategic postures: consumables bundling for recurring revenue capture, centrifugation-integrated disruption for workflow step reduction, and membrane protein extraction optimization for ion channel drug discovery applications. Their collective positioning illustrates how vendor selection criteria fragment across end-user procurement priorities—high-throughput screening workflows versus GMP validation readiness versus discovery-stage protocol flexibility.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Beckman Coulter |
| Merck KGaA |
| Bio-Rad Laboratories |
| QIAGEN |
| Analytik Jena |
| Hielscher Ultrasonics |
| Parr Instrument Company |
| Stansted Fluidic Systems |
| Others |
Pricing and Supply Chain Analysis
Twelve-to-eighteen-month vendor onboarding cycles for EU MDR-qualifiable equipment concentrate pricing power among incumbent suppliers with pre-validated documentation libraries, while spot procurement freezes force buyers into premium service contracts that embed multi-year consumables lock-in.
Pricing Analysis
Next-generation microfluidizer platforms command 40-60% capital premiums over incumbent high-pressure homogenizer lines, while legacy ultrasonic systems face commoditization pressure from Chinese manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated pharmaceutical-grade equipment from research-use configurations. Cost compression in the sonication tier is intensifying because titanium alloy probe replacement cycles shorten under continuous bioprocessing loads. Academic laboratories exhibit highest price sensitivity, while gene therapy CDMOs absorb premium positioning for particle-size precision.
Supply Chain Analysis
Stuttgart-area precision machining centers anchor high-pressure homogenizer pump component supply, creating single-source vulnerability for equipment assemblers dependent on German and Swiss metallurgical tolerances. Stainless steel bar stock and precision ceramic plungers draw from Central European specialty foundries. Logistics chokepoint risk concentrates in Rhine corridor freight congestion and extended customs clearance for ISO 13485-certified subassemblies. Distribution runs through authorized service networks rather than direct OEM relationships, with regional stocking locations in Boston, Basel, and Singapore determining lead-time variability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware development capabilities for in-line process analytical technology integration represent the critical skill gap separating viable suppliers from equipment vendors facing displacement by integrated platform competitors.
For Market Incumbents: Fortify qualification documentation libraries to compress EU MDR onboarding cycles for multinational biologics manufacturers, while embedding consumables bundling into service contracts to preempt pay-per-use financing challengers. Beckman Coulter's centrifugation-disruption integration sets the defensive benchmark; standalone equipment architectures without workflow unification face high-throughput screening account erosion. For New Entrants and Emerging Players: Localized technical service networks in Hyderabad and Bengaluru address the capability vacuum constraining Indian CDMO scale-up, offering first-mover positioning before incumbent service infrastructure deployment. Target enzymatic disruption protocol development for European clean-label food processors seeking chemical-free extraction certification, leveraging label-friendly positioning as the go-to-market wedge against mechanical-equipment incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microfluidizer manufacturing as gene therapy CDMOs specify dual-compliant FDA-EMA validation packages, favoring acquisition targets with pre-harmonized documentation libraries over greenfield certification investments. Watch for FDA pre-approval inspection clearance velocity as the inflection signal distinguishing compliant suppliers from documentation-lagged competitors.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Pharmaceutical OEM procurement lists now exclude uncertified suppliers, rewarding early compliance with captive supplier status. |
| Microfluidizer Platform Integration | Gene therapy CDMOs in Boston and Basel specify microfluidic protocols, compressing conventional homogenizer addressable share. |
| Localized Service Network Deployment | Hyderabad and Bengaluru CDMOs lack scaled mechanical disruption capacity, creating first-mover positioning for vendors with regional technical presence. |
| Consumables-to-Instrument Bundling | High-throughput screening workflows favor recurring revenue capture over standalone capital equipment transactions. |
| Process Analytical Technology Firmware Development | Biopharma customers demand real-time lysis monitoring via in-line turbidity sensors, requiring capabilities few vendors possess. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA qualification guidance documents, and ISO certification registries. Interviews with bioprocess engineering directors, GMP validation specialists, CDMO procurement managers, and aftermarket service heads informed equipment replacement cycle assumptions. Secondary sources include SEC 10-K equipment revenue disclosures, customs trade data for precision pump components, and hospital procurement database extracts. Bottom-up unit shipment modeling triangulates against top-down biologics manufacturing capacity expansion estimates.
Segmentation dimensions modeled span product architecture, application workflow, technology type, and end-user procurement authority across the projection horizon. CAGRs derive from equipment replacement frequency under cGMP documentation requirements, biologics manufacturing cluster expansion rates, and regulatory compliance-driven upgrade cycles. Forecast inputs incorporate NMPA-ICH alignment timelines for Chinese CDMO qualification and EU MDR traceability mandate enforcement patterns.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11 and EU MDR regimes; material policy shifts would require re-modeling. Supply-side concentration in German machining centers, probe degradation rates under continuous operation, and service contract unbundling velocity represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Global Cell Signaling Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Needle Based Biopsy Guns Market
Biomedical Technology
Bioprocess Technology Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
Cell Isolation Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Strand Displacement Amplicon (SDA) Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Glycomics Market
Biomedical Technology
Global Cell Counting Market
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market