
 Protein Expression Technology Market | 2026-2036
Protein Expression Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Protein Expression Technology Market Outlook
The capital-intensity divergence between GMP-grade mammalian system providers and research-scale bacterial kit suppliers is redrawing competitive boundaries in protein expression. Thermo Fisher Scientific leverages its integrated consumables-instrument-service ecosystem to sustain premium positioning across academic and pharmaceutical accounts. Lonza Group AG anchors its competitive profile through contract manufacturing scale, while New England Biolabs specializes in molecular biology reagents that feed upstream expression workflows.
Protein expression technology encompasses the biological systems, vectors, and protocols used to synthesize recombinant proteins in host cells, typically achieving yields from micrograms to grams per liter depending on the platform and optimization level. Its primary commercial purpose is to manufacture therapeutic proteins, industrial enzymes, and diagnostic reagents at scales and purities required for regulatory approval and commercial sale. Mammalian expression systems command the highest value per liter due to their human-compatible glycosylation patterns for biopharmaceutical production, while bacterial systems retain cost leadership in industrial enzyme manufacturing where post-translational modifications remain minimal. Research applications represent a stable volume base, though contract research organizations are shifting procurement toward expression-as-a-service models that bundle technology access with manufacturing execution.
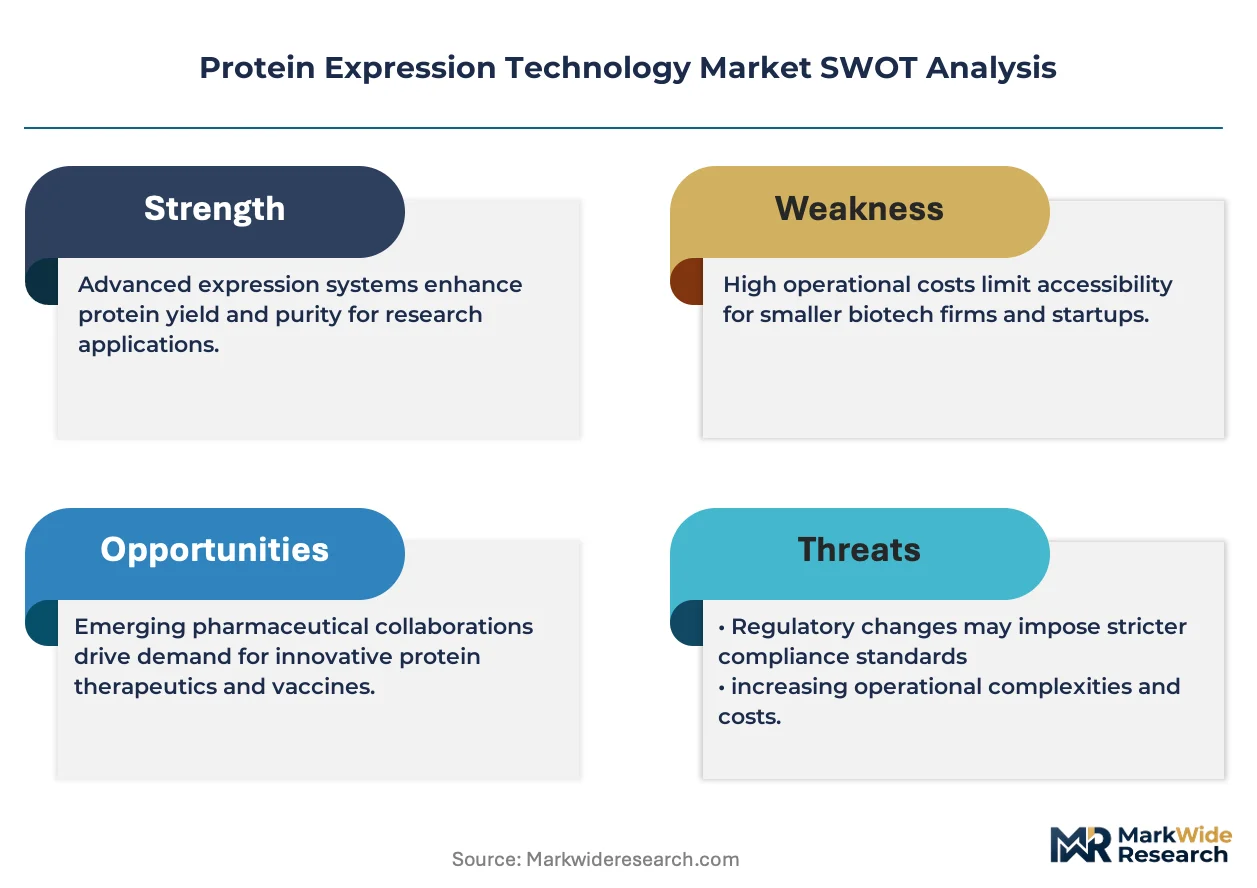
The FDA's biosimilar guidance and EMA's quality requirements for biotechnology-derived proteins shape platform selection and validation protocols for companies seeking commercial approval in the United States and European Union. ISO 13485 and GMP standards further constrain market entry for diagnostic reagent and therapeutic protein suppliers, favoring vendors with established quality management systems. Stakeholders must monitor how gene editing advances, particularly CRISPR-optimized host cell lines, alter the capability requirements and capital thresholds for competitive participation.
Market Dynamics
The FDA's updated biosimilar guidance is compressing validation timelines and forcing biopharmaceutical manufacturers toward GMP-compliant mammalian expression platforms with documented glycosylation fidelity. This regulatory pressure is redrawing capital allocation between research-scale bacterial kit suppliers and production-grade contract manufacturing organizations.
Growth Catalysts
- EMA Quality Guidelines:The European Medicines Agency's biotechnology-derived protein standards are accelerating platform upgrades among contract research organizations seeking commercial approval pathways in the European Union.
- CRISPR-Optimized Host Lines:Gene editing advances in Chinese hamster ovary cells are expanding yield ceilings for complex therapeutic antibodies previously constrained by glycosylation pattern inconsistencies.
- Biopharmaceutical Manufacturing:United States-based biopharmaceutical manufacturers are scaling mammalian system capacity to address the therapeutic protein pipeline concentrated in oncology and autoimmune indications.
Market Restraints
- Serum Price Volatility:Fetal bovine serum supply concentration in Australia and New Zealand creates input cost instability for adherent mammalian culture protocols dependent on animal-derived growth factors.
- GMP Facility Capital Intensity:Construction and qualification of GMP-grade cleanroom suites for mammalian expression requires capital deployment that excludes mid-scale entrants from commercial therapeutic protein supply.
- Bacterial System Substitution:Escherichia coli platforms retain cost leadership in industrial enzyme manufacturing where post-translational modification requirements remain minimal, compressing addressable market for higher-cost mammalian alternatives.
Strategic Opportunities
- Expression-as-a-Service Models:Contract research organizations in the United States are bundling technology access with manufacturing execution, capturing value previously retained by in-house biopharmaceutical facilities.
- ISO 13485 Diagnostic Reagents:In vitro diagnostic manufacturers face unmet demand for recombinant protein standards with certified lot-to-lot consistency, creating white space for qualified expression platform providers.
- Continuous Perfusion Systems:Integration of alternating tangential flow filtration with single-use bioreactors is enabling real-time product harvest that improves volumetric productivity in mammalian cell culture.
Industry Challenges
- Cell Line Development Expertise:The specialized skill set required for stable transfectant selection and clone screening creates recruitment bottlenecks that delay project initiation timelines for emerging contract manufacturers.
- Multi-Attribute Method Validation:Implementation of mass spectrometry-based glycan profiling as a release assay requires analytical chemistry capabilities that strain quality control infrastructure at scaling facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein Expression Technology Market |
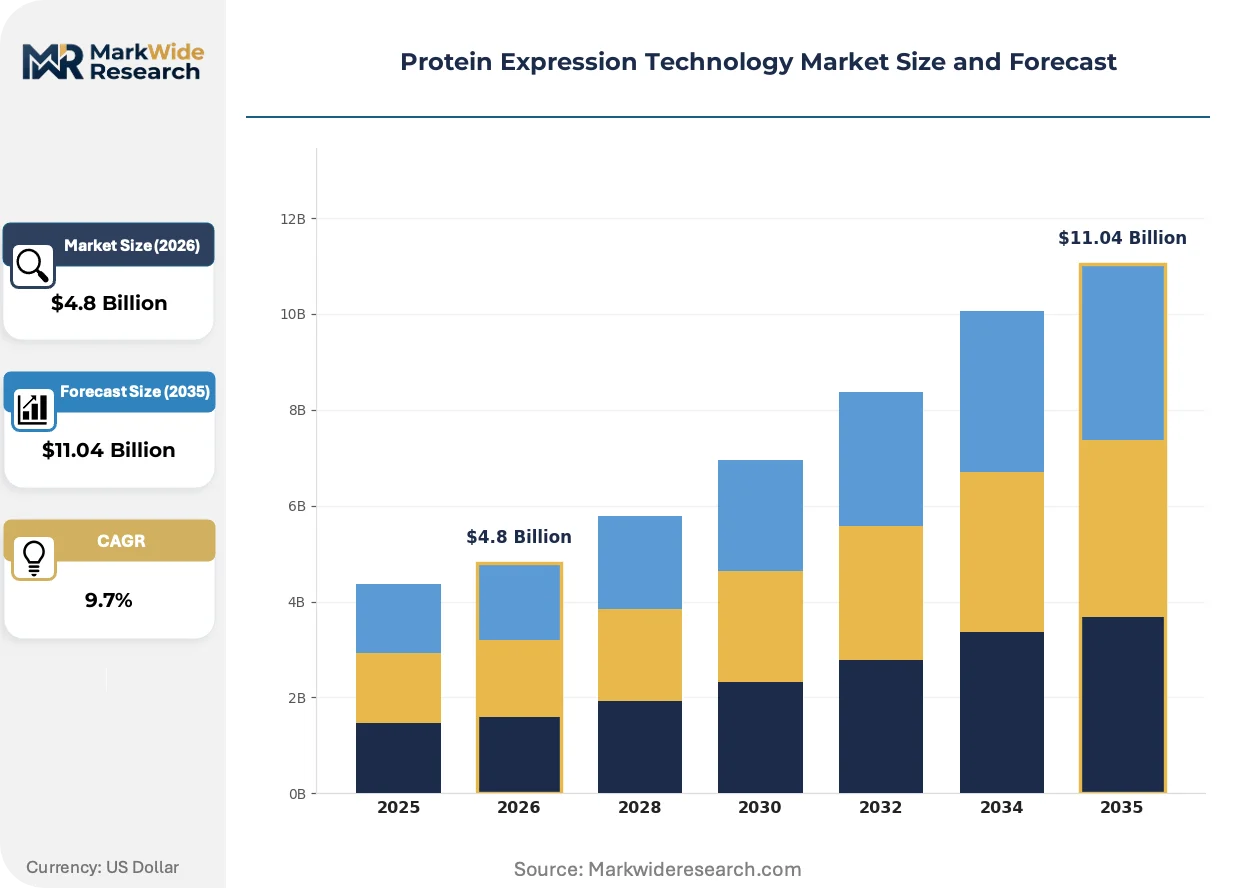
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
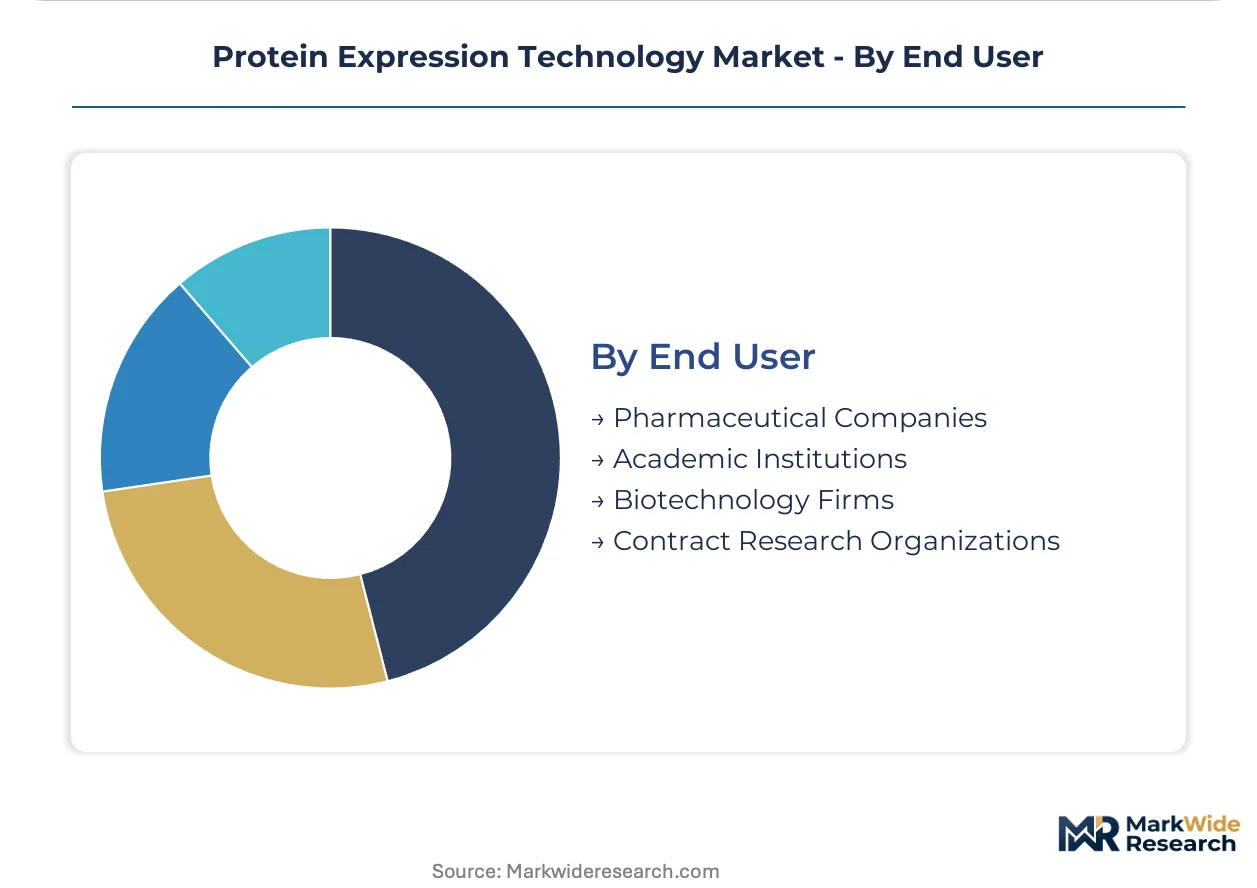
| Segmentation | Product Type: Bacterial Expression Systems, Yeast Expression Systems, Mammalian Expression Systems, Insect Expression Systems Application: Biopharmaceutical Production, Industrial Enzymes, Research Applications, Diagnostic Reagents Technology: Recombinant DNA Technology, Transfection Techniques, Gene Editing, Protein Purification End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Contract Research Organizations |
| Companies Covered | Bio-Rad Laboratories, Inc., Takara Bio Inc., Thermo Fisher Scientific Inc., QIAGEN, Lonza Group AG, Merck KGaA, Promega Corporation, New England Biolabs, Agilent Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein Expression Technology Market Strategic Shifts
Gene editing tools and single-use manufacturing hardware are converging to compress development timelines and shift competitive advantage toward platform-integrated service providers rather than discrete reagent vendors.
CRISPR-Cas9 engineered host cell lines are fragmenting the traditional yield-versus-quality tradeoff in mammalian expression. Biopharmaceutical process development groups are adopting these lines at accelerating pace for complex antibody modalities. The technology is fragmenting market share between legacy stable transfection workflows and rapid genome-edited alternatives that compress cell line development from months to weeks.
REACH regulation in the European Union is tightening chemical substance registration requirements for expression media components and downstream processing reagents. Industrial enzyme manufacturers are reformulating proprietary media formulations to eliminate substances of very high concern. Mammalian system suppliers targeting European therapeutic protein markets are accelerating supply chain audits to document compliance with evolving chemical safety frameworks.
Academic and small biopharma buyers are consolidating purchasing through centralized procurement platforms that bundle expression vectors, competent cells, and technical support into annual subscription contracts. Traditional catalog distributors face margin compression as these platforms capture volume previously fragmented across multiple suppliers. The United States research market exhibits the most visible concentration, with major university systems negotiating enterprise pricing for integrated reagent-service packages.
Protein Expression Technology Market Segmentation

Segmentation in protein expression technology reveals how substitution pressures and regulatory requirements reshape procurement patterns across distinct technical platforms. Understanding these divisions exposes where capital concentrates and which modalities face displacement risk from emerging alternatives.
Product Type:
Bacterial systems face the most acute substitution pressure from mammalian platforms as biopharmaceutical glycosylation requirements tighten, while insect and yeast alternatives occupy narrowing technical niches.
- Mammalian Expression Systems:Chinese hamster ovary and human embryonic kidney cell lines deliver human-compatible glycosylation patterns essential for therapeutic antibody approval. Demand concentrates among United States biopharmaceutical manufacturers scaling capacity for oncology and autoimmune pipelines, with FDA biosimilar guidance accelerating GMP-compliant platform adoption.
- Bacterial Expression Systems:Escherichia coli platforms dominate industrial enzyme manufacturing where post-translational modifications remain minimal and cost efficiency governs procurement. United States contract manufacturers retain volume leadership in research-grade bacterial kits, though margin compression intensifies from centralized academic purchasing platforms.
- Yeast Expression Systems:Saccharomyces cerevisiae and Pichia pastoris offer intermediate glycosylation capabilities for vaccines and non-antibody biologics.
- Insect Expression Systems:Baculovirus-mediated expression in Spodoptera frugiperda cells serves specialized structural biology and vaccine applications with limited commercial scale.
Bacterial systems anchor the volume base while mammalian platforms gain share at the steepest rate.
Application:
Cost tier differentiation separates commodity industrial enzyme production from premium therapeutic protein manufacturing, with diagnostic reagents emerging as a margin-sensitive intermediate category.
- Biopharmaceutical Production:Complex monoclonal antibodies and fusion proteins require mammalian hosts with documented glycosylation fidelity for regulatory submission. United States and European Union manufacturers concentrate investment here, with EMA quality guidelines and FDA biosimilar standards enforcing platform validation rigor.
- Research Applications:Academic laboratories and discovery-stage biotechs consume microgram-to-gram quantities across multiple host systems for target validation and assay development.
- Industrial Enzymes:Food processing, detergent, and biofuel applications prioritize bacterial platform cost leadership where minimal modification suffices.
- Diagnostic Reagents:ISO 13485-certified recombinant protein standards face unmet demand for lot-to-lot consistency in in vitro diagnostic manufacturing.
Industrial enzymes represent the highest-volume application while biopharmaceutical production commands the steepest expansion trajectory.
Technology:
Maturity gradients separate established recombinant DNA workflows from emerging gene editing capabilities that compress development timelines and alter competitive requirements.
- Gene Editing:CRISPR-Cas9 engineered host cell lines fragment traditional yield-versus-quality tradeoffs by enabling rapid genome modification in mammalian systems. United States process development groups adopt these tools at accelerating pace for complex antibody modalities.
- Recombinant DNA Technology:Plasmid design, restriction enzyme cloning, and vector construction remain foundational across all expression platforms.
- Transfection Techniques:Electroporation, lipid-based delivery, and viral transduction methods determine stable clone generation efficiency.
- Protein Purification:Chromatography, filtration, and precipitation workflows downstream of expression govern final product quality and yield recovery.
Recombinant DNA technology anchors current practice while gene editing gains adoption most rapidly.
End User:
Customer type dictates procurement sophistication, with pharmaceutical companies demanding integrated service models and academic institutions consolidating through enterprise purchasing platforms.
- Pharmaceutical Companies:Large-scale biopharmaceutical manufacturers prioritize GMP-compliant mammalian capacity with documented quality systems for commercial therapeutic production. United States-based firms drive capacity expansion concentrated in oncology and autoimmune indications.
- Contract Research Organizations:United States CROs are bundling technology access with manufacturing execution, capturing value previously retained by in-house biopharmaceutical facilities through expression-as-a-service models.
- Academic Institutions:University systems negotiate centralized procurement for bacterial kits and research-grade reagents, compressing margins for traditional catalog distributors.
- Biotechnology Firms:Emerging biotechs outsource expression workflows to access specialized cell line development expertise without capital-intensive facility investment.
Pharmaceutical companies dominate value capture while contract research organizations expand most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net protein expression technology trade flows toward jurisdictions with GMP manufacturing infrastructure and biosimilar approval pathways. The United States maintains import dependence on European consumables while exporting contract manufacturing services. Asian production clusters are capturing bacterial system assembly and research-grade reagent manufacturing.
United States
FDA biosimilar guidance compresses validation timelines for mammalian expression platforms serving oncology and autoimmune therapeutic pipelines. The agency's quality standards enforce documented glycosylation fidelity for commercial approval. Greater Boston and San Francisco Bay Area biotech clusters concentrate CRISPR-optimized host cell line development for complex antibody production.
Germany
EMA biotechnology-derived protein standards drive platform upgrades among contract research organizations seeking European Union commercial pathways. REACH regulation tightens chemical substance registration for expression media components and downstream processing reagents. Rhine-Main and Upper Bavaria industrial zones anchor GMP-compliant manufacturing capacity for diagnostic reagent and therapeutic protein supply.
China
NMPA biopharmaceutical approval reforms accelerate investment in mammalian system capacity for domestic therapeutic antibody production. The country's national pharmaceutical regulator enforces GMP alignment with international standards for export-oriented facilities. Yangtze River Delta biotech parks concentrate gene editing tool development and single-use bioreactor assembly for regional supply.
Switzerland
Swissmedic quality requirements for biotechnology-derived proteins attract contract manufacturing investment from global biopharmaceutical firms. Chemical safety frameworks govern expression media formulation and supply chain documentation for European market access. Basel and Zurich life science clusters integrate CRISPR-engineered host lines into commercial therapeutic protein workflows.
India
CDSCO biosimilar guidelines create demand for GMP-compliant mammalian expression capacity serving domestic and export markets. The national pharmaceutical regulator harmonizes inspection protocols with WHO standards for prequalified supplier status. Hyderabad and Bengaluru biotech corridors expand bacterial system manufacturing for industrial enzyme and research reagent exports.
Protein Expression Technology Market Competitive Environment
Concentration sits with diversified life science conglomerates that bundle consumables, instrumentation, and services into integrated procurement contracts. Mid-scale contract manufacturers occupy a secondary tier through GMP facility specialization. Three archetypes dominate: platform-integrated conglomerates, GMP-focused contract manufacturers, and molecular biology reagent specialists. Competitive dynamics center on strategic partnerships for gene editing tool integration and capacity expansion in mammalian cell culture suites.
Among platform-integrated conglomerates, Thermo Fisher Scientific Inc. exemplifies the consumables-instrument-service ecosystem model. Lonza Group AG anchors the GMP contract manufacturing archetype through European facility networks. New England Biolabs occupies the molecular biology reagent specialist position with upstream workflow components. These three represent distinct competitive vectors rather than direct substitution threats.
| Leading Market Players |
|---|
| Bio-Rad Laboratories, Inc. |
| Takara Bio Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Lonza Group AG |
| Merck KGaA |
| Promega Corporation |
| New England Biolabs |
| Agilent Technologies, Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA biosimilar guidance and GMP certification tiers simultaneously gate supply qualification and stratify pricing power across mammalian expression platforms. Buyers without documented glycosylation fidelity face exclusion from commercial therapeutic protein procurement, while certified suppliers capture premium positioning in United States biopharmaceutical manufacturing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in protein expression technology. Premium tiers attach to GMP-compliant mammalian systems with ISO 13485 certification and validated cell line documentation, while economy tiers serve research-grade bacterial kits sold through centralized academic procurement platforms. Cost compression in the bacterial research segment is intensifying because university systems consolidate annual subscription contracts, squeezing margins for traditional catalog distributors. Contract research organizations exhibit the lowest price sensitivity due to downstream value capture in expression-as-a-service models, whereas academic laboratories negotiate aggressively on per-unit reagent costs.
Supply Chain Analysis
Strategic stockpiling of fetal bovine serum dominates inventory strategy among adherent mammalian culture protocols, given supply concentration in Australia and New Zealand. Manufacturing capacity clusters in the United States, Germany, and Switzerland for GMP-compliant therapeutic protein production, while China and India anchor bacterial system assembly and research-grade reagent manufacturing. Raw material dependencies center on fetal bovine serum, chemically defined media formulations, and single-use bioreactor components. Single-source vulnerability in serum supply creates exposure to geopolitical disruption and animal health incidents. Distribution runs through direct sales teams for pharmaceutical accounts and consolidated procurement platforms for academic buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent protein expression technology providers face substitution defense against CRISPR-optimized host cell lines that compress traditional cell line development timelines from months to weeks.
For Market Incumbents: Shield GMP facility investments by accelerating CRISPR-engineered host line integration into commercial workflows before gene editing specialists capture platform share. Prioritize backward integration into chemically defined media manufacturing to reduce fetal bovine serum exposure. Lock in multi-year expression-as-a-service contracts with United States biotechnology firms to defend against emerging contract manufacturers offering compressed development timelines. For New Entrants and Emerging Players: Lead with CRISPR-optimized Chinese hamster ovary cell line development services targeting mid-stage biotechnology firms lacking in-house genome engineering capabilities. White space concentrates in ISO 13485-certified diagnostic reagent manufacturing, where lot-to-lot consistency requirements exceed current supplier capacity. A go-to-market angle bundling rapid cell line generation with regulatory documentation support penetrates faster than discrete reagent sales. For Investors and Strategic Acquirers: FDA biosimilar guidance reshapes the acquisition landscape by rewarding GMP-compliant mammalian capacity with validated quality systems over research-scale bacterial kit portfolios. Long-term viability favors contract manufacturing organizations with demonstrated glycosylation fidelity and established pharmaceutical relationships. The signal to watch is CRISPR-tool licensing penetration rates among incumbent platform providers as an indicator of technological obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Expansion | United States biopharmaceutical manufacturers scale mammalian capacity for oncology and autoimmune pipelines. |
| CRISPR Host Line Integration | Gene editing specialists compress cell line development timelines for complex antibody modalities. |
| Expression-as-a-Service Launch | Contract research organizations bundle technology access with manufacturing execution to capture outsourced value. |
| ISO 13485 Certification Investment | Diagnostic reagent suppliers address unmet demand for certified lot-to-lot consistency in in vitro manufacturing. |
| Continuous Perfusion System Adoption | Alternating tangential flow filtration integration improves volumetric productivity in mammalian cell culture. |
Study Parameters
A spread of perspectives from biopharmaceutical process development executives, contract manufacturing quality leads, academic procurement directors, and diagnostic reagent regulatory affairs specialists converged on the working assumptions in this study. Primary interviews combined with secondary validation from FDA biosimilar guidance documents, EMA biotechnology-derived protein standards, ClinicalTrials.gov therapeutic antibody pipelines, and SEC filings from listed life science conglomerates. Bottom-up sizing of expression platform installations triangulated against top-down therapeutic protein production forecasts across the analysis window.
Segmentation dimensions modeled include expression system type, application category, end-user archetype, and regional regulatory cluster. CAGRs derived from installed base growth rates, capacity utilization trends, and pricing trajectory assumptions across the projection horizon. Forecast inputs incorporated gene editing tool adoption curves, GMP facility construction pipelines, and centralized academic procurement platform penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA enforcement of glycosylation fidelity standards would require recalibration. Forecasts reflect assumptions regarding serum supply stability, CRISPR regulatory clarity, and pharmaceutical outsourcing propensity. Revision becomes warranted when gene editing platform cost curves cross traditional stable transfection economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Orthobiological Products Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
Global Synthetic Biosensors Market
Biomedical Technology
Spine Biologics Market
Biomedical Technology
Reverse Transcriptase Enzymes Market
Biomedical Technology
Particle-Enhanced Turbidimetric Immunoassays Market
Biomedical Technology
Global Peptide Microarray Market
Biomedical Technology
Handheld DNA Reader Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Global Molecular Biosensors Market