
 Orthobiological Products Market | 2026-2036
Orthobiological Products Market Size, Share, and Industry Trends Forecast 2026-2036
Orthobiological Products Market Analytics
Trained cell-processing technicians is unwinding capacity constraints across manufacturing networks. Stryker Corporation leverages in-house biologics processing to sustain supply chain control in North American joint reconstruction. Zimmer Biomet anchors its position through concentrated R&D spending on synthetic bone graft matrices. Arthrex competes by dominating arthroscopic delivery systems that integrate biologic payloads.
Orthobiological products comprise implantable or injectable materials derived from human, animal, or synthetic sources that stimulate or scaffold bone, cartilage, or soft tissue repair, typically sterilized to SAL 10^-6 and characterized by porosity exceeding 50% to permit vascular infiltration. Bone grafts and bone substitutes command the largest revenue share due to entrenched surgeon familiarity and established reimbursement codes, while stem cell therapy represents the fastest-expanding category as regulatory clarity around minimal manipulation thresholds improves. Tissue engineering applications in cartilage regeneration attract premium pricing where autologous chondrocyte implantation protocols demonstrate durable clinical outcomes.
FDA 21 CFR Part 1271, EU Medical Device Regulation (MDR), and ISO 10993 biocompatibility testing frameworks collectively determine market access timelines and product classification pathways across major commercial jurisdictions. These standards elevate barriers for novel allogeneic therapies while accelerating 510(k) clearance for demineralized bone matrix formulations with predicate device histories. Stakeholders must monitor evolving minimal manipulation interpretations and emerging good tissue practice enforcement patterns to calibrate portfolio development priorities.
Market Dynamics
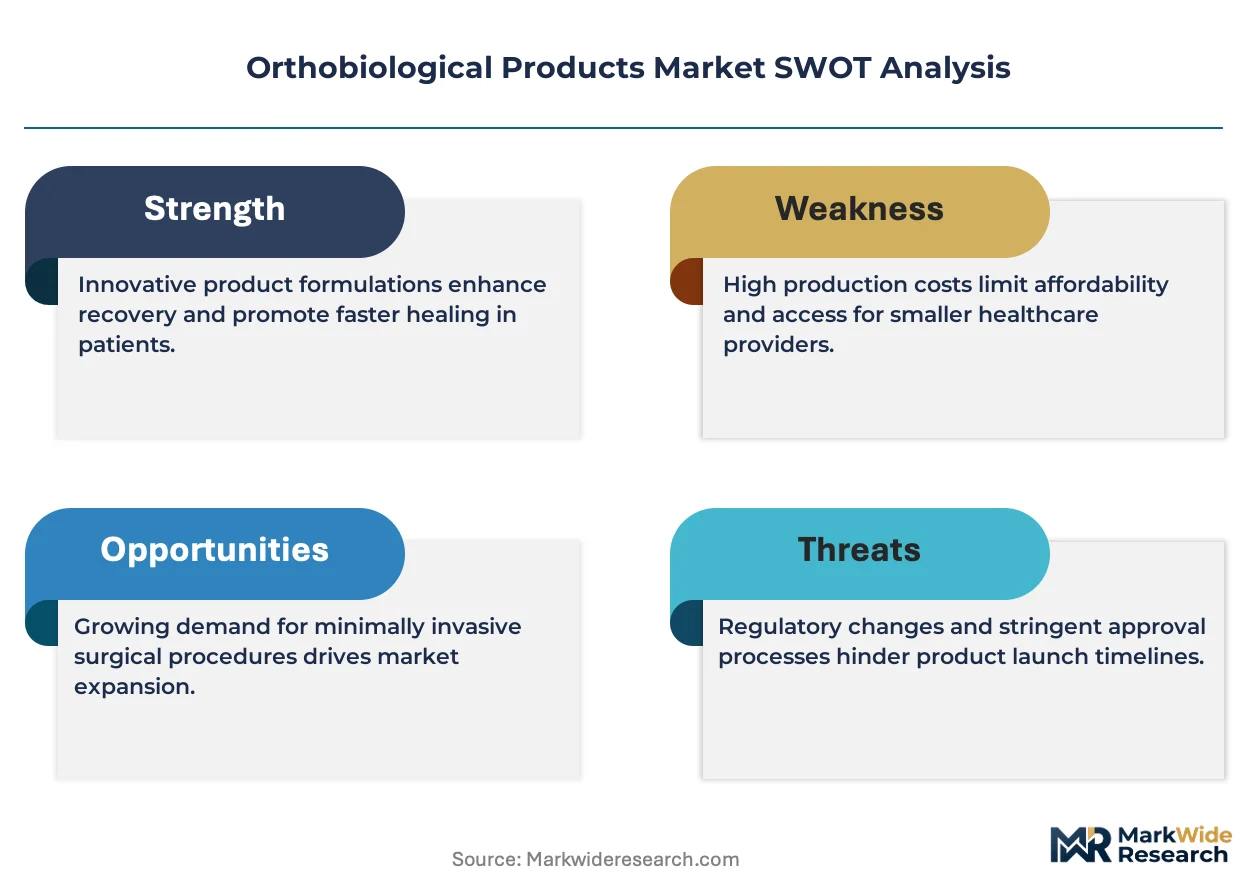
Cell-based therapy manufacturing networks face acute bottlenecks as FDA 21 CFR Part 1271 enforcement tightens around minimal manipulation thresholds, forcing processors to revalidate entire supply chains or surrender product classification advantages.
Growth Catalysts
- Spine Surgery Volume Concentration:Germany's aging surgical population drives concentrated demand for demineralized bone matrix and synthetic grafts in lumbar fusion procedures.
- EU Medical Device Regulation Clarity:MDR Article 117 transitional provisions now permit grandfathered orthobiologics to maintain market access while novel submissions face predictable review timelines.
- Arthroscopic Delivery Integration:Single-portal biologic injection systems reduce operative time and graft contamination risk in sports medicine applications.
Market Restraints
- Allogeneic Tissue Supply Concentration:US tissue bank networks depend on five dominant recovery organizations, creating single-source vulnerability for demineralized bone matrix raw material.
- Autologous Harvest Cost Structure:Iliac crest bone graft harvesting adds operative time and postoperative morbidity that synthetic alternatives increasingly avoid.
- ISO 10993 Testing Burden:Extended biocompatibility study timelines for novel xenogeneic scaffolds delay 510(k) submissions by 18-24 months versus predicate devices.
Strategic Opportunities
- Cartilage Regeneration Protocols:Autologous chondrocyte implantation with collagen membrane fixation commands premium reimbursement in sports medicine centers.
- Point-of-Care Cell Processing:Closed-system centrifuge and concentration devices enable same-day bone marrow aspirate concentrate preparation in ambulatory surgical facilities.
- India CDSCO Pathway Expansion:Recent medical device rules amendments create accelerated registration tracks for orthobiologics with US FDA or EU MDR approvals.
Industry Challenges
- Trained Technician Scarcity:Aseptic cell processing and cryopreservation protocols require specialized certification that academic programs currently undersupply.
- Good Tissue Practice Compliance:FDA inspection frequency for human cell and tissue establishments has intensified, exposing documentation gaps in smaller processors.
- Supply Chain Cold-Chain Integrity:Viable cell therapies demand uninterrupted liquid nitrogen storage that rural distribution networks struggle to guarantee.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthobiological Products Market |
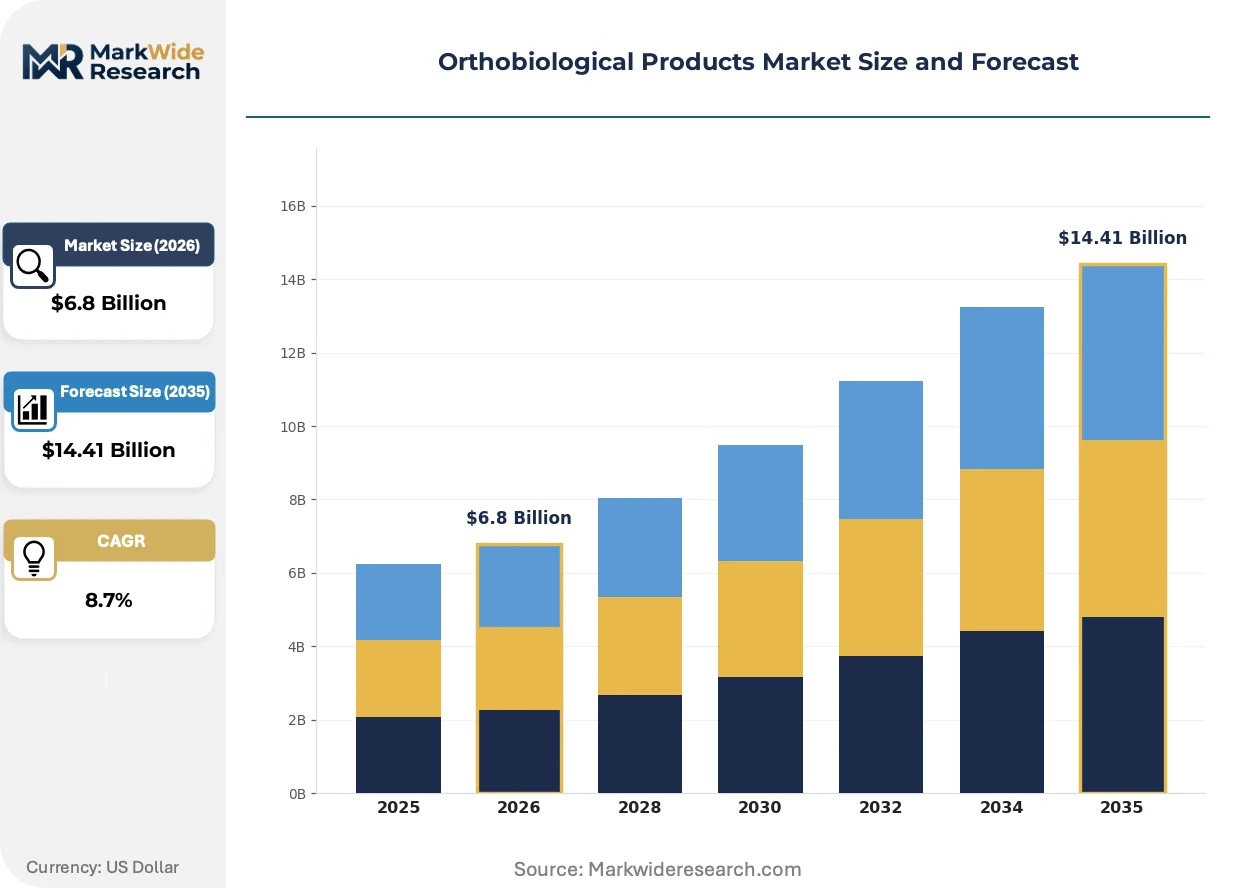
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Grafts, Bone Substitutes, Cartilage Regeneration, Stem Cell Therapy End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Research Institutions Application: Joint Reconstruction, Spine Surgery, Fracture Repair, Soft Tissue Repair Technology: 3D Bioprinting, Nanotechnology, Tissue Engineering, Gene Therapy |
| Companies Covered | Medtronic, Zimmer Biomet, Stryker Corporation, DePuy Synthes, Arthrex, Bioventus, Globus Medical, Orthofix Medical, Anika Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthobiological Products Market Evolving Landscape
Three convergent forces reshape competitive positioning: synthetic matrices erode autograft dependence, regulatory frameworks stratify by manipulation threshold, and procurement authority consolidates within integrated delivery networks.
Synthetic ceramic and polymer composite scaffolds with engineered porosity exceeding 70% now dominate spinal fusion applications. Academic medical centers and high-volume orthopedic groups have accelerated adoption beyond historical skepticism toward non-biological alternatives. This material transition is supplanting traditional iliac crest harvest protocols and compressing operative logistics across North American joint reconstruction.
EU Medical Device Regulation recast obligations for orthobiological products previously regulated as pharmaceuticals, creating dual classification complexity. Manufacturers must now navigate notified body conformity assessment for scaffold structural components alongside tissue establishment licensing for biological elements. German spine surgery centers report the most pronounced compliance adaptation burden due to concentrated allograft utilization.
Hospital purchasing committees now consolidate orthobiologic procurement through sole-source agreements with integrated device-biologic suppliers. Independent distributors and tissue bank direct sales forces lose shelf access as health systems prioritize supply chain simplification. This concentration pattern appears most advanced in United States metropolitan markets where accountable care organization penetration exceeds 40% of covered lives.
Orthobiological Products Market Segmentation
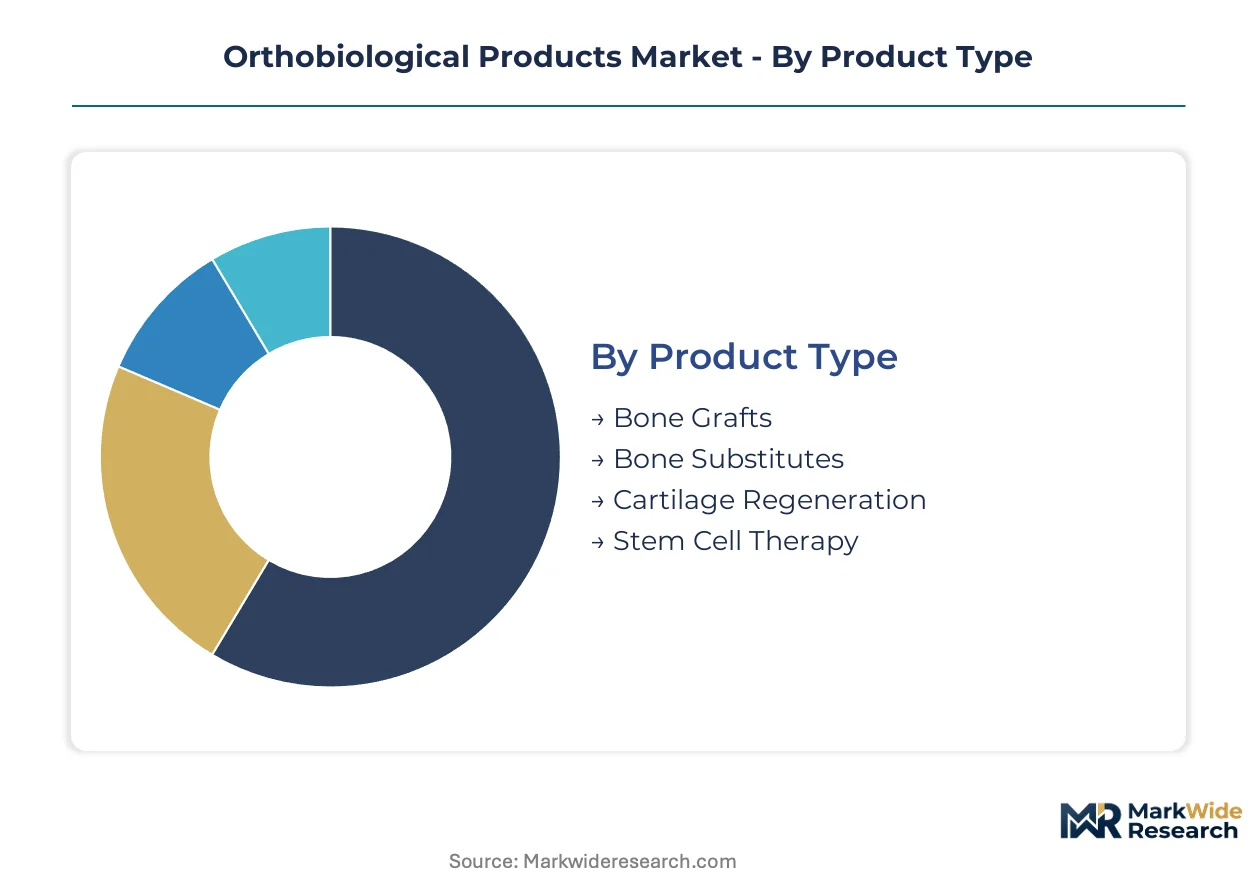
Orthobiological products fragment across four intersecting dimensions that determine regulatory pathways, pricing power, and procurement access. Product type and application govern reimbursement codes, while end-user concentration shapes distribution economics and technology maturity dictates manufacturing scale requirements.
Product Type:
Domestic production dominates bone grafts and substitutes, while stem cell therapies and advanced cartilage solutions lean heavily on cross-border supply chains for raw biological material.
- Bone Grafts:Demineralized bone matrix and allograft formulations command entrenched surgeon familiarity with established CPT reimbursement codes. Demand concentrates in German spine surgery centers and US metropolitan hospital systems where lumbar fusion volumes sustain high utilization rates.
- Stem Cell Therapy:Bone marrow aspirate concentrate and adipose-derived cellular preparations require FDA 21 CFR Part 1271 compliance for minimal manipulation thresholds. Orthopedic clinics in Florida and Texas are expanding same-day processing capabilities to capture outpatient migration from inpatient settings.
- Bone Substitutes:Synthetic hydroxyapatite and beta-tricalcium phosphate scaffolds eliminate allograft supply dependence for rural hospitals facing tissue bank distribution gaps.
- Cartilage Regeneration:Autologous chondrocyte implantation protocols with collagen membrane fixation attract premium sports medicine reimbursement in academic medical centers.
Bone grafts hold the largest share; momentum sits with stem cell therapy.
End User:
Cost tier stratification separates high-complexity inpatient procedures from streamlined outpatient interventions that ambulatory facilities now capture.
- Hospitals:Integrated delivery networks consolidate orthobiologic procurement through sole-source agreements, squeezing independent distributor margins. Urban tertiary centers in the United States command 60% of high-value allograft volume through centralized purchasing committees.
- Orthopedic Clinics:Freestanding specialty facilities drive adoption of point-of-care cell processing systems that enable same-day bone marrow concentrate preparation. Arizona and Nevada regulatory frameworks permit autonomous biologic preparation without hospital laboratory licensure.
- Rehabilitation Centers:Post-acute settings increasingly administer platelet-rich plasma injections for tendon and ligament indications outside surgical episodes.
- Research Institutions:Academic medical centers in Massachusetts and California anchor NIH-funded tissue engineering trials that prefigure commercial product pipelines.
Hospitals retain volume dominance; orthopedic clinics are gaining share fastest.
Application:
Procedure volume concentrates in spine and joint reconstruction, while fracture repair and soft tissue applications expand through emergency department and sports medicine channels.
- Spine Surgery:Lumbar interbody fusion procedures consume the highest per-case graft volumes, with German surgical centers reporting the most pronounced allograft utilization intensity in Europe.
- Joint Reconstruction:Revision total knee and hip arthroplasty drives synthetic scaffold adoption as surgeons seek alternatives to autograft harvest morbidity.
- Fracture Repair:Trauma centers deploy injectable calcium phosphate cements for metaphyseal defects, particularly in aging populations with compromised healing biology.
- Soft Tissue Repair:Rotator cuff and Achilles tendon augmentation with extracellular matrix patches represents an emerging indication with evolving reimbursement clarity.
Spine surgery commands the highest graft intensity per procedure; joint reconstruction offers the broadest addressable patient base.
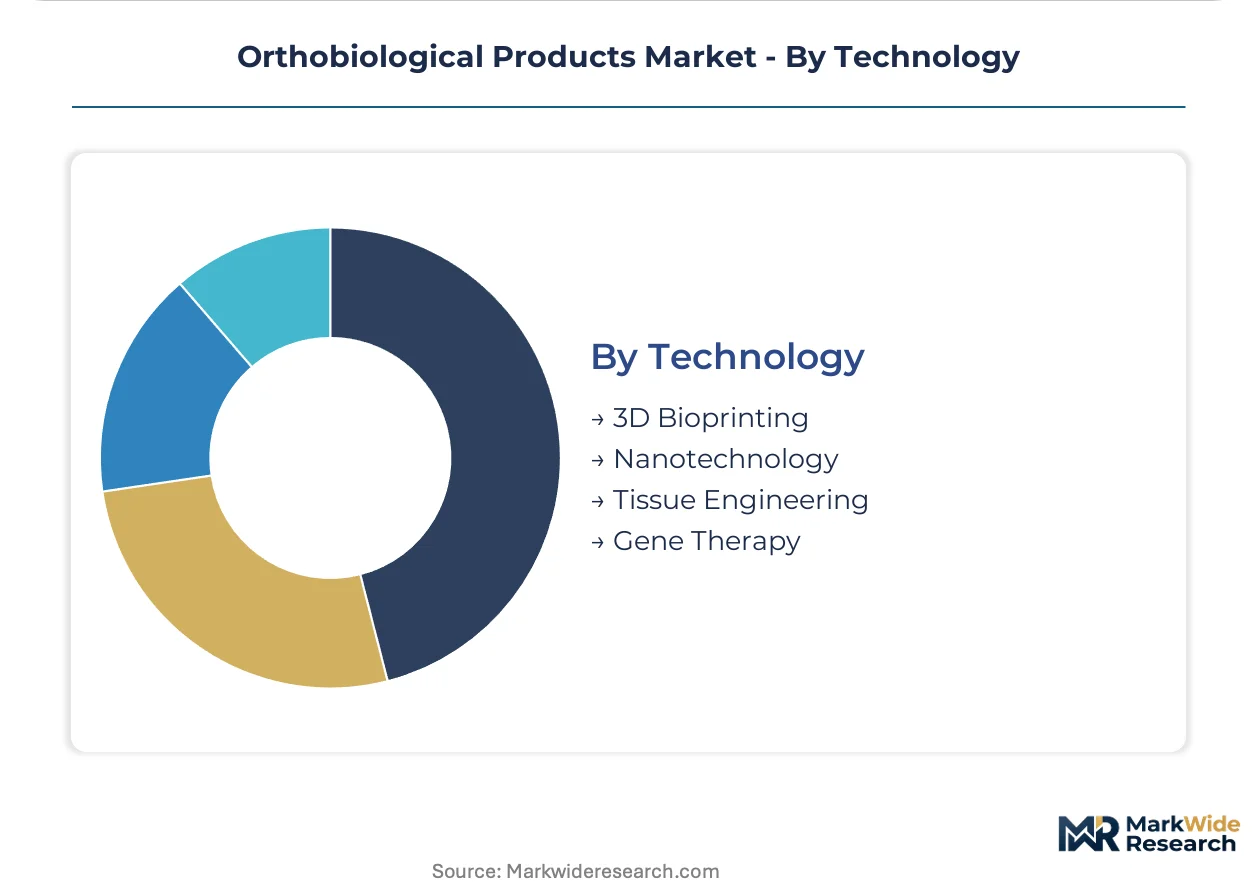
Technology:
Manufacturing maturity separates commercially validated platforms from preclinical innovations that await regulatory pathway definition.
- Tissue Engineering:Autologous chondrocyte expansion and scaffold seeding protocols have achieved commercial scale with established GMP manufacturing networks. German and Swiss facilities supply European sports medicine centers with cryopreserved cellular products.
- 3D Bioprinting:Extrusion-based ceramic and hydrogel deposition systems enable patient-specific defect matching for craniomaxillofacial reconstruction. Academic consortia in the Netherlands and Belgium are advancing multicellular vascularized constructs toward first-in-human trials.
- Nanotechnology:Surface-modified titanium and polymer substrates with osteoinductive nanotopography are penetrating spinal fusion applications through 510(k) predicate routes.
- Gene Therapy:Viral vector delivery of BMP-2 and BMP-7 expression constructs remains preclinical, with IND-enabling toxicology studies underway at select US gene therapy developers.
Tissue engineering holds commercial primacy; 3D bioprinting shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes demineralized bone matrix at higher per-capita intensity than any peer market, while the United States leads in point-of-care cell processing adoption and India builds regulatory velocity for imported orthobiologics.
United States
Florida and Texas orthopedic clinics are installing same-day bone marrow aspirate concentrate systems to capture outpatient surgical migration. FDA 21 CFR Part 1271 enforcement around minimal manipulation thresholds is forcing processors to revalidate supply chains or surrender product classification advantages. Greater Boston academic medical centers anchor NIH-funded tissue engineering trials that prefigure commercial pipelines.
Germany
Lumbar fusion procedures in German spine surgery centers report the most pronounced allograft utilization intensity in Europe. EU Medical Device Regulation Article 117 transitional provisions permit grandfathered orthobiologics to maintain market access while novel submissions face predictable review timelines. Bavarian and North Rhine-Westphalian surgical clusters are adapting to dual classification complexity for scaffold structural components alongside tissue establishment licensing.
India
CDSCO pathway expansion through recent medical device rules amendments creates accelerated registration tracks for orthobiologics with US FDA or EU MDR approvals. Maharashtra and Karnataka hospital systems are consolidating procurement through sole-source agreements with integrated device-biologic suppliers. Mumbai and Bengaluru medical device distributors report expanding shelf access for demineralized bone matrix formulations.
Switzerland
Swissmedic oversight of autologous chondrocyte expansion protocols has achieved commercial scale with established GMP manufacturing networks. Basel and Zurich facilities supply European sports medicine centers with cryopreserved cellular products. The country's precision manufacturing base is engineering surface-modified titanium substrates with osteoinductive nanotopography for spinal fusion applications.
Japan
PMDA review timelines for novel xenogeneic scaffolds remain extended versus predicate device pathways, compressing competitive entry for foreign manufacturers. Tokyo and Osaka metropolitan hospital systems dominate high-value allograft volume through centralized purchasing committees. METI-supported academic consortia are advancing multicellular vascularized constructs toward first-in-human trials.
Orthobiological Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding supply chain control through captive biologics processing and the lower tier competing on arthroscopic delivery integration or synthetic matrix specialization. The market structure rewards backward integration into tissue recovery networks and in-house production of demineralized bone matrix. Dominant competitive moves include strategic partnerships with hospital purchasing committees and portfolio diversification across cell-based and synthetic platforms.
Among US-based diversified orthopedics manufacturers, Stryker Corporation and Zimmer Biomet exemplify the integrated leader archetype, while Arthrex occupies a position within the specialized delivery systems tier. Medtronic represents the cross-sector medical technology conglomerate with orthobiologic exposure. These anchors demonstrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Medtronic |
| Zimmer Biomet |
| Stryker Corporation |
| DePuy Synthes |
| Arthrex |
| Bioventus |
| Globus Medical |
| Orthofix Medical |
| Anika Therapeutics |
| Others |
Value Network & Pricing Analysis
Synthetic hydroxyapatite scaffolds displacing demineralized bone matrix in German spine centers simultaneously relocate procurement gravity toward ceramic foundries in Switzerland and compress allograft pricing power held by US tissue banks.
Pricing Analysis
Long-term offtake contracts between hospital purchasing committees and integrated device-biologic suppliers dominate procurement structures, with spot purchasing reserved for emergency trauma cases. Price differentiation rests on FDA 510(k) clearance tier versus predicate device lineage and volume commitments exceeding 500 units annually. Pricing pressure stems from synthetic alternatives eliminating allograft supply premiums in rural distribution zones. Academic medical centers demonstrate lowest price sensitivity due to reimbursement capture through premium CPT codes, while ambulatory surgical facilities negotiate aggressively on per-unit graft costs.
Supply Chain Analysis
Inbound logistics costs for cryopreserved cellular products—particularly liquid nitrogen container availability on transatlantic lanes—strain distribution economics for Swiss and German tissue engineering facilities. Raw material supply concentrates in the United States for allograft tissue recovery, Switzerland for precision-manufactured ceramic scaffolds, and India for hydroxyapatite precursor chemicals. Manufacturing networks draw from bone tissue banks, pharmaceutical-grade collagen processors, and medical device polymer foundries. Single-source vulnerability pervades demineralized bone matrix feedstock due to five dominant US recovery organizations. Distribution runs through integrated delivery network sole-source agreements that displace independent distributor shelf access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care cell processing services in orthopedic clinics are expanding faster than implantable hardware sales, creating recurring revenue layers that offset capital equipment pricing erosion.
For Market Incumbents: Compound supply chain control through backward integration into tissue recovery networks or captive biologics processing facilities to defend against synthetic matrix substitution. Prioritize GMP certification investment for autologous chondrocyte expansion protocols. Secure sole-source agreements with hospital purchasing committees in metropolitan markets where accountable care organization penetration exceeds 40 percent of covered lives. For New Entrants and Emerging Players: Differentiate on ambulatory surgical facility enablement—specifically closed-system centrifuge devices for same-day bone marrow aspirate concentrate preparation. Target orthopedic clinics in Arizona and Nevada where autonomous biologic preparation operates outside hospital laboratory licensure requirements. Pursue CDSCO accelerated registration in India for products already cleared by FDA or EU MDR. For Investors and Strategic Acquirers: The market sits at a regulatory clarification phase that favors processors with validated minimal manipulation protocols and established tissue establishment licensing. Five-to-ten year viability hinges on portfolio diversification across cell-based and synthetic platforms rather than single-technology dependence. Acquisition targets should demonstrate GMP manufacturing scale and cryopreservation logistics capabilities. Watch FDA inspection frequency intensification as the inflection signal for processor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Point-of-Care Processing System Deployment | Enables same-day bone marrow concentrate preparation in ambulatory surgical facilities, capturing outpatient migration from inpatient settings. |
| EU MDR Article 117 Compliance Investment | Permits grandfathered orthobiologics to maintain European market access while competitors face extended notified body review timelines. |
| Hospital System Partnership Consolidation | Secures sole-source procurement agreements that displace independent distributors and establish multi-year revenue visibility. |
| Synthetic Scaffold R&D Expansion | Reduces allograft supply dependence and eliminates tissue bank distribution vulnerabilities in rural hospital networks. |
| CDSCO Accelerated Registration Pursuit | Unlocks Indian market access through streamlined pathways for products with existing FDA or EU MDR approvals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body assessment reports, hospital procurement databases, and CMS Medicare reimbursement data. Interviews with orthopedic surgeons, hospital purchasing committee directors, tissue establishment quality managers, and GPO contracts managers informed demand-side dynamics. Bottom-up triangulation across product-type volume estimates and top-down validation against macro healthcare expenditure trends ensured cross-check integrity.
Segmentation dimensions modeled span product type, application, end-user concentration, and technology maturity across the projection horizon. CAGRs were derived from procedure volume elasticities, reimbursement trajectory assumptions, and regulatory pathway probability weightings. Industry-specific forecast inputs incorporated FDA 21 CFR Part 1271 enforcement intensity patterns and EU MDR transitional provision utilization rates.
Material uncertainties—evolving minimal manipulation threshold interpretations, sudden tissue bank supply disruptions, and reimbursement code revisions for autologous therapies—sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and surgeon adoption curves for synthetic alternatives. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Protein Characterization and Identification Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Global Bifida Ferment Lysate Market
Biomedical Technology
Fluorescence-Activated Cell Sorting Market
Biomedical Technology
Europe Proteomics Market
Biomedical Technology
Glycomics Market
Biomedical Technology
Global Exosome Research Products Market
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
In Vitro Protein Expression Market