
 Small-Scale Bioreactors Market | 2026-2036
Small-Scale Bioreactors Market Size, Share, and Industry Trends Forecast 2026-2036
Small-Scale Bioreactors Market Outlook
Single-use bioreactor technology is fragmenting the traditional stainless-steel equipment landscape as disposable vessel systems gain traction in clinical-scale production. Sartorius AG leverages its integrated fluid management portfolio to dominate upstream single-use workflows. Thermo Fisher Scientific anchors its position through extensive distribution networks and analytical instrument bundling. Danaher Corporation competes across multiple bioprocessing layers via its operating company structure.
Small-scale bioreactors are closed culture vessels typically ranging from one to fifty liters in working volume, designed for process development, seed train expansion, and clinical batch production of biologics. These systems employ agitation, temperature control, and dissolved oxygen management to maintain mammalian, microbial, or insect cell cultures under optimized growth conditions. Stirred tank configurations retain the largest installed base due to their operational familiarity and scale-up predictability, while wave bioreactor adoption accelerates in gene therapy applications where low-shear environments protect viral vector integrity. Single-use systems capture expanding margin pools as pharmaceutical companies prioritize facility flexibility and reduced cross-contamination risk.
FDA process analytical technology guidelines and EMA good manufacturing practice standards shape equipment validation requirements and data integrity protocols across the installed base. ISO 14644 cleanroom classifications and ASME BPE bioprocessing equipment standards further constrain design parameters and material selections for manufacturers. Stakeholders must monitor evolving cell and gene therapy regulatory pathways where agency expectations for closed-system processing continue to tighten.
Market Dynamics
Single-use vessel technology is fragmenting equipment procurement patterns as pharmaceutical manufacturers prioritize facility reconfiguration speed over stainless-steel asset longevity. This shift compresses validation timelines and redistributes margin pools toward disposable supply chains.
Growth Catalysts
- Gene therapy manufacturing expansion:Viral vector production facilities in Germany, the United States, and China are scaling clinical-batch capacity using low-shear wave bioreactor configurations to protect vector integrity.
- FDA Process Analytical Technology guidelines:Real-time quality monitoring mandates are accelerating sensor-integrated bioreactor adoption across mammalian cell culture workflows.
- Contract manufacturing consolidation:CDMO facility buildouts in Singapore and Switzerland are standardizing on single-use seed train architectures to enable multi-product campaign flexibility.
Market Restraints
- Resin and film supply concentration:Specialized fluoropolymer films for single-use bags rely on concentrated Asian chemical processing capacity, exposing bioreactor manufacturers to input volatility.
- Stainless-steel asset stranding:Existing installed bases in legacy biologics facilities create capital recovery friction that slows full conversion to disposable architectures.
- EMA extractables-leachables testing burden:Single-use system qualification timelines extend validation cycles and compress effective equipment utilization rates.
Strategic Opportunities
- Cell therapy autologous production:Patient-specific manufacturing models in the United States are creating demand for sub-10-liter closed-system bioreactors with integrated cell handling.
- ISO 14644-1 cleanroom convergence:Modular cleanroom pod suppliers are bundling bioreactor pre-validation services, opening channel partnerships for equipment OEMs.
- India biologics manufacturing emergence:CDSCO manufacturing incentives and PLI scheme subsidies are attracting greenfield facility investments requiring clinical-scale bioreactor fleets.
Industry Challenges
- Bioprocess engineer scarcity:Specialized expertise in scale-down model development and single-use system troubleshooting remains concentrated among experienced practitioners in Boston and Basel clusters.
- Legacy distributed control system integration:Brownfield facilities face protocol incompatibility when connecting modern bioreactor skids to existing SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small-Scale Bioreactors Market |
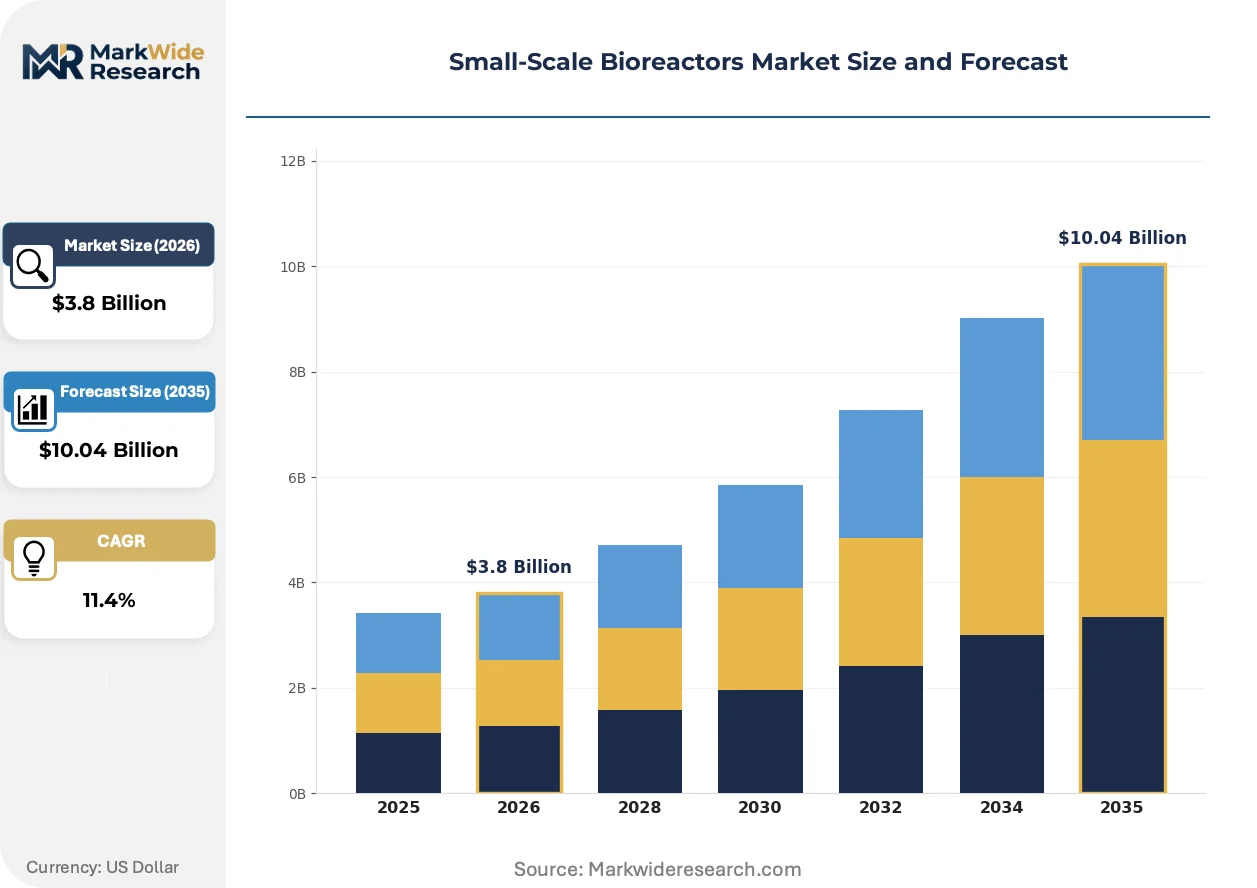
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stirred Tank, Fed-Batch, Continuous, Wave Bioreactor End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Biotechnology Firms Technology: Single-Use Systems, Automated Controls, Sensor Technology, Hybrid Systems Application: Vaccine Production, Protein Expression, Cell Culture, Gene Therapy |
| Companies Covered | Sartorius AG, Thermo Fisher Scientific, Danaher Corporation, Eppendorf AG, Merck KGaA, Infors AG, Getinge AB, Solaris Biotechnology, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small-Scale Bioreactors Market Strategic Shifts
Sensor miniaturization and machine learning integration are compressing process development cycles while enabling predictive culture control. Equipment architectures are converging around modular, data-native designs that prioritize interoperability over standalone functionality.
Perfusion-capable small-scale bioreactors are hybridizing batch and continuous processing modes, allowing seed train operations to feed directly into production bioreactors without intermediate harvest steps. Gene therapy manufacturers in Cambridge and Heidelberg are adopting these systems to reduce viral vector residence time and improve yield consistency. This architecture is compressing facility footprint requirements and enabling distributed manufacturing models closer to clinical sites.
EMA's revised Annex 1 GMP guidelines for sterile manufacturing are mandating closed-system processing for all new biologics facilities, effectively prohibiting open manipulations in Grade A environments. Equipment suppliers must now pre-validate integrated closed sampling and transfer systems before site acceptance testing. Bioreactor configurations with welded tubing sets and sterile connectors are capturing preference share in European facility design specifications.
CDMOs are unbundling equipment procurement from full-service manufacturing contracts, creating direct sales channels for bioreactor OEMs into previously captive accounts. This disintermediation shifts pricing power toward equipment vendors with validated single-use supply chains and accelerates replacement cycles as contract manufacturers compete on facility flexibility. The pattern is most visible in Swiss and Singaporean CDMO clusters where multi-tenant biologics campuses standardize on interchangeable equipment platforms.
Small-Scale Bioreactors Market Segmentation
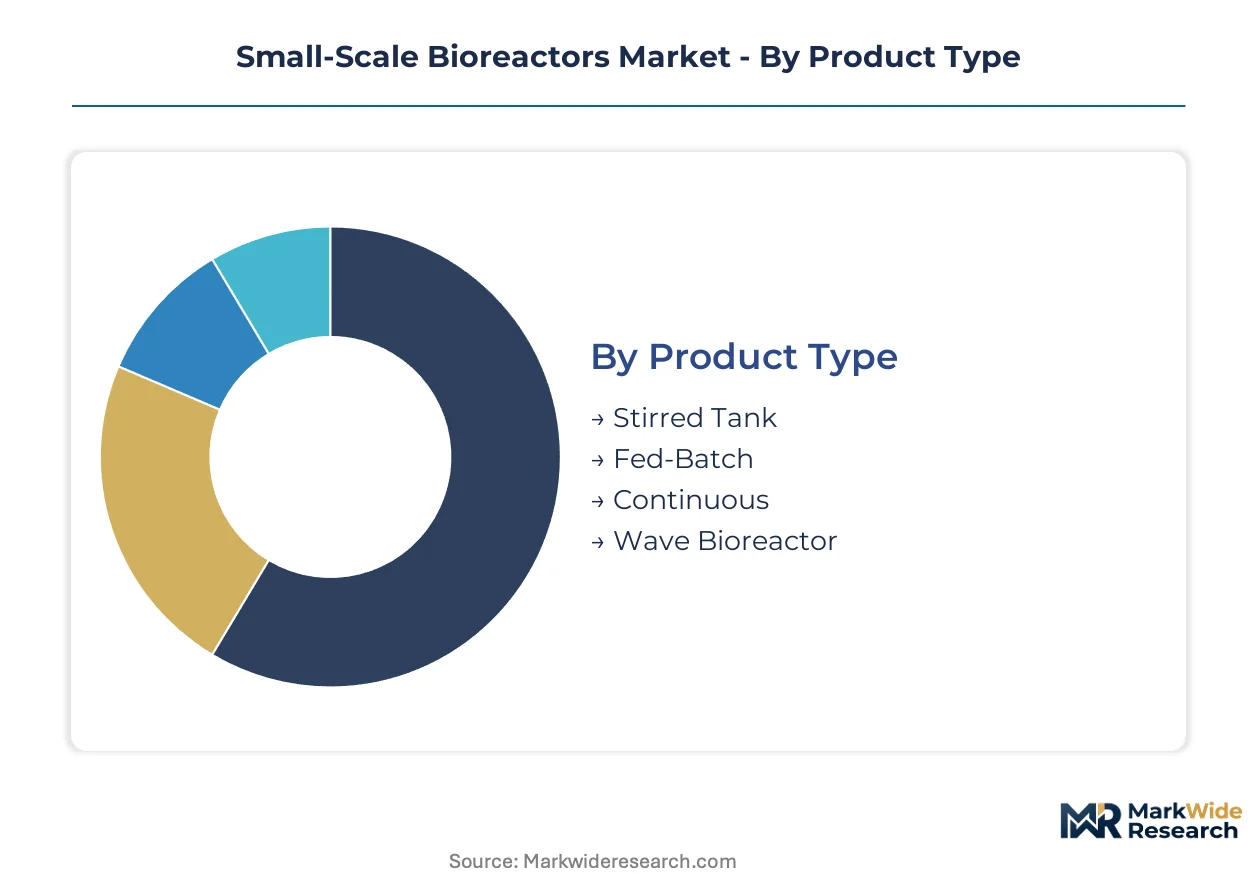
Segmentation in small-scale bioreactors reveals distinct service intensity profiles across equipment categories. Stirred tank systems demand intensive field calibration support, while single-use platforms shift margin toward consumable replenishment cycles.
Product Type:
After-sales service intensity varies sharply across vessel architectures, with stainless-steel systems requiring multi-year maintenance contracts and disposable formats concentrating service spend on installation validation.
- Stirred Tank:Mechanical agitation systems with impeller-based mixing dominate mammalian cell culture workflows. Pharmaceutical manufacturers in Germany specify these for scale-up predictability from 10-liter process development to 2,000-liter production trains. FDA process analytical technology mandates are accelerating integrated sensor adoption in new installations.
- Fed-Batch:Intermittent nutrient supplementation protocols remain the standard operational mode for monoclonal antibody production. Academic institutions in the United States deploy these systems for cost-controlled process optimization before technology transfer to manufacturing partners.
- Continuous:Perfusion-capable architectures enable steady-state cell culture with automated cell retention. CDMOs in Switzerland are standardizing these for viral vector manufacturing to reduce facility footprint.
- Wave Bioreactor:Rocking-motion platforms provide low-shear environments critical for gene therapy applications. Gene therapy manufacturers in Cambridge and Heidelberg specify these for plasmid and lentiviral vector production.
Stirred tank configurations hold the largest share; momentum sits with wave bioreactor adoption in cell and gene therapy process development.
End User:
Procurement authority and validation requirements diverge substantially across customer types, with pharmaceutical companies driving specification standards that cascade to contract research partners.
- Pharmaceutical Companies:Internal biologics manufacturing groups specify equipment platforms that align with global facility standards. EMA Annex 1 GMP revisions are forcing closed-system requirements into capital expenditure planning.
- Academic Institutions:Budget-constrained research programs prioritize equipment versatility across multiple cell lines. University core facilities in Boston and Basel clusters negotiate multi-instrument service bundles.
- Research Organizations:Non-profit and government laboratories focus on open-architecture systems enabling protocol customization. These users generate early-stage data that shapes downstream commercial process design.
- Biotechnology Firms:Venture-backed development-stage companies favor single-use flexibility to preserve capital for pipeline advancement. CDMO partnerships in Singapore increasingly specify equipment interoperability for seamless technology transfer.
Pharmaceutical companies command the largest procurement volume; biotechnology firms are expanding most quickly as gene therapy pipelines mature.
Technology:
Technology stack decisions determine ongoing operational expenditure profiles, with sensor-integrated platforms commanding premium service contracts and hybrid architectures requiring specialized integration support.
- Single-Use Systems:Pre-sterilized disposable vessels eliminate cleaning validation cycles. CDMO facility buildouts in Switzerland standardize on these for multi-product campaign flexibility.
- Automated Controls:Programmable logic controller and distributed control system integration enables unattended operation. Brownfield facilities face protocol incompatibility when connecting modern skids to legacy SCADA architectures.
- Sensor Technology:Real-time dissolved oxygen, pH, and biomass monitoring supports process analytical technology compliance. FDA guidelines are mandating these capabilities for new biologics license applications.
- Hybrid Systems:Combinations of stainless-steel and single-use components balance asset longevity with operational flexibility. These configurations are gaining preference in facility expansion projects where existing infrastructure constrains full conversion.
Single-use systems hold the dominant position; sensor technology is climbing the fastest as regulatory pressure intensifies.
Application:
Application-specific requirements dictate equipment specification, with gene therapy manufacturing imposing the most stringent closed-system and low-shear constraints.
- Vaccine Production:Rapid response manufacturing for pandemic preparedness favors platform technologies with fast facility reconfiguration. CDMOs in India are scaling these capabilities under PLI scheme subsidies.
- Protein Expression:Recombinant protein and antibody production remains the largest volume application. Mammalian cell culture workflows in Chinese manufacturing clusters specify perfusion-capable systems for titer maximization.
- Cell Culture:Seed train expansion and process development applications span working volumes from 1 to 50 liters. Academic and industrial users both demand scale-down model fidelity to production bioreactors.
- Gene Therapy:Viral vector and cell therapy manufacturing requires specialized low-shear handling. EMA and FDA regulatory pathways for these products are tightening closed-system processing requirements.
Protein expression maintains the largest application share; gene therapy is gaining share fastest as regulatory approvals accelerate commercial manufacturing investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for specialized fluoropolymer films and single-use consumables shapes regional competitive dynamics. Equipment manufacturers in Germany and Switzerland source disposable vessel components from concentrated Asian chemical processing capacity. Export flows of validated bioreactor systems concentrate from Western European and North American fabrication centers toward emerging biologics manufacturing clusters.
United States
Gene therapy viral vector facilities in Cambridge and Boston drive demand for low-shear wave bioreactor configurations. FDA process analytical technology guidelines mandate real-time quality monitoring capabilities in new biologics license applications. The Greater Boston cluster anchors domestic manufacturing expansion as venture-backed biotechnology firms scale clinical-batch capacity.
Germany
Pharmaceutical manufacturers specify stirred tank systems for scale-up predictability from process development to production trains. EMA Annex 1 GMP revisions enforce closed-system processing requirements in capital expenditure planning. The Rhine-Main and Upper Bavaria regions concentrate CDMO facility investments under multi-product campaign flexibility mandates.
Switzerland
CDMOs standardize on single-use seed train architectures to enable rapid facility reconfiguration between client programs. Swissmedic sterile manufacturing guidelines align with EMA extractables-leachables testing protocols. The Basel biopharmaceutical corridor hosts concentrated vendor pre-validation services and modular cleanroom pod integration.
China
Domestic biologics manufacturing clusters prioritize perfusion-capable systems for recombinant protein titer maximization. NMPA good manufacturing practice standards for biologics tighten data integrity and equipment validation requirements. The Yangtze River Delta region attracts greenfield facility investments serving both domestic and export-oriented contract manufacturing.
India
CDSCO manufacturing incentives and PLI scheme subsidies accelerate clinical-scale bioreactor fleet procurement for vaccine and biosimilar production. The national pharmaceutical regulator mandates equipment qualification timelines that favor pre-validated single-use platforms. Maharashtra and Telangana states concentrate CDMO buildouts targeting export markets in Africa and Southeast Asia.
Small-Scale Bioreactors Market Competitive Environment
On the supply side, the industry is consolidating around integrated bioprocessing portfolios that span upstream fluid management, analytical instrumentation, and downstream purification. Tiered competitive positioning separates full-stack platform vendors from specialized vessel fabricators and regional automation integrators. Dominant competitive moves include strategic partnerships between equipment OEMs and modular cleanroom suppliers, plus capacity expansion into pre-validation service capabilities.
Among Germany-based precision equipment specialists, Sartorius AG and Eppendorf AG exemplify the integrated fluid management archetype that dominates upstream single-use workflows. Thermo Fisher Scientific represents the distribution-intensive platform model, anchoring market position through analytical instrument bundling and extensive channel coverage. Danaher Corporation occupies a multi-layer position via its operating company structure, competing across bioprocessing equipment categories without consolidated brand presence.
| Leading Market Players |
|---|
| Sartorius AG |
| Thermo Fisher Scientific |
| Danaher Corporation |
| Eppendorf AG |
| Merck KGaA |
| Infors AG |
| Getinge AB |
| Solaris Biotechnology |
| Lonza Group |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Rotterdam container freight corridors dictate landed cost differentials for single-use bioreactor consumables, compressing margins for European CDMOs while amplifying price spread between premium sensor-integrated systems and standard stirred-tank configurations. This logistics tension concentrates pricing power among vendors with captive Asian fluoropolymer film supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical manufacturers command volume discounts through multi-year service contracts, while academic institutions face list-price exposure. Price differentiation hinges on FDA process analytical technology compliance tier and integrated sensor density. Cost compression in economy-tier stainless-steel systems is intensifying because CDMOs prioritize facility flexibility over asset longevity. Biotechnology firms exhibit highest price sensitivity due to venture-constrained capital deployment.
Supply Chain Analysis
Contract manufacturing concentration sits with Lonza Group, Thermo Fisher Scientific, and Samsung Biologics for bioreactor assembly and pre-validation services. Specialized fluoropolymer film production draws from China, Japan, and Germany. Sensor module fabrication rests on South Korean semiconductor foundries and German precision optics suppliers. Single-source vulnerability in fluoropolymer resin supply exposes equipment OEMs to input volatility. Distribution runs through direct OEM sales teams for pharmaceutical accounts and distributor networks for academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Small-scale bioreactors represent an early-cycle expansion story as gene therapy manufacturing capacity buildouts accelerate viral vector facility investments. FDA and EMA regulatory tightening on closed-system processing creates durable equipment replacement demand.
For Market Incumbents: Pre-empt sensor-integrated platform commoditization by locking exclusive fluoropolymer film supply agreements with Asian chemical processors. Defend against emerging modular cleanroom pod suppliers by bundling pre-validation services with equipment sales. Capacity addition in Swiss and Singaporean CDMO corridors preserves pricing power in high-specification segments. For New Entrants and Emerging Players: Mid-scale biotechnology firms in India represent the most penetrable entry point, as PLI scheme subsidies reduce procurement friction for pre-validated single-use platforms. Sub-10-liter closed-system bioreactors for autologous cell therapy production offer white-space positioning against incumbent scale-up architectures. Go-to-market through modular cleanroom pod partnerships bypasses direct competition with established OEM field service networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized bioprocessing equipment divisions. Long-term viability centers on recurring consumable revenue attachment rates rather than equipment placement volume. Watch CDMO facility utilization rates as the inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Film Supply Agreement | Captive resin access insulates Sartorius and Thermo Fisher from Asian chemical processing volatility. |
| Pre-Validation Service Bundling | EMA Annex 1 GMP compliance timelines favor OEMs offering integrated closed-system qualification. |
| Modular Cleanroom Pod Partnership | Swiss and Singaporean CDMOs standardize on interchangeable platforms for multi-product flexibility. |
| Sensor Miniaturization R&D | FDA process analytical technology mandates drive real-time biomass monitoring adoption. |
| India Manufacturing Scale-Up | CDSCO incentives attract greenfield facility investments requiring clinical-scale bioreactor fleets. |
Study Parameters
Desk research of FDA biologics license application filings, EMA manufacturing authorization databases, and CDSCO facility registration records preceded structured interviews with bioprocess engineering directors, CDMO facility planners, and single-use supply chain managers. Secondary validation drew from ISO 14644 cleanroom certification registries and ASME BPE equipment standard documentation. Bottom-up equipment placement counts triangulated against top-down biologics manufacturing capacity estimates across the analysis window.
Assumptions held regulatory pathway timelines and single-use adoption rates fixed while varying gene therapy pipeline maturation and CDMO consolidation scenarios. Segmentation modeling spanned vessel architecture, operational mode, end-user type, and regional regulatory cluster. CAGRs derived from unit shipment trajectories and average selling price evolution across premium and economy tiers. Forecast inputs incorporated perfusion-capable system penetration and sensor-integrated platform mix shifts.
Practitioners should monitor fluoropolymer resin spot pricing and EMA extractables-leachables testing protocol revisions for early signals of margin compression or qualification timeline extension. Quarterly review of CDMO facility utilization rates and gene therapy regulatory approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Plant Phenotyping Equipment Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Biotechnology Instrumentation Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
DNA/RNA Extraction Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Global Bovine Serum Albumin Market
Biotechnology Equipment
Rocking Bioreactors Market