
 Glycomics Market | 2026-2036
Glycomics Market Size, Share, and Industry Trends Forecast 2026-2036
Glycomics Market Intelligence
Multi-source procurement for analytical instrumentation is restructuring how pharmaceutical companies and academic consortia access glycomics capabilities. Bruker Corporation leverages its mass spectrometry portfolio to anchor high-resolution glycan analysis workflows across European research institutes. Thermo Fisher Scientific competes through integrated chromatography-mass spectrometry platforms that span sample preparation through data interpretation. Danaher Corporation extends its life sciences instrumentation footprint through specialized liquid handling and detection systems tailored to glycoprotein characterization.
Glycomics encompasses the systematic study of carbohydrate structures, their biosynthesis, and their functional roles in biological systems, employing techniques such as hydrophilic interaction liquid chromatography (HILIC) and tandem mass spectrometry to resolve glycan linkages and branching patterns with single-residue precision. This discipline serves biopharmaceutical development by enabling quality control of monoclonal antibody glycosylation profiles and identifying disease-associated glycan biomarkers. Mass spectrometry commands the technology segment due to its unmatched sensitivity in profiling complex glycan mixtures from minute biological samples. Drug development applications attract disproportionate investment as sponsors pursue glycoengineered biologics with enhanced effector function and reduced immunogenicity.
The FDA maintains stringent glycosylation consistency requirements for approved biologics, compelling sponsors to invest in analytical validation and comparability protocols. EMA's biosimilar guidance on glycan critical quality attributes further shapes how developers design analytical strategies for European market access. ISO 17025 accreditation and ICH Q5E guidelines on comparability create layered compliance obligations that filter market participants by technical capability. Stakeholders must monitor how evolving regulatory expectations around glycan analysis will reshape capital allocation between platform standardization and bespoke method development.
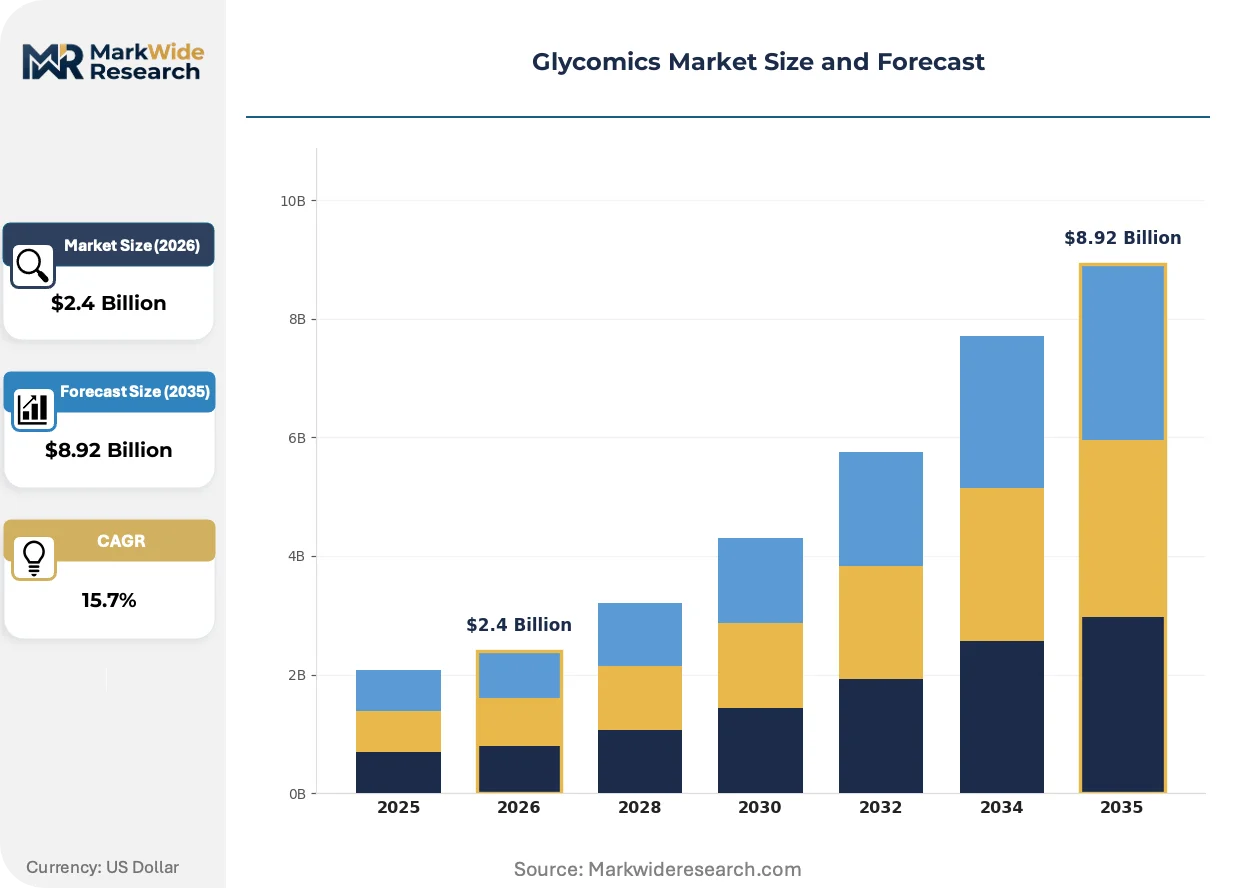
Market Dynamics
FDA accelerated approval pathways for glycoprotein therapeutics compress development timelines, forcing sponsors to front-load analytical validation investments while academic-industrial consortia in the United States, Germany, and Japan anchor funding pipelines.
Growth Catalysts
- EMA Biosimilar Glycan Guidance:European developers design analytical strategies around critical quality attributes, expanding contract research demand for glycan comparability protocols.
- Oncology Biologics Pipeline:Glycoengineered monoclonal antibodies with enhanced effector function require precise glycosylation profiling, driving mass spectrometry platform adoption.
- Japan Academic-Industrial Consortia:METI-funded partnerships between universities and biopharmaceutical manufacturers accelerate translation of glycan biomarker discoveries into clinical applications.
Market Restraints
- High-Purity Enzyme Costs:PNGase F and other glycan-releasing enzymes concentrate among specialized biochemical suppliers, creating input cost volatility for analytical laboratories.
- Reference Material Scarcity:NIST and other standards bodies maintain limited certified glycan reference panels, constraining method validation across sites.
- Skilled Technician Bottleneck:HILIC-MS method development requires hybrid expertise in chromatography and glycobiology that training programs have not scaled to match demand.
Strategic Opportunities
- India CDMO Expansion:PLI scheme incentives for biopharmaceutical manufacturing attract glycomics analytical service providers to establish technical centers.
- AI-Assisted Spectral Interpretation:Machine learning tools trained on glycan fragmentation patterns converge with cloud-based data platforms to accelerate biomarker identification workflows.
- Point-of-Care Glycan Diagnostics:Lateral flow and microfluidic formats adapted from infectious disease testing migrate into metabolic disease screening applications.
Industry Challenges
- ISO 17025 Accreditation Timelines:Glycan analysis laboratories face 12-18 month certification cycles that delay contract revenue recognition and capacity utilization.
- Legacy LIMS Integration:Mass spectrometry data formats from multiple vendors require custom middleware development to connect with established pharmaceutical quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycomics Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.92 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saccharides, Glycoproteins, Glycolipids, Glycosaminoglycans Application: Drug Development, Diagnostics, Therapeutics, Research Technology: Chromatography, Mass Spectrometry, Microarray, NMR End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Biotechnology Firms |
| Companies Covered | Bruker Corporation, Shimadzu Corporation, Thermo Fisher Scientific, Takara Bio, New England Biolabs, Merck KGaA, Waters Corporation, Danaher Corporation, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycomics Market Strategic Shifts & Innovations
Multi-omics integration is dissolving boundaries between glycomics, proteomics, and metabolomics workflows, with sponsors demanding unified data architectures that trace glycan modifications through biological pathways rather than treating them as isolated measurements.
High-resolution ion mobility mass spectrometry is converging with trapped ion mobility spectrometry to resolve isobaric glycan structures that chromatography alone cannot separate. Biopharmaceutical quality control laboratories in Germany and Switzerland are adopting these platforms to meet EMA biosimilar comparability requirements. The technology is converging with automated sample preparation robotics to compress turnaround times for release testing from days to hours.
FDA guidance on glycosylation critical quality attributes for biosimilar interchangeability is tightening analytical expectations for sponsors seeking US market access. Developers must now demonstrate statistical equivalence across multiple glycan features rather than selected markers. Oncology-focused biologics manufacturers are responding by internalizing glycomics capabilities rather than relying entirely on contract analytical services.
Consolidated procurement of multi-vendor instrument platforms is displacing single-source analytical relationships. Large pharmaceutical sponsors now negotiate enterprise agreements spanning mass spectrometry, liquid handling, and data analysis software from coordinated supplier ecosystems. This pattern is most visible among top-20 biopharmaceutical companies headquartered in the United States and operating integrated manufacturing networks across Massachusetts, North Carolina, and California clusters.
Glycomics Market Segmentation
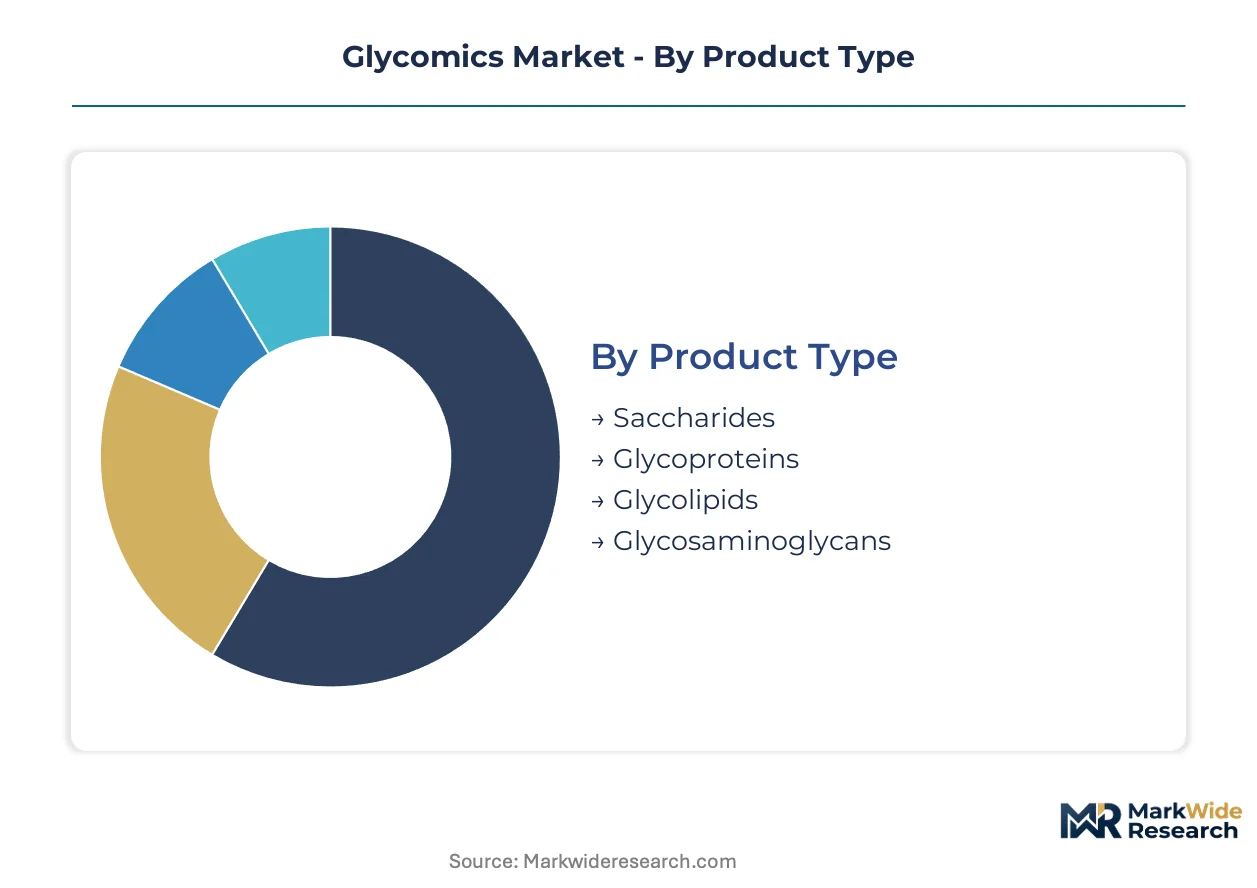
Glycomics market segmentation reflects divergent technical requirements across biopharmaceutical manufacturing and academic research. Product specifications, analytical workflows, and end-user procurement patterns vary sharply between quality-control environments and exploratory discovery settings.
Product Type:
Customization intensity spans from standardized commodity saccharides to bespoke glycoengineered biologics requiring patient-specific glycosylation profiles.
- Glycoproteins:Therapeutic antibodies and recombinant proteins carry N-linked and O-linked glycans that modulate half-life and immunogenicity. Biopharmaceutical manufacturers in Massachusetts and North Carolina invest heavily in glycoengineering platforms to optimize effector function for oncology indications.
- Saccharides:Free glycans serve as reference standards and analytical controls across HILIC-MS workflows. Academic consortia in Germany purchase certified saccharide panels to validate inter-laboratory comparability for EMA biosimilar submissions.
- Glycolipids:Cell membrane components implicated in immune recognition pathways.
- Glycosaminoglycans:Long unbranched polysaccharides central to extracellular matrix biology.
Most installed capacity flows through glycoprotein characterization. Expansion is steepest in glycoengineered therapeutic antibodies.
Application:
Revenue concentration shifts from exploratory research toward regulated drug development as glycomics matures from academic discipline to manufacturing imperative.
- Drug Development:Sponsors map glycosylation critical quality attributes during cell line selection and process optimization. FDA accelerated approval pathways compress analytical validation timelines, forcing front-loaded investment in mass spectrometry infrastructure.
- Diagnostics:Glycan biomarker panels distinguish malignant from benign tissue states. Japanese academic-industrial partnerships translate fucosylation signatures into liver cancer screening assays.
- Therapeutics:Direct glycan-based interventions remain nascent.
- Research:Fundamental glycobiology studies drive chromatography and microarray consumption.
Drug development commands the largest share of contract analytical spending. Diagnostics applications are climbing the fastest as regulatory pathways clarify.
Technology:
Capital deployment favors integrated platforms over point solutions, with procurement decisions hinging on vendor ecosystem coherence rather than standalone specifications.
- Mass Spectrometry:Tandem MS with collision-induced dissociation resolves glycan linkages and branching at single-residue precision. Biopharmaceutical quality control laboratories adopt high-resolution ion mobility variants to meet EMA biosimilar comparability requirements.
- Chromatography:HILIC separates glycans by hydrophilicity prior to MS detection. European research institutes standardize on amide-column workflows for released N-glycan profiling.
- Microarray:Printed glycan libraries enable high-throughput lectin binding studies.
- NMR:Nuclear magnetic resonance provides orthogonal structural confirmation for ambiguous assignments.
Mass spectrometry platforms dominate current instrument procurement. Chromatography-MS integration is gaining share fastest as sponsors consolidate vendor relationships.
End User:
Procurement scale and technical sophistication diverge sharply between multinational manufacturers with captive analytical capabilities and resource-constrained academic laboratories.
- Pharmaceutical Companies:Top-20 biopharmaceutical sponsors internalize glycomics capabilities to protect intellectual property around glycoengineered biologics. Enterprise agreements span mass spectrometry, liquid handling, and data analysis software from coordinated supplier ecosystems.
- Biotechnology Firms:Emerging developers rely on contract research organizations for glycan comparability protocols. CDMO expansion in India attracts analytical service providers establishing technical centers under PLI scheme incentives.
- Academic Institutions:University laboratories pursue fundamental glycobiology with grant-funded instrument access.
- Research Organizations:Non-profit institutes bridge translation from discovery to clinical application.
Pharmaceutical companies deploy the greatest absolute analytical capacity. Biotechnology firms are expanding their in-house capabilities fastest as pipeline assets advance toward regulatory submission.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Massachusetts biopharmaceutical corridor anchors glycomics instrumentation deployment. Academic-industrial partnerships in Cambridge and Boston concentrate mass spectrometry infrastructure for glycoprotein characterization. Sponsors in this cluster internalize analytical capabilities to protect glycoengineered biologics intellectual property.
United States
FDA accelerated approval pathways for glycoprotein therapeutics compress development timelines for oncology sponsors. The agency's glycosylation critical quality attribute requirements force front-loaded investment in analytical validation infrastructure. Research Triangle Park in North Carolina hosts expanding biologics manufacturing facilities with captive glycomics quality control laboratories.
Germany
EMA biosimilar guidance on glycan critical quality attributes shapes analytical strategy design for European market access. The country's national pharmaceutical regulator enforces stringent comparability protocols for approved biologics. Heidelberg and Munich academic consortia standardize HILIC-MS workflows for inter-laboratory validation studies.
Japan
METI-funded partnerships between universities and biopharmaceutical manufacturers accelerate glycan biomarker translation into clinical applications. The national pharmaceutical regulator maintains rigorous glycosylation consistency standards for therapeutic antibodies. Tokyo and Osaka industrial clusters deploy high-resolution ion mobility mass spectrometry for biosimilar release testing.
Switzerland
Swissmedic's alignment with EMA biosimilar comparability requirements attracts biopharmaceutical quality control investment. The national pharmaceutical regulator emphasizes statistical equivalence demonstration across multiple glycan features. Basel and Zurich host integrated manufacturing networks with enterprise agreements spanning coordinated supplier ecosystems.
India
PLI scheme incentives for biopharmaceutical manufacturing attract glycomics analytical service providers to establish technical centers. CDSCO's evolving biosimilar guidelines create compliance preparation demand among emerging developers. Hyderabad and Bangalore biotechnology parks expand contract research capacity for glycan comparability protocols.
Glycomics Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized glycan analysis niches and point-of-care diagnostic formats. The vendor base stratifies across integrated platform suppliers, specialized enzyme manufacturers, and contract analytical service providers. Instrumentation specialists and biochemical reagent suppliers represent distinct strategic archetypes. Competitive moves concentrate on multi-vendor enterprise agreements and automated sample preparation robotics integration.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify platform integration strategies. Bruker Corporation occupies a position within the analytical instrumentation specialist tier. These three entities anchor the supplier ecosystem through coordinated mass spectrometry, liquid handling, and data analysis software offerings.
| Leading Market Players |
|---|
| Bruker Corporation |
| Shimadzu Corporation |
| Thermo Fisher Scientific |
| Takara Bio |
| New England Biolabs |
| Merck KGaA |
| Waters Corporation |
| Danaher Corporation |
| Agilent Technologies |
| Others |
Cost & Logistics Intelligence
EMA biosimilar glycan guidance gates both qualified supply and premium-tier pricing access, as laboratories must secure ISO 17025 accreditation and validated reference materials before serving European biopharmaceutical sponsors. This regulatory threshold stratifies the vendor base between certified analytical service providers commanding project-based premiums and uncertified competitors limited to exploratory research contracts.
Pricing Analysis
Input-cost pass-through from high-purity enzyme suppliers concentrates pricing power among specialized biochemical manufacturers of PNGase F and glycan-releasing reagents. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited laboratories from method-development shops and academic core facilities. Cost compression in standard-tier chromatography consumables is intensifying because multiple vendors now offer amide-column alternatives. Biotechnology firms with constrained capital budgets exhibit the greatest price sensitivity, while top-20 pharmaceutical sponsors prioritize analytical validation depth over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from FDA-regulated biopharmaceutical sponsors mandate multi-supplier qualification for mass spectrometry platforms and critical reagent enzymes. Manufacturing concentration spans the United States, Germany, and Japan for analytical instrumentation, while specialized biochemical inputs draw from established suppliers in Switzerland and the United Kingdom. Single-source vulnerability persists for certified glycan reference panels maintained by NIST and national standards bodies. Distribution runs through direct enterprise agreements with instrument vendors and specialized biochemical distributors serving contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in glycomics instrumentation and services rests on automation-driven cost-down trajectories and the premium-tier shift toward integrated multi-omics platforms. Sponsors increasingly internalize capabilities to protect glycoengineering intellectual property, compressing contract research pricing at the standard tier while elevating premium spend for regulatory-compliant validation.
For Market Incumbents: To counter enterprise agreement consolidation among top-20 biopharmaceutical sponsors, deepen backward integration into automated sample preparation robotics and captive enzyme manufacturing. Anchor multi-vendor platform coherence through coordinated mass spectrometry, liquid handling, and data analysis software offerings that reduce pharmaceutical quality system integration friction. For New Entrants and Emerging Players: Contract research organizations represent the most penetrable channel partner type for analytical service providers seeking scale without direct instrument manufacturing investment. Target India CDMO expansion under PLI scheme incentives, where emerging developers require glycan comparability protocols for CDSCO biosimilar submissions. Lead with AI-assisted spectral interpretation tools that accelerate biomarker identification workflows without capital-intensive infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for specialized glycan analysis laboratories because ISO 17025 accreditation timelines create durable competitive moats and sponsor switching costs. Platform consolidation across European and North American analytical service providers offers 5-10 year viability as regulatory expectations tighten. Watch FDA guidance evolution on glycosylation critical quality attributes for biosimilar interchangeability as the inflection indicator for premium-tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval for glycoprotein therapeutics compresses analytical validation timelines for oncology sponsors. |
| Manufacturing Scale-Up | Automated sample preparation robotics integration reduces release testing turnaround from days to hours in quality control laboratories. |
| Platform Integration | Multi-omics data architectures dissolve boundaries between glycomics, proteomics, and metabolomics workflows for unified pathway tracing. |
| Acquisition of Specialist Firm | AI-assisted spectral interpretation tools trained on glycan fragmentation patterns accelerate biomarker identification without infrastructure buildout. |
| Geographic Expansion | India CDMO technical centers under PLI scheme incentives capture contract research demand from emerging biosimilar developers. |
Research Approach
Bottom-up drug development modeling reconciled against top-down analytical instrumentation deployment tracking forms the analytical core of this study. Primary interviews with biopharmaceutical quality control directors, regulatory affairs leads, contract research organization executives, and academic glycobiology principal investigators combined with secondary validation from FDA filings, EMA submissions, ISO 17025 accreditation databases, and instrument vendor enterprise agreement disclosures. Top-down and bottom-up triangulation cross-checks capital expenditure patterns against sponsor pipeline stage distributions.
Input-output matrix framing maps glycoprotein therapeutic pipeline advancement to installed mass spectrometry capacity across the projection horizon. Segmentation dimensions include product type, application, technology platform, and end-user procurement scale, with regional regulatory cluster as an additional modeled variable. CAGRs derive from instrument replacement cycles, sponsor internalization trends, and contract research outsourcing elasticity. Forecast inputs incorporate EMA biosimilar guidance evolution and METI-funded partnership translation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA glycosylation critical quality attribute guidance revisions and NIST reference material availability. Deviation in ISO 17025 accreditation timeline compression or AI-assisted spectral interpretation adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Liquid Biopsy Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Bioadhesive Microspheres Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Global Primary Cell Culture Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Global Biomarker Technologies Market